
 1440p Gaming Monitors Market | 2026-2036
1440p Gaming Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
1440p Gaming Monitors Market Insights
Panel engineer availability in Taiwan and South Korea is collapsing as semiconductor fabs expand hiring for advanced packaging roles. Asus leverages vertical integration into display controller firmware to sustain product differentiation in premium tiers. Samsung anchors its competitive position through captive OLED supply and in-house production of quantum dot enhancement films. AOC competes aggressively on price while operating primarily through e-commerce channel partnerships across Southeast Asia.
A 1440p gaming monitor delivers a 2560×1440 pixel resolution at refresh rates typically spanning 144 Hz to 360 Hz, employing IPS or VA liquid crystal matrices with response times under 4 ms to eliminate motion blur during fast-paced rendering. Its primary commercial purpose is to bridge the visual fidelity gap between mainstream 1080p displays and GPU-intensive 4K panels while maintaining frame rate headroom for competitive multiplayer environments. Curved screen variants are capturing margin pools in immersive simulation segments where field-of-view extension commands pricing premiums. OLED technology is displacing LCD dominance in enthusiast tiers as burn-in mitigation algorithms mature and manufacturing yields improve. The 27-inch screen size occupies the volume center of the market, balancing desk footprint compatibility with pixel density thresholds for crisp text rendering.
FCC electromagnetic emissions standards in the United States and CE marking requirements under EU RoHS directives constrain power supply designs and backlight inverter architectures, effectively filtering out uncertified imports from gray-market channels. REACH chemical restrictions from ECHA limit certain flame retardants in plastic bezels, compelling reformulation of housing materials across Taiwanese and Chinese contract manufacturers. Energy efficiency labeling programs in multiple jurisdictions are tightening standby power thresholds, forcing redesigns of monitor control boards. Stakeholders must monitor whether VESA DisplayHDR specification updates will mandate local dimming zones as a baseline requirement, as this technical inflection would reshape cost structures for mid-tier product lines and determine which panel technologies remain viable across price bands.
Market Dynamics
OLED burn-in mitigation algorithms have crossed a reliability threshold that is collapsing LCD's historical cost advantage in enthusiast tiers and triggering a wholesale panel technology transition.
Growth Catalysts
- VESA DisplayHDR certification:Tournament organizers mandate certified panels for official competition hardware, forcing refresh cycles across esports infrastructure.
- Seoul-Incheon manufacturing corridor:Panel fabs cluster within 50 kilometers of final assembly plants, compressing logistics costs and enabling just-in-time customization.
- Quantum dot enhancement films:Wider color gamut coverage is becoming table stakes for premium positioning as streaming platforms expand HDR content libraries.
Market Restraints
- Panel engineer scarcity:Taiwan and South Korea face acute talent shortages as semiconductor fabs siphon skilled labor into advanced packaging roles.
- Backlight inverter redesign costs:FCC electromagnetic emissions standards and EU RoHS directives force power supply architecture changes that filter out uncertified imports.
- OLED manufacturing yield volatility:Sub-85% yields at Gen 8.5 fabs constrain volume scalability for mid-tier price bands.
Strategic Opportunities
- Curved screen variants:Flight and racing simulation segments command 40-60% pricing premiums for field-of-view extension.
- E-commerce channel partnerships:Southeast Asian markets remain underpenetrated by premium brands, creating white space for direct-to-consumer logistics investments.
- Energy efficiency labeling programs:Tightening standby power thresholds in multiple jurisdictions favor control board redesigns that extend product lifecycle relevance.
Industry Challenges
- Firmware development capacity:Display controller optimization requires scarce embedded systems talent as monitor intelligence converges with GPU feature synchronization.
- REACH chemical compliance timelines:ECHA flame retardant restrictions compel housing material reformulation across Taiwanese contract manufacturers with 18-24 month qualification cycles.
- Local dimming zone integration:VESA specification uncertainty forces parallel development tracks that inflate R&D overhead for mid-tier product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1440p Gaming Monitors Market |
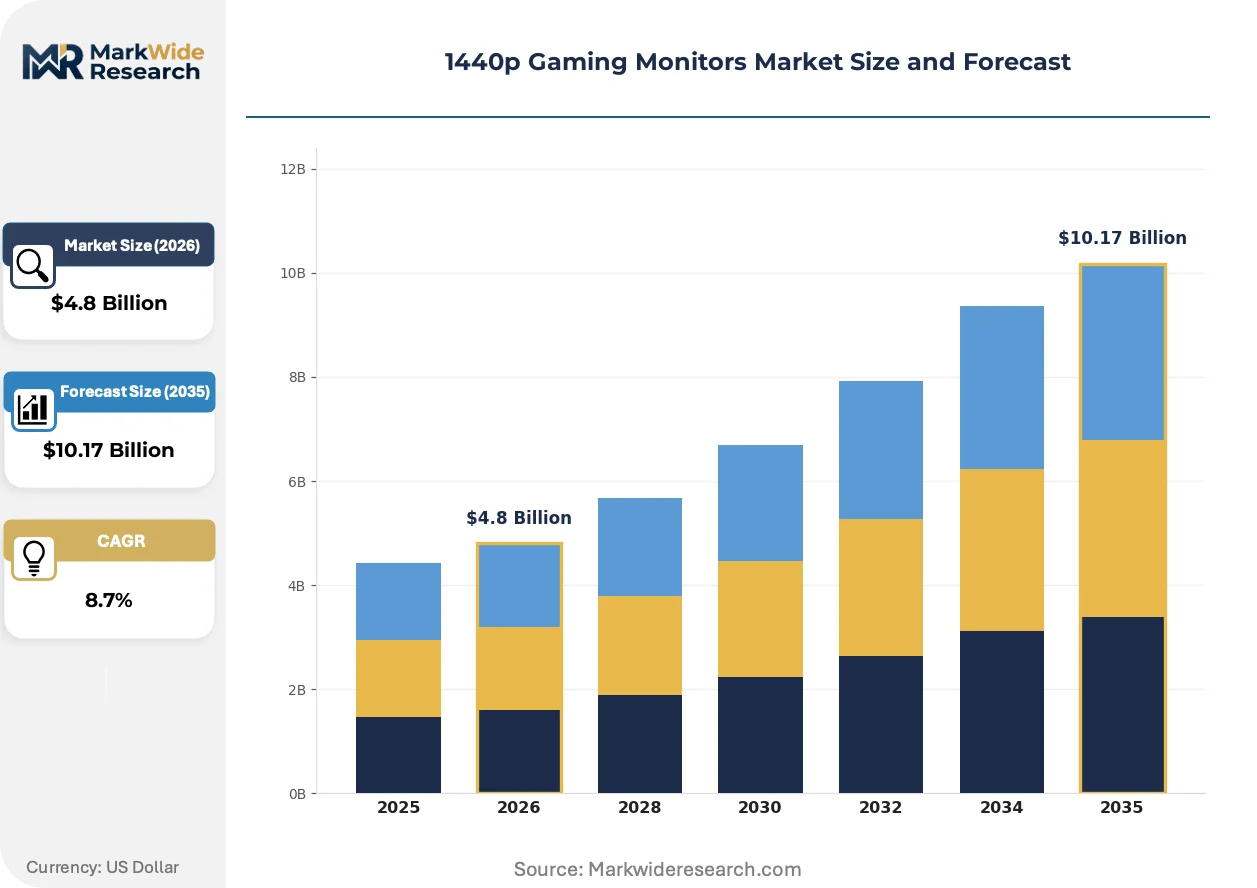
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
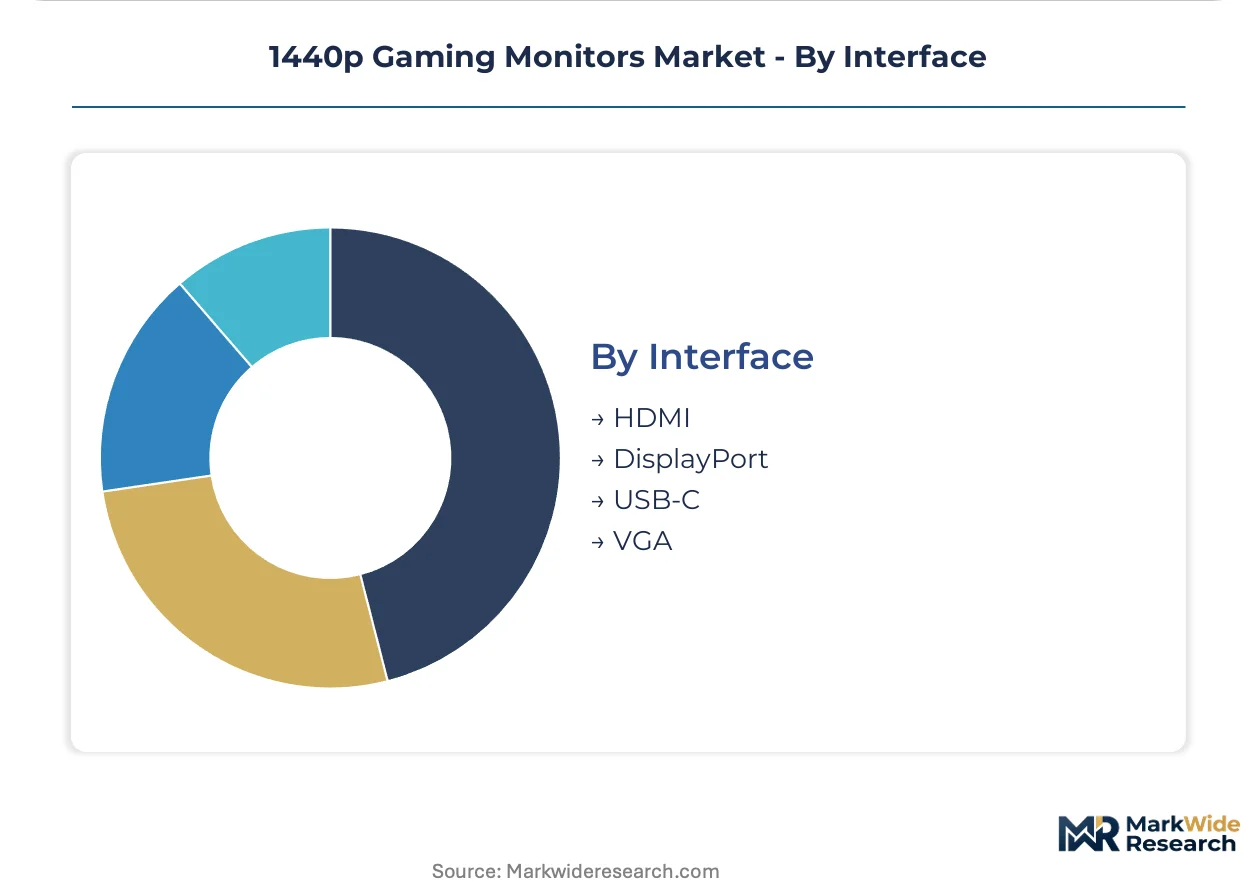
| Segmentation | Product Type: Flat Panel, Curved, G-Sync, FreeSync Screen Size: 24 inch, 27 inch, 32 inch, 34 inch Technology: LCD, LED, OLED, QLED Interface: HDMI, DisplayPort, USB-C, VGA |
| Companies Covered | AOC, MSI, Asus, Gigabyte, Dell Alienware, LG, Alienware, Samsung, Acer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1440p Gaming Monitors Market Trends and Innovations
Display technology, regulatory pressure, and procurement behavior are converging to compress product lifecycles and restructure competitive advantage around firmware capabilities rather than panel sourcing alone.
OLED panels with mature pixel-shifting algorithms and brightness limiters are supplanting IPS LCD dominance in the 27-inch enthusiast segment. Esports organizations and content creators are accelerating adoption despite 30-40% unit cost premiums. The technology shift is compressing margin pools for VA panel specialists while rewarding brands with captive OLED supply agreements.
EU REACH restrictions on halogenated flame retardants are forcing bezel and chassis material reformulations across the supply base. Taiwanese and Chinese contract manufacturers face 12-18 month requalification cycles for alternative polymer compounds. Mid-tier product lines bear disproportionate cost impacts as they lack volume leverage to absorb compliance overhead.
Direct-to-consumer configuration tools are fragmenting traditional distributor relationships as buyers specify refresh rate, curvature, and stand ergonomics through brand websites. Specialist retailers in Germany and the United Kingdom are losing attach-rate revenue from cable and peripheral bundling. The channel shift is most visible among 18-34 demographic segments purchasing 240 Hz-plus panels for competitive multiplayer titles.
1440p Gaming Monitors Market Segmentation
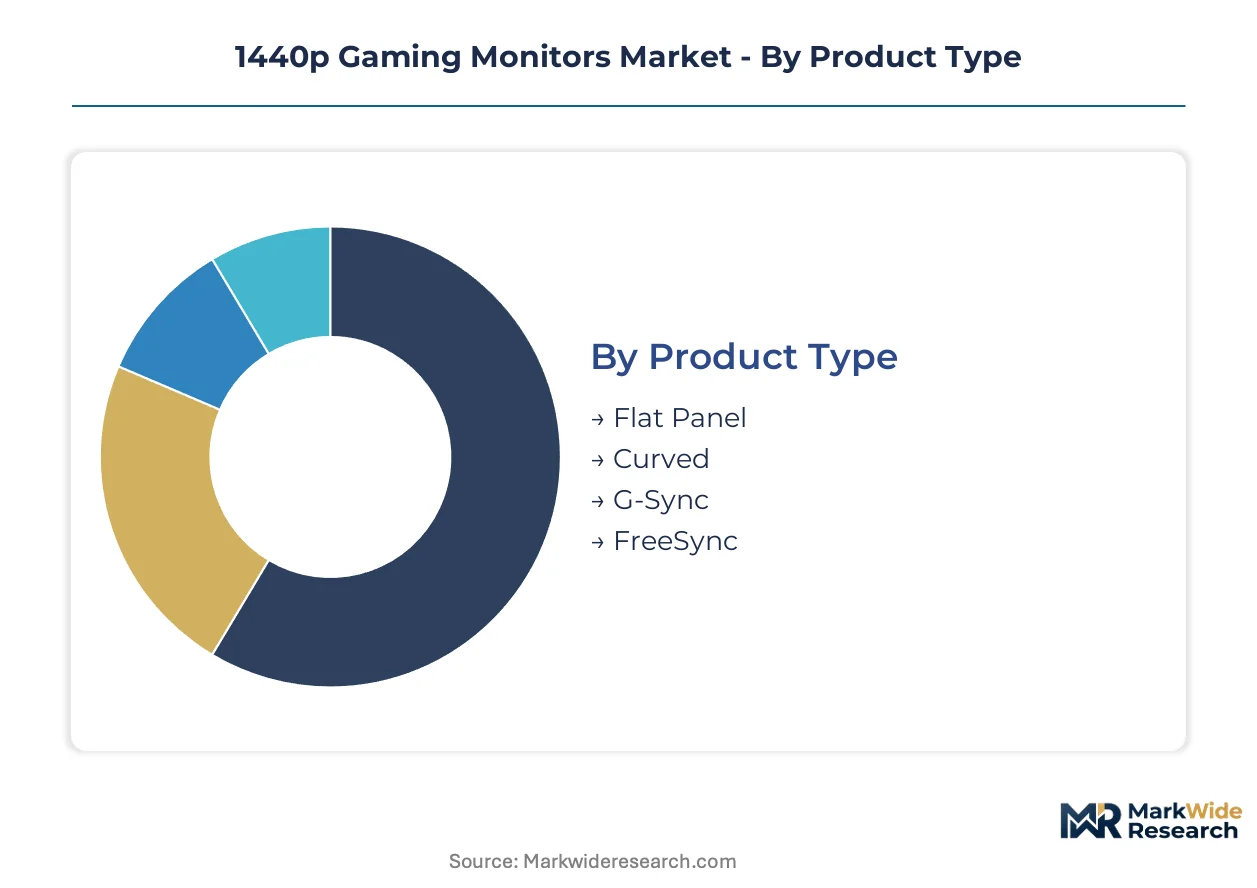
1440p gaming monitors fragment across four structural dimensions that determine procurement priorities. Product type and technology classifications drive certification requirements and margin structures, while screen size and interface specifications shape compatibility ecosystems and upgrade cycles.
Product Type:
FCC electromagnetic emissions testing and VESA DisplayHDR certification create divergent compliance burdens across form factors and synchronization standards.
- Flat Panel:Standard planar LCD and OLED configurations dominate esports tournament procurement due to predictable geometry for multi-monitor arrays. Demand concentrates in South Korea's Seoul-Incheon corridor where panel fabs supply direct-to-assembly logistics for certified competition hardware.
- Curved:Radiused screens with 1000R to 1800R curvature radius command pricing premiums in flight and racing simulation segments. The segment is the fastest mover on share as field-of-view extension becomes table stakes for immersive single-player titles.
- G-Sync:NVIDIA hardware module integration requires proprietary scaler chips and firmware validation cycles.
- FreeSync:AMD adaptive sync operates through open-standard display controller implementations.
Flat Panel handles the majority of throughput; Curved is climbing the fastest on share.
Screen Size:
Pixel density thresholds and desk footprint constraints segment buyer preferences across residential and commercial installations.
- 27 inch:Occupies the volume center balancing 109 PPI clarity with ergonomic viewing distances. Procurement concentrates in Germany and the United Kingdom where direct-to-consumer configuration tools fragment traditional distributor relationships.
- 32 inch:Larger format panels attract content creators requiring timeline real estate for video editing workflows. Demand is expanding most quickly as GPU performance headroom at 1440p enables higher refresh rates on bigger canvases.
- 24 inch:Compact footprint suits dormitory and shared living environments with space constraints.
- 34 inch:Ultrawide aspect ratio variants target productivity-gaming hybrid use cases.
27 inch handles the majority of throughput; 32 inch is gaining share fastest.
Technology:
Manufacturing yield differentials and backlight system architectures determine cost structures and HDR performance tiers.
- OLED:Self-emissive pixels with pixel-shifting burn-in mitigation algorithms are displacing LCD dominance in enthusiast tiers. Demand concentrates among esports organizations and content creators accepting 30-40% unit cost premiums for infinite contrast ratios.
- LCD:IPS and VA liquid crystal matrices retain cost advantages in mid-tier bands despite narrowing performance gaps. Procurement is accelerating most quickly in Southeast Asian e-commerce channels where price-sensitive buyers prioritize refresh rate over black levels.
- LED:Edge-lit and full-array backlight configurations serve budget-conscious segments.
- QLED:Quantum dot enhancement films extend color gamut coverage for streaming platform HDR content.
LCD handles the majority of throughput; OLED shows the steepest expansion trajectory.
Interface:
Bandwidth specifications and alternate mode capabilities determine GPU compatibility and cable ecosystem requirements.
- DisplayPort:High-bandwidth protocol supports 240 Hz-plus refresh rates at full 1440p resolution without compression. Demand concentrates in competitive multiplayer segments where frame rate headroom determines tournament eligibility.
- USB-C:Single-cable power delivery and video transport appeals to laptop docking workflows. The interface is expanding most quickly as mobile GPU performance reaches desktop parity for 1440p rendering.
- HDMI:Ubiquitous consumer electronics compatibility drives inclusion across all price tiers.
- VGA:Legacy analog support persists in institutional refresh cycles with extended replacement timelines.
DisplayPort handles the majority of throughput; USB-C is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: South Korea and Taiwan prioritize tournament-grade refresh rates above 240 Hz, while Germany and the United States emphasize direct-to-consumer configuration tools for ergonomic customization.
South Korea
Esports infrastructure investment drives fleet procurement of DisplayHDR-certified panels for tournament venues. The Ministry of Trade, Industry and Energy (METI) coordinates with MFDS on electromagnetic compatibility standards for competition hardware. Seoul-Incheon corridor concentration enables just-in-time panel-to-assembly logistics within 50 kilometers.
Taiwan
Panel fab clustering supports OEM manufacturing for global gaming brands with compressed lead times. The Bureau of Standards, Metrology and Inspection (BSMI) enforces energy efficiency labeling that exceeds baseline IEC requirements. Hsinchu Science Park houses display controller firmware development centers competing for scarce embedded systems talent.
United States
Content creator demand for 32-inch formats with timeline real estate accelerates upgrade cycles beyond residential replacement norms. FCC electromagnetic emissions standards filter uncertified imports from gray-market channels, particularly for backlight inverter architectures. Austin and Seattle metro areas concentrate direct-to-consumer brand headquarters with configuration-tool development teams.
Germany
Specialist retailers face attach-rate erosion as 18-34 demographic segments migrate to brand websites for 240 Hz-plus panel procurement. EU REACH restrictions on halogenated flame retardants compel 12-18 month housing material requalification cycles. Bavaria hosts precision engineering suppliers for monitor stand and ergonomic mounting systems.
China
E-commerce channel penetration in Southeast Asian markets creates white space for logistics investments from Shenzhen and Dongguan manufacturing bases. GB standards for electromagnetic compatibility align with but exceed baseline international requirements. Yangtze River Delta panel assembly plants serve price-sensitive segments prioritizing refresh rate over black level performance.
1440p Gaming Monitors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive OLED supply and in-house quantum dot film production distinguishing premium positioning from assembly-dependent competitors. The vendor base stratifies across three archetypes: semiconductor conglomerates with display divisions, dedicated monitor specialists with controller firmware capabilities, and contract manufacturers serving e-commerce channels. Consolidation pressure intensifies as burn-in mitigation algorithm development requires R&D scale beyond mid-tier reach. Dominant competitive moves include backward integration into display controller silicon and geographic expansion through direct-to-consumer logistics platforms.
Within the integrated conglomerate tier, Samsung and LG exemplify captive supply chain advantages through internal OLED panel production and quantum dot enhancement film manufacturing. Asus occupies a position bridging specialist and integrated archetypes through upstream control over display controller firmware development. AOC represents the scale-driven contract manufacturing segment competing aggressively on price through Southeast Asian e-commerce channel partnerships.
| Leading Market Players |
|---|
| AOC |
| MSI |
| Asus |
| Gigabyte |
| Dell Alienware |
| LG |
| Alienware |
| Samsung |
| Acer |
| Others |
Pricing and Supply Chain Analysis
Gen 8.5 fab capacity utilization above 85% in South Korea and Taiwan compresses margin headroom for mid-tier LCD panels while concentrating pricing power among OLED suppliers with yield-stable production. Scale economies at Seoul-Incheon corridor assembly plants anchor cost floors for tournament-certified hardware, forcing brands without captive panel supply to absorb margin compression or surrender share.
Pricing Analysis
Long-term offtake contracts between Samsung and LG with esports tournament organizers lock in volume commitments for DisplayHDR-certified OLED panels, while spot-market procurement dominates mid-tier LCD transactions. Three-tier pricing structure across premium OLED, standard IPS, and economy VA levels differentiates on burn-in mitigation maturity and local dimming zone count. Pricing pressure stems from yield volatility at Gen 8.5 OLED fabs constraining volume scalability. E-commerce channel buyers in Southeast Asia exhibit highest price sensitivity, prioritizing refresh rate specifications over HDR certification tiers.
Supply Chain Analysis
Just-in-time inventory strategies predominate among Seoul-Incheon corridor assemblers, with panel-to-finished-goods logistics compressed within 50-kilometer radii to minimize working capital. Supply concentrates in South Korea, Taiwan, and China, with Hsinchu Science Park housing display controller firmware development and Shenzhen serving price-sensitive Southeast Asian e-commerce channels. Raw material dependencies include quantum dot enhancement films, polarizer sheets, and flame-retardant polymer compounds. Single-source vulnerability around OLED panel supply from Samsung and LG Display threatens mid-tier brands without alternative sourcing. Distribution runs through direct-to-consumer brand websites and specialist retailers in Germany and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among esports tournament organizers and direct-to-consumer procurement platforms, fragmenting traditional distributor relationships and compressing attach-rate revenue pools for peripheral bundling.
For Market Incumbents: Fortify captive OLED supply agreements through exclusive offtake arrangements with Samsung and LG Display, insulating against yield-constrained volume shortages. Deepen backward integration into display controller firmware development to sustain feature synchronization advantages as GPU-matching intelligence becomes table stakes. Prioritize certification investment in VESA DisplayHDR tiers to defend tournament hardware eligibility against emerging entrants. For New Entrants and Emerging Players: Anchor in Southeast Asian e-commerce white space where premium brand penetration remains thin and logistics infrastructure investments can capture price-sensitive 240 Hz-plus demand. Target curved screen variants for flight and racing simulation segments commanding 40-60% pricing premiums with lower certification overhead than esports tournament tiers. Deploy direct-to-consumer configuration tools to bypass entrenched distributor relationships in Germany and the United Kingdom. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among brands with tournament hardware certification contracts and firmware subscription services for burn-in mitigation algorithm updates. Long-term viability favors integrated players with captive panel supply and in-house quantum dot film production over assembly-dependent contract manufacturers. Acquisition target archetype: mid-tier specialists with established e-commerce channel partnerships but lacking OLED supply security. Monitor VESA DisplayHDR specification updates mandating local dimming zones as inflection indicator for mid-tier product line viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Display Controller Silicon | Asus and Samsung leverage in-house firmware teams to sustain GPU synchronization advantages. |
| Direct-to-Consumer Logistics Platform Expansion | AOC and MSI capture Southeast Asian white space through e-commerce channel partnerships. |
| Exclusive OLED Supply Agreement | LG Display locks tournament organizer volume commitments through long-term offtake structures. |
| Curved Screen Variant Development | Gigabyte and Acer command simulation segment premiums with 1000R-1800R field-of-view extension. |
| Energy Efficiency Control Board Redesign | Dell Alienware extends product lifecycle relevance under tightening EU standby power thresholds. |
Research Methodology
Operator-level perspectives from panel fab engineers, display controller firmware developers, esports tournament procurement managers, and Southeast Asian e-commerce channel partners anchored the qualitative base. Secondary validation drew from VESA certification databases, FCC electromagnetic emissions filings, EU REACH substance restriction updates, and Korean Ministry of Trade customs records. Bottom-up shipment estimates by panel technology and screen size triangulated against top-down gaming hardware attach-rate models.
Sensitivity analysis tested yield assumptions at Gen 8.5 OLED fabs and adoption curves for burn-in mitigation algorithms across the projection horizon. Segmentation dimensions modeled include product type, screen size, technology, interface, and regional regulatory cluster. CAGRs derived from panel supply forecasts weighted by refresh rate tier penetration and GPU performance headroom evolution. Industry-specific inputs incorporated DisplayHDR certification pipeline timelines and REACH chemical requalification cycle durations.
Material uncertainties — OLED manufacturing yield volatility, VESA specification mandate timing, and semiconductor fab hiring competition for panel engineering talent — sit outside the modeled envelope. Forecasts reflect documented assumptions on technology transition rates and regulatory compliance cost absorption. Practitioners should keep alternative scenarios live as burn-in mitigation algorithm reliability thresholds and local dimming zone integration requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global OLED Market
Display Technologies
Global Display Controllers Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Digital Holographic Display Market
Display Technologies
OLED Panel Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Field Emission Display Market
Display Technologies
3D Display Module Market
Display Technologies
Smart Screen Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Dot Matrix Display Market
Display Technologies
Global Ferro Liquid Display Market
Display Technologies
Privacy Screens Market
Display Technologies
4K Technology Market
Display Technologies
Collaboration Display Market