
 Volumetric Display Market | 2026-2036
Volumetric Display Market Size, Share, and Industry Trends Forecast 2026-2036
Volumetric Display Market Intelligence
Medical imaging and surgical planning is realigning the volumetric display end-use mix, displacing earlier concentration in entertainment and retail installations. Lightspace Technologies leverages its electrostatic modulation patents to dominate high-resolution clinical workstations. Voxon Photonics sustains manufacturing scale in swept-volume hardware for defense and research buyers across Australia and North America. Looking Glass Factory differentiates through accessible light-field displays that occupy the education and design prototyping segments with lower entry pricing.
A volumetric display renders three-dimensional imagery in physical space without requiring head-mounted apparatus or stereoscopic glasses, typically employing rotating projection surfaces, laser-induced plasma excitation, or layered light-field modulation to generate viewable voxels across 360-degree viewing zones. Swept-volume systems currently anchor the product type landscape due to mature motor-control supply chains and proven reliability in military simulation environments. Light field technology leads the technology dimension in R&D intensity, while voxel-based architectures compete on computational efficiency for real-time scientific visualization workloads. Multi-view displays capture expanding share in advertising and virtual conferencing use cases where audience size and interaction distance vary.
FDA clearance pathways for diagnostic display devices shape product development timelines for medical applications in the United States. EMA's Medical Device Regulation and IEC 60601-1 electrical safety standards govern European market access, while South Korea's MFDS accelerates local approval for holographic surgical planning tools. Stakeholders must monitor divergence between regional electromagnetic emission standards and voxel-resolution certification thresholds as these will determine which technology platforms achieve cross-border deployment at scale.
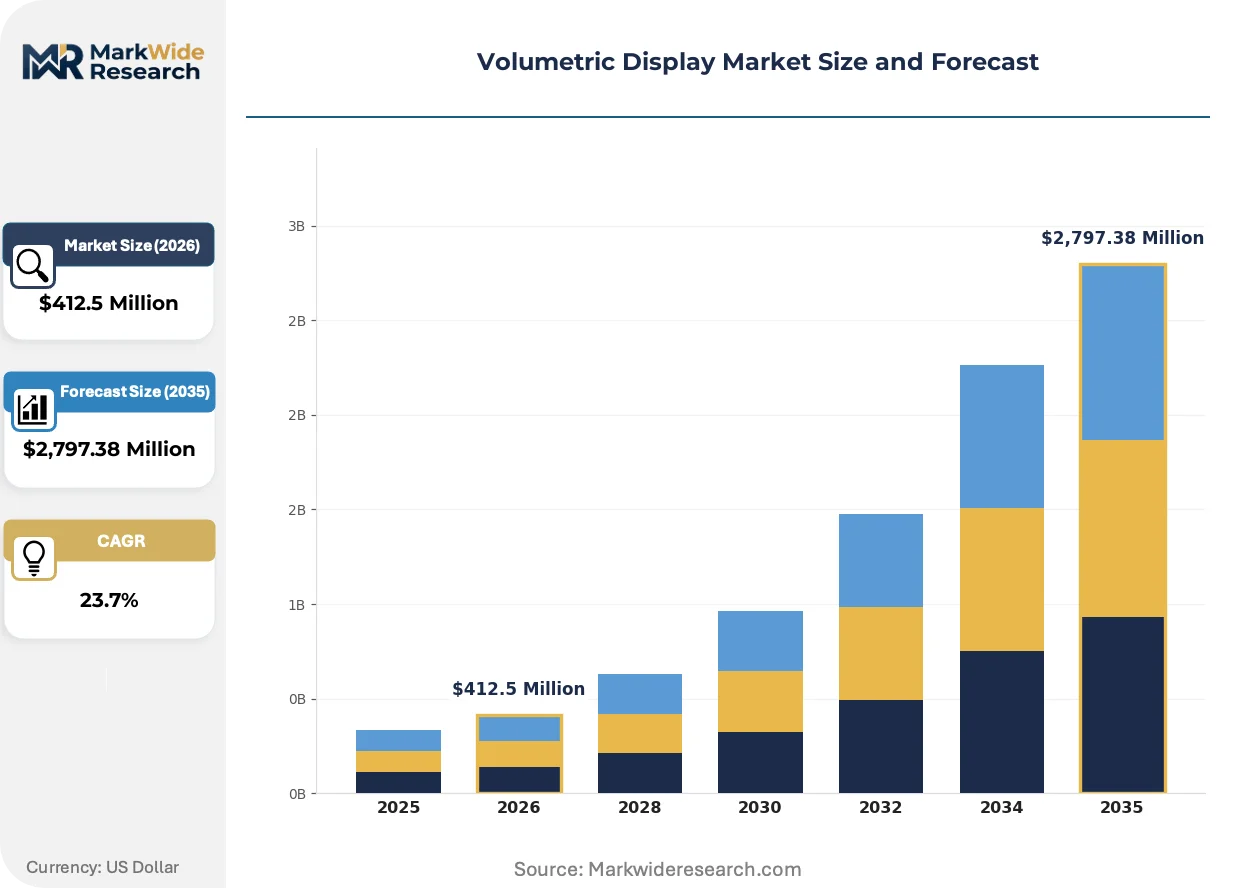
Market Dynamics
Defense procurement of holographic visualization systems is compressing development cycles across all volumetric display categories, pulling civilian medical and industrial applications into faster commercialization timelines than previously projected.
Growth Catalysts
- Laser-induced plasma excitation:Laboratory demonstrations at Lawrence Livermore National Laboratory and Japan's RIKEN institute demonstrate scalable voxel density without mechanical rotation, opening pathways for solid-state volumetric hardware.
- FDA 510(k) premarket notification pathway:Streamlined clearance for diagnostic display devices accelerates hospital procurement of holographic surgical planning workstations in the United States.
- South Korea photonics clusters:Government-backed programs in Gwangju and Daejeon concentrate precision optics manufacturing, reducing prototyping lead times for swept-volume motor assemblies and light-field modulation panels.
Market Restraints
- Galvanometer scanner supply concentration:German and Japanese precision motor manufacturers control 70%+ of high-speed mirror positioning components, creating single-source vulnerability for swept-volume system builders.
- IEC 60601-1 electrical safety certification costs:Medical-grade isolation requirements and leakage current testing add substantial fixed cost layers before revenue generation.
- Flat-panel OLED substitution:Autostereoscopic glasses-free 3D displays from LG and Samsung Display capture price-sensitive entertainment and retail signage applications.
Strategic Opportunities
- Remote surgical mentorship networks:Real-time holographic transmission of operative fields enables specialist guidance across rural hospital systems in India and Southeast Asia.
- EU AI Act compliance infrastructure:Conformity assessment requirements for AI-enabled diagnostic displays create first-mover advantage for vendors with embedded explainability features.
- Light-field and haptic feedback convergence:Integration of ultrasonic mid-air tactile interfaces with volumetric imagery opens industrial design and automotive styling applications.
Industry Challenges
- Voxel rendering pipeline optimization:Real-time computation of 100 million+ voxels at 60Hz demands specialized GPU architectures and custom shader programming scarce in mainstream graphics talent pools.
- Legacy PACS integration:Hospital IT departments resist disruption to established DICOM viewing workflows, requiring expensive middleware development for volumetric display compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volumetric Display Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $2,797.38 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrostatic, Swept-Volume, Laser Plasma, Multi-View, Holographic Technology: Light Field, Volumetric Light Modulation, Integral Imaging, Layer-Based Projection, Voxel-Based Use Case: Education, Military Training, Scientific Visualization, Advertising, Virtual Conferencing End User: Research Institutions, Defense Agencies, Educational Establishments, Marketing Firms, Entertainment Studios |
| Companies Covered | Lightspace Technologies, Leia Inc., Voxon Photonics, Alioscopy, SeeReal Technologies, Looking Glass Factory, Holoxica Ltd, Holografika, The Coretec Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volumetric Display Market Strategic Shifts & Innovations
Photonics manufacturing techniques borrowed from semiconductor lithography are crossing into display fabrication, collapsing the traditional separation between emitter arrays and modulation layers.
Electro-optic phase modulator arrays fabricated on silicon photonics platforms are modularizing light-field engine construction. Medical imaging OEMs in Germany and Massachusetts adopt these integrated photonic circuits for compact clinical workstations. The shift collapses optical bench assemblies into chip-scale packages, reducing unit footprint.
Japan's METI has expanded subsidies under the Society 5.0 initiative to cover holographic telepresence infrastructure for remote technical training. Domestic manufacturers must demonstrate interoperability with JIS X 8341 accessibility standards to qualify. The policy accelerates adoption in manufacturing and disaster response coordination centers.
Hospital capital equipment committees now require volumetric displays to demonstrate measurable reduction in surgical planning time versus conventional multi-planar reconstruction. Vendors respond with outcome-guarantee pilot programs. This procurement criterion is most pronounced in tertiary cardiac centers across Texas, California, and New York.
Volumetric Display Market Segmentation
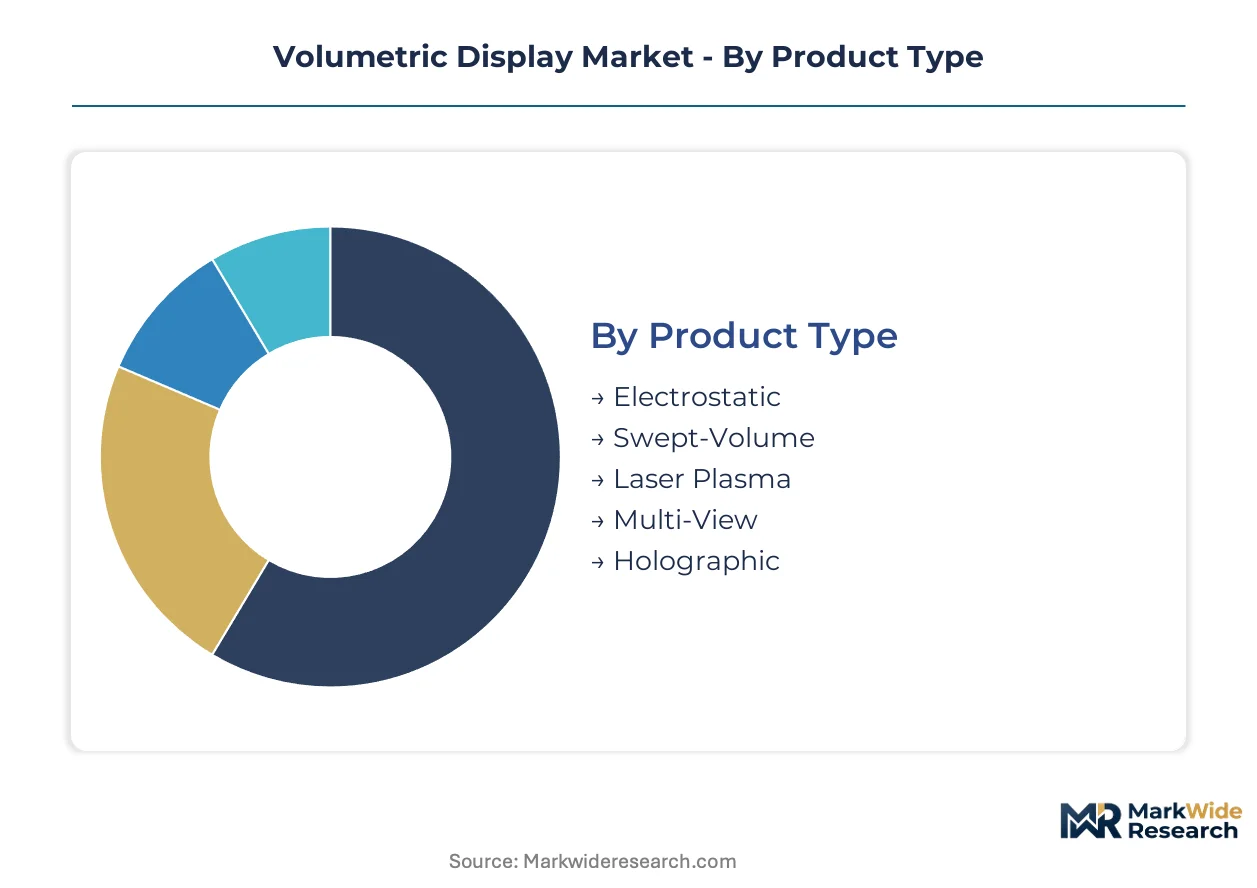
Volumetric display procurement patterns diverge sharply across hardware architectures and institutional buyer profiles. Technology selection hinges on voxel density requirements, viewing angle specifications, and electromagnetic emission constraints that vary by deployment environment.
Product Type:
Technical specifications around mechanical rotation, plasma excitation, and electrostatic modulation define the hardware landscape.
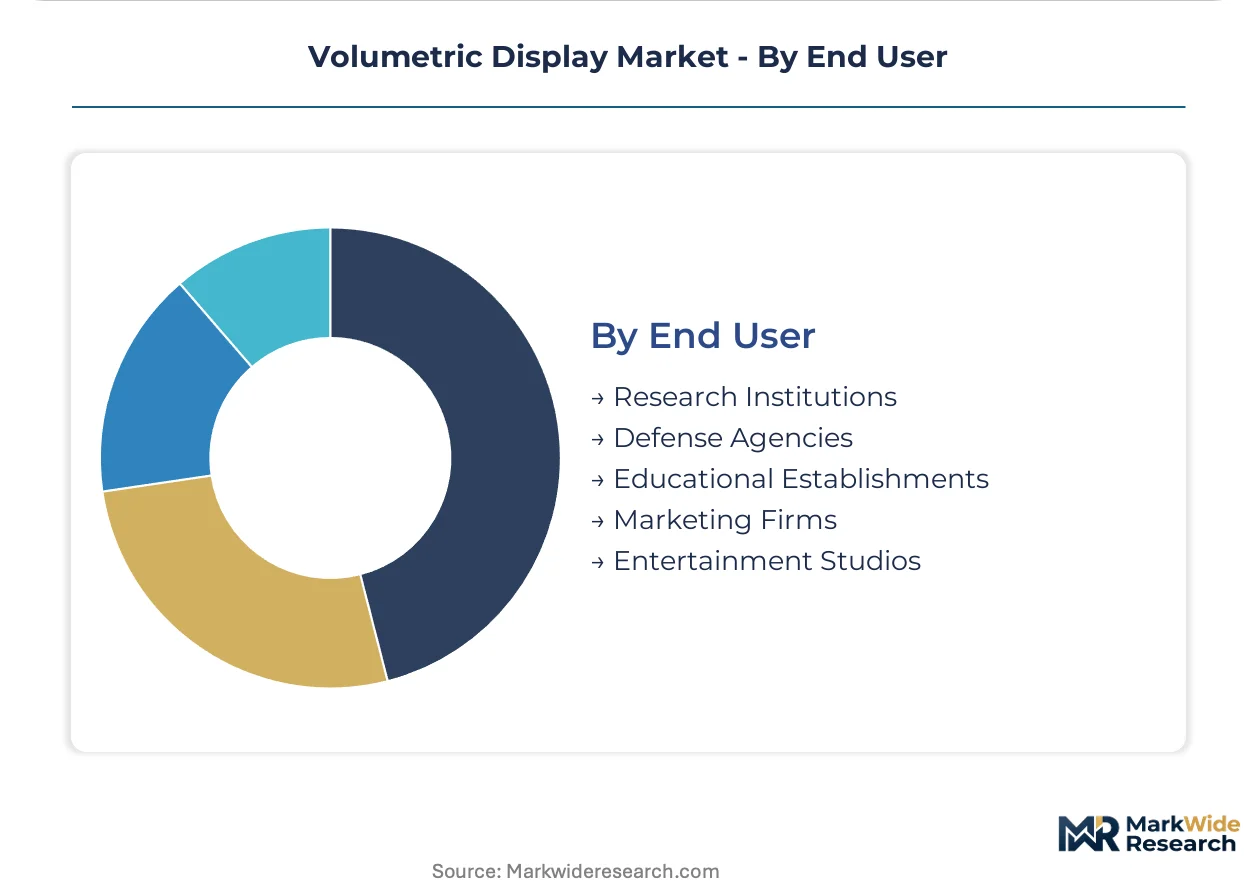
- Swept-Volume:Rotating projection surfaces driven by precision galvanometer assemblies generate viewable voxels across 360-degree zones. Defense agencies in the United States and allied nations anchor procurement volumes for pilot training and battlefield visualization simulators where proven reliability outweighs unit cost.
- Electrostatic:Electrostatic modulation patents enable high-resolution clinical workstations without mechanical wear components. Lightspace Technologies dominates this architecture for FDA-cleared diagnostic displays where voxel stability affects surgical planning accuracy.
- Laser Plasma:Laser-induced plasma excitation creates scalable voxel density without moving parts, demonstrated at Lawrence Livermore National Laboratory and Japan's RIKEN institute.
- Multi-View:Directional pixel arrays serve advertising installations and virtual conferencing where audience positioning varies.
- Holographic:Interference-pattern reconstruction systems concentrate in research and premium telepresence applications.
Swept-Volume leads on scale; Laser Plasma leads on momentum.
Technology:
Light engine architectures determine computational load, optical efficiency, and compatibility with existing graphics pipelines.
- Light Field:Layered modulation panels capture the steepest expansion trajectory in R&D investment. South Korea's Gwangju and Daejeon photonics clusters reduce prototyping lead times for integrated photonic circuit fabrication.
- Voxel-Based:Direct volumetric addressing optimizes computational efficiency for real-time scientific visualization workloads at research institutions.
- Volumetric Light Modulation:Phase modulator arrays fabricated on silicon photonics platforms collapse optical bench assemblies into chip-scale packages.
- Integral Imaging:Lenslet arrays produce autostereoscopic effects without head tracking for education and museum installations.
- Layer-Based Projection:Stacked transparent screens offer intermediate cost positioning between flat-panel substitutes and true volumetric systems.
Voxel-Based dominates current deployment volumes; Light Field commands development capital.
Use Case:
Application requirements around interaction distance, audience size, and content refresh frequency segment demand.
- Military Training:Holographic visualization systems compress development cycles across all categories. United States defense procurement pulls civilian medical and industrial applications into faster commercialization timelines.
- Scientific Visualization:Real-time computation of 100 million+ voxels at 60Hz demands specialized GPU architectures and custom shader programming.
- Education:Looking Glass Factory occupies this segment with accessible light-field displays and lower entry pricing for design prototyping curricula.
- Advertising:Multi-view displays capture expanding share where audience size and interaction distance vary across retail environments.
- Virtual Conferencing:Holographic telepresence infrastructure receives expanded subsidies under Japan's METI Society 5.0 initiative.
Military Training anchors revenue; Scientific Visualization gains share fastest.
End User:
Institutional procurement processes and certification requirements create distinct customer archetypes.
- Defense Agencies:Swept-volume reliability requirements and classified facility electromagnetic standards shape vendor qualification. German and Japanese precision motor manufacturers control critical galvanometer scanner supply.
- Research Institutions:Voxel rendering pipeline optimization and legacy PACS integration resistance drive middleware development costs for hospital IT compatibility.
- Educational Establishments:Outcome-guarantee pilot programs respond to capital equipment committee demands for measurable surgical planning time reduction.
- Marketing Firms:Price-sensitive entertainment and retail signage applications face substitution pressure from autostereoscopic flat-panel OLED displays.
- Entertainment Studios:Content creation toolchains require volumetric capture and playback pipeline integration.
Defense Agencies concentrate procurement volume; Research Institutions drive specification advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where volumetric display hardware achieves commercial scale first. Jurisdictions with streamlined medical device clearance and concentrated photonics manufacturing clusters attract capital commitments faster than regions with fragmented certification pathways.
United States
Defense procurement through DARPA and service branches sustains swept-volume system demand for pilot training simulators. FDA 510(k) pathways for diagnostic display devices accelerate hospital adoption of holographic surgical planning tools. Boston and Austin host dense concentrations of medical imaging OEMs integrating volumetric workstations into cardiac and neurosurgical suites.
South Korea
Government-backed photonics programs in Gwangju and Daejeon compress prototyping cycles for light-field modulation panels. MFDS fast-track approvals for holographic surgical planning tools reduce time-to-revenue for domestic manufacturers. Seoul Capital Area anchors precision optics supply chains feeding both display component ecosystems and consumer electronics integrators.
Japan
METI Society 5.0 subsidies for holographic telepresence infrastructure expand deployment in manufacturing training centers. JIS X 8341 accessibility standards shape product design for domestic qualification. RIKEN institute demonstrations of laser-induced plasma excitation position Japanese laboratories at the frontier of solid-state volumetric research.
Germany
EMA Medical Device Regulation and IEC 60601-1 electrical safety standards govern European market access for clinical volumetric systems. Bavaria and Baden-Württemberg precision motor manufacturers control critical galvanometer scanner supply for swept-volume builders. Siemens Healthineers and regional imaging OEMs pilot volumetric PACS integration in Munich and Erlangen hospital networks.
Australia
Defense research partnerships with the United States pull swept-volume procurement for joint military simulation programs. Voxon Photonics sustains manufacturing scale from Adelaide for North American and allied nation buyers. TGA alignment with FDA precedents streamlines parallel clearance for diagnostic display devices targeting Asia-Pacific export markets.
Volumetric Display Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments. The market exhibits moderate concentration with technology-specific silos rather than integrated full-line dominance. Three archetypes define competitive positioning: electrostatic modulation patent holders, swept-volume hardware fabricators, and accessible light-field platform builders. Capacity expansion through South Korean and Japanese photonics clusters and strategic technology licensing between defense contractors and medical OEMs constitute the dominant competitive moves.
Among electrostatic modulation specialists, Lightspace Technologies occupies a position exemplifying high-resolution clinical workstation dominance through patent-protected architectures. Voxon Photonics represents the swept-volume fabrication archetype with sustained manufacturing scale across defense and research buyer segments. Looking Glass Factory anchors the accessible-tier vector, exemplifying lower-entry-pricing strategies for education and design prototyping markets.
| Leading Market Players |
|---|
| Lightspace Technologies |
| Leia Inc. |
| Voxon Photonics |
| Alioscopy |
| SeeReal Technologies |
| Looking Glass Factory |
| Holoxica Ltd |
| Holografika |
| The Coretec Group |
| Others |
Cost & Logistics Intelligence
Silicon photonics integration into light-field modulation engines collapses optical bench assemblies into chip-scale packages, simultaneously compressing unit production costs and concentrating manufacturing competence within South Korean and Japanese precision optics clusters.
Pricing Analysis
Distributor margins on swept-volume systems compress pricing transparency for defense and research buyers, while direct-to-OEM arrangements for clinical workstations preserve premium capture. Three-tier pricing structure across FDA-cleared diagnostic, IEC 60601-1 compliant industrial, and uncertified education tiers separates certification-grade premiums from volume accessibility. Cost compression in entertainment and retail segments intensifies because flat-panel OLED autostereoscopic substitutes erode addressable demand. Marketing firms and entertainment studios exhibit highest price sensitivity; defense agencies and tertiary cardiac centers demonstrate lowest sensitivity due to outcome-guarantee procurement frameworks.
Supply Chain Analysis
Returns and refurbishment flows for high-value galvanometer assemblies remain underdeveloped, creating asset-recovery inefficiencies for swept-volume system operators. Component sourcing draws from German and Japanese precision motor manufacturers for galvanometer scanners, South Korean photonics clusters for light-field modulation panels, and Taiwanese semiconductor foundries for electro-optic phase modulator arrays. Single-source vulnerability in high-speed mirror positioning components constitutes primary structural risk. Distribution runs through specialized medical device distributors for clinical applications and direct defense procurement channels for military simulation hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate between South Korea's compressed MFDS approval timelines and Germany's extended EMA Medical Device Regulation pathways, rewarding vendors with dual-territory regulatory infrastructure.
For Market Incumbents: Deepen backward integration into precision galvanometer manufacturing to neutralize German and Japanese supplier concentration risk. Expand captive production of electro-optic phase modulator arrays within Gwangju photonics clusters to compress prototyping lead times. Defensive priority centers on neutralizing flat-panel OLED substitution pressure through outcome-guarantee pilot programs that demonstrate measurable surgical planning time reduction. For New Entrants and Emerging Players: Rural hospital systems in India and Southeast Asia represent the most penetrable buyer archetype for remote surgical mentorship networks. Entry through accessible light-field education platforms creates brand recognition pipelines toward clinical upgrade cycles. Go-to-market execution should leverage Japan's METI Society 5.0 subsidy infrastructure for holographic telepresence qualification. For Investors and Strategic Acquirers: Valuations sit cheapest among swept-volume hardware fabricators with proven defense contract execution but limited medical certification progress. Long-term viability across the analysis window hinges on FDA 510(k) clearance velocity and silicon photonics integration depth. Acquisition target archetype: electrostatic modulation patent holders with clinical workstation deployments. Signal to watch: MFDS fast-track approval announcements for holographic surgical planning tools as inflection indicator for Asia-Pacific revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Collapses optical bench assemblies into chip-scale packages for compact clinical workstations. |
| FDA 510(k) Premarket Notification | Streamlines hospital procurement of holographic surgical planning systems in the United States. |
| Defense Contract Expansion | Pulls civilian medical applications into accelerated commercialization timelines through DARPA funding. |
| Photonics Cluster Capacity Buildout | Compresses prototyping lead times for light-field modulation panels in Gwangju and Daejeon. |
| Holographic Telepresence Partnership | Qualifies vendors for Japan's METI Society 5.0 subsidy infrastructure in manufacturing training. |
Research Approach
Multiple input streams — primary interviews with display engineering directors, hospital purchasing committee members, defense procurement officers, and photonics manufacturing executives; secondary validation through FDA 510(k) filings, MFDS approval databases, METI subsidy disclosures, and IEC standards documentation; plus customs records for precision motor and optical component trade flows — were reconciled through bottom-up and top-down triangulation.
Historical shipment data was cross-referenced against expert panel inputs to model volume trajectories across the projection horizon. Segmentation dimensions included hardware architecture, light engine technology, use case intensity, and institutional buyer certification requirements. CAGRs were derived from curve-fitting approaches calibrated to defense procurement acceleration patterns and medical device clearance velocity. Industry-specific forecast inputs incorporated galvanometer scanner supply constraints and silicon photonics yield improvement curves.
Underlying measurement precision varies by segment; defense procurement and FDA-cleared medical applications carry tighter precision than education and advertising installations due to disclosed contract values and regulatory filing transparency. Forecasts reflect modeling assumptions around photonics manufacturing yield curves and regulatory approval timelines. Practitioners should monitor MFDS fast-track announcements, FDA 510(k) clearance volumes, and METI subsidy allocation shifts for early signals of geographic demand migration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global 5K Display Resolution Market
Display Technologies
Electrochromic Window Market
Display Technologies
Europe Microdisplay Market
Display Technologies
AMOLED Substrate Market
Display Technologies
Touch and Display Integration IC for Tablet Market
Display Technologies
Global Wearable Display Market
Display Technologies
Projector Screen Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
Global LED Digital Signage Market
Display Technologies
Global Medical Display Market
Display Technologies
Multimedia Projectors Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Seven Segment Display Market
Display Technologies
Large Format Display (LFD) Market
Display Technologies
3D Display Market