
 Vietnam Road Freight Transport Market | 2026-2036
Vietnam Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Road Freight Transport Market Analytics
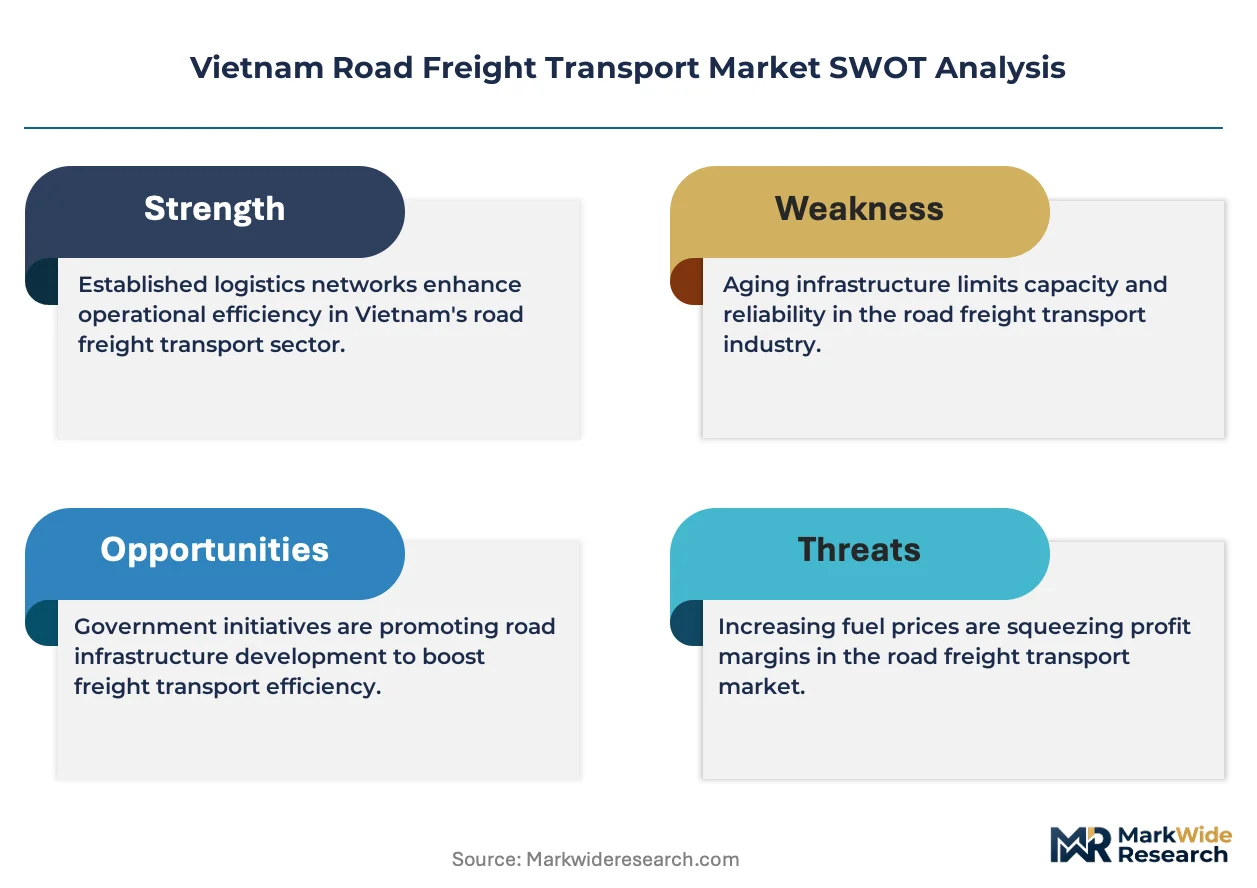
The premium full-truck-load segment is consolidating around temperature-controlled and just-in-time delivery capabilities, while commodity less-than-truck-load services compete on price across fragmented provincial lanes. Viettel Post leverages its telecom-backed digital platform to anchor last-mile density in urban centers. Indo Trans Logistics Corporation sustains cross-border dominance through Lao Cai and Lang Son gateway control. PetroVietnam Transportation Corporation differentiates via specialized freight for energy sector cargo.
Vietnam road freight transport encompasses the movement of goods overland using motor vehicles on the national highway network, with trucks dominating at load capacities from 0-5 tons for urban distribution to above 15 tons for long-haul container runs. The sector functions as the backbone of domestic supply chains, connecting seaports, industrial zones, and consumption centers across a terrain where rail coverage remains sparse. Full truck load services capture the largest revenue pool from manufacturing and retail end users moving containerized exports. Cold chain represents the fastest-expanding service type, driven by seafood and agricultural export compliance requirements. The 6-10 ton and 11-15 ton vehicle categories absorb disproportionate investment as fleet operators balance payload efficiency with road toll and axle-load regulations.
Vietnam's Ministry of Transport and the Vietnam Register enforce emission standards and vehicle inspection protocols that reshape fleet replacement cycles, while the national logistics master plan directs infrastructure investment toward expressway corridors linking northern, central, and southern economic zones. The country's national pharmaceutical regulator and food safety authority impose chain-of-custody requirements that elevate cold chain certification as a market access barrier. Stakeholders must monitor how expressway toll policies and axle-load enforcement reshape operating cost structures across vehicle type segments.
Market Dynamics
Vietnam's national logistics master plan is redirecting infrastructure investment toward expressway corridors, compressing transit times between northern, central, and southern economic zones while reshaping fleet deployment patterns across the country.
Growth Catalysts
- Electronics Domestic Sourcing:Samsung and Apple suppliers are expanding component manufacturing in Bac Ninh and Thai Nguyen provinces, generating containerized freight demand between industrial parks and seaports.
- National Logistics Master Plan:The Ministry of Transport is prioritizing expressway completion on the North-South corridor, reducing Hanoi-Ho Chi Minh City transit from 36 to 18 hours.
- Cold Chain Compliance:The food safety authority is mandating temperature logging for seafood exports to EU and US markets, forcing fleet upgrades to refrigerated vehicles.
Market Restraints
- Diesel Price Volatility:Fuel constitutes 35-40% of operating costs for Vietnamese fleet operators, with price swings eroding margin predictability on fixed-rate contracts.
- Driver Shortage Concentration:Long-haul routes face acute recruitment gaps as younger workers reject extended absences from family in the Mekong Delta and Red River Delta labor pools.
- Axle-Load Enforcement:Vietnam Register inspection protocols at weigh stations disrupt schedules and force payload reductions below rated vehicle capacity.
Strategic Opportunities
- Central Highlands Agricultural Lanes:Dak Lak and Lam Dong provinces lack refrigerated capacity for durian and coffee exports to China, creating first-mover advantage for certified cold chain operators.
- Digital Freight Matching:Smartphone penetration among owner-operators enables platform-based load consolidation, reducing empty backhaul rates on fragmented provincial routes.
- Cross-Border ASEAN Integration:Lao Cai and Lang Son border infrastructure upgrades facilitate China-Vietnam transshipment, capturing re-export flows from ASEAN manufacturing.
Industry Challenges
- Telematics Integration Complexity:Legacy fleet management systems resist API connectivity with emerging digital freight platforms, forcing middleware investments.
- Cold Chain Certification Timelines:HACCP and GDP compliance documentation for pharmaceutical transport requires 6-12 month validation cycles, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Road Freight Transport Market |
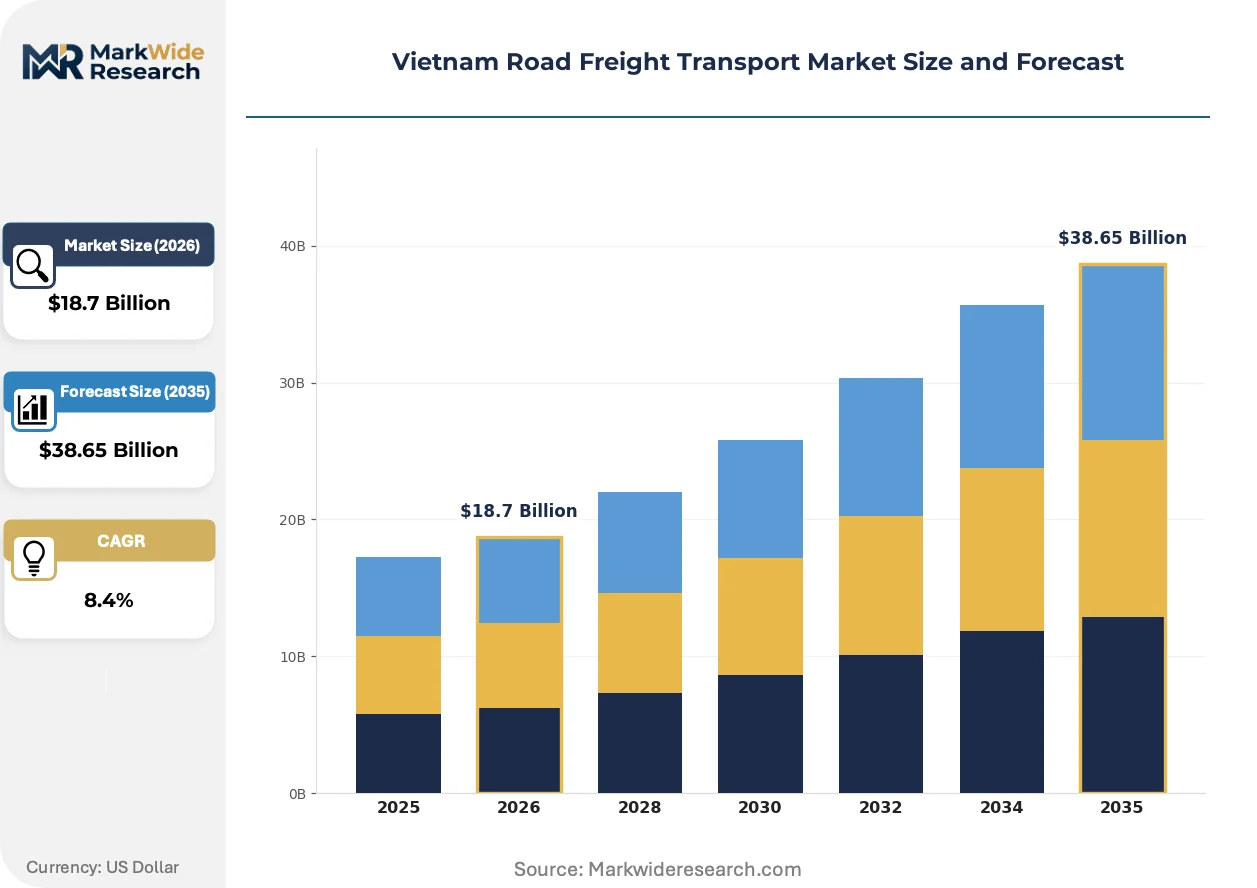
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Cold Chain, Specialized Freight Vehicle Type: Trucks, Vans, Buses, Trailers End User: Retail, Construction, Agriculture, Manufacturing Load Capacity: 0-5 Tons, 6-10 Tons, 11-15 Tons, Above 15 Tons |
| Companies Covered | A.P. Moller - Maersk, Bee Logistics Corporation, Indo Trans Logistics Corporation, PetroVietnam Transportation Corporation (PVTrans), Saigon Newport Corporation, Viettel Post, Nippon Express Holdings, Kuehne + Nagel, DHL Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Road Freight Transport Market Evolving Landscape
Digital platforms and emission regulations are converging to compress fleet replacement cycles while elevating service differentiation beyond price competition in Vietnam's road freight sector.
Telematics systems combining GPS tracking, fuel consumption monitoring, and driver behavior analytics are integrating into fleet management operations. Electronics manufacturers with just-in-time supply chains are adopting these platforms fastest, demanding real-time shipment visibility. The technology is integrating dispatch optimization with port terminal systems, reducing container dwell times at Cat Lai and Cai Mep terminals.
Vietnam Register enforcement of Euro 4 emission standards for new commercial vehicle registrations is accelerating diesel engine turnover. Domestic assemblers must source compliant powertrains, raising vehicle acquisition costs for small fleet operators. The 6-10 ton segment faces the steepest compliance burden as this category dominates urban distribution and falls under strict urban emission zone rules.
Shippers in the Ho Chi Minh City-Dong Nai-Binh Duong corridor are consolidating freight procurement through annual contracts with performance penalties. Fragmented owner-operators are losing direct factory relationships to asset-light logistics platforms that aggregate capacity. Electronics exporters with SAP-integrated supply chains are driving this consolidation, prioritizing API-connected providers over traditional phone-based dispatch.
Vietnam Road Freight Transport Market Segmentation
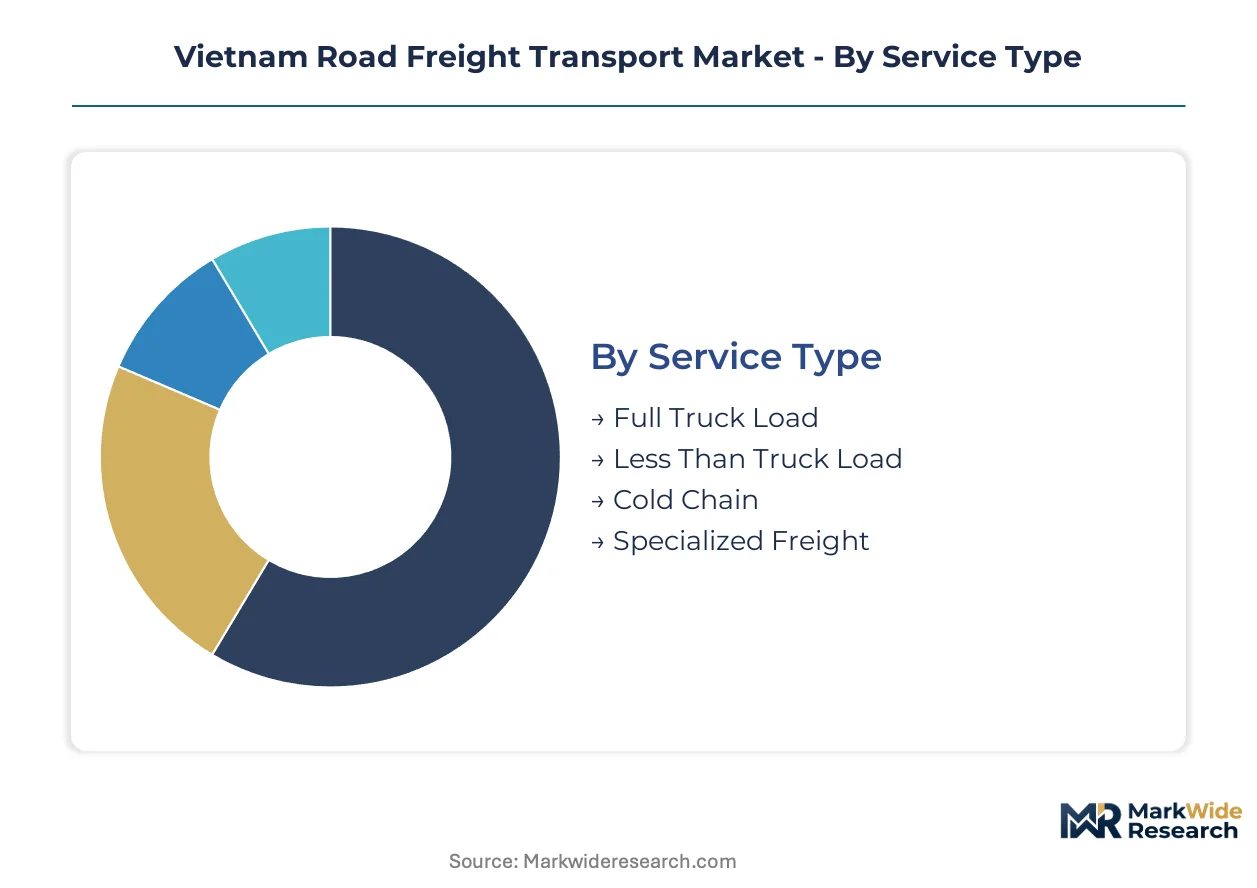
Vietnam's road freight market fragments across service tiers, vehicle classes, and cargo specifications that determine fleet investment priorities and margin structures. Electronics exporters and agricultural shippers impose divergent requirements that reshape competitive positioning across each segment boundary.
Service Type:
Volume-heavy contract logistics anchor revenue pools while premium temperature-controlled services command margin premiums.
- Full Truck Load:Dedicated vehicle allocation for single-shipper container movements between industrial parks and deepwater ports. Manufacturing exporters in the Ho Chi Minh City-Dong Nai-Binh Duong corridor drive concentration here, with annual contract structures displacing spot-market arrangements.
- Cold Chain:Refrigerated transport maintaining temperature integrity for seafood, pharmaceuticals, and fresh produce through HACCP-certified protocols. EU and US export compliance mandates from Vietnam's food safety authority are forcing fleet upgrades and certification investments.
- Less Than Truck Load:Consolidated cargo from multiple shippers sharing vehicle capacity on fragmented provincial routes. Digital freight platforms are compressing margins here through smartphone-based load matching among owner-operators.
- Specialized Freight:Oversized, hazardous, or project cargo requiring escort vehicles and route permits. Energy sector equipment and construction machinery dominate demand, with PetroVietnam Transportation Corporation anchoring this niche.
Today's leader: Full Truck Load. Tomorrow's challenger: Cold Chain.
Vehicle Type:
Fleet composition reflects payload efficiency trade-offs against axle-load regulations and urban access restrictions.
- Trucks:Rigid-body commercial vehicles from light-duty distribution to heavy-haul tractor units. The 6-10 ton and 11-15 ton categories absorb disproportionate investment as operators balance payload with Vietnam Register inspection protocols.
- Trailers:Detachable semi-trailers and container chassis enabling intermodal transfers at Cat Lai and Cai Mep terminals. Electronics manufacturers with just-in-time supply chains demand real-time trailer tracking integration.
- Vans:Light commercial vehicles below 3.5 tons for urban last-mile delivery. Viettel Post deploys these for e-commerce parcel density in Hanoi and Ho Chi Minh City.
- Buses:Converted passenger vehicles for low-volume cargo on remote routes where dedicated freight capacity remains uneconomic.
Trucks dominate asset bases. Trailers capture technology investment.
End User:
Customer concentration patterns determine contract duration and service-level requirements.
- Manufacturing:Electronics and automotive component producers requiring scheduled container movements with penalty clauses for delay. Samsung and Apple supplier networks in Bac Ninh and Thai Nguyen provinces generate predictable freight demand.
- Retail:Modern trade distributors and e-commerce fulfillment centers demanding multi-drop urban distribution. Cold chain compliance separates premium retailers from traditional wet-market suppliers.
- Agriculture:Coffee, rice, and durian exporters from the Central Highlands seeking refrigerated capacity for China-bound shipments. Dak Lak and Lam Dong provinces lack certified cold chain infrastructure.
- Construction:Cement, steel, and equipment movements tied to infrastructure project cycles. Expressway construction under the national logistics master plan is redirecting haul patterns.
Manufacturing commands contract stability. Agriculture offers expansion terrain.
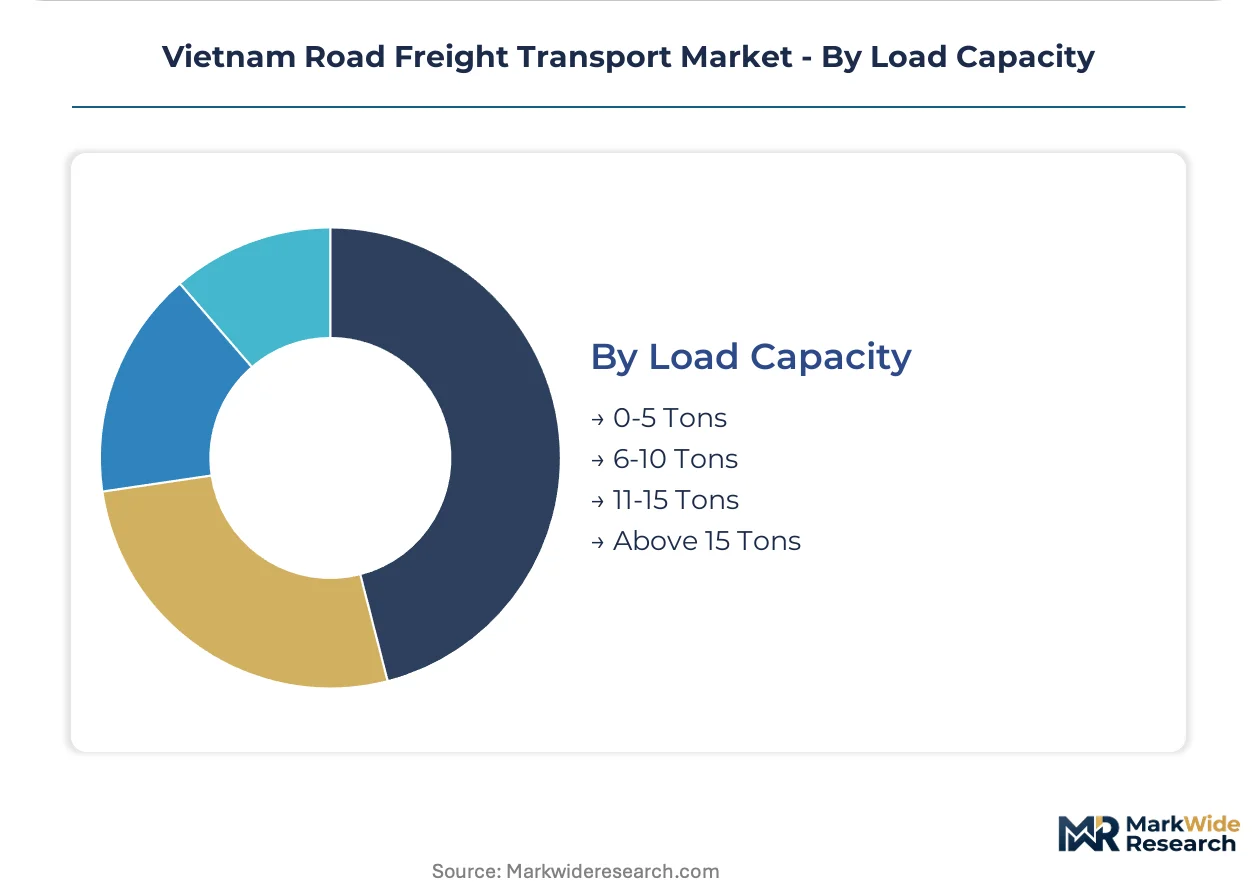
Load Capacity:
Regulatory enforcement at weigh stations and toll structures shapes optimal payload configurations.
- 6-10 Tons:Mid-weight vehicles dominating urban distribution and regional feeder services. Euro 4 emission compliance from Vietnam Register hits this segment hardest due to urban emission zone exposure.
- 11-15 Tons:Heavy-duty rigid trucks balancing payload efficiency with axle-load limits. Long-haul operators favor this category for Hanoi-Ho Chi Minh City corridor runs.
- 0-5 Tons:Light commercial vehicles for last-mile delivery and narrow-access industrial zones. Driver recruitment is least acute here due to daily return-to-base schedules.
- Above 15 Tons:Tractor-trailer combinations for containerized export movements. Axle-load enforcement forces payload reductions below rated capacity, eroding per-trip economics.
6-10 Tons anchors urban fleets. Above 15 Tons faces regulatory compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Driver pools in the Mekong Delta and Red River Delta anchor Vietnam's road freight workforce, with migration patterns concentrating operational talent around the Ho Chi Minh City-Dong Nai-Binh Duong industrial corridor.
Northern Vietnam
Electronics component manufacturing in Bac Ninh and Thai Nguyen provinces generates containerized freight demand between industrial parks and Hai Phong port. Vietnam's Ministry of Transport prioritizes expressway completion on the North-South corridor, reducing Hanoi-Ho Chi Minh City transit from 36 to 18 hours. Samsung and Apple supplier networks in this region drive predictable contract logistics volumes.
Southern Vietnam
The Ho Chi Minh City-Dong Nai-Binh Duong triangle concentrates manufacturing exporters demanding just-in-time delivery with penalty clauses for delay. Vietnam Register enforces Euro 4 emission standards for new commercial vehicle registrations, accelerating fleet turnover in urban distribution. Cat Lai and Cai Mep terminals serve as intermodal hubs where electronics exporters integrate trailer tracking with SAP supply chains.
Central Highlands
Dak Lak and Lam Dong provinces lack refrigerated capacity for durian and coffee exports to China, creating first-mover advantage for certified cold chain operators. The food safety authority mandates temperature logging for agricultural exports to EU and US markets, forcing fleet upgrades. Coffee and specialty crop processing clusters around Buon Ma Thuot and Da Lat remain underserved by temperature-controlled logistics.
Central Coast
Da Nang and Quang Nam provinces function as logistics intermediaries connecting northern and southern economic zones. Expressway toll policies reshape operating cost structures for long-haul operators traversing this corridor. The national logistics master plan directs infrastructure investment toward expressway completion, compressing transit times between economic zones.
Border Gate Zones
Lao Cai and Lang Son border infrastructure upgrades facilitate China-Vietnam transshipment, capturing re-export flows from ASEAN manufacturing. Vietnam's customs administration coordinates with Chinese counterparts to streamline cross-border clearance. Indo Trans Logistics Corporation sustains cross-border dominance through gateway control at these northern entry points.
Vietnam Road Freight Transport Market Competitive Landscape
Capital-heavy fleet operators compete with asset-light digital platforms for shipper relationships, creating a tiered structure where asset ownership separates premium contract logistics from price-commoditized spot markets. The market fragments across state-linked energy transporters, telecom-backed last-mile specialists, and global forwarders with Vietnamese operating licenses. Three archetypes dominate: integrated logistics platforms with digital freight matching capabilities, specialized cold chain operators with HACCP certification, and cross-border specialists controlling border gateway infrastructure. Competitive moves center on fleet telematics integration with shipper ERP systems and cold chain certification investments for pharmaceutical and seafood export compliance.
Among state-affiliated transport entities, PetroVietnam Transportation Corporation exemplifies the energy-sector specialist archetype through captive freight relationships with hydrocarbon producers. Viettel Post occupies a position within the telecom-integrated logistics tier, leveraging digital infrastructure density for urban last-mile coverage. Indo Trans Logistics Corporation represents the cross-border gateway specialist model, anchoring northern border corridor control. These three entities illustrate how regulatory relationships, technology platforms, and geographic positioning create defensible market positions against pure price competition.
| Leading Market Players |
|---|
| A.P. Moller - Maersk |
| Bee Logistics Corporation |
| Indo Trans Logistics Corporation |
| PetroVietnam Transportation Corporation (PVTrans) |
| Saigon Newport Corporation |
| Viettel Post |
| Nippon Express Holdings |
| Kuehne + Nagel |
| DHL Group |
| Others |
Value Network & Pricing Analysis
Diesel benchmark fluctuations cascade through Vietnam's road freight sector, compressing margins for owner-operators on fixed-rate contracts while elevating fuel surcharge mechanisms in annual agreements with electronics exporters. The Ho Chi Minh City-Dong Nai-Binh Duong corridor concentrates pricing power among integrated logistics platforms that bundle telematics visibility with dedicated fleet allocation.
Pricing Analysis
Bundled service contracts combining fleet allocation with real-time tracking command premium positioning against unbundled spot-market transactions on fragmented provincial lanes. Cold chain certification separates premium pricing tiers from commodity freight, with HACCP-validated operators capturing margin premiums for seafood and pharmaceutical exports. Price compression intensifies in less-than-truck-load segments as digital freight platforms aggregate owner-operator capacity through smartphone-based load matching. Manufacturing exporters with SAP-integrated supply chains exhibit lowest price sensitivity, prioritizing API-connected visibility over rate minimization.
Supply Chain Analysis
Certification gating through Vietnam Register Euro 4 standards and food safety authority HACCP protocols restricts fleet supply to qualified operators, concentrating compliant capacity around major industrial corridors. Vehicle assembly draws from Japanese and South Korean powertrain suppliers, while refrigerated unit imports rest on Thai and Chinese manufacturing. Single-source vulnerability sits with specialized trailer chassis for container movements at Cat Lai and Cai Mep terminals. Distribution runs through expressway corridors prioritized under the national logistics master plan, compressing transit times between northern and southern economic zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's road freight market offers margin expansion through cold chain certification premiums and telematics-enabled service bundling, as fuel cost pass-through mechanisms strengthen in contract structures with electronics manufacturers.
For Market Incumbents: Anchor defensive positioning through captive cold chain certification investments and exclusive trailer pools at Cat Lai and Cai Mep terminals. Threat from asset-light digital platforms demands API integration with shipper ERP systems as a retention lever. Consolidate provincial lane density through acquisition of owner-operator networks in the Central Highlands agricultural corridor. For New Entrants and Emerging Players: Begin with certified refrigerated capacity in Dak Lak and Lam Dong provinces, where durian and coffee exports to China lack compliant logistics infrastructure. The most penetrable segment sits with agricultural exporters seeking temperature-validated China-bound shipments. A go-to-market angle combining HACCP certification with Mandarin-language customer service captures first-mover advantage. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized cold chain operators possessing food safety authority validation and cross-border gateway control at Lao Cai or Lang Son. Long-term viability hinges on expressway corridor access and telematics platform integration. The signal to watch is enforcement intensity of axle-load regulations at Vietnam Register weigh stations, which would accelerate fleet replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Certification Investment | HACCP validation from Vietnam's food safety authority unlocks premium seafood and pharmaceutical export contracts. |
| Telematics Platform Integration | API connectivity with Samsung and Apple supplier ERP systems secures annual contract logistics relationships. |
| Cross-Border Gateway Control | Lao Cai and Lang Son infrastructure positioning captures China-Vietnam transshipment flows from ASEAN manufacturing. |
| Expressway Corridor Fleet Deployment | North-South corridor concentration aligns with Ministry of Transport infrastructure priorities reducing transit times. |
| Digital Freight Matching Capability | Smartphone-based load consolidation among owner-operators reduces empty backhaul rates on fragmented provincial routes. |
Research Methodology
Direct dialogue with fleet operations managers, logistics procurement leads at electronics manufacturers, cold chain certification specialists, and Vietnam Register enforcement officials grounded qualitative findings. Secondary validation drew from Ministry of Transport infrastructure disclosures, Vietnam Register emission standard protocols, food safety authority export compliance documentation, and customs administration cross-border trade statistics. Bottom-up fleet capacity assessments triangulated against top-down logistics spend estimates across manufacturing, retail, and agricultural end-use sectors.
Bottom-up modeling aggregated vehicle fleet composition by tonnage category and service type, while top-down approaches calibrated total addressable logistics spend against manufacturing export values. Segmentation dimensions included service tier, vehicle class, cargo specification, and regional corridor density. CAGRs were derived from trend extrapolation of fleet replacement cycles, expressway completion timelines, and cold chain compliance adoption curves. Forecast inputs incorporated diesel price volatility scenarios and driver shortage concentration patterns in Mekong Delta and Red River Delta labor pools.
Several conditions sit outside the modeled scope, including abrupt shifts in China-Vietnam trade policy, accelerated electric vehicle adoption mandates, and regional military tensions affecting border gateway operations. Forecasts reflect assumptions around steady enforcement of axle-load regulations and continued expressway investment under the national logistics master plan. A model refresh is warranted upon material change in Euro 5 emission standard announcement timing or food safety authority cold chain mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Malaysia Refrigerated Trailer Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
Latin America Cross Border Road Freight Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
Malaysia Domestic CEP Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
Chile Road Freight Transport Market
Transportation & Logistics
Cross-Border Road Transport Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
Railcar Unloader Market
Transportation & Logistics
Indonesia Road Freight Transport Market