
 Marine Hatch Covers Market | 2026-2036
Marine Hatch Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Hatch Covers Market Foresight
After-sales maintenance contracts and lifecycle service agreements are repositioning how marine hatch cover suppliers capture value beyond initial equipment sales. Palfinger Marine leverages its global service network to anchor long-term revenue from European ferry operators. TTS Group ASA sustains competitive differentiation through specialized hydraulic systems integration for harsh-environment offshore installations. Cargotec Corporation dominates port equipment adjacencies, extending its service footprint into hatch cover retrofit programs across Nordic shipping lanes.
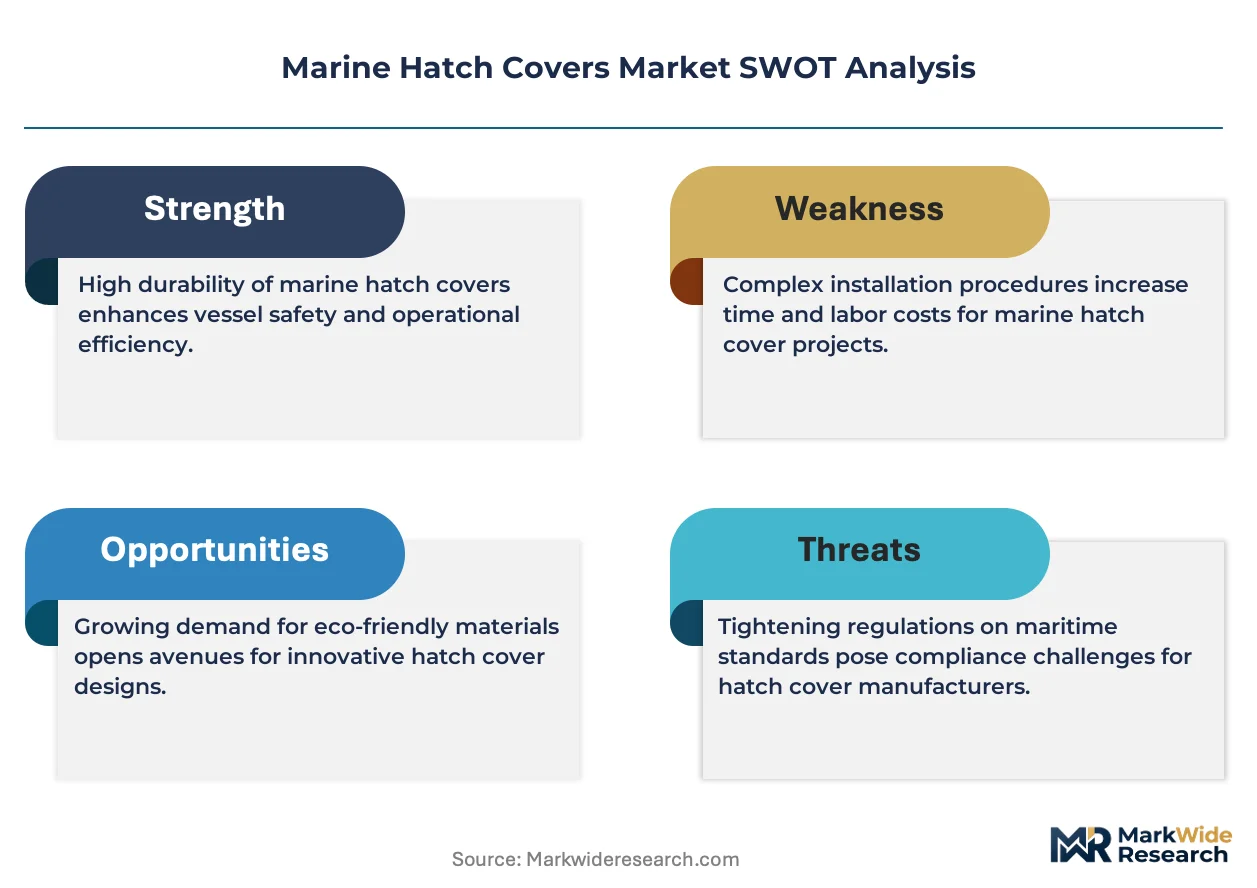
Marine hatch covers are engineered closures sealing deck openings on vessels, typically fabricated from high-tensile steel or marine-grade aluminum with rubber gasket sealing systems rated for watertight integrity under SOLAS load specifications; their primary function is to protect cargo holds, machinery spaces, and personnel areas from seawater ingress while enabling rapid access during loading and port operations. Openable hatch covers lead commercial installations due to operational flexibility in container and bulk carrier fleets, while composite material variants represent the fastest-growing segment as shipyards pursue weight reduction for fuel efficiency compliance. Steel remains the mature volume base for tanker and naval applications where structural load requirements override lightweighting priorities.
IMO SOLAS regulations mandate specific weathertight and watertight performance standards that directly shape hatch cover design loads, testing protocols, and material certification requirements for international trading vessels. Classification societies including Lloyd's Register and DNV enforce construction standards that gate market access for non-compliant manufacturers. Stakeholders must monitor evolving carbon intensity indicators and their cascade into hull weight optimization mandates that will redefine material selection criteria and supplier qualification benchmarks.
Market Dynamics
Fleet renewal programs across commercial shipping are accelerating as the International Maritime Organization tightens emissions standards, forcing operators to replace aging hatch cover systems with lightweight, compliant alternatives that reduce fuel consumption and carbon intensity.
Growth Catalysts
- IMO Carbon Intensity Indicators:The maritime regulator's tightening emissions benchmarks compel container and bulk carrier operators to retrofit vessels with weight-optimized hatch cover systems that improve vessel efficiency ratings and avoid commercial penalties.
- Steel-aluminum hybrid fabrication:Advanced welding techniques now enable shipyards to combine high-tensile steel load-bearing frames with marine-grade aluminum panels, cutting unit weight by 15-20 percent while maintaining SOLAS structural certification.
- Geoje and Ulsan shipbuilding clusters:South Korea's concentrated ultra-large container vessel construction activity generates concentrated demand for specialized hatch cover systems engineered for 24,000+ TEU vessel specifications.
Market Restraints
- High-tensile steel price volatility:Fluctuations in specialty steel alloy costs compress fabrication margins and complicate long-term contract pricing for hatch cover manufacturers serving tanker and naval segments.
- Single-source rubber gasket supply:Marine-grade EPDM sealing systems concentrate among a limited supplier base in Northeast Asia, creating vulnerability to supply disruption for European and North American hatch cover assemblers.
- Watertight testing protocol complexity:Classification society load testing requirements extend certification timelines and increase engineering overhead for manufacturers seeking multi-society approval.
Strategic Opportunities
- Indian coastal shipping modernization:The country's Sagarmala port development initiative and domestic fleet renewal programs create underpenetrated demand for mid-sized hatch cover systems serving regional bulk and container trades.
- Lifecycle service contract expansion:After-sales maintenance agreements for gasket replacement, hydraulic system refurbishment, and structural inspection open recurring revenue streams beyond initial equipment sales.
- EU Green Deal vessel retrofit mandates:The European Commission's carbon reduction targets for existing fleets drive replacement demand for lightweight hatch covers that improve vessel energy efficiency design indices.
Industry Challenges
- Certified welder scarcity:Specialized aluminum-steel hybrid welding expertise remains concentrated among aging workforces in mature shipbuilding regions, constraining production scaling for emerging fabricators.
- Multi-society approval timelines:Simultaneous Lloyd's Register, DNV, and ABS certification processes for new hatch cover designs extend time-to-revenue and increase pre-commercialization engineering investment.
- Legacy hydraulic system integration:Retrofit installations on 15-20 year vessel fleets face mechanical interface mismatches between modern automated hatch covers and existing deck machinery control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Hatch Covers Market |
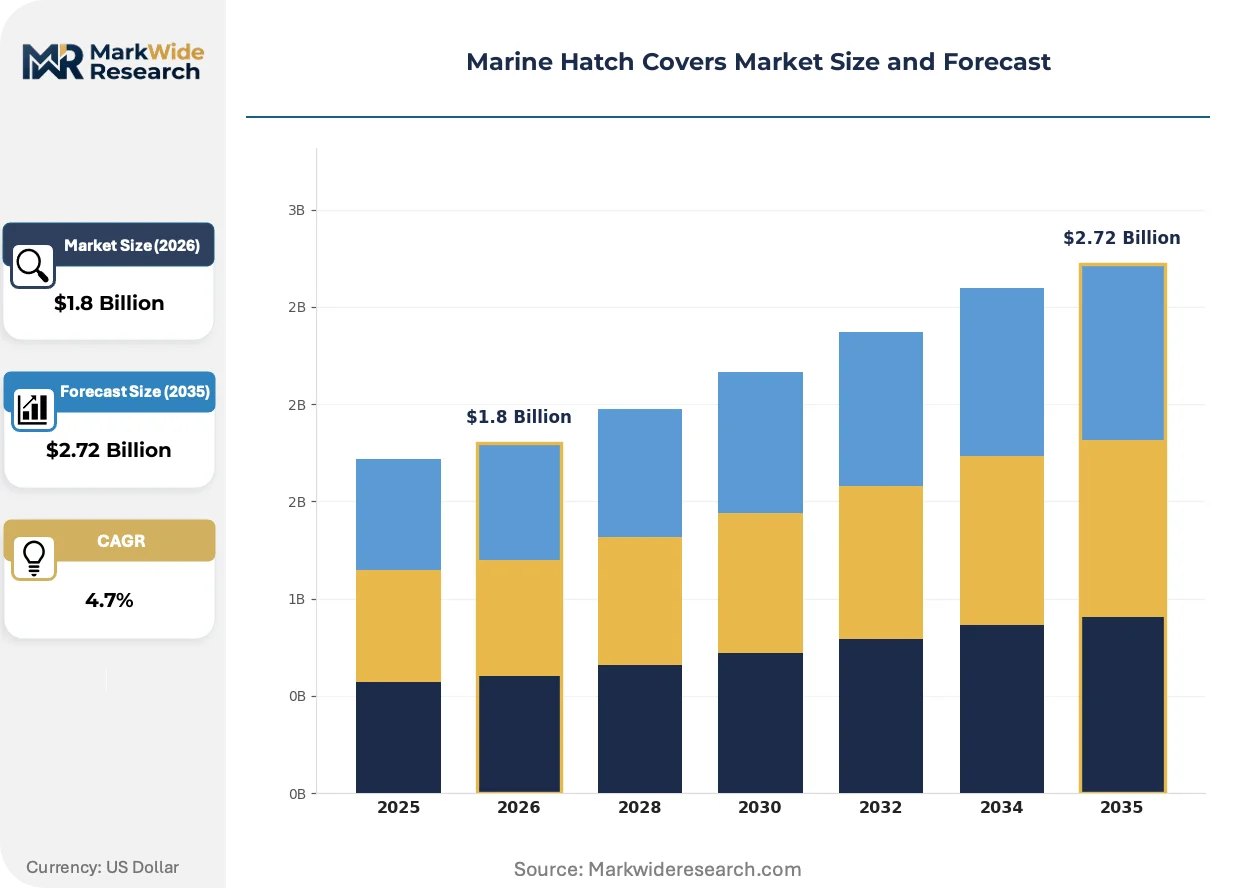
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Openable, Removable, Drop-down Material: Steel, Aluminum, FRP, Composite Application: Commercial Vessels, Cargo Ships, Tankers, Naval Ships Installation Type: Onshore, Offshore, Dry Dock, Shipyard |
| Companies Covered | Palfinger Marine, TTS Group ASA, Cargotec Corporation, Anchor & Chain, OUCO, Macor Marine Solutions, INKOW Machinery Co. Ltd., Coops Nieborg, Baier Hatch Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Hatch Covers Market Shifts & Advancements
Marine hatch cover engineering is pivoting from passive structural components to active weight-optimization systems, with material science advances and regulatory compliance automation reshaping supplier value propositions across commercial and naval vessel segments.
Composite sandwich panel construction is integrating carbon-fiber reinforced polymer skins with aluminum honeycomb cores to achieve SOLAS-mandated load ratings at 40 percent lower mass than conventional steel equivalents. Norwegian offshore support vessel operators are adopting these systems aggressively for platform supply and anchor handling fleets. The technology is integrating sensor-enabled structural health monitoring that tracks fatigue loading and predicts maintenance intervals, compressing traditional inspection-based service models.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant containment requirements for reefer vessel hatch covers, mandating enhanced sealing integrity and leak detection integration. The regulation forces manufacturers to redesign gasket compression systems and add automated monitoring ports. Mediterranean and Baltic short-sea reefer fleets face the most acute compliance pressure, with Italian and Greek operators front-loading retrofit investments ahead of 2027 enforcement milestones.
Charterers are unbundling hatch cover maintenance from bundled vessel management contracts, creating direct procurement relationships with specialized service providers. Container line procurement departments now negotiate separate agreements for gasket replacement, hydraulic refurbishment, and emergency response coverage. This pattern is most pronounced in North European trades, where Maersk and MSC have established preferred supplier panels for lifecycle service across their owned and long-term chartered fleets.
Marine Hatch Covers Market Segmentation
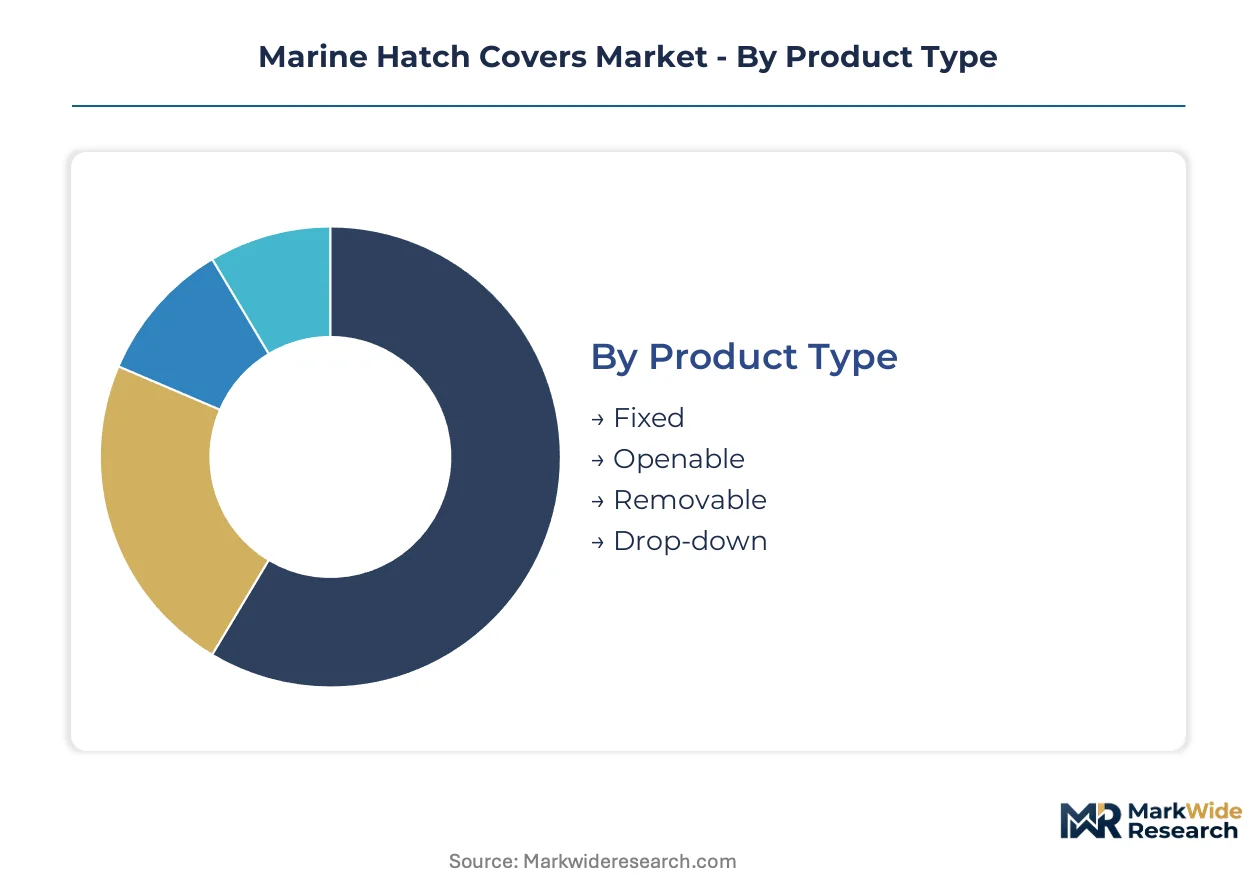
Marine hatch cover procurement patterns diverge sharply between standardized bulk orders for newbuild fleets and highly customized engineering for specialized vessel retrofits. Understanding these segmentation fault lines enables suppliers to align fabrication capacity with margin profiles across container, tanker, and naval end-uses.
Product Type:
Customization intensity varies from fully engineered one-offs to catalog-specified repeat orders across this category.
- Openable:Hinged or sliding panel systems enable rapid cargo access during port rotations while maintaining weathertight integrity under SOLAS load specifications. Container carriers operating Asia-Europe routes specify these systems most heavily as terminal automation demands faster hatch cycling times. Steel-aluminum hybrid fabrication is displacing pure steel construction in this segment as EEDI compliance tightens.
- Fixed:Permanent welded closures seal machinery spaces and void compartments where access frequency is minimal. Tanker operators in the Middle East favor fixed covers for ballast and pump room applications where structural simplicity reduces lifetime maintenance burden. The segment commands lower unit margins but anchors volume for fabricators serving crude and product tanker newbuild programs.
- Removable:Bolted panel systems suit vessel modification projects requiring intermittent access to cargo holds or deck machinery. Coastal bulk carriers in India deploy removable covers for seasonal grain trade flexibility.
- Drop-down:Vertically retracting systems maximize deck clearance for roll-on/roll-off cargo operations. Mediterranean short-sea ferry operators specify these for mixed freight configurations.
Leading the category by volume: Openable. Expanding most quickly: Drop-down systems gaining share in multipurpose vessel configurations.
Material:
Weight-optimization pressure from IMO carbon intensity regulations is redefining material selection hierarchies across commercial and naval fleets.
- Steel:High-tensile grades dominate tanker and naval applications where blast resistance and structural load-bearing override lightweighting priorities. South Korean yards specify HY-80 and HY-100 steels for ultra-large crude carriers requiring deck strength for distributed loading. Price volatility in specialty alloy feedstocks compresses fabrication margins unpredictably.
- Composite:Carbon-fiber reinforced polymer and sandwich panel construction achieves SOLAS load ratings at substantially reduced mass versus metal equivalents. Norwegian offshore support vessel operators have adopted these systems aggressively for platform supply fleets where fuel efficiency directly impacts charter economics. Sensor-embedded structural health monitoring is integrating with composite systems to predict fatigue-driven maintenance intervals.
- Aluminum:Marine-grade alloys serve passenger vessel and fast ferry segments where topside weight reduction improves stability margins. Italian shipbuilders favor aluminum for Mediterranean cruise ship retrofits.
- FRP:Fiber-reinforced plastic covers suit corrosive chemical tanker environments and select naval auxiliary craft. Limited structural certification scope constrains addressable market.
Steel commands the installed base. Composite materials are climbing the fastest as EEDI phase-in accelerates.
Application:
Vessel type determines regulatory stringency, maintenance protocols, and replacement cycle timing for hatch cover procurement.
- Commercial Vessels:Container ships, general cargo carriers, and multipurpose vessels constitute the core demand volume driven by fleet renewal programs. Operators navigating EU waters face Green Deal retrofit mandates that accelerate replacement of legacy steel covers with weight-optimized alternatives. Charter rate sensitivity in this segment compresses procurement timelines and favors suppliers with modular installation capabilities.
- Naval Ships:Warship specifications demand blast-resistant construction, electromagnetic signature management, and weapons integration compatibility. Classification through national military certification bodies rather than commercial societies extends engineering validation cycles. UK and French naval programs are prioritizing aluminum-steel hybrid systems for next-generation frigate construction.
- Cargo Ships:Dedicated bulk carriers and general cargo vessels represent mature replacement demand with standardized specification patterns. Indonesian and Vietnamese domestic fleets are modernizing under port infrastructure development programs.
- Tankers:Crude and product carriers require vapor-tight sealing systems meeting International Maritime Organization pollution prevention protocols. Greek and Singapore-flagged fleets anchor retrofit activity.
Commercial vessels lead by volume. Naval applications are gaining share fastest as defense procurement accelerates in NATO member states.
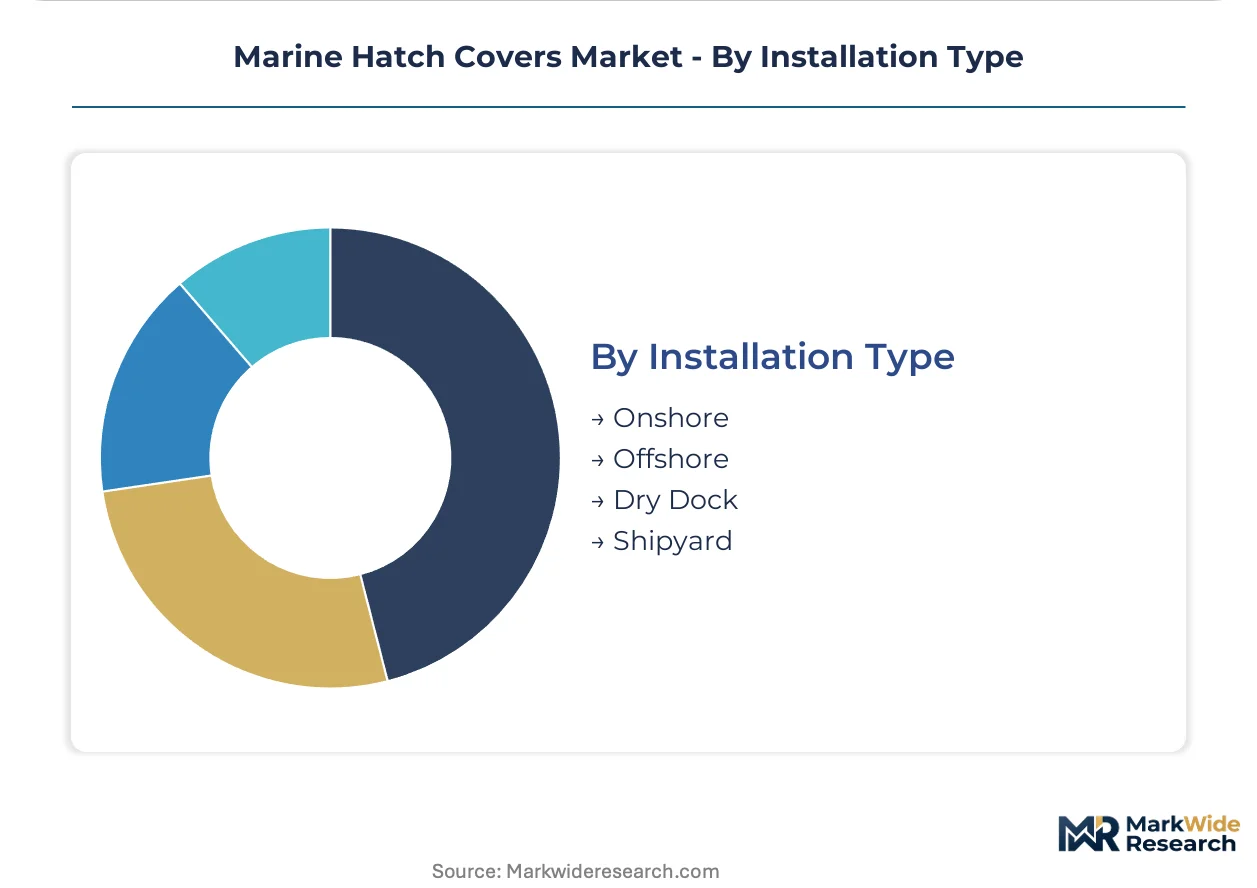
Installation Type:
Location of fitment determines logistics complexity, labor skill requirements, and contract structure for hatch cover suppliers.
- Shipyard:Newbuild integration at construction facilities enables optimized sequencing with hull block assembly and deck machinery installation. South Korean yards at Ulsan and Geoje concentrate ultra-large container vessel contracts requiring synchronized hatch cover delivery windows. Just-in-time fabrication partnerships with yard engineering departments secure preferred supplier status.
- Dry Dock:Scheduled maintenance periods provide concentrated access for comprehensive hatch cover replacement and structural modification. Northern European repair clusters at Rotterdam and Hamburg manage peak demand during winter layup seasons. Compresses project timelines and demands rapid response logistics from component suppliers.
- Onshore:Pre-assembly and testing at supplier facilities prior to vessel delivery reduces onboard installation risk. Japanese fabricators utilize onshore staging for complex automated systems requiring extensive commissioning.
- Offshore:At-sea replacement and emergency repair operations require specialized floating crane coordination and weather window management. Limited to critical operational necessity due to cost and safety constraints.
Shipyard installation dominates volume. Dry dock activity is expanding fastest as fleet age profiles trigger replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipbuilding capacity concentrates in East Asian fabrication clusters while hatch cover consumption disperses across vessel operating hubs in Europe and the Middle East. South Korean yards produce the majority of ultra-large container vessels requiring specialized deck sealing systems. European operators drive retrofit demand through emissions compliance programs.
South Korea
Ulsan and Geoje shipbuilding clusters generate concentrated demand for 24,000+ TEU container vessel hatch specifications. The Ministry of Trade, Industry and Energy coordinates national shipbuilding competitiveness initiatives supporting advanced fabrication technology adoption. Hyundai Heavy Industries and Samsung Heavy Industries anchor procurement volumes through just-in-time supplier integration programs.
China
State-owned shipyards in Dalian and Shanghai sustain volume production of bulk carriers and tankers requiring standardized hatch configurations. The Ministry of Industry and Information Technology enforces domestic content requirements under the Made in China 2025 framework. Jiangnan Shipyard and CSSC facilities in the Yangtze River Delta cluster dominate regional fabrication capacity.
Japan
Imabari Shipbuilding and Japan Marine United specialize in energy-efficient vessel designs prioritizing weight-optimized deck systems. METI administers carbon reduction incentives for fleet modernization investments. Osaka and Nagoya industrial corridors concentrate precision engineering subcontractors serving hatch cover hydraulic integration requirements.
Germany
Hamburg and Bremerhaven port operators drive lifecycle service demand for gasket replacement and structural inspection contracts. The EU Green Deal mandates vessel energy efficiency upgrades affecting retrofit procurement timelines. Meyer Werft in Papenburg focuses on cruise ship hatch specifications requiring passenger safety certification.
Greece
Piraeus-based shipowners anchor Mediterranean tanker and bulk carrier retrofit activity as carbon intensity regulations tighten. The Hellenic Ministry of Shipping coordinates flag-state compliance with IMO emission benchmarks. Greek operators front-load investments ahead of EU enforcement milestones for existing fleet modifications.
Marine Hatch Covers Market Competitive Landscape
Capital-heavy steel fabricators compete with asset-light engineering specialists across differentiated value chain positions. Market structure fragments between integrated shipyard suppliers and independent component manufacturers serving aftermarket retrofit channels. Three archetypes dominate: Korean-Japanese conglomerates with captive shipyard relationships, Nordic hydraulic system integrators, and European lifecycle service specialists. Competitive moves concentrate on welding technology licensing partnerships and geographic expansion into Indian coastal shipping markets.
Among Nordic engineering specialists, TTS Group ASA and Cargotec Corporation exemplify hydraulic integration and port equipment adjacency strategies respectively. Palfinger Marine anchors the European service network archetype through ferry operator maintenance contracts. These three entities represent distinct competitive positioning vectors: systems integration expertise, equipment ecosystem leverage, and aftermarket service density.
| Leading Market Players |
|---|
| Palfinger Marine |
| TTS Group ASA |
| Cargotec Corporation |
| Anchor & Chain |
| OUCO |
| Macor Marine Solutions |
| INKOW Machinery Co. Ltd. |
| Coops Nieborg |
| Baier Hatch Company |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between Lloyd's Register-approved premium fabricators and uncertified commodity suppliers manifests in both pricing power and supply chain architecture. Shipyards in Ulsan and Geoje pay substantial premiums for guaranteed SOLAS compliance and multi-society approval, while regional bulk carrier operators in Southeast Asia source from lower-tier fabricators accepting single-classification certification and compressed delivery timelines.
Pricing Analysis
Margin tightening in the commodity steel hatch cover tier reflects HY-80 alloy price volatility and Korean yard procurement consolidation. Three-tier pricing structure across premium, standard, and economy levels separates Lloyd's/DNV dual-certified fabricators from single-society suppliers and uncertified regional producers. Container line procurement departments exhibit highest price sensitivity due to charter rate compression, while naval programs demonstrate lowest sensitivity given blast-resistance specifications and extended validation cycles. Cost-down pressure on standard-tier fabricators accelerates because shipyards are consolidating supplier panels and demanding lifecycle service bundling.
Supply Chain Analysis
Ocean freight cost differentials between Northeast Asian steel feedstock origins and European assembly locations shape competitive positioning for hatch cover fabricators. Supply concentrates in South Korea, China, and Japan for high-tensile steel frames, with marine-grade EPDM gasket systems drawing from a limited supplier base in Northeast Asia. Raw material dependencies center on specialty steel alloys, aluminum honeycomb cores, and carbon-fiber reinforced polymer skins. Single-source vulnerability in rubber gasket supply creates disruption risk for European and North American assemblers. Distribution runs through shipyard direct procurement for newbuild programs and specialized marine service networks for aftermarket retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite sandwich panel technology is displacing conventional steel fabrication across offshore support and container vessel segments, creating asymmetric reward structures for suppliers mastering carbon-fiber aluminum honeycomb integration.
For Market Incumbents: Deploy lifecycle service contract expansion as the primary defensive lever. Lock in long-term gasket replacement and hydraulic refurbishment agreements with European ferry operators and container lines before charterers complete their unbundling of hatch cover maintenance from bundled vessel management contracts. Deepen backward integration into marine-grade EPDM sealing systems production to mitigate single-source supply vulnerability and capture margin currently flowing to Northeast Asian gasket specialists. For New Entrants and Emerging Players: Ship repair clusters in Rotterdam and Hamburg represent the most penetrable channel partner type for establishing aftermarket footholds. Target dry dock scheduling windows during winter layup seasons when Northern European operators concentrate comprehensive hatch cover replacement projects. Indian coastal shipping under the Sagarmala initiative offers white-space demand for mid-sized removable hatch systems serving seasonal grain trades. A specialized hydraulic refurbishment service model bypasses capital-intensive fabrication barriers while building relationships for eventual equipment supply. For Investors and Strategic Acquirers: Re-rating potential sits with Nordic hydraulic system integrators given EU Green Deal retrofit mandates accelerating replacement demand for lightweight automated hatch covers. Five-to-ten year viability favors suppliers combining composite material certification with sensor-enabled structural health monitoring capabilities. Acquisition target archetype: mid-cap fabricators with Lloyd's Register approval gaps that strategic buyers can close through engineering investment. The signal to watch is charterer procurement department establishment of preferred supplier panels for lifecycle service, indicating unbundling maturity and direct contract availability.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Certification Investment | DNV approval for carbon-fiber sandwich panels unlocks Norwegian offshore support vessel demand. |
| Lifecycle Service Network Expansion | Gasket replacement contracts with Maersk and MSC anchor recurring revenue beyond equipment sales. |
| Steel-Aluminum Hybrid Welding Capability | HY-80 frame with marine-grade aluminum panel construction captures IMO Carbon Intensity Indicator compliance demand. |
| Sensor-Enabled Structural Health Monitoring Integration | Fatigue loading prediction compresses inspection-based service models for platform supply fleets. |
| Indian Coastal Shipping Market Entry | Sagarmala port development creates underpenetrated demand for mid-sized removable hatch systems. |
Research Methodology
Multi-period observation of shipyard delivery schedules, classification society certification timelines, and charter rate sensitivity patterns anchored the trend analysis, supplemented by interviews with shipyard procurement directors, marine classification surveyors, hatch cover fabrication plant managers, and container line technical superintendents. Secondary validation drew from Lloyd's Register and DNV construction standards filings, IMO SOLAS regulatory updates, Korean Ministry of Trade shipbuilding competitiveness reports, and EU Green Deal maritime enforcement documentation. Bottom-up vessel fleet age profiling and top-down shipbuilding orderbook analysis were triangulated against supplier revenue segmentation.
The input-output matrix framed demand modeling across product type, material composition, vessel application, and installation location dimensions throughout the forecast period. CAGRs were derived from weighted average of historical shipbuilding output trends and regulatory compliance-driven replacement cycle acceleration. Industry-specific forecast inputs included EEDI phase-in stringency trajectories and ultra-large container vessel specification evolution at Korean yards.
Caveats apply where IMO carbon intensity benchmark revisions or specialty steel alloy supply disruptions could materially shift the outlook. Forecasts reflect assumptions about classification society approval timeline stability and charterer procurement unbundling progression. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
North America Container Terminal Operations Market
Maritime Equipment
Ship Galley Equipment Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Container Docking Stations Market
Maritime Equipment
Passenger Ferries Market