
 Norway E-Bike Market | 2026-2036
Norway E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Norway E-Bike Market Analytics
Mid-range specification tiers with 250W nominal motors and integrated battery systems is rotating demand toward higher-utility commuting platforms. Giant Manufacturing leverages its European assembly footprint to sustain competitive lead times across Nordic distribution channels. Trek Bicycle Corporation anchors its position through specialized dealer networks in Bergen and Trondheim. Riese & Müller differentiates via premium full-suspension designs that occupy the touring-adjacent segment.
An e-bike combines a pedal-assisted electric drivetrain with a rechargeable battery pack, typically rated at 36V or 48V with capacities between 400Wh and 750Wh, to augment human propulsion for urban mobility and recreational transport. Commuter configurations lead volume as Oslo's toll-ring incentives and parking constraints redirect daily transport choices. Mountain e-bikes represent the fastest-expanding product category, driven by trail access expansion in Østmarka and Nordmarka forest reserves. Lithium-ion battery systems command the dominant technology position due to energy density advantages and declining cell costs.
Norwegian Road Directorate guidelines and EU-type approval frameworks under Regulation 168/2013 shape product compliance requirements for throttle limitations and speed classifications. The Norwegian Environment Agency coordinates with municipal planners to integrate cycling infrastructure with electrified transit corridors. Stakeholders must monitor evolving battery recycling mandates and potential adjustments to purchase incentive thresholds that could reshape entry-price competitiveness.
Market Dynamics
Oslo's toll-ring congestion pricing and parking restrictions are redirecting commuter behavior toward electrified two-wheel mobility, while municipal cycling infrastructure investments create dedicated corridor access that reinforces modal shift permanence.
Growth Catalysts
- EU Regulation 168/2013 harmonization:Type-approval frameworks streamline cross-border product certification, reducing manufacturer compliance duplication across Nordic distribution channels.
- Lithium-ion energy density improvements:Cell chemistry advances extend single-charge range capabilities, eliminating range anxiety for fjord-region tourism circuits and suburban commuting corridors.
- Norwegian Environment Agency coordination:Municipal electrified transit corridor integration prioritizes cycling infrastructure alongside bus and rail electrification, creating intermodal connectivity nodes.
Market Restraints
- Battery cell supply concentration:Asian cell manufacturers dominate lithium-ion production, exposing Norwegian assemblers to shipping cost volatility and currency fluctuation risks.
- Import duty structures:Non-EU origin components face tariff friction that elevates landed costs for frames and drive systems sourced outside European trade agreements.
- Winter weather degradation:Road salt and freeze-thaw cycling accelerate frame corrosion and electrical connector fatigue, compressing component lifespans versus temperate climate benchmarks.
Strategic Opportunities
- Tromsø and Arctic Circle tourism circuits:Midnight sun and aurora viewing seasons create untapped demand for guided e-bike expedition services with extended-range battery configurations.
- Battery recycling mandate preparation:Anticipated EU Battery Regulation recycling targets position early compliance investments as competitive differentiation for circular economy credentials.
- Subscription and leasing platforms:Mobility-as-a-service models bypass upfront purchase barriers for price-sensitive urban commuters and seasonal residents.
Industry Challenges
- Certification timeline compression:EU-type approval processes for speed pedelec classifications create 4-6 month product launch delays that mismatch seasonal demand windows.
- Specialized technician scarcity:Mid-drive motor diagnostics and battery management system repair skills outpace vocational training program throughput in Norwegian technical institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway E-Bike Market |
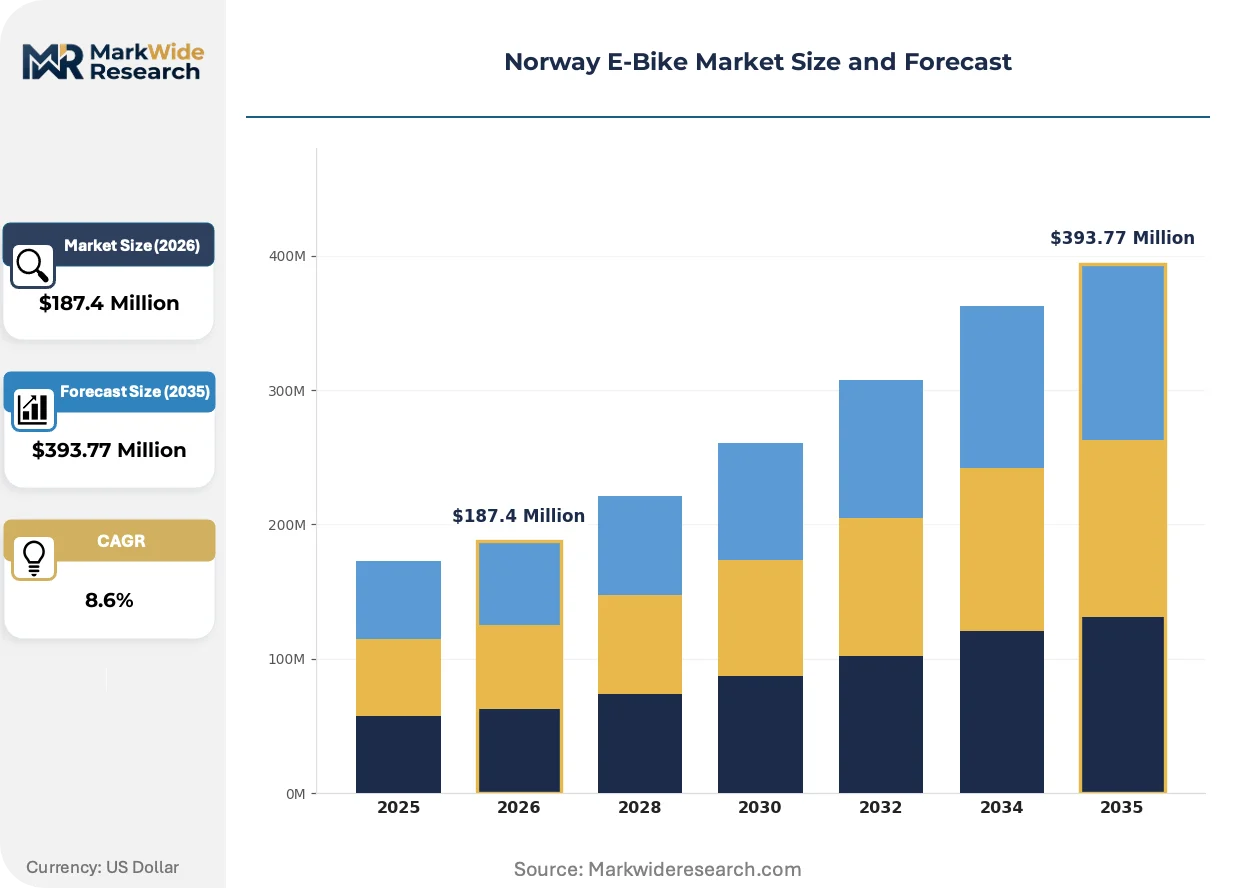
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain, Road, Commuter, Folding Battery Type: Lithium-Ion, Lead Acid, Nickel-Metal Hydride, Others End User: Urban Riders, Recreational Users, Delivery Services, Tourists Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Accell Group, Giant Manufacturing, Trek Bicycle Corporation, Kalkhoff Werke, Canyon Bicycle, Merida Industry, Cannondale Bicycle Corporation, Royal Dutch Gazelle, Riese & Müller, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway E-Bike Market Evolving Landscape
Battery chemistry evolution and drivetrain integration patterns are restructuring product architecture, while procurement behavior shifts toward service-inclusive ownership models that bundle maintenance with hardware.
Mid-drive motor systems with torque-sensing pedal assist are bifurcating the product landscape between commuter-optimized 250W nominal units and performance-oriented speed pedelec variants. Oslo's metropolitan buyers prioritize seamless transit integration and rack compatibility, while Bergen's hill-terrain commuters demand higher torque output for steep gradient climbing. This technology divergence is compressing single-speed hub motor market share to entry-price segments.
Norwegian Road Directorate guidelines incorporating EU Regulation 168/2013 throttle limitations and speed classifications are mandating firmware-locked 25 km/h assistance cutoffs for standard pedelec categories. Manufacturers must maintain separate software builds for Norwegian market compliance versus export configurations. Speed pedelec segments requiring helmet, registration, and insurance compliance are experiencing demand concentration among suburban commuters bypassing toll-ring boundaries.
Service bundling is displacing transactional hardware sales as dominant channel economics. Specialized dealer networks in Trondheim and Stavanger are pivoting toward annual maintenance contracts with battery health monitoring and seasonal storage services. This shift is most visible among urban professional demographics prioritizing reliability guarantees over capital ownership, with subscription penetration highest in Oslo's densest transit corridors.
Norway E-Bike Market Segmentation
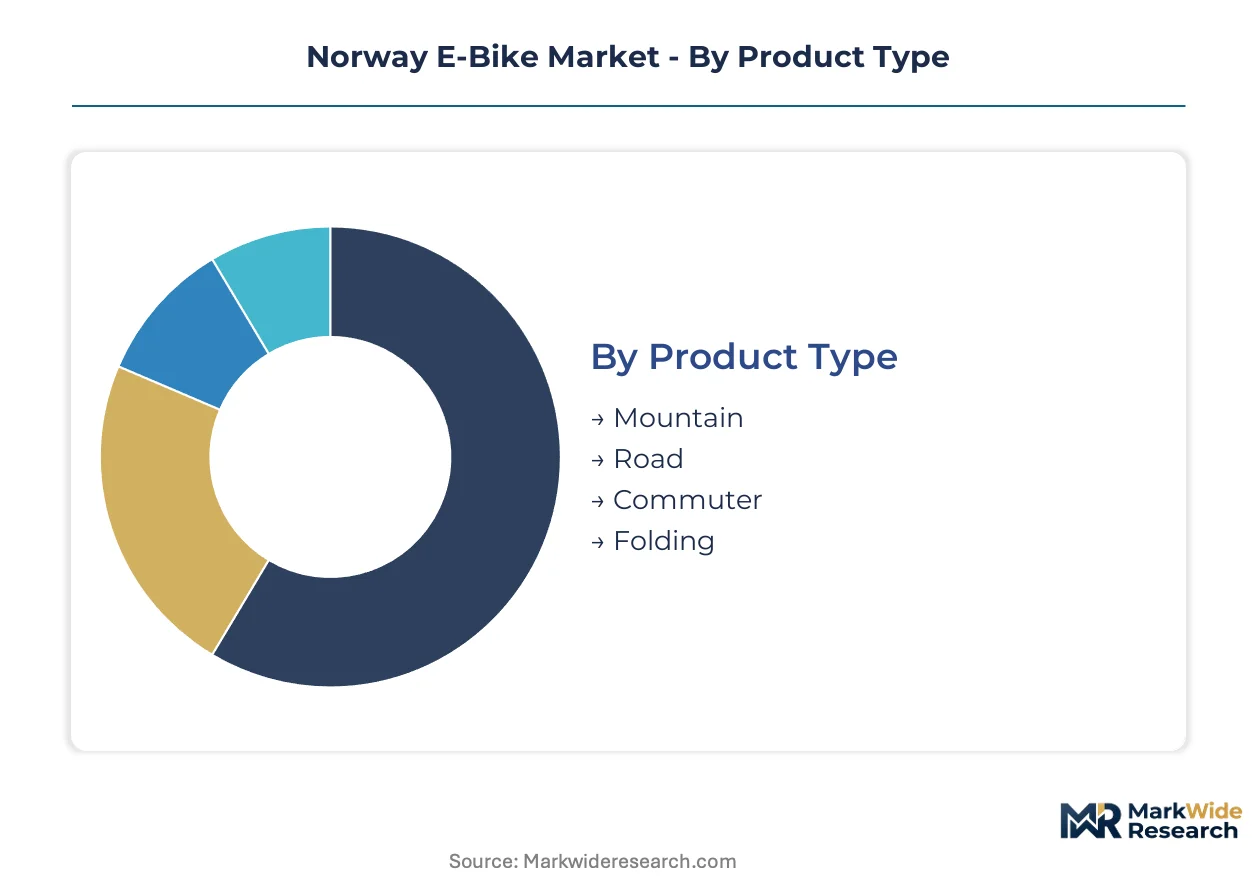
Segmentation patterns in the Norway E-Bike Market reveal distinct demand corridors shaped by topography, climate resilience requirements, and municipal incentive structures. Product architecture and battery chemistry choices diverge sharply between domestic commuter applications and export-oriented touring configurations.
Product Type:
Geographic concentration varies: commuter and folding variants dominate Oslo's toll-ring corridor and dense urban cores, while mountain and road categories serve export markets and domestic tourism circuits.
- Mountain:Full-suspension frames with 120-160mm travel and torque-rich mid-drive motors handle Østmarka and Nordmarka forest terrain. Demand clusters around Bergen's trail access expansion and guided expedition operators serving Arctic Circle circuits.
- Commuter:Step-through frames with integrated 500Wh-625Wh batteries and rack-compatible geometry prioritize Oslo's parking-constrained professionals. Norwegian Environment Agency corridor investments reinforce modal shift permanence across electrified transit nodes.
- Road:Drop-bar configurations with 250W nominal motors target fitness-oriented riders on paved fjord routes. Domestic volume remains modest; export orientation dominates production planning.
- Folding:Hinge-frame designs with 400Wh compact batteries address multi-modal commuters in Stavanger and Trondheim's constrained storage environments. Transit integration drives specification priorities.
Commuter configurations hold the largest share; momentum sits with Mountain variants as trail infrastructure expands.
Battery Type:
Cost tier alignment shapes chemistry selection: lithium-ion commands premium positioning while lead acid and nickel-metal hydride serve price-sensitive entry segments with performance trade-offs.
- Lithium-Ion:NMC and LFP cell chemistries deliver 500-750Wh capacities with 80-120km range envelopes. Norwegian assemblers source predominantly from Asian cell manufacturers, exposing supply chains to shipping cost volatility.
- Lead Acid:Heavy, cycle-limited technology persists in rental fleet applications and seasonal tourism operations where capital depreciation tolerance exceeds performance requirements. Tromsø expedition services utilize these for cost-controlled fleet scaling.
- Nickel-Metal Hydride:Intermediate energy density suits institutional procurement with moderate range demands. Municipal bike-share systems in Bergen pilot these for cold-weather reliability testing.
- Others:Solid-state prototypes and sodium-ion experimental cells occupy R&D pipelines. Norwegian technical institutes evaluate these for future Arctic temperature performance.
Lithium-Ion dominates volume and value; steepest expansion trajectory belongs to emerging solid-state alternatives in development pipelines.
End User:
Customer type fragmentation reflects income stratification and usage intensity: daily commuters anchor replacement demand while tourists and delivery services drive seasonal volatility.
- Urban Riders:Oslo's toll-ring boundary workers prioritize reliability guarantees and theft-resistant locking systems. Subscription penetration runs highest among this demographic.
- Recreational Users:Weekend trail riders in Nordmarka and Sunnmøre Alps demand full-suspension durability and extended-range batteries for all-day excursions.
- Delivery Services:Cargo-capable frames with dual-battery 1000Wh+ configurations serve last-mile logistics across Bergen's hill terrain. Fleet operators negotiate volume maintenance contracts.
- Tourists:Guided fjord circuit operators specify step-through frames with weather-sealed electronics. Midnight sun seasonality compresses annual utilization into concentrated summer months.
Urban Riders represent the installed base core; gaining share fastest are Delivery Services as logistics electrification accelerates.
Price Tier:
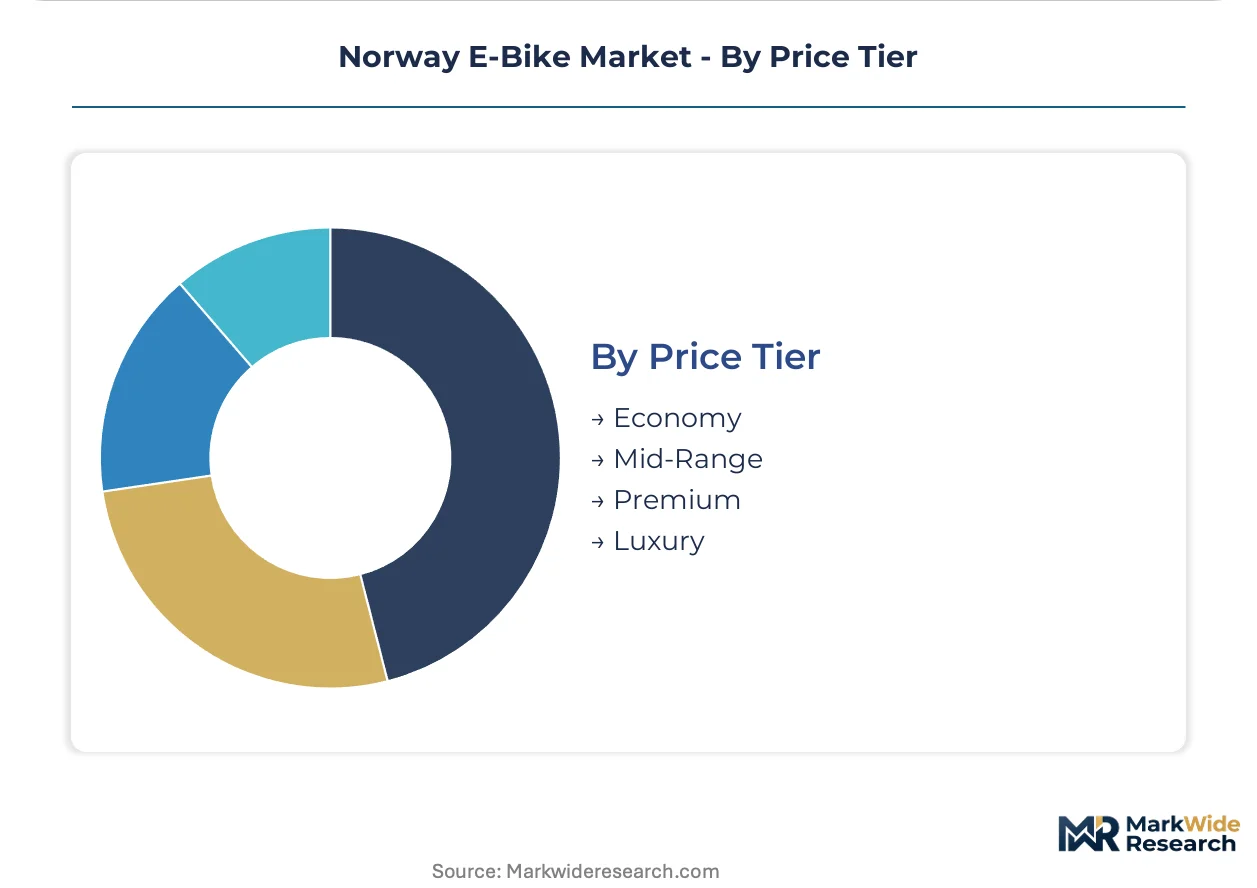
Margin structure concentrates at extremes: economy segments sacrifice serviceability for entry access while luxury tiers capture brand premium through bespoke frame geometry and concierge maintenance.
- Economy:Hub-motor designs with 400Wh batteries and steel frames target students and seasonal residents. Oslo's densest corridors show highest concentration.
- Mid-Range:250W mid-drive systems with 500Wh integrated batteries and hydraulic disc brakes serve mainstream commuters. This tier captures the broadest demographic cross-section.
- Premium:Carbon-fiber frames with 625Wh batteries and smartphone connectivity command professional buyer loyalty. Trondheim and Stavanger dealer networks specialize here.
- Luxury:Custom geometry, belt-drive systems, and annual maintenance bundling target high-net-worth individuals in Oslo's western districts. Riese & Müller and comparable brands anchor this tier.
Mid-Range captures volume leadership; Premium climbs the fastest as service bundling displaces transactional sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity concentrates in German and Dutch industrial corridors serving Nordic distribution networks. Norwegian municipalities coordinate infrastructure investments with neighboring regulatory frameworks. Cross-border type-approval harmonization under EU Regulation 168/2013 shapes product flow patterns across Scandinavian markets.
Germany
Kalkhoff Werke and Riese & Müller anchor mid-drive system production for premium export tiers. KBA vehicle certification requirements align with Norwegian Road Directorate speed classification protocols. Stuttgart's engineering clusters supply torque-sensing pedal assist modules to Oslo's metropolitan dealer networks.
Netherlands
Royal Dutch Gazelle and Accell Group dominate step-through frame manufacturing for flat-terrain commuter specifications. REACH chemical compliance mandates shape battery enclosure material selections. Eindhoven's component fabrication hubs export integrated 500Wh battery systems to Bergen's hill-terrain retrofit market.
Denmark
Copenhagen's cycling infrastructure investments create demand spillover for Norwegian tourism circuit operators. Danish Energy Agency electrification targets align with Norwegian Environment Agency corridor coordination. Aarhus municipal bike-share procurement influences Nordic fleet specification standards.
Sweden
Giant Manufacturing leverages its European assembly footprint for lead-time compression into Nordic channels. Swedish Transport Administration cycling path investments mirror Norwegian municipal infrastructure patterns. Gothenburg's port logistics handle lithium-ion cell transshipment to Tromsø expedition fleet operators.
Belgium
EU institutional presence in Brussels accelerates regulatory harmonization for battery recycling mandate preparation. Flanders' technical institutes collaborate with Norwegian counterparts on solid-state cell cold-weather performance testing. Antwerp's port infrastructure serves as alternative routing for Asian cell manufacturers avoiding North Sea congestion.
Norway E-Bike Market Competitive Landscape
Concentration sits with European assembly specialists possessing integrated battery system capabilities and established Nordic distribution channels. Tiered competition separates premium full-suspension fabricators from volume commuter platforms and economy hub-motor suppliers. Strategic archetypes include vertically integrated frame-and-motor manufacturers, specialist suspension tuners, and regional assemblers sourcing drive systems from third-party suppliers. Dominant competitive moves encompass dealer network exclusivity arrangements and firmware-locked compliance builds for market-specific regulatory requirements.
Among German-based premium fabricators, Riese & Müller and Kalkhoff Werke occupy positions emphasizing torque-rich mid-drive configurations and extended-range touring specifications. Giant Manufacturing, a Taiwan-based Co., Ltd., represents the scale-driven archetype with European assembly footprint advantages. Trek Bicycle Corporation anchors the specialist dealer network model through established presence in Bergen and Trondheim corridors. These three exemplify divergent strategic postures: bespoke geometry customization, continental manufacturing scale, and localized service infrastructure investment respectively.
| Leading Market Players |
|---|
| Accell Group |
| Giant Manufacturing |
| Trek Bicycle Corporation |
| Kalkhoff Werke |
| Canyon Bicycle |
| Merida Industry |
| Cannondale Bicycle Corporation |
| Royal Dutch Gazelle |
| Riese & Müller |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements for lithium-ion cells lock in both supply access and price visibility for Norwegian assemblers, insulating mid-range product tiers from Asian spot market volatility while compressing margins on premium configurations where spot sourcing persists.
Pricing Analysis
EU Regulation 168/2013 dictates the pricing tier structure through speed classification compliance costs. Three-tier pricing structure across premium, standard, and economy levels separates speed pedelec variants requiring registration and insurance from standard 250W pedelecs. Price differentiation hinges on battery capacity grade and firmware certification tier. Cost compression in economy hub-motor segments is intensifying because import duty exposure on non-EU frames elevates landed costs. Urban professional commuters show lowest price sensitivity, while students and seasonal residents drive volume at entry tiers.
Supply Chain Analysis
Inventory cycles stretching 8-12 weeks for integrated battery systems force Norwegian distributors to pre-position stock ahead of spring demand windows. Cell production concentrates in China, South Korea, and Japan, with Norwegian assemblers drawing from German and Dutch frame fabrication hubs. Raw material dependencies span lithium carbonate, nickel sulfate, and rare-earth magnets for mid-drive motors. Single-source vulnerability in torque-sensor modules creates chokepoint exposure. Distribution runs through specialized dealer networks in Oslo, Bergen, and Trondheim with seasonal storage services bundled.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Norway E-Bike Market is positioned for cyclical recovery as municipal infrastructure investment accelerates through Norwegian Environment Agency corridor coordination programs.
For Market Incumbents: Compound dealer network exclusivity arrangements in Trondheim and Stavanger to lock out emerging subscription platform competitors. Deepen backward integration into battery management system firmware development to differentiate service bundling offers. Prioritize certification investment for anticipated EU Battery Regulation recycling mandates ahead of compliance deadlines.
For New Entrants and Emerging Players: After-sales service gaps in Arctic Circle expedition fleet maintenance present white-space entry points. Tromsø and northern tourism circuits remain underpenetrated by incumbent service infrastructure. Target cargo-capable configurations for Bergen's hill-terrain delivery services through direct fleet operator contracting rather than retail channel buildout.
For Investors and Strategic Acquirers: Specialist suspension tuners with established Nordmarka trail access partnerships represent compelling acquisition targets. Long-term viability over the coming decade rests on circular economy credential positioning ahead of regulatory enforcement. Monitor Norwegian Road Directorate speed classification threshold adjustments as inflection indicators for speed pedelec segment expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Recycling Compliance Investment | Early EU Battery Regulation alignment secures circular economy credentials for Norwegian assemblers. |
| Subscription Platform Launch | Mobility-as-a-service models bypass upfront purchase barriers in Oslo's densest transit corridors. |
| Arctic Expedition Fleet Partnership | Midnight sun tourism circuits in Tromsø create seasonal demand concentration for extended-range configurations. |
| Dealer Network Exclusivity Expansion | Specialized service infrastructure in Bergen and Trondheim locks in professional commuter loyalty. |
| Firmware-Locked Compliance Build | Separate Norwegian market software configurations satisfy EU Regulation 168/2013 throttle limitations. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across public and proprietary sources. Interviews covered product managers at European assemblers, procurement leads at Norwegian dealer networks, municipal transport planners in Oslo and Bergen, and technical training directors at vocational institutes. Secondary sources included Norwegian Road Directorate regulatory filings, EU type-approval databases under Regulation 168/2013, customs import records, and municipal infrastructure investment disclosures. Bottom-up unit demand modeling triangulated against top-down market sizing from battery capacity shipments and dealer inventory turns.
Across the analysis window, forecasts incorporate product type segmentation by frame geometry and motor placement, battery chemistry tier by cell format and capacity, end-user archetype by usage intensity and income stratification, and price tier by specification bundle and service inclusion. CAGRs were derived from trend extrapolation of historical adoption curves adjusted for infrastructure investment trajectories and incentive policy continuity. Key inputs include lithium-ion cell cost decline curves, trail access expansion timelines in Østmarka and Nordmarka, and toll-ring boundary adjustments affecting commuter modal choice.
Underlying assumptions cover regulatory harmonization continuity, incentive threshold stability, and supply chain lead-time normalization, with deviation risk concentrated in battery cell shipping cost volatility and vocational training throughput for mid-drive diagnostics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
E-Rickshaw Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
South Africa Electric Cars Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
Mexico Electric Car Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
North America Wireless Electric Vehicle Charging Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Electric Vehicle Rental Market