
 Vehicle Intelligence System Market | 2026-2036
Vehicle Intelligence System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Intelligence System Market Outlook
Software-defined feature subscriptions is broadening what automakers monetize per vehicle. Robert Bosch GmbH leverages its sensor portfolio to anchor recurring revenue from over-the-air updates. Continental AG competes through deep specialization in AI-driven predictive algorithms. Denso Corporation sustains manufacturing scale across North American and Asian production corridors.
A vehicle intelligence system integrates artificial intelligence, machine learning, computer vision, and sensor fusion to process real-time vehicular and environmental data for decision-making, typically operating with sub-100-millisecond latency for safety-critical functions. Its primary purpose spans autonomous navigation, collision avoidance, and operational optimization across commercial and passenger transport. Sensor fusion hardware captures the largest margin pool due to silicon complexity and calibration requirements, while predictive maintenance software registers the fastest expansion as fleet operators prioritize uptime economics. Driver assistance applications remain the most mature segment with established OEM integration pathways.
NHTSA, the EU AI Act, and Japan's METI each shape product standards and market access through divergent testing protocols and liability frameworks. The EU AI Act imposes risk-classification requirements on autonomous decision systems that directly affect software architecture choices. Stakeholders must monitor regulatory fragmentation between safety-critical certification regimes and data governance rules to align R&D spend with enforceable compliance thresholds.
Market Dynamics
NHTSA's advancing automatic emergency braking mandates are compressing OEM procurement timelines and forcing tier-one suppliers to accelerate AI validation cycles while maintaining sub-100-millisecond safety-critical latency thresholds.
Growth Catalysts
- EU AI Act risk-classification framework:The regulation mandates conformity assessments for autonomous decision systems, creating certified supplier tiers that reward early compliance investments with preferred OEM status.
- Commercial fleet uptime economics:Logistics operators are prioritizing predictive maintenance software to minimize vehicle downtime, driving recurring revenue models for platform providers.
- Sensor fusion silicon complexity:Calibration-intensive hardware requirements are locking in premium margin structures for specialized component manufacturers serving German and Japanese automotive corridors.
Market Restraints
- LiDAR and radar component cost volatility:Semiconductor supply concentration in East Asian foundries exposes sensor module producers to input price swings that compress gross margins.
- Regulatory fragmentation between NHTSA and EU AI Act:Divergent testing protocols and liability frameworks force parallel certification tracks that inflate R&D overhead.
- Edge computing hardware substitution:Centralized vehicle architectures threaten distributed sensor processing nodes, pressuring specialized chip suppliers.
Strategic Opportunities
- India's automotive PLI scheme:Production-linked incentives for advanced driver assistance system manufacturing are attracting component localization investments from tier-one suppliers.
- Over-the-air update channel expansion:Software-defined vehicle platforms enable subscription monetization of safety and convenience features previously sold as hardware.
- 5G-V2X and edge AI convergence:Integration of cellular vehicle-to-everything networks with onboard inference engines creates new data service revenue streams for telecom-automotive partnerships.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 certification expertise is concentrated among a limited pool of specialists, constraining supplier scaling capacity.
- Legacy CAN bus integration complexity:New intelligent systems must interface with decades-old vehicle network architectures, requiring costly protocol translation layers.
- AI model validation timeline compression:Edge case simulation requirements for neural network deployment are extending certification cycles beyond OEM platform launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Intelligence System Market |
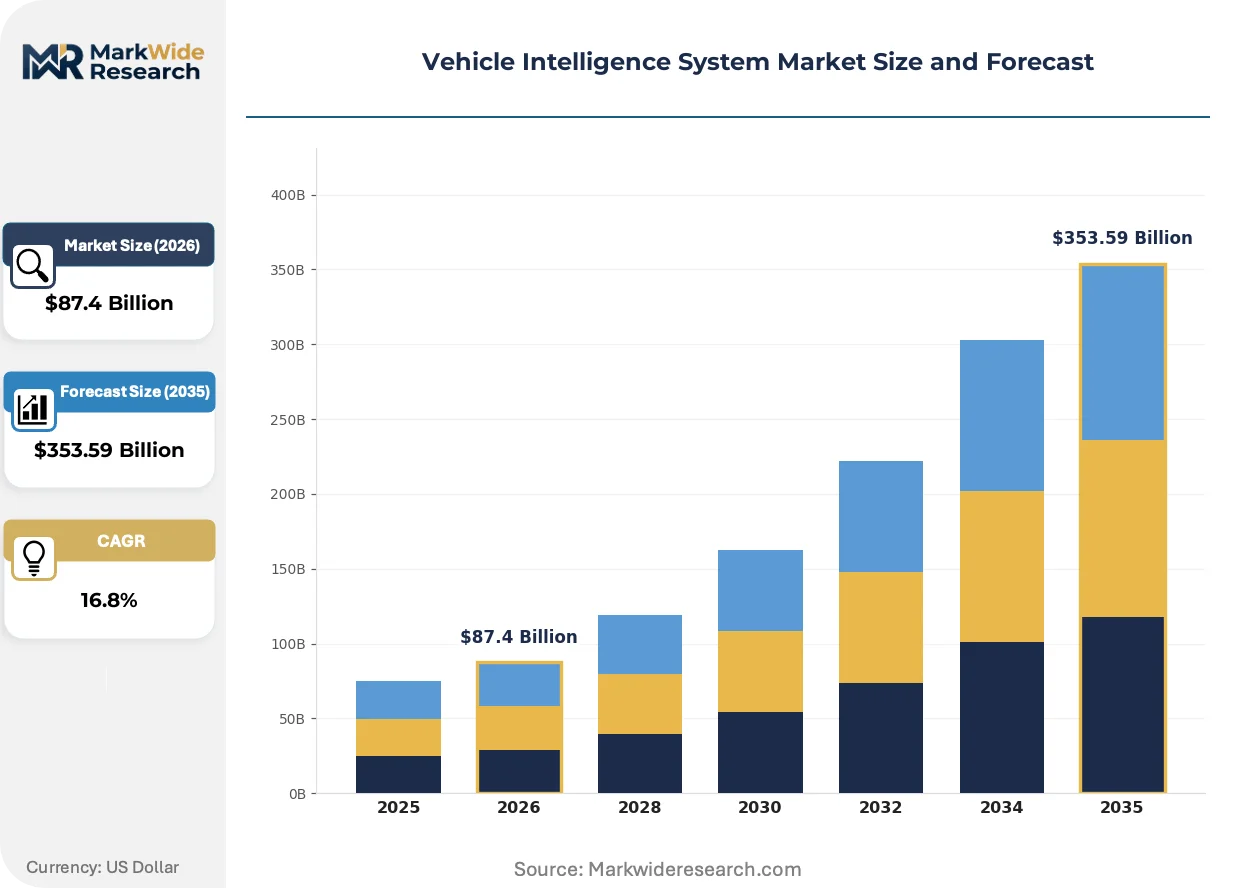
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $353.59 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Artificial Intelligence, Machine Learning, Computer Vision, Sensor Fusion Application: Fleet Management, Autonomous Driving, Predictive Maintenance, Driver Assistance Component: Hardware, Software, Connectivity Modules, In-Vehicle Systems End User: OEMs, Tier-1 Suppliers, Fleet Operators, Aftermarket Providers |
| Companies Covered | Continental AG, Denso Corporation, Robert Bosch GmbH, Autoliv Inc., Aptiv PLC, ZF Friedrichshafen AG, Magna International Inc., Hyundai Mobis, Valeo S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Intelligence System Market Strategic Shifts
Edge inference architectures are redistributing computational load away from centralized domains, while regulatory pressure on algorithmic transparency is forcing explainable AI investments. Procurement patterns are simultaneously fragmenting as fleet operators and OEMs diverge on platform specifications.
Neural network processing at the sensor node is decentralizing perception pipelines that previously routed raw data to centralized domain controllers. Tier-one suppliers are adopting this architecture for next-generation driver assistance platforms. The shift is compressing wiring harness complexity and reducing latency-critical data transmission costs.
The EU AI Act's high-risk system classification is mandating algorithmic audit trails and human oversight interfaces for autonomous decision modules. Automotive software architects are reengineering neural network architectures to satisfy explainability requirements. German OEMs are most affected, with product roadmaps being adjusted to accommodate conformity assessment timelines.
Fleet operators are unbundling predictive maintenance contracts from vehicle acquisition, purchasing software subscriptions directly from platform vendors rather than through OEM intermediaries. This channel disintermediation is most visible in North American commercial transport verticals, where uptime guarantees now drive vendor selection criteria independent of vehicle brand.
Vehicle Intelligence System Market Segmentation
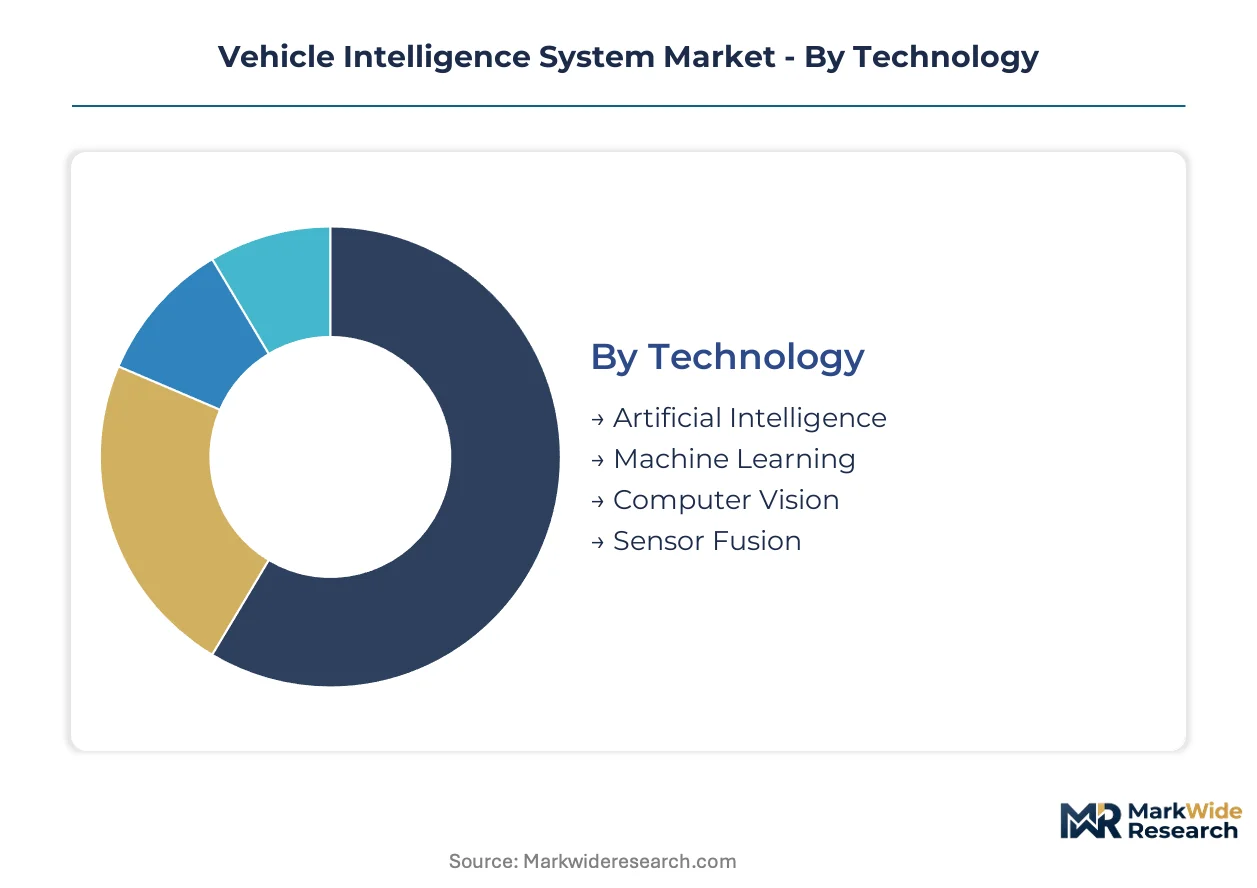
Segmentation in vehicle intelligence systems reveals how procurement priorities diverge between safety-critical hardware and software monetization channels. Buyers weight latency specifications against subscription revenue potential when allocating platform budgets across technology layers.
Technology:
Procurement teams prioritize inference speed and certification complexity when selecting core technology stacks for platform integration.
- Artificial Intelligence:Neural network architectures process real-time driving decisions with sub-100-millisecond latency requirements. Demand concentrates among German OEMs integrating EU AI Act-compliant audit trails into autonomous modules.
- Machine Learning:Predictive algorithms optimize fleet routing and energy consumption through continuous model refinement. Logistics operators in the United States prioritize uptime economics when sourcing ML-driven maintenance platforms.
- Computer Vision:Camera-based perception systems interpret traffic scenarios and pedestrian detection.
- Sensor Fusion:Multi-modal data integration combines LiDAR, radar, and optical inputs for redundancy.
Artificial Intelligence leads on scale; Machine Learning leads on momentum.
Application:
Commercial buyers and passenger vehicle OEMs diverge sharply on feature prioritization and deployment timelines.
- Driver Assistance:Established ADAS platforms including adaptive cruise control and lane-keeping assist dominate current OEM integration pathways. Japanese automakers anchor volume demand through standardized sensor suites across mass-market vehicle lines.
- Predictive Maintenance:Fleet uptime optimization drives software subscription purchases independent of vehicle acquisition. North American logistics corridors show strongest uptake as operators unbundle maintenance contracts from OEM channels.
- Autonomous Driving:Full self-driving stacks remain in validation cycles with extended certification timelines.
- Fleet Management:Centralized vehicle monitoring and route optimization serve commercial transport operators.
Driver Assistance leads on scale; Predictive Maintenance gains share fastest.
Component:
Margin concentration follows silicon complexity and calibration requirements rather than unit volume.
- Hardware:Sensor modules and edge computing units capture premium margins due to semiconductor fabrication complexity and thermal management specifications. German and Japanese production corridors concentrate manufacturing scale for fusion processors.
- Software:Over-the-air update platforms enable recurring revenue from feature subscriptions previously sold as physical components. Robert Bosch GmbH and Continental AG compete through predictive algorithm specialization.
- Connectivity Modules:5G-V2X and cellular integration enable vehicle-to-infrastructure communication.
- In-Vehicle Systems:Integrated cockpit processors consolidate infotainment and safety functions.
Hardware leads on scale; Software shows the steepest expansion trajectory.
End User:
Channel structure determines pricing power and technical specification authority in procurement negotiations.
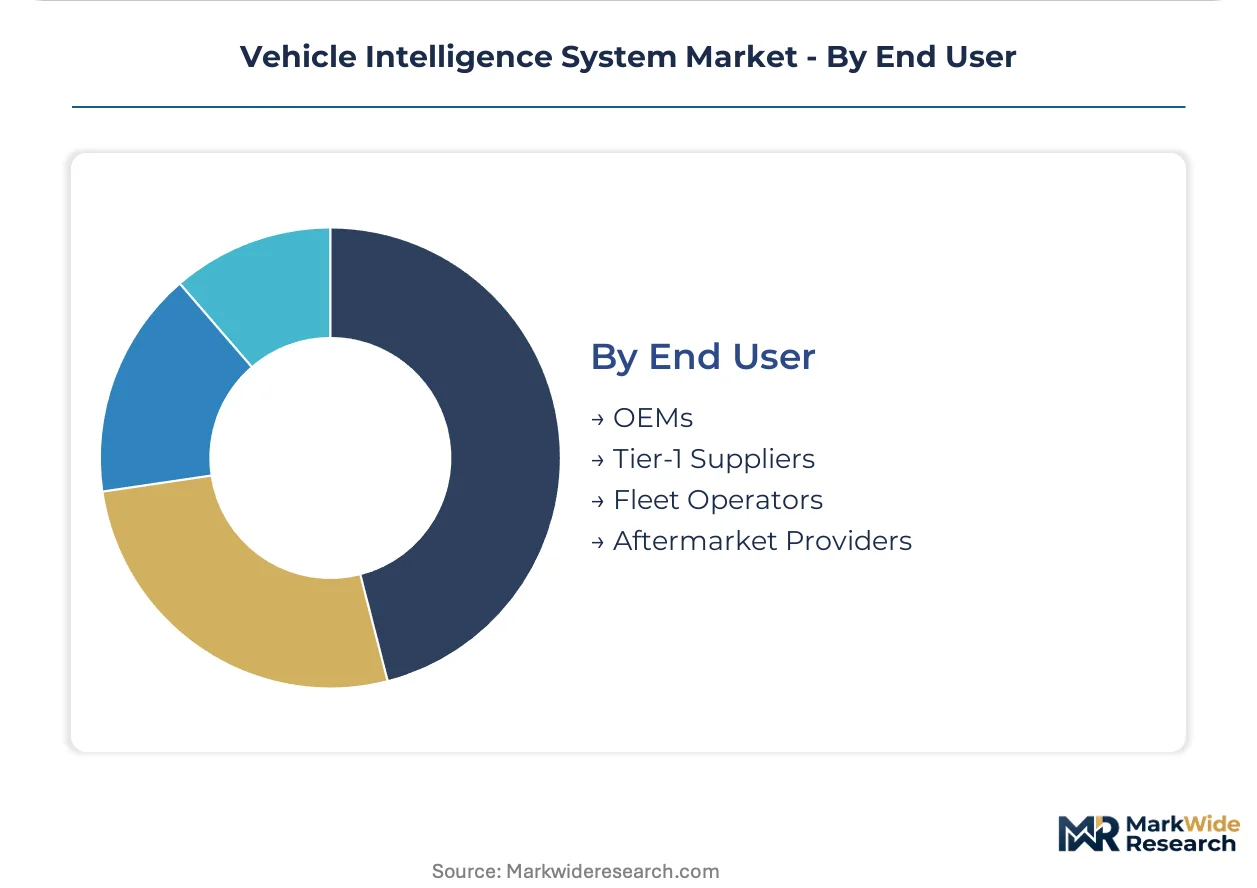
- OEMs:Vehicle manufacturers specify platform architectures and validate supplier compliance with NHTSA automatic emergency braking mandates. Procurement timelines compress as federal standards advance, forcing accelerated AI validation cycles.
- Fleet Operators:Commercial transport buyers increasingly source predictive maintenance software directly from platform vendors, bypassing OEM intermediaries. Uptime guarantees now drive vendor selection criteria in North American corridors.
- Tier-1 Suppliers:Component integrators bridge OEM specifications with specialized sensor and algorithm providers.
- Aftermarket Providers:Retrofit installation serves vehicle owners seeking post-purchase feature upgrades.
OEMs lead on scale; Fleet Operators lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as suppliers migrate toward jurisdictions with streamlined certification pathways and production-linked incentive schemes. Cost-of-compliance gaps between NHTSA and EU AI Act regimes are accelerating facility relocation decisions among tier-one component producers.
United States
NHTSA's advancing automatic emergency braking mandates are compressing OEM procurement timelines and accelerating AI validation investments. Federal Motor Vehicle Safety Standards enforcement creates compliance urgency for domestic sensor fusion suppliers. Michigan and Ohio automotive corridors concentrate tier-one engineering centers where suppliers maintain sub-100-millisecond latency testing facilities.
Germany
EU AI Act high-risk system classifications are mandating algorithmic audit trails and human oversight interfaces for autonomous modules. KBA conformity assessment requirements are extending product development cycles for Stuttgart and Munich-based OEMs. Baden-Württemberg's manufacturing belt anchors sensor fusion hardware production serving premium vehicle platforms.
Japan
METI standards for autonomous driving safety validation are creating preferred supplier tiers among domestic component manufacturers. JIS certification requirements for automotive AI systems enforce rigorous testing protocols. Aichi Prefecture's Nagoya-Toyota industrial corridor concentrates edge computing hardware fabrication for Asian export markets.
China
MIIT intelligent connected vehicle regulations are mandating data localization and security assessments for foreign platform providers. GB standards for autonomous driving systems create parallel certification tracks that inflate market entry costs. Yangtze River Delta clusters around Shanghai host domestic LiDAR and radar module production scaling for local OEM procurement.
India
Automotive PLI scheme production-linked incentives for advanced driver assistance systems are attracting component localization investments from tier-one suppliers. BIS certification requirements for automotive electronics create compliance frameworks for import substitution. Tamil Nadu and Gujarat manufacturing corridors concentrate sensor module assembly operations serving domestic and export demand.
Vehicle Intelligence System Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated tier-one suppliers commanding premium positioning in safety-critical hardware while software platforms fragment across specialized algorithm vendors. The vendor base concentrates among German, Japanese, and US-based component integrators with established OEM validation relationships. Three archetypes dominate: sensor fusion hardware specialists, predictive algorithm developers, and full-stack platform integrators. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as suppliers race to meet compressed NHTSA compliance timelines.
Within the full-stack platform integrator tier, Continental AG and Robert Bosch GmbH occupy positions exemplifying the convergence of sensor hardware scale with software monetization capabilities. Denso Corporation anchors the Japanese manufacturing archetype with production corridor concentration across North American and Asian supply chains. These three entities represent differentiated pathways for capturing recurring revenue from over-the-air update channels while maintaining safety-critical hardware certification advantages.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Robert Bosch GmbH |
| Autoliv Inc. |
| Aptiv PLC |
| ZF Friedrichshafen AG |
| Magna International Inc. |
| Hyundai Mobis |
| Valeo S.A. |
| Others |
Value Chain & Pricing Dynamics
EU AI Act high-risk system classifications gate qualified supply tiers and premium-tier pricing access for autonomous decision modules, forcing tier-one suppliers to absorb conformity assessment costs while OEMs reserve preferred vendor status for certified architectures. German and Japanese automakers now pay certification premiums for sensor fusion hardware that satisfies algorithmic audit trail mandates.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for LiDAR and radar modules, compressing margins for established suppliers. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-compliant systems from NHTSA-certified alternatives and uncertified economy tiers. Price differentiation stems from ISO 26262 functional safety grade and volume scale commitments. Pricing pressure stems from semiconductor supply concentration in East Asian foundries. Fleet operators show highest price sensitivity; German premium OEMs show lowest.
Supply Chain Analysis
India's automotive PLI scheme domestic-content mandates are reshaping sourcing patterns for advanced driver assistance system components. Manufacturing concentrates in Germany, Japan, and China. Supply chains draw from silicon wafers, precision optics, and rare earth magnet inputs. Single-source vulnerability runs through Taiwan-based semiconductor fabrication. Distribution runs through tier-one integrators to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vehicle intelligence systems constitute a late-cycle quality story as commercial fleet operators shift procurement criteria toward uptime-guaranteed predictive maintenance platforms over hardware-centric specifications.
For Market Incumbents: Anticipate margin compression from edge computing hardware substitution threatening distributed sensor processing nodes. Lock in backward integration into LiDAR optics fabrication to defend component cost volatility exposure. Accelerate ISO 26262 certification investments to exploit functional safety engineer scarcity constraining rival scaling capacity. For New Entrants and Emerging Players: Capture predictive maintenance software subscriptions in North American logistics corridors where fleet operators bypass OEM intermediaries. Target India's automotive PLI scheme corridors for sensor module assembly localization. Lead with direct-to-fleet go-to-market models unbundled from vehicle acquisition channels. For Investors and Strategic Acquirers: Roll-up economics work for specialized predictive algorithm developers because fleet operator channel disintermediation fragments vendor relationships across verticals. Five-to-ten-year viability hinges on software-defined vehicle platform integration depth. Watch NHTSA automatic emergency braking mandate acceleration as inflection indicator for tier-one supplier consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Algorithmic audit trail capabilities unlock preferred supplier status with Stuttgart-based OEMs. |
| India PLI Localization | Tamil Nadu manufacturing corridors attract tier-one sensor module assembly for cost-competitive export supply. |
| Predictive Maintenance Platform Launch | Direct fleet operator subscriptions bypass OEM intermediaries in North American logistics verticals. |
| Edge AI Chip Partnership | Onboard inference engine integration enables 5G-V2X data service revenue streams with telecom operators. |
| Over-the-Air Update Infrastructure | Software-defined feature subscriptions convert hardware sales into recurring revenue from German automaker platforms. |
Study Parameters
Coverage spans Germany, the United States, Japan, China, and India, with primary inputs from each automotive production corridor. Primary interviews with OEM platform engineers, tier-one supplier procurement leads, fleet operations managers, and aftermarket distributors combined with secondary validation from vehicle production databases, NHTSA regulatory filings, EU AI Act implementation guidance, and METI safety validation standards. Bottom-up segment modeling triangulated against top-down macroeconomic drivers.
Rate-of-change decomposition across the analysis window separates volume expansion from value-per-unit shifts. Segmentation dimensions modeled include technology layer, application maturity tier, component margin structure, and end-user channel authority. CAGRs derived from regression analysis against regulatory mandate timelines and OEM platform launch cycles. Forecast inputs incorporate sensor fusion silicon cost curves and predictive maintenance software penetration rates.
Regulatory mandate acceleration, semiconductor supply disruption, and fleet operator procurement channel shifts are the dominant revision risks. Forecasts reflect assumptions on NHTSA compliance timeline adherence and EU AI Act conformity assessment throughput capacity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
Middle East and Africa ADAS Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
Self-Driving Cars and Trucks Market
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Luxury Autonomous Vehicle Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
Autonomous Taxi Market
Autonomous Vehicles
Automotive Lidar Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Self-Balancing Mobility Market
Autonomous Vehicles
Europe ADAS Market