
 Europe Stevedoring and Marine Cargo Handling Market | 2026-2036
Europe Stevedoring and Marine Cargo Handling Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Stevedoring and Marine Cargo Handling Market Foresight
The EU Green Deal is recalibrating berth-side power requirements across North Sea ports. Euroports leverages its Belgian hub network to sustain cold chain throughput. Associated British Ports anchors UK-Ireland ro-ro volumes. Peel Ports Group competes on Liverpool's automated crane density.
Europe stevedoring and marine cargo handling encompasses the loading, unloading, stowage, and transfer of vessel-borne freight using shore-based equipment and labor, typically operating within vessel turnaround windows of 12–48 hours for container vessels and 3–7 days for bulk carriers. Its primary purpose is minimizing port stay costs while maintaining cargo integrity across temperature-sensitive, hazardous, and oversized freight categories. Container handling leads service type revenue due to standardized TEU economics and transshipment density at Antwerp and Rotterdam. Automated systems within the technology dimension attract capital fastest as labor costs and berth optimization pressures intensify. Bulk cargo handling remains structurally mature with compressed margins outside grain and mineral specialization.
The European Maritime Safety Agency enforces sulfur emission controls that reshape fuel bunkering and shore power investment timelines. The EU F-Gas Regulation constrains refrigerated container reefer unit specifications, forcing equipment fleet refresh cycles. Port state control regimes under Paris MoU inspection standards filter market access for non-compliant operators. Stakeholders must weigh automation capex against labor flexibility as the Green Deal implementation timeline tightens.
Market Dynamics
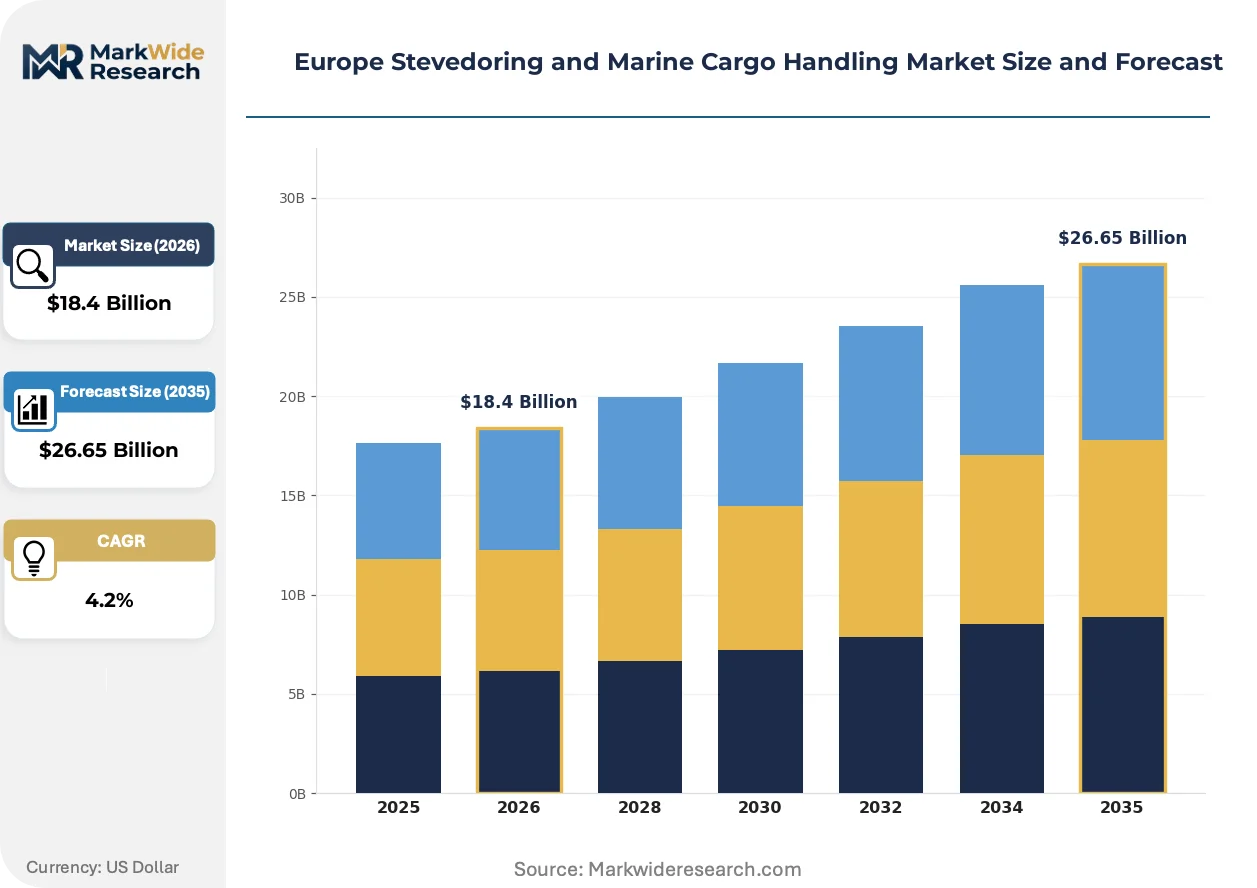
The EU Green Deal is forcing a wholesale recalibration of berth-side power infrastructure across North Sea and Baltic ports. Shore power mandates, sulfur emission controls under the European Maritime Safety Agency, and cold chain integrity requirements are compressing vessel turnaround windows while demanding capital deployment in electrification and automation.
Growth Catalysts
- EU Green Deal shore power mandates:The regulation requires vessels at berth to connect to onshore electricity, driving port electrification capex and creating service demand for installation and maintenance of high-voltage shore connection systems.
- Antwerp-Rotterdam transshipment density:Container volumes concentrate in the Netherlands-Belgium corridor, generating economies of scale in stevedoring labor pools and equipment utilization that attract feeder vessel networks.
- Cold chain pharmaceutical logistics:Temperature-sensitive biologics and vaccine distribution require specialized reefer handling, expanding demand for monitored stowage and rapid vessel-to-warehouse transfer protocols.
Market Restraints
- High-voltage grid infrastructure gaps:Many secondary ports lack sufficient grid capacity to support megawatt-scale shore power, limiting compliance options and forcing reliance on expensive battery-buffered solutions.
- Skilled crane operator scarcity:Automation deployment outpaces workforce retraining, creating bottlenecks in hybrid operations where human oversight remains mandatory for non-standardized cargo.
- EU F-Gas Regulation equipment constraints:Refrigerant phase-down schedules force premature reefer fleet replacement, straining capital budgets and compressing margins on temperature-controlled handling contracts.
Strategic Opportunities
- Baltic port electrification lag:Polish and Lithuanian terminals remain underinvested in shore power relative to North Sea peers, offering first-mover positioning as EU Green Deal enforcement tightens.
- Automated guided vehicle convergence:Integration of AGV fleets with terminal operating systems enables continuous cargo flow without human tractor drivers, reducing labor cost exposure in high-wage jurisdictions.
- Paris MoU inspection data monetization:Compliance analytics derived from port state control regimes can be packaged as risk-assessment services for cargo insurers and vessel operators.
Industry Challenges
- Legacy terminal operating system integration:Proprietary software architectures from equipment manufacturers resist interoperability with third-party automation layers, delaying unified fleet management.
- Certification timeline compression:EU Machinery Directive conformity assessments for automated crane systems now require extended safety validation cycles that extend deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Stevedoring and Marine Cargo Handling Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $26.65 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Container Handling, Bulk Cargo Handling, Breakbulk Handling, Ro-Ro Handling Client Type: Shipping Lines, Freight Forwarders, Port Authorities, Logistics Companies Technology: Automated Systems, Manual Operations, Hybrid Systems, Tracking Software Equipment Type: Cranes, Forklifts, Conveyors, Stackers |
| Companies Covered | Euroports, Bolloré Logistics, PD Ports, Katoen Natie, Noatum Logistics, Associated British Ports, HES International, Wallenius Wilhelmsen, Peel Ports Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Stevedoring and Marine Cargo Handling Market Shifts & Advancements
Automation and electrification are converging to redefine cargo velocity metrics and labor economics across European container and bulk terminals. Three distinct vectors are reshaping competitive positioning: equipment intelligence, regulatory compliance architecture, and buyer-side contracting evolution.
Remote-controlled ship-to-shore cranes equipped with camera-based container positioning are automating the final meter of hoist operations previously requiring manual tagline handling. Major transshipment hubs in Rotterdam and Hamburg are deploying these systems to compress single-lift cycle times below ninety seconds. The technology is automating labor out of the highest-risk berth-side functions while maintaining human oversight for exception handling.
The EU F-Gas Regulation is accelerating refrigerant transition timelines for reefer containers, forcing terminal operators to maintain dual-fleet capability during the phase-down period. Equipment lessors face stranded asset risk in older reefer gensets that cannot be retrofitted to compliant refrigerants. Pharmaceutical shippers operating under Good Distribution Practice guidelines are most affected, demanding documented cold chain continuity across the equipment transition.
Shipping lines are consolidating procurement of stevedoring services under multi-terminal framework agreements that bundle cargo handling, storage, and intermodal transfer. This displaces the traditional port-by-port contracting model and concentrates negotiating leverage with carriers operating 18,000+ TEU vessels. The shift is most visible in the Mediterranean, where MSC and CMA CGM have established captive terminal networks that internalize handling economics.
Europe Stevedoring and Marine Cargo Handling Market Segmentation
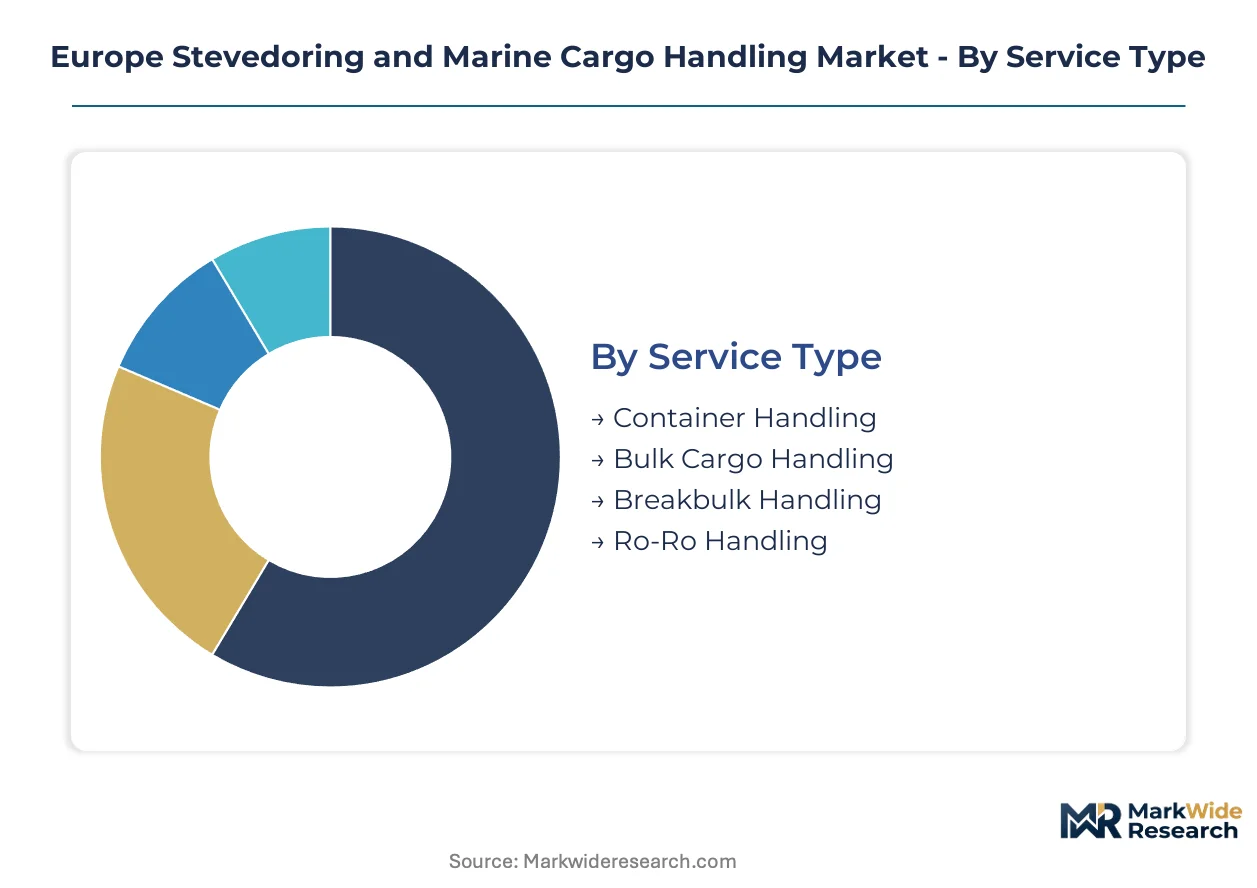
Stevedoring economics diverge sharply across cargo formats and client relationships, with automation intensity and contract duration varying by segment. Understanding these fault lines clarifies where capital deployment yields margin expansion versus commodity exposure.
Service Type:
Buyers in this category separate by cargo velocity requirements and equipment specialization needs, with containerized freight demanding standardized TEU economics while bulk flows tolerate longer vessel stays.
- Container Handling:Standardized lift operations using ship-to-shore cranes and rubber-tired gantries dominate revenue. Rotterdam and Antwerp transshipment density drives feeder network concentration, with EU Green Deal shore power mandates compressing turnaround windows and forcing electrification capex.
- Bulk Cargo Handling:Grain, mineral, and liquid bulk flows utilize grab cranes and conveyor systems with lower labor intensity. Specialized terminals in Hamburg and Gdansk capture margin through dedicated storage infrastructure, though oversupply outside grain corridors squeezes pricing.
- Breakbulk Handling:Project cargo and heavy lift operations require mobile harbor cranes and custom stowage planning.
- Ro-Ro Handling:Ferry and vehicle carrier operations depend on ramp infrastructure and lashings labor pools concentrated in UK-Ireland corridors.
Volume sits with Container Handling; growth tilts toward Ro-Ro Handling as automotive electrification reshapes European vehicle logistics.
Client Type:
Contract structures in this category range from multi-terminal framework agreements to single-berth spot arrangements, with negotiating leverage concentrated among vessel operators controlling 18,000+ TEU fleets.
- Shipping Lines:MSC and CMA CGM have consolidated procurement under captive terminal networks, internalizing handling economics and displacing port-by-port contracting. Mediterranean hub consolidation accelerates this shift.
- Freight Forwarders:NVOCCs and integrators purchase stevedoring as bundled intermodal services, prioritizing cargo visibility and dwell time guarantees over per-lift rates.
- Port Authorities:Municipal and regional port landlords negotiate concession terms and labor allocation frameworks.
- Logistics Companies:3PLs and cold chain specialists contract for value-added services including customs staging and reefer monitoring.
Revenue concentrates with Shipping Lines; margin expansion favors Logistics Companies as pharmaceutical cold chain requirements deepen service bundling.
Technology:
Capital intensity and labor substitution potential differentiate technology tiers, with automated systems attracting investment fastest where wage structures and berth scarcity coincide.
- Automated Systems:Remote-controlled ship-to-shore cranes with camera-based positioning compress lift cycles below ninety seconds. Rotterdam and Hamburg deployment is reshaping labor economics while EU Machinery Directive conformity assessments extend safety validation timelines.
- Manual Operations:Conventional crane and tractor operations persist at secondary ports and in breakbulk niches requiring human judgment for non-standardized cargo.
- Hybrid Systems:Semi-automated yards with human-supervised AGV fleets bridge capital constraints and labor scarcity.
- Tracking Software:Terminal operating systems and cargo visibility platforms enable yard optimization and exception management.
Deployment concentrates in Automated Systems; adoption velocity peaks in Hybrid Systems as Polish and Baltic terminals phase modernization.
Equipment Type:
Asset specificity and utilization rates determine equipment investment returns, with crane density and automation compatibility driving terminal competitiveness.
- Cranes:Ship-to-shore, mobile harbor, and rubber-tired gantry cranes represent the largest capital commitment. Peel Ports Group competes on Liverpool's automated crane density, while EU F-Gas Regulation refrigerant constraints force parallel fleet maintenance during phase-down periods.
- Forklifts:Reach stackers and empty handlers manage yard logistics and reefer box positioning.
- Conveyors:Continuous bulk handling systems serve grain and mineral terminals with high throughput, low labor requirements.
- Stackers:Automated stacking cranes and straddle carriers optimize yard density in high-volume container terminals.
Capital deployment concentrates in Cranes; electrification urgency tilts toward Stackers as battery-buffered solutions address grid capacity gaps at secondary ports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam and Antwerp anchor the Netherlands-Belgium corridor where transshipment density concentrates European container throughput. This corridor generates economies of scale in stevedoring labor pools and equipment utilization that attract feeder vessel networks across the North Sea and Baltic.
Netherlands
Rotterdam's Maasvlakte terminals handle the highest container volumes in Europe, driving demand for automated crane systems and AGV fleets. The EU Green Deal mandates shore power installation at all major berths by 2030, forcing port electrification capex. The Rotterdam-Antwerp pipeline sustains cold chain pharmaceutical logistics through specialized reefer handling facilities.
Belgium
Antwerp's Deurganck dock competes directly with Rotterdam for transshipment cargo, with Euroports leveraging its Belgian hub network for temperature-controlled throughput. REACH compliance requirements shape chemical cargo handling protocols at the port's petrochemical cluster. The Waasland harbor area hosts specialized breakbulk terminals serving project cargo flows.
Germany
Hamburg's Container Terminal Altenwerder deploys remote-controlled ship-to-shore cranes to compress lift cycles below ninety seconds. The EU Machinery Directive extends safety validation timelines for automated systems, delaying unified fleet management. The JadeWeserPort in Wilhelmshaven handles ultra-large container vessels with deep-water access unmatched by North Sea competitors.
United Kingdom
Associated British Ports anchors UK-Ireland ro-ro volumes through Southampton and Hull terminals. Peel Ports Group competes on Liverpool's automated crane density against London Gateway's deep-water capabilities. The UK's departure from EU customs frameworks forces reinvestment in border inspection infrastructure at Dover and Felixstowe.
Poland
Gdansk's DCT terminal captures Baltic container growth as Polish manufacturing exports expand. Secondary Polish ports remain underinvested in shore power relative to North Sea peers, offering first-mover positioning as EU Green Deal enforcement tightens. The port's grain terminals specialize in Black Sea agricultural transit cargo.
Europe Stevedoring and Marine Cargo Handling Market Competitive Landscape
Premium-margin players sit above commodity-margin players across automation intensity and cold chain specialization. The market structures around three tiers: integrated port operators with captive terminal networks, specialized logistics providers bundling stevedoring with value-added services, and regional port authorities outsourcing labor management. Consolidation concentrates negotiating leverage with carriers operating 18,000+ TEU vessels. Competitive moves center on multi-terminal framework agreements and electrification capex partnerships with grid operators.
Among Belgian and Dutch integrated operators, Euroports and Katoen Natie exemplify the cold chain specialization archetype. Associated British Ports anchors the UK-Ireland corridor position. These three occupy distinct geographic footprints while competing for pharmaceutical logistics contracts requiring temperature integrity documentation.
| Leading Market Players |
|---|
| Euroports |
| Bolloré Logistics |
| PD Ports |
| Katoen Natie |
| Noatum Logistics |
| Associated British Ports |
| HES International |
| Wallenius Wilhelmsen |
| Peel Ports Group |
| Others |
Supply & Pricing Matrix
Remote-controlled crane deployment across Rotterdam and Hamburg terminals compresses vessel turnaround windows below ninety seconds, simultaneously raising capital intensity and concentrating pricing power among operators with electrified berth infrastructure. The EU Green Deal shore power mandates force parallel investment in grid-connected systems, creating a cost bifurcation between compliant and non-compliant terminals.
Pricing Analysis
Throughput-based pricing anchors container handling contracts, with per-lift rates scaling to guaranteed TEU volumes across multi-terminal framework agreements. Price differentiation separates automated terminals with sub-ninety-second lift cycles from manual operations, while pharmaceutical cold chain handling commands premium margins for temperature-integrity documentation. Cost compression in bulk cargo handling intensifies as grain corridor oversupply squeezes spot rates. Freight forwarders purchasing bundled intermodal services exhibit lowest price sensitivity; regional port authorities negotiating labor allocation frameworks show highest sensitivity to per-lift benchmarking.
Supply Chain Analysis
CE marking and EU Machinery Directive conformity assessments gate equipment procurement from Chinese and South Korean crane manufacturers, extending safety validation timelines for automated systems. Critical components including high-voltage shore connection systems and camera-based container positioning sensors draw from German and Japanese suppliers. Single-source vulnerability concentrates in specialized reefer gensets facing EU F-Gas Regulation phase-down constraints. Distribution runs through equipment lessors and terminal operators with captive maintenance capabilities, bypassing traditional distributor networks for direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shore power infrastructure deployment across North Sea and Baltic ports lags EU Green Deal enforcement timelines, creating a capacity bottleneck that sustains pricing premiums for compliant terminals. Grid connection queues and high-voltage installation backlogs prop contract rates.
For Market Incumbents: Lock in multi-terminal framework agreements with MSC and CMA CGM before captive network consolidation completes. Defend margin position by accelerating AGV fleet integration with terminal operating systems to reduce labor cost exposure. Prioritize backward integration into shore power maintenance capabilities as electrification capex cycles intensify. For New Entrants and Emerging Players: EU Green Deal enforcement in Poland and Lithuanian secondary ports opens a window for first-mover shore power installation services. Target Baltic terminals with battery-buffered connection systems where grid capacity gaps persist. Enter through electrification partnership structures with regional grid operators rather than competing on lift economics. For Investors and Strategic Acquirers: Exit pathways concentrate in cold chain-specialized terminal operators with pharmaceutical logistics certifications. Long-term viability hinges on automation deployment velocity and Green Deal compliance positioning. Watch for Paris MoU inspection data monetization services as an inflection signal for risk-assessment platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Shore Power Infrastructure Deployment | EU Green Deal mandates at Rotterdam and Antwerp terminals create compliance-driven service demand. |
| AGV Fleet Integration | Terminal operating system convergence at Hamburg and Liverpool reduces human tractor driver dependence. |
| Cold Chain Certification Investment | Good Distribution Practice compliance unlocks pharmaceutical logistics contracts with temperature documentation requirements. |
| Reefer Fleet Refresh Partnership | EU F-Gas Regulation phase-down forces dual-fleet capability during refrigerant transition periods. |
| Multi-Terminal Framework Agreement | Bundled procurement consolidation with 18,000+ TEU carriers displaces port-by-port contracting models. |
Research Methodology
Independent corroboration across terminal operating data, port authority concession filings, and shipping line procurement disclosures underwrites the qualitative findings. Primary interviews with terminal operations directors, port authority planning officers, crane fleet procurement managers, and pharmaceutical logistics specialists combined with secondary validation from EU Maritime Safety Agency enforcement records, Paris MoU inspection databases, and customs trade flow data. Bottom-up equipment deployment counts and top-down revenue estimates triangulate market sizing.
Comparable-period anchoring to historical throughput and electrification capex cycles calibrated the projection horizon across service type, client relationship structure, technology tier, and equipment category dimensions. CAGRs derived from regression analysis against vessel call frequency and TEU volume trajectories incorporate EU Green Deal implementation pace and cold chain pharmaceutical shipment growth as terminal-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for automated crane systems with extended EU Machinery Directive validation cycles would alter the outlook. Forecasts reflect assumptions on grid infrastructure buildout timing and refrigerant transition schedules. A model refresh is warranted upon material change in EU Green Deal enforcement intensity or shore power mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Latin America Offshore Support Vessels Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Middle East Offshore Support Vessels Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Ship Stabilizers Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
Marine Steering Gear Systems Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Very Large Gas Carrier Market
Maritime Equipment
Reefer Container Market
Maritime Equipment
Ship-To-Shore (STS) Container Cranes Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
Drill Ships Market