
 Golf Cart Market | 2026-2036
Golf Cart Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Cart Market Analysis
Modular battery-pack configurations and subscription-style fleet-management bundles are broadening buyer choice across municipal, hospitality, and residential segments. Club Car leverages vertical integration into lithium-ion powertrain assembly to sustain margin control. Yamaha Golf-Car Company anchors its position through manufacturing scale across Asian and North American plants. Textron Inc. competes via brand strength in the utility-cart sub-category.
A golf cart is a low-speed electric or gasoline-powered vehicle, typically rated under 25 mph, designed for short-distance transport across groomed terrain, gated communities, and commercial campuses; modern units integrate AC motor drives, regenerative braking, and CAN-bus diagnostics for fleet telemetry. Electric cart configurations now dominate procurement decisions across golf courses and residential communities, while lithium-ion battery types command the fastest-growing margin pool as lead-acid systems mature into replacement-cycle economics. Utility cart applications in industrial facilities represent a concentrated but stable demand segment where payload capacity and all-terrain specifications differentiate supplier offerings.
The EPA tailpipe standards and NHTSA low-speed vehicle classifications shape gasoline-cart compliance costs and street-legal access in the United States, while OSHA workplace-transport rules influence industrial-facility procurement specifications for utility variants. ISO 6469 electric-vehicle safety standards and IEC battery-testing protocols govern lithium-ion pack certification for international suppliers. Stakeholders must monitor evolving municipal ordinances that reclassify golf carts for on-road neighborhood use, as these local regulatory shifts will determine addressable market expansion faster than product innovation cycles.
Market Dynamics
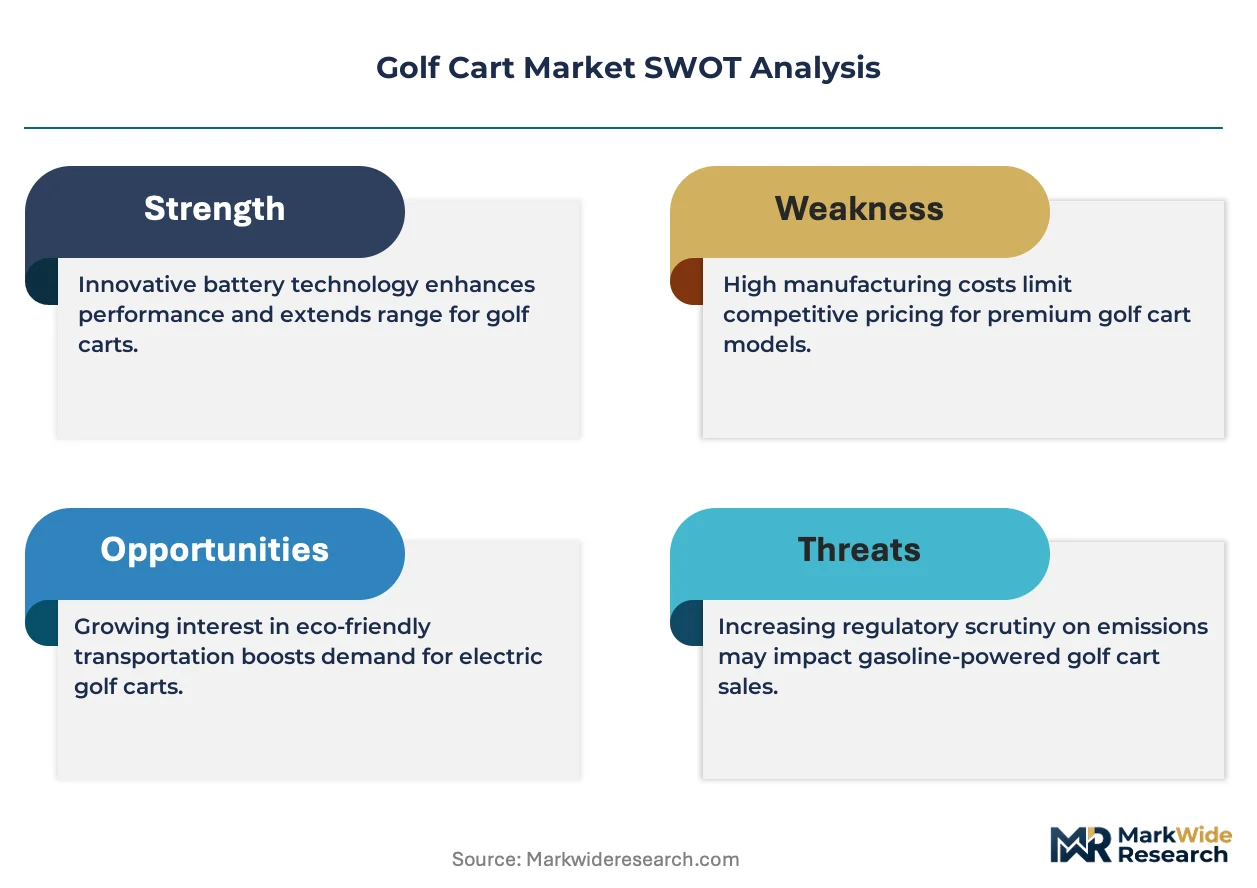
Lithium-ion battery chemistry migration is compressing replacement cycles and rewiring supplier economics across golf course, residential, and utility fleet segments. This single technology inflection is redistributing margin pools from aftermarket parts toward integrated powertrain vendors.
Growth Catalysts
- Sun Belt Retirement Clustering:Master-planned communities in Arizona, Florida, and Texas are embedding golf carts into municipal transport codes. NHTSA low-speed vehicle classifications enable street-legal access in these jurisdictions.
- OSHA Industrial Utility Mandates:Workplace-transport rules in manufacturing campuses are specifying electric utility carts for indoor emissions compliance. This pulls demand from lead-acid toward lithium configurations.
- Regenerative Braking Maturation:AC motor drives with energy recovery are extending range per charge. Golf course superintendents are specifying these systems to reduce midday charging interruptions.
Market Restraints
- Lithium Raw Material Concentration:Cathode active material supply concentrates in Chinese processing facilities. This creates input cost volatility independent of finished cart demand.
- Lead-Acid Replacement Economics:Mature installed bases in municipal fleets delay full-fleet turnover. Budget cycles favor single-unit replacement over platform upgrades.
- Gasoline Cart Regulatory Friction:EPA tailpipe standards are elevating compliance costs for internal-combustion units. Small-engine certification timelines stretch product development schedules.
Strategic Opportunities
- India Resort Hospitality Expansion:Heritage golf developments in Rajasthan and Karnataka are specifying electric shuttle fleets. BIS electric-vehicle safety standards provide a certification pathway for international suppliers.
- Subscription Fleet Management:Telemetry-enabled CAN-bus diagnostics allow usage-based billing models. This unbundles capital expenditure for municipal purchasers.
- Solar-Canopy Integration:Photovoltaic roof panels paired with lithium packs enable off-grid charging. Island resorts in the Caribbean are piloting these configurations.
Industry Challenges
- Battery Pack Thermal Management Expertise:OEM engineering teams lack IEC 62660 cell-testing protocol fluency. Certification delays extend product launch timelines.
- Legacy Fleet CAN-Bus Fragmentation:Proprietary diagnostic protocols from prior decades resist standardization. Telematics integration requires custom gateway hardware per vintage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Cart Market |
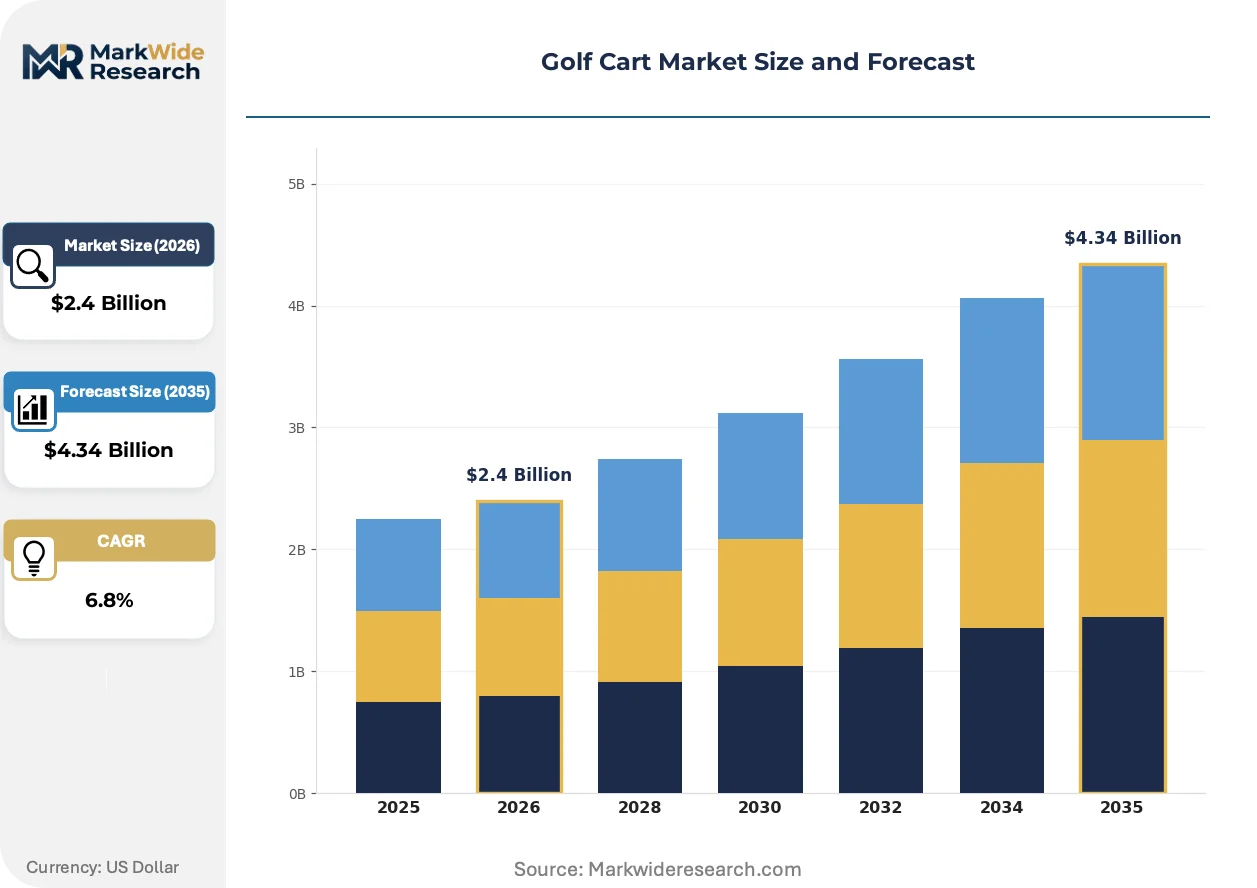
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Cart, Gasoline Cart, Utility Cart, Personal Transporter Application: Golf Courses, Residential Communities, Industrial Facilities, Recreational Events End User: Golf Players, Facility Managers, Event Organizers, Tourists Battery Type: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Others |
| Companies Covered | Club Car, Yamaha Golf-Car Company, Textron Inc., E-Z-GO, Suzhou Eagle Electric Vehicle Manufacturing Co., Ltd., Marshell Green Power, Polaris Inc., Columbia Vehicle Group Inc., Dongguan Excar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Cart Market Emerging Trajectories
Electrification is rewriting product specifications faster than buyer procurement cycles can absorb. Three distinct vectors are compressing traditional competitive advantages.
Lithium iron phosphate cell chemistry is consolidating as the dominant battery architecture for golf and utility carts. Resort fleet managers are specifying these packs for cycle-life predictability. The technology is consolidating supplier margins toward cell manufacturers and away from downstream assemblers.
REACH substance restrictions in the European Union are phasing out specific electrolyte additives and flame-retardant materials in battery construction. Formulation reformulation is elevating R&D intensity for exporters serving EU member states. German and French distributors are demanding full material disclosure documentation ahead of procurement decisions.
Buyer committees in municipal parks departments are unbundling vehicle purchase from service contracts. Third-party maintenance providers are capturing aftermarket revenue previously retained by OEM distribution networks. This pattern is most visible in Florida county government RFP structures.
Golf Cart Market Segmentation
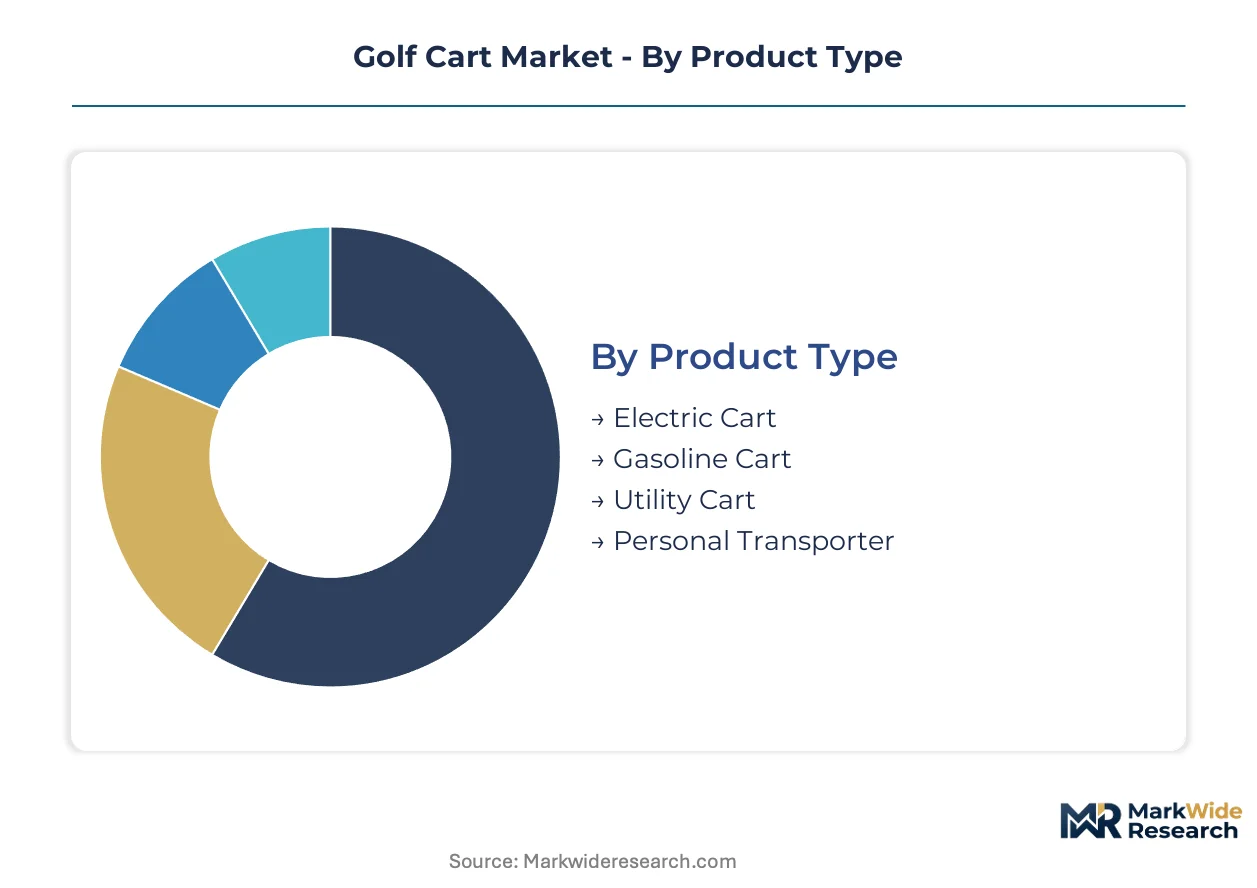
Segmentation in the golf cart market reveals how procurement priorities diverge across powertrain technologies, use environments, and buyer sophistication. Understanding these splits exposes where margin pools concentrate and which specifications command pricing premiums.
Product Type:
Buyers differentiate primarily by total cost of ownership and regulatory compliance requirements rather than upfront sticker price.
- Electric Cart:AC motor drives with regenerative braking dominate new fleet specifications. Demand concentrates in Sun Belt retirement communities where NHTSA low-speed vehicle classifications enable street-legal operation on municipal roads.
- Gasoline Cart:Internal-combustion configurations retain share in remote golf developments lacking charging infrastructure. EPA tailpipe compliance costs are compressing procurement volumes in jurisdictions with stringent small-engine certification timelines.
- Utility Cart:Payload-rated variants with all-terrain specifications serve manufacturing campuses under OSHA indoor emissions mandates.
- Personal Transporter:Compact single-rider units target resort hospitality for guest mobility across expansive property footprints.
Volume sits with Electric Cart; growth tilts toward Utility Cart.
Application:
End-use environments dictate durability specifications, duty-cycle intensity, and fleet-management complexity.
- Golf Courses:Traditional 18-hole and 9-hole facilities specify fleet-scale procurement with CAN-bus telemetry for superintendent oversight. Arizona and Florida course operators are mandating lithium-ion configurations to eliminate midday charging interruptions.
- Residential Communities:Master-planned developments in Texas embed carts into municipal transport codes as primary neighborhood vehicles.
- Industrial Facilities:Manufacturing campuses specify electric utility variants for indoor OSHA compliance.
- Recreational Events:Temporary deployment models favor rental-fleet economics over ownership for festival and sporting event logistics.
Procurement scale peaks at Golf Courses; expansion accelerates fastest in Residential Communities.
End User:
Decision-making authority varies sharply between individual purchasers and institutional procurement committees.
- Golf Players:Individual enthusiasts prioritize ride comfort and bag-storage capacity in private ownership decisions.
- Facility Managers:Superintendents and campus operators control fleet-scale purchasing with total-cost-of-ownership analytics.
- Event Organizers:Rental-dependent buyers emphasize rapid deployment flexibility and minimal maintenance overhead.
- Tourists:End-consumers in resort environments drive demand for passenger-capacity configurations through usage patterns rather than direct purchasing.
Facility Managers command the largest transaction sizes; Tourists exert indirect influence through hospitality operator specifications.
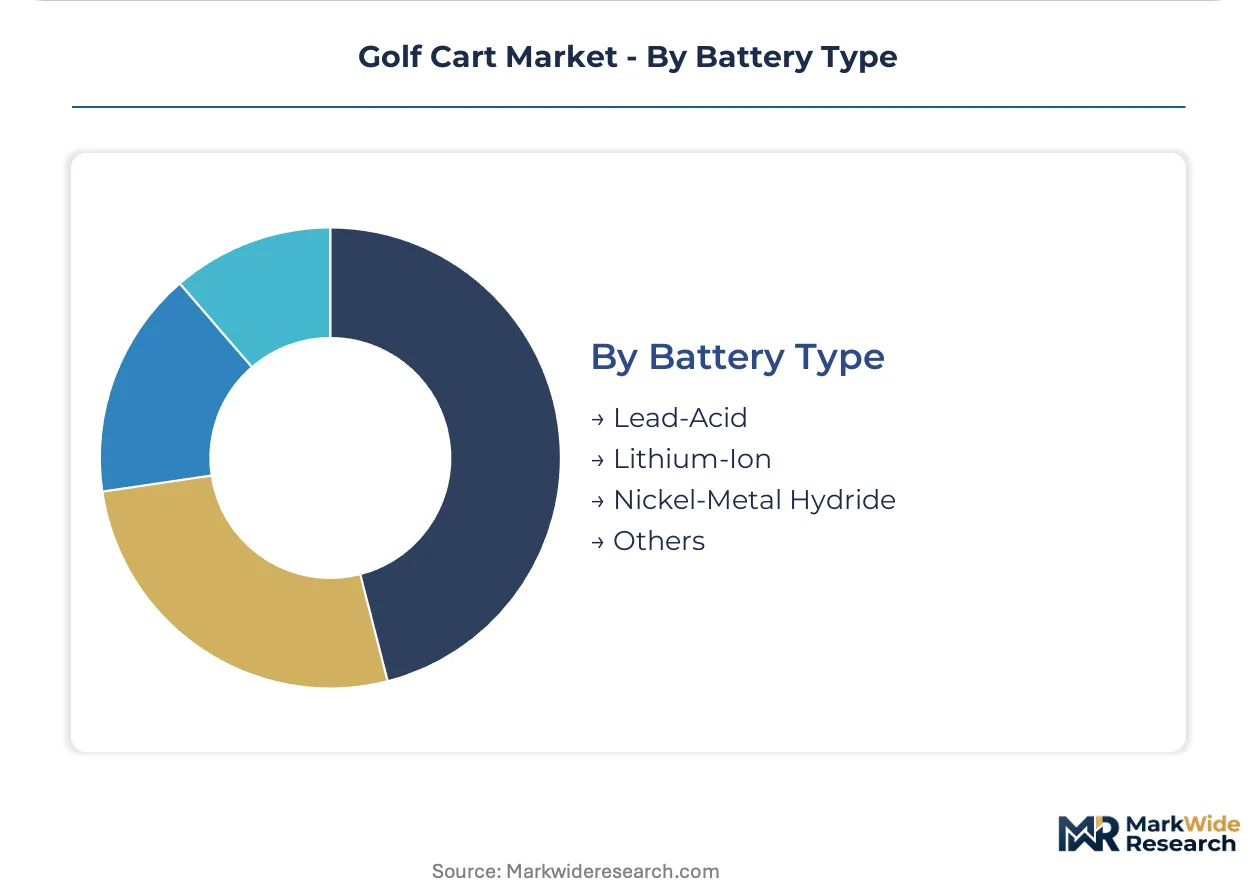
Battery Type:
Chemistry selection determines lifecycle economics, thermal management requirements, and supply chain exposure.
- Lithium-Ion:Lithium iron phosphate cell chemistry is consolidating as the dominant architecture for cycle-life predictability. Cathode active material processing concentration in Chinese facilities creates input cost volatility independent of finished cart demand.
- Lead-Acid:Mature installed bases in municipal fleets delay full turnover as budget cycles favor single-unit replacement over platform upgrades.
- Nickel-Metal Hydride:Intermediate chemistry retains niche presence in legacy fleet retrofits where charging infrastructure cannot support lithium voltage profiles.
- Others:Emerging solid-state and sodium-ion formulations remain pre-commercial for low-speed vehicle duty cycles.
Installed base remains with Lead-Acid; specification momentum belongs to Lithium-Ion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Sun Belt retirement corridors concentrate procurement volumes for street-legal low-speed vehicles. NHTSA classifications enable municipal road access in jurisdictions rewriting transport codes. Tax-advantaged master-planned developments embed fleet-scale specifications into community covenants.
United States
Arizona, Florida, and Texas master-planned communities mandate golf cart access on municipal roads. NHTSA low-speed vehicle classifications preempt state-level restrictions in these jurisdictions. The Villages in Florida operates the nation's largest private cart-accessible road network.
Germany
Industrial facility managers specify electric utility variants under workplace emissions rules. REACH substance restrictions phase out specific battery electrolyte additives for EU-bound exports. Bavarian manufacturing campuses pilot telemetry-enabled fleet management systems.
China
Cathode active material processing concentrates in Jiangsu and Hunan provinces. GB standards for electric vehicle safety govern low-speed vehicle certification pathways. Suzhou industrial parks host vertically integrated lithium-ion pack assembly operations.
India
Rajasthan and Karnataka heritage resorts specify electric shuttle fleets for guest mobility. BIS electric-vehicle safety standards provide certification pathways for international suppliers. Bangalore technology parks trial solar-canopy charging configurations.
Japan
Resort hospitality operators in Okinawa and Hokkaido deploy compact personal transporters. METI clean energy directives accelerate lithium-ion procurement in island municipalities. Nagoya manufacturing clusters supply precision motor-drive components.
Golf Cart Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across powertrain and utility segments. The market structure tilts toward consolidation at the premium tier while fragmentation persists in regional electric vehicle assembly. Two strategic archetypes dominate: vertically integrated powertrain manufacturers controlling lithium-ion supply chains, and modular assemblers sourcing battery packs from third-party vendors. Competitive moves center on backward integration into cell manufacturing and geographic expansion through distributor network acquisition.
Among North American-based manufacturers, Club Car and E-Z-GO exemplify the diversified conglomerate archetype with captive supply chain control. Suzhou Eagle Electric Vehicle Manufacturing Co., Ltd. represents the scale-driven Chinese specialist tier. Yamaha Golf-Car Company anchors the Asian multinational position through manufacturing footprint across multiple continents.
| Leading Market Players |
|---|
| Club Car |
| Yamaha Golf-Car Company |
| Textron Inc. |
| E-Z-GO |
| Suzhou Eagle Electric Vehicle Manufacturing Co., Ltd. |
| Marshell Green Power |
| Polaris Inc. |
| Columbia Vehicle Group Inc. |
| Dongguan Excar |
| Others |
Supply Flow & Price Mechanics
Municipal fleet procurement committees in Florida and Arizona are mandating lithium-ion configurations with CAN-bus telemetry, forcing suppliers to absorb cell-certification costs and compressing margins on standard lead-acid replacement units. This specification pressure is redistributing pricing power toward integrated powertrain vendors while squeezing modular assemblers dependent on third-party battery sourcing.
Pricing Analysis
Short lead-time premiums dominate transaction economics for fleet-scale orders, with superintendents paying markups for lithium configurations deliverable within compressed installation windows. Three-tier pricing structure across premium, standard, and economy levels separates telemetry-enabled AC motor drives from basic DC configurations and refurbished lead-acid units. Price differentiation hinges on IEC 62660 certification status and aftermarket service bundling. Cost compression in economy tiers is intensifying because municipal budget cycles favor single-unit replacement over platform upgrades. Facility managers exhibit highest price sensitivity; resort hospitality operators show lowest.
Supply Chain Analysis
Domestic-content mandates in Indian BIS certification pathways and proposed EU battery passport requirements are reshaping sourcing decisions for international suppliers serving those jurisdictions. Cathode active material processing concentrates in Chinese Jiangsu and Hunan provinces, with precision motor-drive component manufacturing anchored in Japanese Nagoya clusters and final assembly distributed across Mexican border facilities for North American market access. Raw material dependencies span lithium carbonate, nickel sulfate, and rare-earth permanent magnets. Single-source vulnerability in Chinese cathode processing creates tariff-exposure risk for non-integrated assemblers. Distribution runs through OEM captive networks in premium tiers and independent distributors in replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around powertrain integration capabilities, with lithium-ion chemistry migration forcing pure-play assemblers into acquisition targets or exit.
For Market Incumbents: Anchor market position through backward integration into cell testing protocols and thermal management engineering, closing the capability gap that delays product launches for modular competitors. Capture municipal fleet telemetry data via CAN-bus diagnostics to lock in subscription renewal revenue and defend against third-party maintenance providers eroding aftermarket share. Prioritize certification investment in IEC 62660 protocols as a barrier to emerging Asian entrants lacking testing infrastructure. For New Entrants and Emerging Players: The price-point gap between premium lithium telemetry configurations and economy lead-acid replacements offers white-space entry for mid-tier lithium iron phosphate specialists targeting Texas and Arizona residential community associations with simplified fleet-management bundles. Penetrable geography centers on Indian heritage resort developments in Rajasthan and Karnataka where BIS certification pathways remain uncongested. Go-to-market angle emphasizes solar-canopy integration for Caribbean island resorts seeking off-grid charging independence. For Investors and Strategic Acquirers: The window for entry favors vertically integrated powertrain manufacturers with captive lithium supply agreements and in-house IEC certification capabilities. Long-term viability rests on five-to-ten-year fleet replacement cycles compressing as battery lifecycle economics improve. Acquisition target archetype: regional electric vehicle assemblers with established municipal distributor relationships but lacking backward integration. Signal to watch: municipal ordinance expansions reclassifying golf carts for on-road neighborhood use in Sun Belt jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium iron phosphate cell allocation from Jiangsu processing facilities ahead of competitor procurement cycles. |
| Telemetry Platform Integration | Enables usage-based billing models for Florida municipal fleets through CAN-bus diagnostic standardization. |
| Certification Pathway Investment | Accelerates BIS electric-vehicle safety approval for Rajasthan resort hospitality specifications. |
| Geographic Manufacturing Footprint | Positions final assembly in Mexican border zones to mitigate tariff exposure on Chinese-sourced cathode materials. |
| Aftermarket Service Network Acquisition | Recaptures maintenance revenue from third-party providers penetrating Florida county government RFP structures. |
Methodological Framework
Document review covered EPA tailpipe compliance filings, NHTSA low-speed vehicle classification databases, and IEC battery-testing protocol documentation, complemented by interviews with golf course superintendents, municipal fleet procurement officers, lithium-ion cell manufacturing engineers, and resort hospitality operations directors. Secondary validation drew from OSHA workplace-transport rulemaking records, SEC 10-K disclosures from diversified conglomerate manufacturers, and customs trade data for electric vehicle component flows. Bottom-up unit economics triangulated against top-down market sizing from regional vehicle registration databases.
Segmentation outputs reflect powertrain technology splits, application environment intensity, and buyer procurement sophistication across the projection horizon. The analytical framework modeled electric versus gasoline versus utility cart configurations, lithium-ion versus lead-acid battery chemistry adoption curves, and fleet-scale versus individual ownership decision patterns. CAGRs derived from replacement cycle compression rates and municipal transport code expansion trajectories. Industry-specific inputs included cathode material price volatility indices and NHTSA classification jurisdiction maps.
Inputs from EPA certification timelines and BIS standards development were available through the study window; gaps in proprietary fleet telemetry utilization data introduce uncertainty bands around subscription revenue forecasts. Forecasts reflect assumptions on lithium-ion cost parity achievement and Sun Belt municipal ordinance propagation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
Luxury Yacht Market
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
US Electric UTV and ATV Powertrain Market
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
Electric Golf Cart Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Self Balancing Scooter Market
Recreational Vehicles
Towable Tubes Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market