
 Teardrop Trailer Market | 2026-2036
Teardrop Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Teardrop Trailer Market Insights
Oregon-based fiberglass producers is expanding wet-layup capacity to serve teardrop hull demand across the Pacific Northwest. Timberleaf Trailers leverages its aluminum monocoque construction to command premium positioning in the lightweight segment. nuCamp sustains a vertically integrated assembly campus in northern Indiana that anchors its cost structure. Escapod specializes in welded-steel off-road chassis designs that dominate Utah's backcountry rental fleet.
A teardrop trailer is a streamlined, compact towable recreational vehicle typically measuring four to six feet in width and eight to ten feet in length, constructed with a bonded shell of aluminum, fiberglass, or composite panels over a steel or aluminum frame, designed primarily for sleeping quarters with an exterior galley accessible through a rear hatch. Off-road variants with independent suspension and all-terrain tires are capturing the fastest growth trajectory as overlanding participation rises. The aluminum material segment leads unit volume due to its strength-to-weight ratio and corrosion resistance, while fiberglass commands superior margin pools in the luxury product tier where gel-coat finishes justify price premiums.
The U.S. National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standard 108 for lighting and reflector requirements on trailers under 3,000 pounds, while the Recreational Vehicle Industry Association administers self-certified build standards that shape product liability exposure. State-level departments of transportation impose varying width and brake thresholds that fragment homologation requirements across jurisdictions. Buyers and builders must monitor evolving electrification compatibility as EV tow ratings and charging infrastructure reshape powertrain pairing decisions.
Market Dynamics
The U.S. National Highway Traffic Safety Administration's updated braking and lighting standards for sub-3,500-pound trailers is forcing manufacturers to redesign electrical architectures and upgrade component sourcing, compressing margins for smaller builders while favoring scaled producers with captive engineering resources.
Growth Catalysts
- Overlanding participation surge:Weekend campers and backcountry hobbyists are pulling demand toward off-road variants with independent suspension systems and all-terrain tires.
- Federal Motor Vehicle Safety Standard 108:NHTSA enforcement of lighting and reflector requirements is accelerating compliance investment and raising barriers to informal kit builders.
- Dispersed camping access expansion:Bureau of Land Management territory utilization across the American Southwest is concentrating buyer interest in lightweight, towable units suited to primitive road conditions.
Market Restraints
- Aluminum price volatility:Raw material input swings compress margin predictability for producers dependent on sheet and extrusion supply.
- Fiberglass supply concentration:Wet-layup capacity expansion in the Pacific Northwest has not matched hull demand growth, creating bottleneck risk.
- State brake threshold fragmentation:Varying department of transportation requirements across jurisdictions multiply homologation costs for interstate distribution.
Strategic Opportunities
- EV tow rating compatibility:Electrification infrastructure expansion creates white space for trailers engineered around reduced tongue weights and aerodynamic efficiency.
- Backcountry rental fleet penetration:Utah's guided overlanding operators represent an underdeveloped channel for welded-steel off-road chassis supply.
- Indiana manufacturing cluster proximity:Vertically integrated assembly campuses in the northern Indiana corridor offer logistics cost advantages for Midwest distribution.
Industry Challenges
- Composite lamination skill scarcity:Gel-coat finishing and fiberglass bonding expertise pools are thinning as veteran technicians exit the workforce.
- Self-certified build liability exposure:Recreational Vehicle Industry Association standards create legal ambiguity when product failure occurs in extreme off-road conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Teardrop Trailer Market |
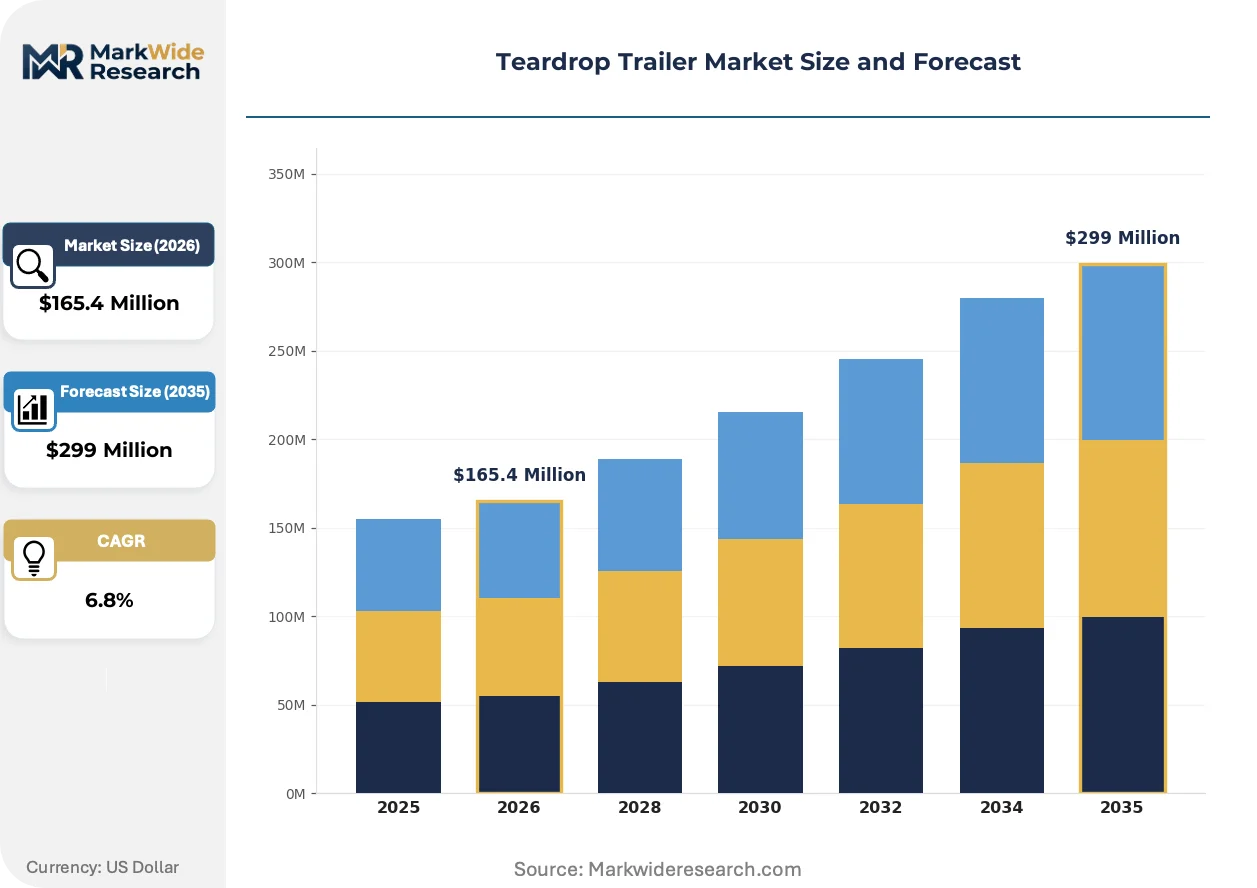
| Market Size in 2026 | $165.4 Million |
| Market Size in 2035 | $299 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Hybrid, Off-road, Luxury Size: Lightweight, Standard, Large, Mini Material: Aluminum, Fiberglass, Wood, Steel End User: Recreational Users, Outdoor Enthusiasts, Rental Companies, Manufacturers |
| Companies Covered | Timberleaf Trailers, nuCamp, Vistabule, Little Guy Trailers, Escapod, Aero Teardrops, Bean Trailer, Camp-Inn, Pin Drop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Teardrop Trailer Market Trends and Innovations
Material substitution and regulatory recalibration are compressing traditional construction methods while electrification compatibility emerges as a design priority. Builders are rethinking chassis architecture and shell bonding to capture shifting buyer expectations.
Composite panel construction with vacuum-infused resin systems is overtaking wet-layup fiberglass in premium tier production. Overlanding hobbyists seeking durability under vibration stress are specifying bonded sandwich cores. This shift is compressing cycle times for hull fabrication while raising capital requirements for mold tooling.
NHTSA enforcement patterns around trailer lighting compliance are tightening vendor qualification standards. Component suppliers must now document photometric testing traceability. Small-scale builders lacking in-house compliance engineering are outsourcing certification to third-party laboratories, adding cost layers.
Rental fleet procurement is displacing individual ownership as the dominant channel for first-time buyer exposure. Utah backcountry operators and Southwest desert guides are aggregating demand for standardized off-road specifications. This concentration is forcing manufacturers to prioritize fleet serviceability and parts commonality over customization flexibility.
Teardrop Trailer Market Segmentation
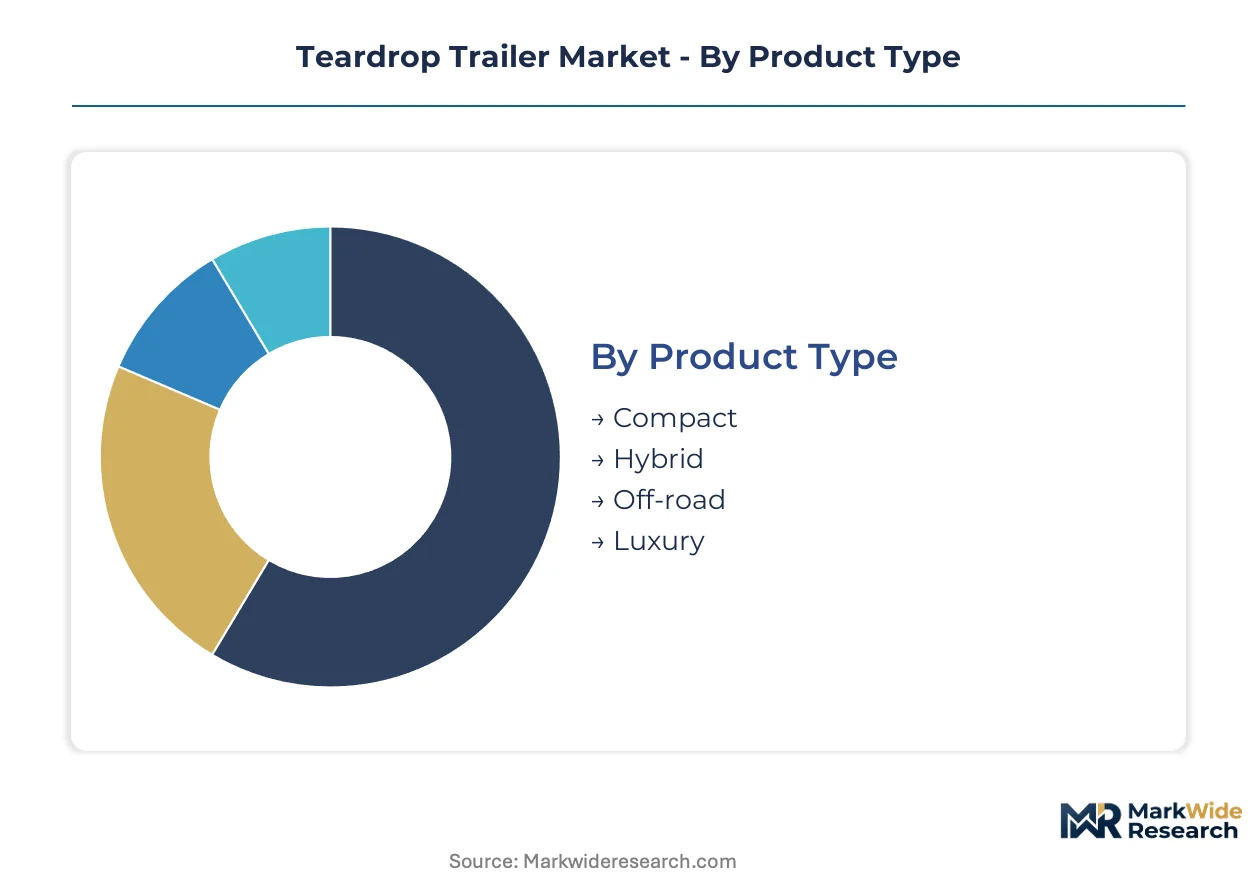
Teardrop trailer buyers sort into sharply different technical and economic profiles. Material selection drives manufacturing cost structure and warranty exposure. Product type determines suspension specification and chassis engineering requirements.
Product Type:
Buyers differentiate primarily by terrain capability and amenity level rather than pure sleeping capacity.
- Off-road:Independent suspension systems and all-terrain tires define this specification. Utah backcountry rental fleets and Southwest desert guides are pulling demand toward welded-steel chassis designs with elevated ground clearance. Overlanding participation is expanding most quickly in this tier.
- Compact:Streamlined profiles measuring four to six feet in width optimize for EV tow ratings and reduced drag coefficients. Weekend campers in dispersed Bureau of Land Management territory favor this format for primitive road access.
- Hybrid:Combines hard-shell sleeping quarters with expandable tent sections for added interior volume.
- Luxury:Gel-coat fiberglass finishes and climate-controlled interiors command premium positioning in the high-end tier.
Compact leads volumes today; off-road is gaining share fastest.
Size:
Weight classification determines brake system requirements and state-level registration thresholds.
- Lightweight:Sub-1,500-pound units bypass auxiliary brake mandates in most jurisdictions. Aluminum monocoque construction from Indiana manufacturers dominates this specification for fuel efficiency and corrosion resistance.
- Standard:Eight to ten foot lengths accommodate two adult sleepers with exterior galley access through rear hatch configurations.
- Mini:Ultra-compact formats under seven feet target motorcycle and small crossover towing.
- Large:Extended chassis variants with standing headroom and wet bath provisions blur category boundaries with conventional travel trailers.
Lightweight captures the broadest buyer base; mini specifications show steepest expansion trajectory among urban apartment dwellers seeking weekend mobility.
Material:
Shell composition dictates lamination labor requirements, mold capital intensity, and field repairability.
- Aluminum:Sheet and extrusion construction delivers superior strength-to-weight ratios for tongue weight reduction. Pacific Northwest producers are expanding wet-layup capacity to serve hull demand, though raw input price volatility compresses margin predictability.
- Fiberglass:Vacuum-infused resin systems with bonded sandwich cores are overtaking wet-layup methods in premium tier production. Gel-coat finishing expertise pools are thinning as veteran technicians exit the workforce.
- Steel:Welded chassis designs dominate Utah rental fleet specifications for vibration durability under extreme off-road stress.
- Wood:Traditional frame construction persists in kit-builder and DIY segments with lowest capital barriers.
Aluminum leads volumes today; fiberglass is climbing the fastest in revenue per unit terms.
End User:
Procurement patterns split between individual ownership and fleet aggregation with diverging serviceability priorities.
- Recreational Users:Individual buyers prioritize customization flexibility and aesthetic differentiation for personal camping use.
- Outdoor Enthusiasts:Overlanding hobbyists specify independent suspension and all-terrain packages for backcountry access.
- Rental Companies:Utah guided overlanding operators and Southwest desert guides are aggregating demand for standardized specifications with parts commonality and rapid turnaround maintenance.
- Manufacturers:OEM chassis suppliers and component vendors serve the upstream production ecosystem.
Recreational users anchor current volumes; rental fleet procurement is displacing individual ownership as the dominant channel for first-time buyer exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where teardrop trailer production concentrates, as compliance cost gaps between jurisdictions drive assembly migration toward states with lighter brake thresholds and dispersed camping access expansion.
United States
Bureau of Land Management territory utilization across the American Southwest concentrates buyer interest in lightweight units suited to primitive roads. The National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standard 108 for sub-3,000-pound trailer lighting requirements. Northern Indiana hosts vertically integrated assembly campuses that anchor cost structures for Midwest distribution networks.
Canada
Weekend campers in British Columbia and Alberta pull demand toward compact formats compatible with smaller tow vehicles. Transport Canada aligns with U.S. lighting standards while maintaining distinct brake threshold triggers that fragment homologation requirements. Quebec-based fabricators serve eastern provinces with aluminum monocoque construction optimized for corrosion resistance in harsh winters.
Germany
Overlanding hobbyists in Bavaria and Baden-Württemberg specify independent suspension systems for Alpine backcountry access. The Kraftfahrt-Bundesamt enforces type-approval standards for trailer braking and lighting that exceed baseline EU requirements. Stuttgart-area engineering clusters supply chassis design expertise to premium-tier European manufacturers.
Australia
Outback tourism operators aggregate demand for off-road variants with welded-steel chassis rated for extreme vibration stress. The Department of Infrastructure and Regional Development administers the Australian Design Rules for trailer compliance. Queensland and Western Australia rental fleets standardize specifications around rapid-turnaround maintenance protocols.
United Kingdom
Urban apartment dwellers in Greater London and the Southeast favor mini specifications under seven feet for small crossover towing. The Driver and Vehicle Standards Agency mandates trailer lighting and braking inspections that raise barriers to informal kit builders. Midlands manufacturing corridors supply aluminum sheet and extrusion inputs to domestic assemblers.
Teardrop Trailer Market Competitive Landscape
Indiana-based producers anchor one tier; Pacific Northwest and Rocky Mountain specialists hold differentiated positions in fiberglass and off-road segments. The vendor base splits between scaled assemblers with captive engineering resources and regional fabricators serving rental fleet concentration. Three archetypes dominate: vertically integrated Midwest manufacturers, aluminum monocoque premium-positioned builders, and welded-steel off-road chassis specialists. Competitive moves center on compliance engineering investment and backcountry rental fleet penetration.
Within the vertically integrated tier, nuCamp occupies a position exemplifying captive supply chain control over assembly campuses. Among Rocky Mountain specialists, Escapod represents the welded-steel off-road chassis archetype serving Utah backcountry rental operators. Timberleaf Trailers anchors the aluminum monocoque premium segment with strength-to-weight optimization. These three companies illustrate how geographic clustering around material inputs and end-use demand shapes competitive positioning.
| Leading Market Players |
|---|
| Timberleaf Trailers |
| nuCamp |
| Vistabule |
| Little Guy Trailers |
| Escapod |
| Aero Teardrops |
| Bean Trailer |
| Camp-Inn |
| Pin Drop |
| Others |
Pricing and Supply Chain Analysis
Utah backcountry rental fleet operators aggregate procurement volume around standardized off-road specifications, anchoring a contract-based pricing structure that rewards parts commonality over customization flexibility. This buyer concentration compresses margin pools for small-scale fabricators while scaling economies favor Indiana-based producers with captive aluminum extrusion supply.
Pricing Analysis
Direct-to-fleet channels bypass traditional dealer markups and compress the margin stack to manufacturer-plus-service-contract terms. Pricing stratifies across premium gel-coat fiberglass, standard aluminum monocoque, and economy-grade welded-steel tiers differentiated by suspension specification and interior finish grade. Cost compression in the economy tier intensifies because raw aluminum input volatility transfers directly to sheet and extrusion pricing. Fleet buyers exhibit highest price sensitivity; individual overlanding hobbyists purchasing for personal use show lowest sensitivity to premium positioning.
Supply Chain Analysis
Direct-to-OEM component channels serve scaled assemblers in northern Indiana while regional fabricators in the Pacific Northwest and Rocky Mountain states rely on distributed supplier networks. Manufacturing gravity centers on the United States for final assembly, with raw aluminum sheet drawn from domestic smelters and fiberglass resin systems imported from Canadian chemical producers. Single-source vulnerability concentrates in gel-coat finishing expertise pools as veteran technicians exit the workforce. Distribution runs through manufacturer-direct fleet contracts and independent dealer networks serving recreational buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The teardrop trailer market compounds steadily as dispersed camping access expansion on Bureau of Land Management territory sustains replacement demand and first-time buyer conversion.
For Market Incumbents: Deploy compliance engineering investment to capture NHTSA Federal Motor Vehicle Safety Standard 108 certification barriers that disadvantage informal kit builders. Escalate captive aluminum extrusion capacity in the Indiana corridor to defend margin position against raw material volatility. Threat substitution from EV tow rating incompatibility demands aerodynamic hull redesign and reduced tongue weight specifications. For New Entrants and Emerging Players: The premium-to-economy price-point gap in off-road chassis specifications offers white-space entry for welded-steel specialists targeting Utah rental fleet procurement. Compact formats optimized for EV tow ratings represent the most penetrable product tier as electrification infrastructure expands. Go-to-market execution should anchor on direct fleet contracting rather than dealer network buildout. For Investors and Strategic Acquirers: Outdoor recreation platform operators are the most active acquirer in this space, seeking manufacturing assets to vertically integrate rental fleet supply. Long-term viability frames around five-to-ten year holding periods as overlanding participation matures from hobbyist niche to mainstream weekend activity. The signal to monitor is EV tow rating standardization across major automotive OEMs, which would inflect demand toward aerodynamic compact specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Federal Compliance Certification | NHTSA FMVSS 108 documentation barriers informal competitors from interstate distribution. |
| Backward Integration into Aluminum Extrusion | Indiana campus expansion secures input cost stability against commodity volatility. |
| EV-Optimized Hull Redesign | Reduced drag coefficients and tongue weights align with emerging tow vehicle electrification. |
| Fleet Service Contracting | Utah backcountry operators aggregate demand for standardized specifications with rapid-turnaround maintenance. |
| Gel-Coat Technician Training Programs | Workforce development addresses composite lamination skill scarcity threatening premium tier production. |
Research Methodology
Bottom-up rental fleet and individual ownership modeling reconciled against top-down material input and production capacity tracking forms the analytical core of this study. Primary interviews with trailer manufacturing executives, fleet procurement managers at Utah overlanding operators, NHTSA compliance engineering consultants, and Pacific Northwest fiberglass fabricators were validated against secondary sources including Bureau of Land Management dispersed camping utilization reports, Recreational Vehicle Industry Association build standard filings, and aluminum commodity trade data. Triangulation between demand-side survey responses and supply-side production estimates ensures cross-verified volume and value outputs.
Input-output matrices model unit shipments and average selling prices across the projection horizon by product type, material composition, weight classification, and end-user channel. Segmentation dimensions include off-road versus compact versus luxury specifications, aluminum versus fiberglass versus steel shell construction, and fleet versus individual procurement patterns. CAGRs derive from regression analysis of historical participation rates in overlanding activities correlated with trailer registration data and forecasted against Bureau of Land Management access expansion timelines. Industry-specific forecast inputs incorporate EV tow rating evolution and NHTSA enforcement pattern intensification.
Caveats apply where aluminum price volatility, fiberglass supply bottlenecks, or state-level brake threshold regulatory shifts could materially shift the outlook. Forecasts reflect base-case assumptions regarding dispersed camping access continuity and overlanding participation growth trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
North America Hovercraft Market
Recreational Vehicles
Leisure Boat Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market
Recreational Vehicles
Recreational Boats Market
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
Snowmobile Trailer Axle Market
Recreational Vehicles
Electric Golf Cart Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
Golf Cart Market