
 Automotive Aftermarket Fuel Additives Market | 2026-2036
Automotive Aftermarket Fuel Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Aftermarket Fuel Additives Market Analysis
Multi-bottle treatment kits is hardening as the dominant retail configuration, replacing single-purpose containers with bundled injector cleaner, octane booster, and stabilizer combinations. BASF SE leverages its integrated chemical supply chain to control input costs across additive families. Afton Chemical Corporation anchors North American distribution through relationships with major petroleum refiners. Lucas Oil Products, Inc. competes in the performance-enthusiast segment with concentrated formulations for high-compression engines.
Automotive aftermarket fuel additives are chemical formulations blended into gasoline, diesel, or alternative fuels to enhance combustion efficiency, reduce deposit formation, and protect fuel system components; typical compositions include polyetheramine detergents, polyisobutylene succinimide dispersants, and organometallic octane improvers at treat rates of 0.1 to 1.0 percent by volume. These products serve commercial purposes by extending injector life, restoring lost fuel economy, and enabling compliance with emissions standards in vehicles operating beyond factory warranty periods. Fuel injector cleaners lead product type revenue due to direct-to-consumer familiarity and repeat purchase cycles, while diesel additives represent the fastest-growing category driven by commercial fleet uptime requirements. Passenger vehicles dominate application volume, though heavy-duty trucks generate superior per-unit revenue through higher treat rates and specialized cetane improver formulations.
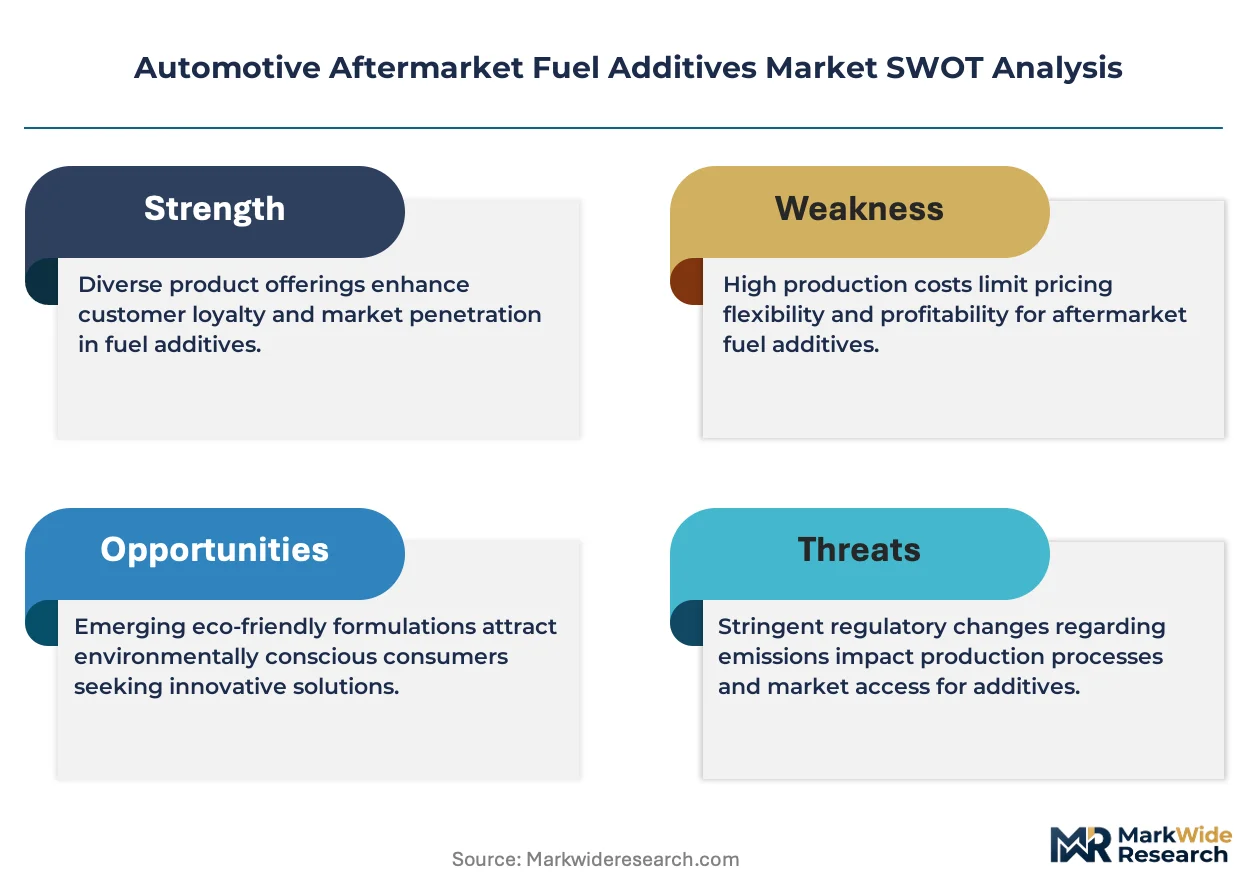
The United States Environmental Protection Agency regulates fuel additive registration through the Toxic Substances Control Act and 40 CFR Part 79, mandating emissions testing before market entry. California Air Resources Board imposes additional volatility and benzene limits that shape regional formulation requirements. The European Chemicals Agency enforces REACH registration for imported additive packages, creating compliance barriers for non-EU suppliers. Stakeholders must monitor tightening particulate number limits and the spread of renewable diesel blends that alter additive solubility and compatibility profiles.
Market Dynamics
Diesel particulate filter maintenance costs are forcing commercial fleet operators into preventive additive programs, converting reactive repair spending into predictable chemical procurement budgets.
Growth Catalysts
- EPA 40 CFR Part 79:Mandatory emissions testing for fuel additive registration creates compliance-driven replacement cycles as older formulations lose certification.
- Renewable diesel blends:Solubility challenges with hydrotreated vegetable oil require reformulated dispersant packages, generating technical refresh demand.
- Commercial fleet uptime requirements:Heavy-duty truck operators prioritize injector cleanliness to minimize roadside breakdowns and lost revenue.
Market Restraints
- Polyetheramine feedstock concentration:Three Asian petrochemical producers control over 70 percent of global PEA supply, exposing formulators to price volatility.
- REACH registration costs:European Chemicals Agency compliance fees exceed €100,000 per substance, blocking small importers from EU market entry.
- Direct injection carbon buildup:Gasoline direct injection engines experience valve deposit issues that basic detergent additives cannot address, limiting product efficacy claims.
Strategic Opportunities
- India BIS fuel quality enforcement:Stricter benzene and sulfur limits in metropolitan fuel supplies create additive adoption potential as vehicle owners seek performance restoration.
- Subscription-based replenishment:Direct-to-consumer auto-ship programs bypass traditional auto parts retail, capturing lifetime value from enthusiast segments.
- Hybrid powertrain compatibility:Formulations addressing intermittent combustion cycles in plug-in hybrids represent an underserved technical specification.
Industry Challenges
- Combustion chemist talent scarcity:Specialized expertise in organometallic compound stability is concentrated among retiring formulators at legacy petroleum laboratories.
- CARB volatility certification timelines:California Air Resources Board testing queues extend 18-24 months, delaying product launches for reformulated gasoline seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Aftermarket Fuel Additives Market |
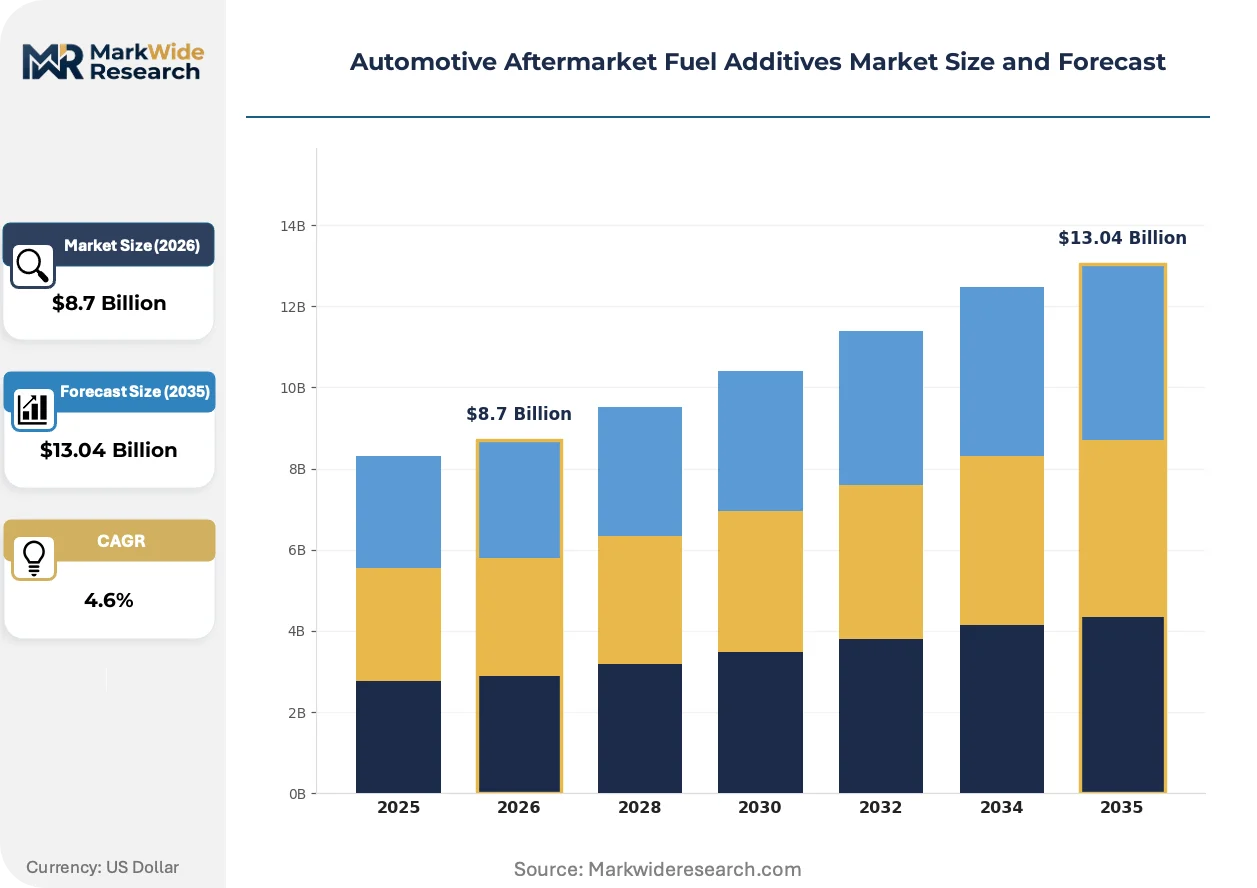
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Injector Cleaners, Octane Boosters, Diesel Additives, Cetane Improvers Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Distribution Channel: Online Retail, Automotive Stores, Supermarkets, Wholesalers Consumer Type: Individual Consumers, Fleet Operators, Workshops, OEMs |
| Companies Covered | Lubrizol Corporation, Infineum International Ltd., Afton Chemical Corporation, BG Products, Inc., Lucas Oil Products, Inc., BASF SE, Innospec Inc., Ashland Inc., Chevron Oronite Company LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Aftermarket Fuel Additives Market Emerging Trajectories
Formulation chemistry is converging with digital distribution models as additive producers bypass traditional retail shelf space constraints. Three developments are compressing competitive timelines.
Polyetheramine detergent technology is unifying deposit control across port and direct injection architectures. Tier 1 suppliers are adopting these dual-mechanism formulations for OEM factory-fill applications. This convergence is collapsing the historical separation between gasoline and diesel additive development tracks.
California Air Resources Board is tightening Reid Vapor Pressure limits for summer-grade gasoline, forcing reformulation of volatile organic compound carriers in additive packages. Blenders are responding with higher-flash-point solvent systems that maintain treat-rate efficacy. The impact concentrates in Western US distribution networks where CARB rules apply.
Fleet procurement departments are consolidating chemical spending through integrated vehicle maintenance platforms. Traditional jobber networks lose volume to telematics-linked replenishment systems that trigger additive orders based on engine hours. This pattern is most visible in Germany where commercial vehicle telematics penetration exceeds 60 percent.
Automotive Aftermarket Fuel Additives Market Segmentation
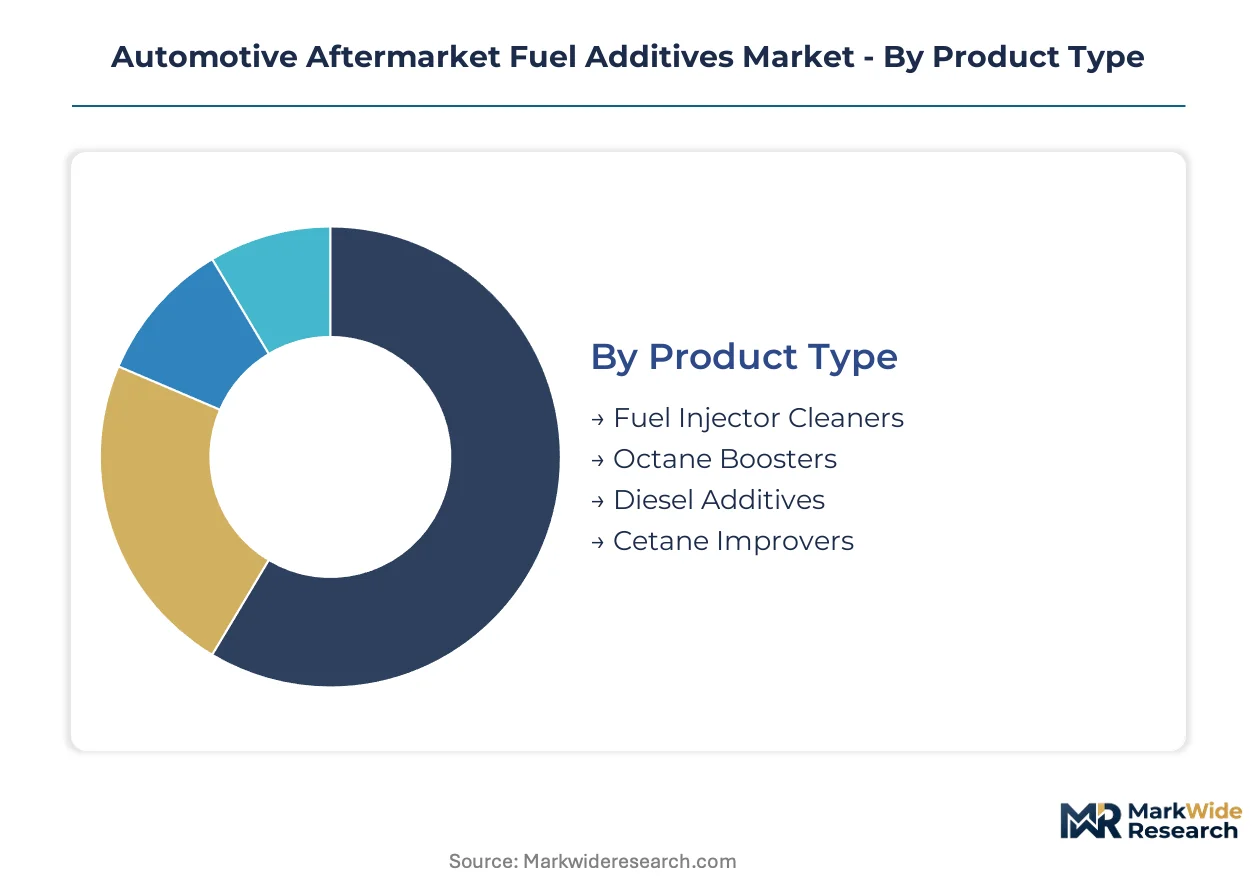
Fuel additive purchasing decisions hinge on engine architecture, duty cycle intensity, and procurement authority. Each segmentation dimension reveals distinct price sensitivity, technical specification requirements, and channel preferences that shape formulation and packaging strategies.
Product Type:
Fleet procurement departments prioritize treat-rate economics and emissions compliance certification over retail branding.
- Fuel Injector Cleaners:Polyetheramine-based detergents dissolve intake valve and combustion chamber deposits at treat rates of 0.1-0.3 percent by volume. United States passenger vehicle owners drive repeat purchase cycles through direct-to-consumer familiarity with injector maintenance.
- Diesel Additives:Multi-functional packages combine cetane improvers, lubricity agents, and dispersants to address hydrotreated vegetable oil compatibility challenges. Commercial fleet operators in Germany convert reactive DPF maintenance spending into preventive chemical procurement budgets.
- Octane Boosters:Organometallic compounds raise gasoline octane ratings 2-5 points for high-compression engines. Performance enthusiasts accept premium pricing for concentrated formulations.
- Cetane Improvers:2-Ethylhexyl nitrate and di-tert-butyl peroxide accelerate ignition delay reduction in cold-start conditions. Heavy-duty truck specifications demand higher treat rates than passenger applications.
Fuel injector cleaners lead on scale; diesel additives lead on momentum.
Application:
Duty cycle severity determines additive consumption intensity and formulation sophistication requirements.
- Heavy-Duty Trucks:Extended idle hours and high-load operation accelerate injector deposit formation and fuel degradation. Fleet telematics integration in Germany triggers automated additive replenishment based on engine operating hours.
- Passenger Vehicles:Gasoline direct injection engines experience intake valve carbon buildup that basic detergent packages cannot address. United States vehicle owners aged 8-12 years sustain aftermarket chemical consumption.
- Commercial Vehicles:Delivery van operators balance uptime requirements with per-mile cost controls. Urban stop-and-go duty cycles increase deposit accumulation rates.
- Motorcycles:Small-displacement engines with irregular usage patterns benefit from fuel stabilizers and corrosion inhibitors. Seasonal storage drives concentrated seasonal demand.
Passenger vehicles dominate unit volume; heavy-duty trucks generate superior per-unit revenue.
Distribution Channel:
Channel selection reflects purchase urgency, technical consultation needs, and subscription adoption patterns.
- Online Retail:Direct-to-consumer auto-ship programs capture lifetime value from enthusiast segments. Digital platforms bypass traditional auto parts retail shelf space constraints.
- Automotive Stores:Counter staff provide application guidance for confused consumers navigating injector cleaner versus octane booster selections. United States chains maintain regional formulation inventories for CARB compliance zones.
- Supermarkets:Impulse placement of single-bottle treatments captures price-sensitive maintenance deferrers. Limited shelf space favors bundled multi-purpose formulations.
- Wholesalers:Jobber networks supply independent repair shops with bulk packaging options. Volume consolidation pressures are shifting procurement toward telematics-linked fleet platforms.
Automotive stores anchor current volume; online retail is gaining share fastest.
Consumer Type:
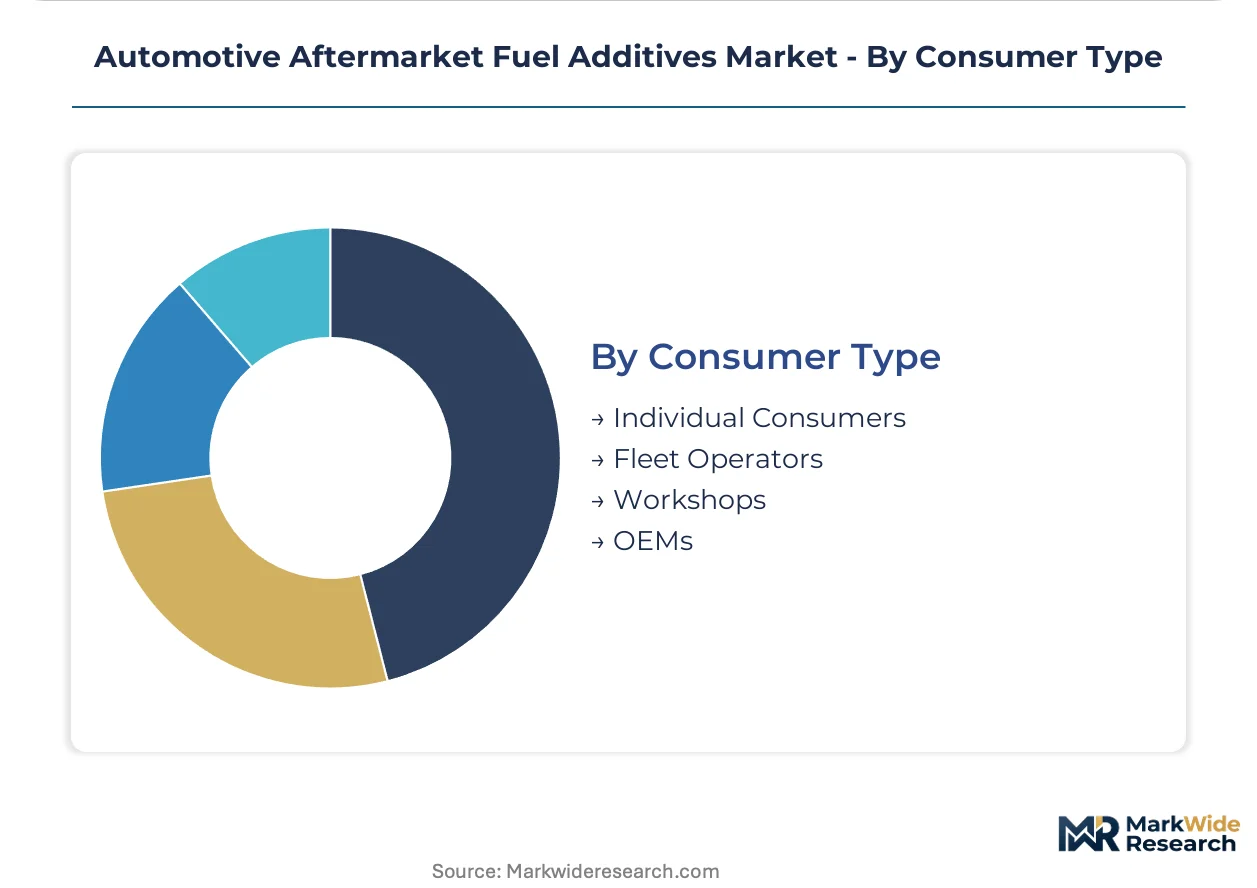
Procurement authority and technical sophistication create four distinct serviceable addressable markets.
- Fleet Operators:Integrated vehicle maintenance platforms consolidate chemical spending through telematics-triggered replenishment. Predictable consumption patterns support volume pricing negotiations.
- Individual Consumers:Brand recognition and packaging clarity drive retail selection. Price elasticity varies sharply between emergency repair scenarios and routine maintenance.
- Workshops:Service bay upsell opportunities depend on visual demonstration of injector spray pattern improvement. Technical training requirements limit additive recommendation consistency.
- OEMs:Factory-fill specifications demand exhaustive emissions certification and supply chain audit documentation. Long qualification timelines favor incumbent suppliers with established regulatory relationships.
Fleet operators concentrate purchasing volume; individual consumers fragment across thousands of decision points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive aftermarket fuel additives industry traces its commercial origins to mid-20th century United States petroleum refining corridors, where detergent chemistry first scaled for mass-market gasoline distribution. Regional demand patterns now reflect diverging fleet compositions, emissions enforcement intensity, and fuel quality infrastructure maturity across major automotive markets.
United States
Aging light-duty vehicle parc averaging 12.5 years sustains steady aftermarket chemical consumption as owners seek performance restoration. EPA 40 CFR Part 79 mandates emissions testing for additive registration, creating compliance-driven replacement cycles for legacy formulations. The Houston-Gulf Coast petrochemical corridor anchors domestic polyetheramine production, supplying formulators with critical detergent feedstocks.
Germany
Commercial vehicle telematics penetration exceeding 60 percent enables automated additive replenishment triggered by engine operating hours. KBA type-approval requirements for fuel system treatments add certification layers beyond EU baseline standards. The Rhine-Ruhr industrial cluster hosts concentrated blending operations serving Central European fleet operators managing hydrotreated vegetable oil compatibility challenges.
China
Expanding heavy-duty truck fleet and tightening GB fuel quality standards drive diesel additive adoption for particulate filter protection. MIIT oversight of automotive chemicals aligns with national dual carbon goals pressuring combustion efficiency improvements. The Yangtze River Delta manufacturing belt concentrates domestic additive packaging and distribution infrastructure.
India
BIS enforcement of stricter benzene and sulfur limits in metropolitan fuel supplies creates performance restoration demand among vehicle owners. CDSCO registration requirements for fuel system treatments remain lighter than REACH-equivalent regimes, lowering import barriers. The Maharashtra-Gujarat industrial corridor hosts emerging blending capacity targeting commercial fleet procurement consolidation.
Japan
Hybrid powertrain proliferation generates formulation demand addressing intermittent combustion cycle deposits. METI coordination of fuel quality standards with automotive manufacturer specifications shapes additive compatibility requirements. The Kanto region around Tokyo maintains concentrated aftermarket distribution serving aging passenger vehicle stock.
Automotive Aftermarket Fuel Additives Market Vendor Landscape
The competitive structure tilts toward integrated petrochemical conglomerates with captive raw material positions. Three strategic archetypes dominate: multinational chemical majors leveraging backward integration into detergent feedstocks; specialized additive houses concentrating on regulatory certification expertise; and performance-oriented brands serving enthusiast segments with concentrated formulations. Capacity expansion and portfolio diversification represent the dominant competitive moves as players address renewable diesel blend compatibility requirements.
Among the integrated chemical majors, BASF SE exemplifies backward integration advantages across polyetheramine supply chains. Afton Chemical Corporation and Lucas Oil Products, Inc. occupy differentiated positions within the North American market structure, with the former anchoring refiner-facing distribution relationships and the latter representing the enthusiast-segment specialization archetype. These three companies illustrate how competitive positioning fragments across feedstock control, regulatory relationship depth, and brand equity intensity rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Lubrizol Corporation |
| Infineum International Ltd. |
| Afton Chemical Corporation |
| BG Products, Inc. |
| Lucas Oil Products, Inc. |
| BASF SE |
| Innospec Inc. |
| Ashland Inc. |
| Chevron Oronite Company LLC |
| Others |
Supply Flow & Price Mechanics
Polyetheramine spot indices cascade through three distinct pricing tiers as formulators pass feedstock volatility downstream to fleet procurement departments and retail consumers. Diesel additive packages command premium positioning against gasoline treatments due to higher treat-rate requirements and specialized cetane improver loadings. EPA certification costs and CARB volatility testing timelines embed compliance premiums that concentrate in Western United States distribution networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification depth and treat-rate concentration. Premium formulations carry EPA 40 CFR Part 79 emissions certification and CARB volatility compliance, while economy tiers compete on per-ounce cost for price-sensitive retail consumers. Cost compression in the standard tier intensifies because renewable diesel blend incompatibility forces rapid technical refresh cycles. Fleet operators exhibit lowest price sensitivity due to uptime value capture, whereas supermarket impulse buyers defer purchases when unit costs exceed psychological thresholds.
Supply Chain Analysis
Dual-sourcing requirements from major petroleum refiners mandate multi-supplier qualification for polyetheramine detergent feedstocks. Production concentrates in the United States Gulf Coast, Germany's Rhine-Ruhr corridor, and China's Yangtze River Delta manufacturing belt. Raw material dependencies center on ethylene oxide derivatives, organometallic octane improvers, and hydrotreated vegetable oil compatibility agents. Single-source vulnerability from three Asian petrochemical producers controlling over 70 percent of global PEA supply exposes formulators to price spikes. Distribution runs through integrated vehicle maintenance platforms in Germany and traditional jobber networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as fleet operators shift procurement toward premium formulations with verified emissions compliance and telematics-triggered replenishment integration.
For Market Incumbents: Cement backward integration into polyetheramine supply chains to neutralize Asian feedstock concentration risk. Secure long-term offtake agreements with hydrotreated vegetable oil producers before renewable diesel blend mandates expand. Prioritize CARB certification pipeline investments to compress 18-24 month volatility testing timelines that delay product launches. For New Entrants and Emerging Players: BIS fuel quality enforcement in India opens a window for import-focused additive houses targeting performance restoration demand in metropolitan fuel markets. White-space concentration sits with hybrid powertrain compatibility formulations addressing intermittent combustion cycle deposits. Direct-to-consumer auto-ship programs bypass retail shelf space constraints and capture enthusiast segment lifetime value. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized additive houses possessing deep EPA regulatory relationships and existing CARB certification portfolios. Long-term viability favors players with demonstrated renewable diesel blend reformulation capabilities and telematics platform integration. Watch for inflection when fleet telematics penetration crosses critical thresholds in commercial vehicle markets outside Germany.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyetheramine Feedstocks | Captive supply of critical detergent raw materials neutralizes Asian producer pricing power. |
| Renewable Diesel Compatibility Certification | EPA 40 CFR Part 79 registration for hydrotreated vegetable oil formulations opens fleet procurement channels. |
| Telematics Platform Integration | Engine-hours-triggered replenishment contracts convert transactional sales to predictable recurring revenue. |
| CARB Volatility Testing Pipeline Expansion | Compressed certification timelines capture summer-grade gasoline reformulation windows in Western US markets. |
| Direct-to-Consumer Auto-Ship Launch | Bypasses automotive retail shelf constraints and captures enthusiast segment repeat purchase cycles. |
Methodological Framework
Direct dialogue with formulator R&D directors, fleet procurement managers at commercial vehicle operators, automotive aftermarket distributors, and regulatory affairs specialists at petroleum refiners grounded qualitative insights. Secondary validation drew from EPA 40 CFR Part 79 registration databases, CARB certified product listings, ECHA REACH substance inventories, customs trade data on polyetheramine imports, and SEC filings from integrated chemical majors. Bottom-up segment sizing triangulated against top-down fuel consumption projections and vehicle parc aging models.
Segment-level value outputs across product type, application, distribution channel, and consumer type dimensions were modeled over the projection horizon. CAGRs were derived from regression analysis against historical additive consumption intensity, fleet composition shifts, and regulatory enforcement trajectories. Forecast inputs incorporated renewable diesel blend penetration curves, telematics adoption rates in commercial fleets, and particulate filter maintenance cost inflation.
Revisions become necessary when EPA emissions testing backlogs extend beyond historical 18-24 month queues, Asian polyetheramine supply disruptions materialize, or renewable diesel blend specifications shift solubility requirements. Deviation in CARB volatility limit tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Vehicle Health Monitoring Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
United Kingdom Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Stolen Vehicle Recovery Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market