
 RV Solar Panels Market | 2026-2036
RV Solar Panels Market Size, Share, and Industry Trends Forecast 2026-2036
RV Solar Panels Market Insights
Market Dynamics
Remote monitoring and predictive maintenance subscriptions is decoupling hardware sales from recurring revenue streams in the RV solar ecosystem. LONGi Solar leverages its monocrystalline wafer scale to dominate cost-efficient supply for OEM integrations. Canadian Solar sustains geographic diversification across North American distribution channels. Rich Solar specializes in purpose-built kits for aftermarket RV retrofitters, competing on installation simplicity rather than cell efficiency alone.
Technology and Segmentation
RV solar panels are photovoltaic modules engineered for mobile deployment, typically constructed with lightweight aluminum frames, tempered glass laminates, and junction boxes rated for vibration resistance up to 5,000 cycles, converting sunlight into DC electricity to charge lithium or lead-acid battery banks without shore power dependency. Monocrystalline segments command premium positioning due to higher watt-per-square-foot output critical for space-constrained rooftops, while portable installations represent the fastest-growing structural category as rental firms and weekend campers prioritize flexibility over permanent mounting. Thin-film variants occupy niche applications where extreme weight reduction outweighs efficiency penalties on smaller towable trailers.
Regulatory Environment
FCC Part 15 governs electromagnetic emissions from integrated charge controllers and inverter systems, while California Energy Commission Title 24 provisions increasingly reference solar-ready pre-wiring mandates for new recreational vehicle construction. NREL certification protocols shape product credibility for interstate commerce, influencing buyer procurement criteria across dealership networks. Stakeholders must track evolving state-level net metering reforms and utility interconnection standards that determine whether RV-integrated systems qualify for grid-export compensation during stationary deployment.
Market Dynamics
Remote monitoring subscriptions are decoupling hardware revenue from recurring service income, forcing manufacturers to build software capabilities alongside photovoltaic module production. This structural shift rewards firms that can integrate predictive maintenance algorithms with charge controller hardware.
Growth Catalysts
- California Title 24 pre-wiring mandates:New recreational vehicle construction standards require solar-ready electrical infrastructure, embedding photovoltaic compatibility into OEM production lines.
- Full-time RV owner density:The southwestern United States corridor from Phoenix to Palm Springs concentrates demand for rooftop systems among permanent mobile residents seeking energy independence.
- Monocrystalline efficiency gains:Higher watt-per-square-foot output addresses space-constrained rooftop geometries on Class B and Class C motorhomes.
Market Restraints
- Polysilicon price volatility:Raw material input costs for wafer production fluctuate with Chinese manufacturing capacity constraints and trade policy adjustments.
- Lithium battery bank costs:Storage system expenses represent 40-60% of total installed system cost, compressing addressable market for budget-conscious weekend campers.
- FCC Part 15 compliance burden:Electromagnetic emissions testing for integrated inverters and charge controllers adds certification timeline friction for new market entrants.
Strategic Opportunities
- Portable installation segment:Rental fleet operators and seasonal campers prioritize flexible deployment over permanent mounting, opening aftermarket kit demand.
- Arizona-California desert corridor:Irradiance levels exceeding 6.5 kWh/m²/day create optimal conditions for thin-film variants on lightweight towable trailers.
- Net metering reform tailwinds:State-level utility interconnection standards determining grid-export compensation for stationary RV deployment create arbitrage opportunities for seasonal park residents.
Industry Challenges
- NREL certification timelines:Interstate commerce credibility requires photovoltaic testing protocol completion, creating 4-6 month product launch delays.
- Installation technician scarcity:Specialized training for vibration-resistant junction box mounting and roof penetration sealing limits service network expansion.
- Legacy lead-acid integration:Compatibility engineering for existing battery bank architectures complicates lithium upgrade pathways for retrofit installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RV Solar Panels Market |
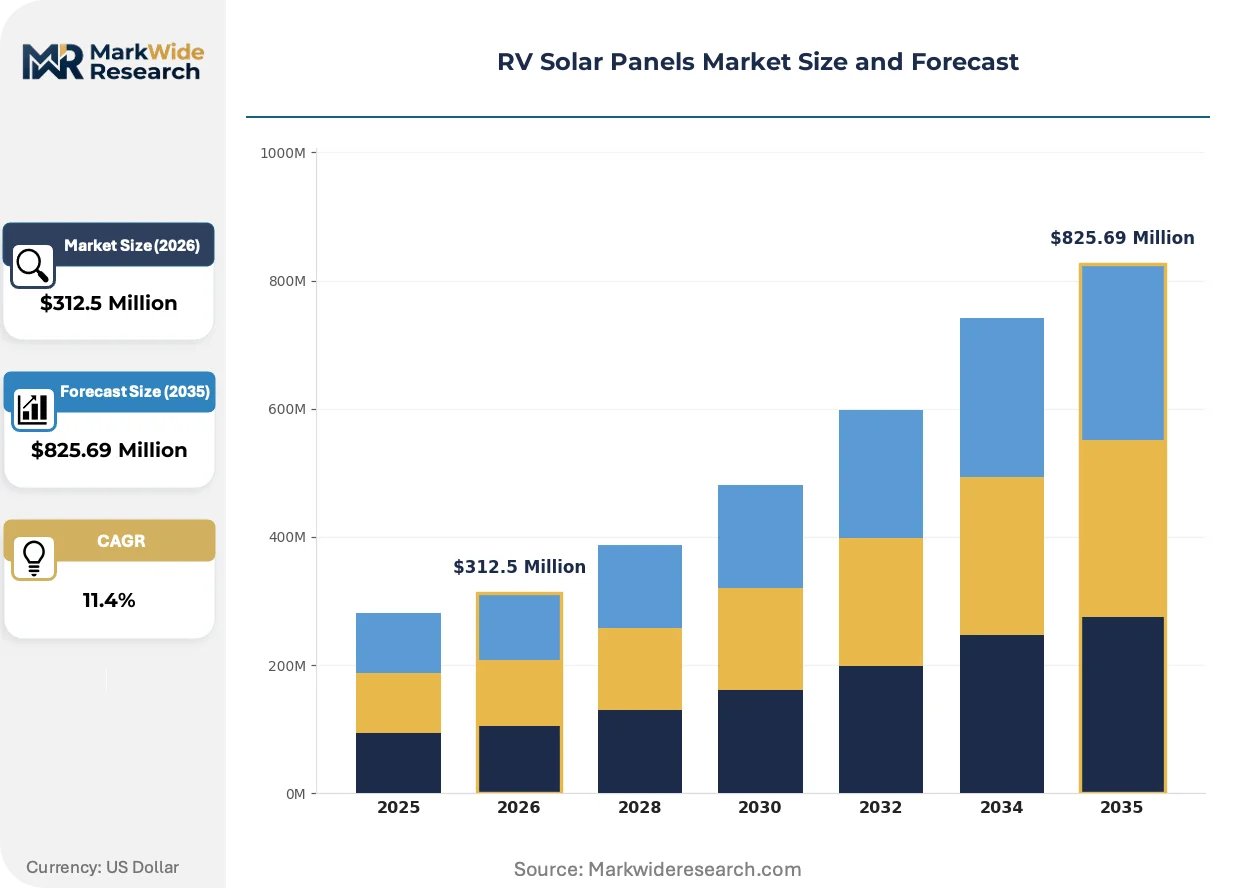
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Installation Type: Roof-Mounted, Portable, Ground-Mounted, Hybrid Power Rating: 100W, 200W, 300W, 400W End User: Individual Owners, RV Rental Firms, RV Manufacturers, Commercial Fleets |
| Companies Covered | LONGi Solar, Canadian Solar, JinkoSolar, Rich Solar, Aiko Solar, JA Solar, Tongwei Solar, QCells, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RV Solar Panels Market Trends and Innovations
Power electronics miniaturization and cellular connectivity are converging to transform how RV owners manage energy systems, shifting competitive advantage toward software-integrated hardware ecosystems.
Module-level power electronics with embedded microinverters is decentralizing energy conversion from centralized string inverters to individual panel optimization. Full-time boondockers and off-grid enthusiasts are adopting these systems at accelerating rates despite 15-20% cost premiums. This topology is decentralizing system design authority from professional installers to end-users, compressing dealer channel margins and enabling direct-to-consumer sales models.
California Energy Commission Title 24 solar-ready pre-wiring provisions are mandating conduit and electrical infrastructure in new RV construction. These requirements force OEMs to standardize roof penetration sealing methods and wire gauge specifications during chassis assembly. Class A motorhome manufacturers face the steepest compliance costs, while smaller trailer builders benefit from simpler electrical architectures.
Subscription-based remote diagnostics are displacing traditional warranty service models across the aftermarket channel. Buyers now expect cellular-enabled charge controllers with mobile app visibility into state-of-charge and panel performance metrics. This behavioral shift is most pronounced among rental fleet operators in Nevada and Utah, where asset utilization tracking justifies hardware cost premiums through reduced field service dispatch frequency.
RV Solar Panels Market Segmentation
RV solar panel segmentation reflects divergent technical requirements between permanent mobile residents seeking maximum output density and seasonal users prioritizing deployment flexibility. Cell technology choices and mounting configurations determine system economics across distinct use cases from desert boondocking to rental fleet management.
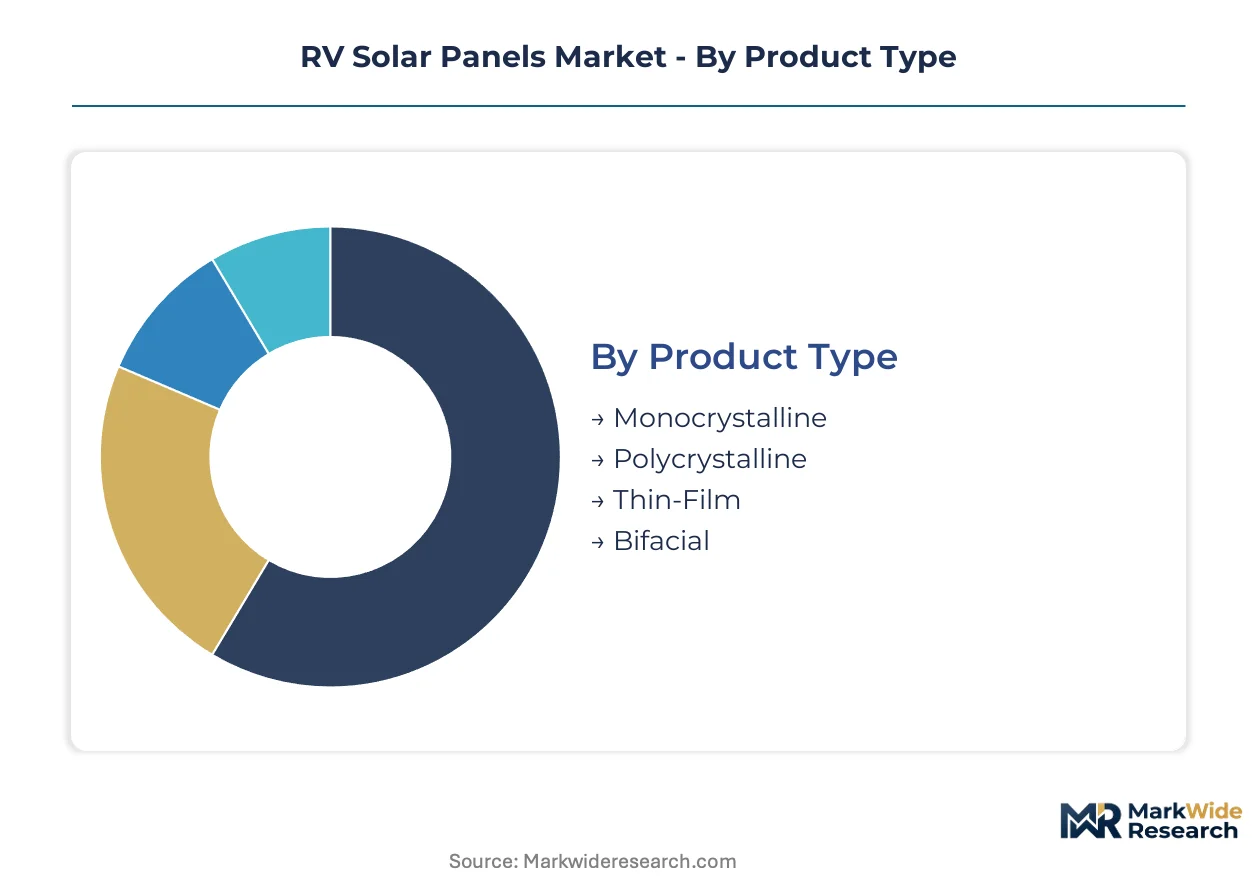
Product Type:
Monocrystalline and polycrystalline segments serve as embedded rooftop systems for energy-independent full-timers, while thin-film and bifacial variants address standalone applications where weight or bifacial gain justifies efficiency trade-offs.
- Monocrystalline:Single-crystal silicon wafers deliver the highest conversion efficiency, typically 19-22%, critical for space-constrained Class B and Class C motorhome rooftops. Demand concentrates among Arizona and California permanent RV residents where watt-per-square-foot maximization determines boondocking duration.
- Thin-Film:Cadmium telluride or copper indium gallium selenide deposition on flexible substrates achieves sub-2 kg/m² weight profiles, enabling adhesive mounting without structural reinforcement. Lightweight towable trailers in the southwestern desert corridor adopt these systems where roof load limits restrict conventional glass-framed modules.
- Polycrystalline:Multi-crystal silicon construction offers moderate efficiency at reduced cell cost, serving budget-conscious aftermarket retrofitters.
- Bifacial:Double-sided energy capture from rear-side albedo reflection gains 5-20% additional output on highly reflective desert surfaces.
Volume placements concentrate in monocrystalline; the faster expansion belongs to thin-film.
Installation Type:
Mounting configuration segmentation tracks the cost-versus-flexibility trade-off, with permanent hardware embedding into OEM production lines and portable systems serving seasonal rental economics.
- Roof-Mounted:Rigid aluminum-framed modules secured through Z-bracket or adhesive systems constitute the dominant embedded architecture. Class A motorhome manufacturers integrate these during chassis assembly to comply with California Title 24 pre-wiring mandates.
- Portable:Folding suitcase arrays with integrated charge controllers deploy via ground placement or temporary roof positioning. Utah and Nevada rental fleet operators prioritize this segment for asset utilization flexibility across variable customer trip durations.
- Ground-Mounted:Tilt-adjustable frames optimize seasonal angle capture for stationary seasonal park residents.
- Hybrid:Dual-mode systems switch between roof-fixed and portable deployment for multi-use RV owners.
Roof-mounted systems anchor revenue concentration; portable installations are gaining share fastest.
Power Rating:
Wattage segmentation aligns with battery bank capacity scaling and available rooftop real estate across vehicle classes from compact camper vans to luxury motorcoaches.
- 100W:Entry-level kits serve weekend campers with minimal electrical demand, typically paired with single 100Ah lead-acid batteries.
- 200W:Mid-range systems balance cost and output for extended off-grid stays.
- 300W:Higher-output arrays support lithium battery banks and inverter-driven appliance loads for full-time boondockers.
- 400W:Maximum-density configurations occupy premium Class A and large fifth-wheel rooftops.
200W-300W ratings dominate unit shipments; 400W systems show the steepest expansion trajectory.
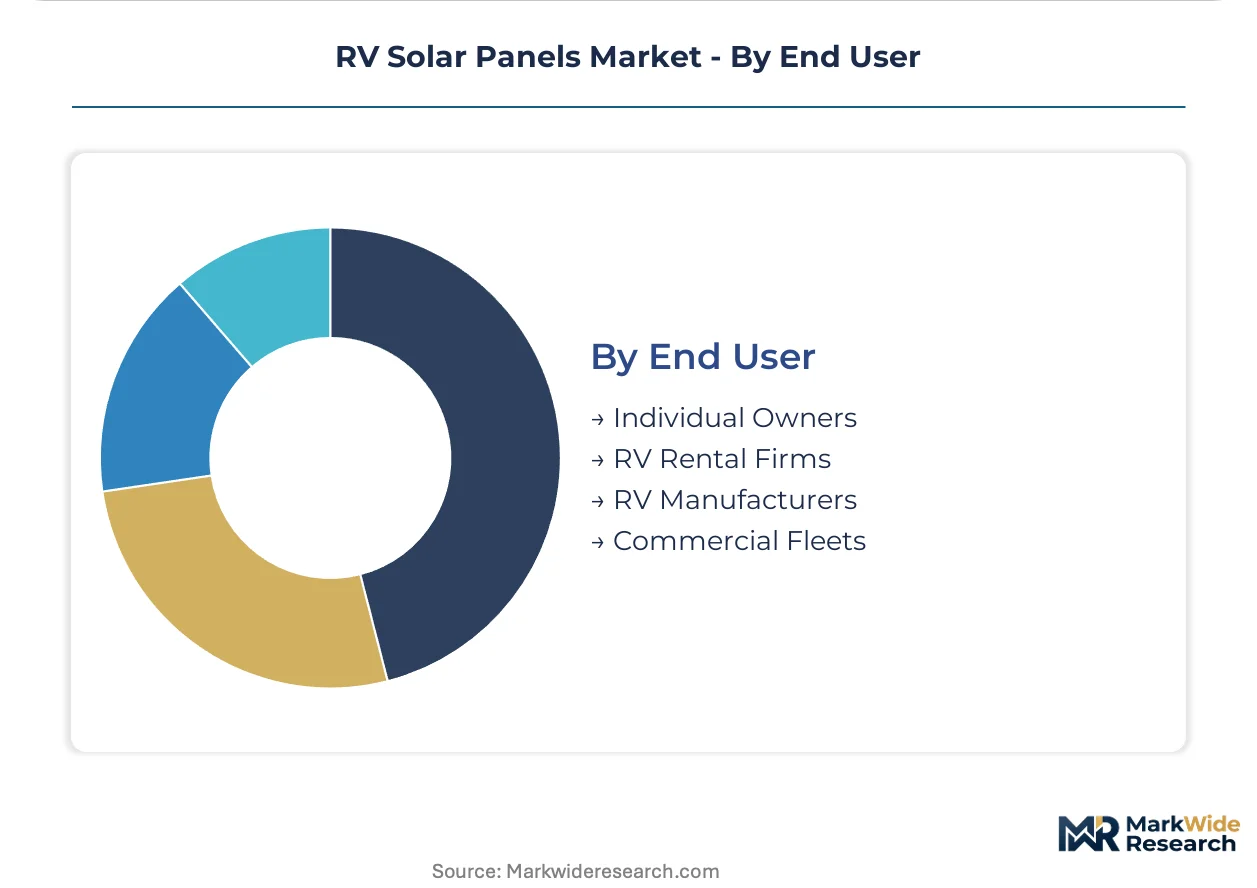
End User:
Customer type segmentation distinguishes between owner-operated systems with long payback horizons and fleet-managed assets where utilization tracking justifies hardware premiums.
- Individual Owners:Full-time mobile residents and serious off-grid enthusiasts drive monocrystalline rooftop adoption with 5-7 year ownership horizons.
- RV Rental Firms:Corporate fleet operators in the Phoenix-Palm Springs corridor deploy portable systems with cellular monitoring for remote asset management.
- RV Manufacturers:OEM integration of solar-ready pre-wiring and factory-installed modules responds to California Energy Commission mandates.
- Commercial Fleets:Mobile service businesses and construction site offices utilize ground-mounted or hybrid systems for stationary power independence.
Individual owners anchor volume; rental firms represent the most rapidly expanding customer category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of photovoltaic cells while the United States absorbs the highest RV solar deployment volumes. This production-consumption divide shapes trade flows and pricing structures across the industry.
United States
Full-time RV owners in the southwestern desert corridor drive rooftop system demand, with Arizona and California registering the highest per-capita installations. FCC Part 15 governs electromagnetic emissions from integrated charge controllers and inverters. The Phoenix-Palm Springs metropolitan axis concentrates both permanent mobile residents and rental fleet operators deploying monitored portable arrays.
Canada
Seasonal campers in British Columbia and Alberta prioritize lightweight thin-film systems for summer off-grid expeditions. Health Canada sets electrical safety standards for recreational vehicle modifications. Vancouver Island and the Rocky Mountain corridor host clusters of aftermarket installers serving the coastal-to-mountain camping circuit.
Germany
Caravan tourism across Bavaria and Baden-Württemberg sustains steady demand for compact monocrystalline kits. CE marking requirements under EU directives standardize product safety for cross-border commerce. The Stuttgart-Munich industrial belt houses distributors supplying Alpine camping regions with vibration-resistant module systems.
Australia
Remote touring culture in Western Australia and Queensland drives adoption of high-output rooftop configurations for extended outback travel. The Clean Energy Council administers product accreditation for grid-interactive systems. Perth and Brisbane serve as logistics hubs for distributing corrosion-resistant aluminum-framed modules to coastal and desert camping zones.
Japan
Compact camper van owners in the Kanto and Kansai regions seek space-efficient monocrystalline arrays for weekend excursions. METI renewable energy incentives influence residential solar adoption patterns that extend to recreational applications. Nagoya-based chassis manufacturers increasingly specify solar-ready pre-wiring for domestic RV production lines.
RV Solar Panels Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the RV solar value chain. Wafer manufacturers with captive polysilicon supply dominate upstream cost structures while downstream integrators specialize in kit assembly and installation services. Three archetypes define competitive positioning: scale-driven monocrystalline suppliers, purpose-built aftermarket specialists, and vertically integrated OEM partners. Capacity expansion in Southeast Asian cell manufacturing and strategic partnerships between module makers and charge controller developers represent the dominant competitive moves reshaping supply relationships.
Among Chinese wafer-scale producers, LONGi Solar and JinkoSolar occupy positions as archetypal cost-efficient suppliers for OEM integration programs. Canadian Solar represents the geographic diversification archetype with established North American distribution infrastructure. Rich Solar exemplifies the purpose-built specialist model targeting aftermarket retrofitters with simplified installation systems.
| Leading Market Players |
|---|
| LONGi Solar |
| Canadian Solar |
| JinkoSolar |
| Rich Solar |
| Aiko Solar |
| JA Solar |
| Tongwei Solar |
| QCells |
| Trina Solar |
| Others |
Pricing and Supply Chain Analysis
Chinese state-backed wafer producers anchor upstream supply, translating polysilicon scale into pricing discipline that squeezes mid-tier module assemblers lacking captive silicon supply. This ownership pattern concentrates cost advantage among vertically integrated cell manufacturers while forcing pure-play kit designers toward software differentiation to escape commodity margin compression.
Pricing Analysis
Margin tightening in aftermarket monocrystalline kits reflects LONGi Solar and JinkoSolar wafer-scale cost positions. Three-tier pricing structure across premium NREL-certified, standard UL-listed, and economy non-certified levels separates buyers by installation complexity tolerance. Price differentiation hinges on California Title 24 pre-wiring compliance and cellular monitoring subscription bundling. Weekend campers show highest price sensitivity; full-time boondockers absorb premiums for efficiency density.
Supply Chain Analysis
Returns of failed junction boxes and charge controllers flow back through Arizona distributor hubs for refurbishment, creating secondary supply for budget retrofitters. Polysilicon refining concentrates in China; cell manufacturing spreads across Vietnam and Malaysia; North American distribution centers in Phoenix and Ontario handle final-mile logistics. Raw material dependencies include metallurgical-grade silicon, aluminum extrusion stock, and lithium iron phosphate cells. Tariff exposure on Chinese module imports creates margin risk for price-sensitive portable kit segments. Distribution runs through OEM direct contracts, specialty RV dealers, and direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California Title 24 mandates erect a compliance moat that rewards pre-certified incumbents while filtering out undercapitalized entrants lacking NREL testing infrastructure investment.
For Market Incumbents: Cement Title 24 pre-wiring partnerships with Class A motorhome OEMs before regulatory adoption spreads to additional states. Deepen backward integration into charge controller firmware development to capture recurring remote monitoring revenue streams threatened by standalone software entrants. Prioritize Arizona and Nevada service network density to capture seasonal park installation demand. For New Entrants and Emerging Players: Direct-to-consumer YouTube tutorial channels and Amazon storefronts bypass dealer channel gatekeepers dominated by established kit brands. Target thin-film portable systems for Utah rental fleet operators prioritizing asset flexibility over efficiency specifications. White-space exists in hybrid roof-portable dual-mode systems for multi-use RV owners unwilling to commit to permanent mounting. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-integrated hardware specialists with cellular monitoring platforms in the southwestern United States corridor. Long-term viability rests on recurring service revenue attachment rates rather than module shipment volumes. Monitor state-level net metering reform legislation as inflection signal for stationary RV grid-export economics.| Strategic Initiative | Industry Significance |
|---|---|
| NREL Certification Investment | California Title 24 compliance unlocks OEM pre-wiring integration contracts with motorhome manufacturers. |
| Charge Controller Firmware Acquisition | Predictive maintenance algorithms transform hardware vendors into recurring-revenue SaaS platforms. |
| Portable Kit Distribution Partnership | Nevada and Utah rental fleet operators prioritize flexible deployment over permanent rooftop systems. |
| Thin-Film Manufacturing Scale-Up | Sub-2 kg/m² weight profiles enable adhesive mounting on lightweight towable trailer roof limits. |
| Arizona Service Network Expansion | Installation technician scarcity limits aftermarket retrofit capacity in highest-irradiance desert corridors. |
Research Methodology
Document review covered NREL certification protocols, California Energy Commission Title 24 provisions, and FCC Part 15 electromagnetic emissions standards, complemented by interviews with RV manufacturer platform engineers, aftermarket installation technicians, rental fleet operations managers, and charge controller firmware developers. Secondary validation drew from EIA solar deployment data, customs import records for photovoltaic modules, and SEC filings of publicly traded wafer producers. Bottom-up unit shipment estimates triangulated against top-down addressable rooftop real estate calculations across Class A, B, and C motorhome categories.
Segment-level projections across monocrystalline, polycrystalline, thin-film, and bifacial cell technologies combined with roof-mounted, portable, ground-mounted, and hybrid installation configurations produced volume and value trajectories over the projection horizon. CAGRs derived from regression analysis of historical adoption curves against irradiance mapping, battery cost decline rates, and full-time RV household formation trends. Forecast inputs incorporated lithium battery bank price elasticity, cellular data plan subscription attach rates, and seasonal park electrical infrastructure expansion pipelines.
The model holds under stable polysilicon supply and continued California regulatory leadership; deviation in federal tariff policy or interstate net metering standardization would shift regional demand concentration. Forecasts reflect assumptions regarding NREL certification timeline stability and lithium storage cost trajectories. Practitioners should monitor Arizona and Nevada utility commission proceedings for early signals of stationary RV grid-interconnection rule changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
North America Hovercraft Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Watercraft Accessories Market
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
Luxury Yacht Market
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Snowmobile Trailer Axle Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Self Balancing Scooter Market