
 Kayak Seats Market | 2026-2036
Kayak Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Kayak Seats Market Insights
ISO 8098 recreational craft seating durability certification is redrawing supplier eligibility across the kayak seats value chain. Johnson Outdoors leverages its vertically controlled supply network to sustain premium positioning in ergonomic foam seating. Confluence Outdoor anchors its competitive stance through deep R&D investment in adjustable backrest architectures. AQUADESIGN specializes in lightweight marine-grade configurations that dominate European tour operator procurement cycles.
A kayak seat constitutes a load-bearing interface between the paddler and the hull, typically engineered from compression-molded foam, marine-grade nylon or neoprene laminates, and corrosion-resistant hardware with drainage channels to manage water ingress and pressure distribution over multi-hour excursions. Foam seats occupy the largest installed base due to proven durability and cost-efficient replacement cycles across rental fleets. Sit-on-top seats represent the fastest-expanding product type, driven by saltwater fishing and coastal recreation adoption where waterproof construction and elevated backrest geometry prove essential. Neoprene laminates command margin concentration in the professional paddler segment where thermal insulation and abrasion resistance justify material premiums.
EPA material content standards govern foam formulations and PVC plasticizer thresholds for products sold in the United States, while REACH restricts phthalate and flame-retardant chemistry across European distribution channels. These frameworks compel manufacturers to reformulate material stacks or sacrifice market access in regulated jurisdictions. Stakeholders must monitor evolving chemical restriction timelines and pre-qualify alternative polymer systems before compliance deadlines eliminate incumbent formulations from saleable inventory.
Market Dynamics
ISO 8098 recreational craft seating durability certification is redrawing supplier eligibility across the kayak seats value chain, forcing reformulation of foam and PVC components to meet tightening chemical content rules in regulated jurisdictions.
Growth Catalysts
- REACH phthalate restrictions:European manufacturers accelerating substitution of legacy plasticizers with bio-based alternatives, creating first-mover advantages for compliant suppliers.
- Saltwater fishing adoption:Coastal recreational users in the United States driving demand for waterproof sit-on-top configurations with elevated backrest geometry.
- Rental fleet refresh cycles:Tour operators along the Gulf Coast and Pacific Northwest upgrading seating at scale to reduce maintenance downtime and improve customer retention.
Market Restraints
- Petrochemical input volatility:Marine-grade neoprene and compression-molded foam remain exposed to crude-linked pricing swings, compressing margin predictability for mid-tier manufacturers.
- Supplier concentration in Asian polymer processing:Limited qualified sources for REACH-compliant foam formulations create single-source vulnerability for European distributors.
- Technical ceiling in thermal insulation:Neoprene laminates face inherent weight-density tradeoffs that constrain performance gains in professional paddler segments.
Strategic Opportunities
- EPA material standard harmonization:Anticipated alignment between United States and European chemical thresholds would reduce dual-formulation costs for cross-Atlantic suppliers.
- Adjustable backrest architectures:Convergence of ergonomic research and marine-grade corrosion hardware enables premium positioning in multi-hour excursion segments.
- Direct-to-rental procurement platforms:Digital channels bypassing traditional marine distributors are capturing volume from fleet operators seeking specification customization.
Industry Challenges
- ISO 8098 certification timelines:Testing protocols for load-bearing durability extend product development cycles by 8-14 months, delaying revenue recognition for new entrants.
- Legacy inventory stranding:Pre-REACH foam formulations face accelerated obsolescence as compliance deadlines approach, forcing write-downs across distributor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kayak Seats Market |
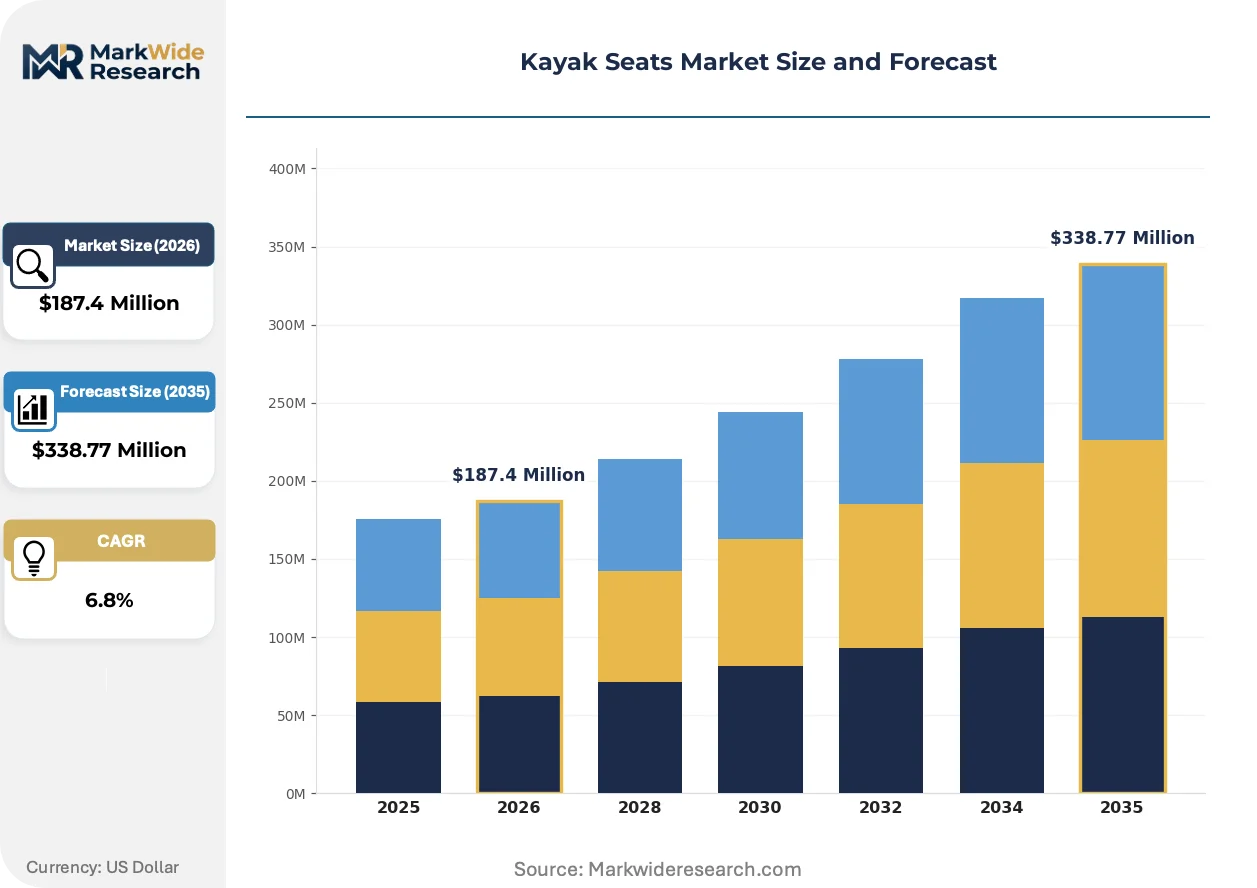
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Seats, Foam Seats, Baidarka Seats, Sit-On-Top Seats Material: Nylon, PVC, Neoprene, Polyester Feature: Ergonomic Design, Adjustable Backrest, Waterproof, Lightweight End User: Recreational Users, Professional Paddlers, Tour Operators, Rental Services |
| Companies Covered | Johnson Outdoors, Confluence Outdoor, AQUADESIGN, Nautiraid, Rotomod, Skwoosh, YakGear, Surf to Summit, GCI Outdoor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kayak Seats Market Trends and Innovations
Material science advances and procurement model evolution are compressing traditional competitive advantages in kayak seating, with certification requirements and digital distribution channels redistributing value capture across the supply chain.
Modular compression-molded foam systems with interchangeable density zones are decomposing the monolithic seat architecture that has dominated rental fleets for decades. Tour operators in the Pacific Northwest are piloting component-level replacement programs that reduce per-unit refresh costs by enabling field-level cushion swaps rather than full-seat disposal. This technology is decomposing the replacement cycle economics that previously favored low-cost disposable seating.
EPA material content standards governing foam formulations and PVC plasticizer thresholds are compelling manufacturers to pre-qualify alternative polymer systems before compliance deadlines eliminate incumbent formulations. The industrial consequence is a bifurcation between reformulation-capable suppliers and those sacrificing United States market access. Saltwater fishing applications face the steepest adjustment burden due to waterproofing requirements that historically relied on restricted chemistries.
Fleet procurement is consolidating specification authority at the regional operator level, displacing the decentralized purchasing that previously flowed through local marine retailers. Large rental services along the Gulf Coast are issuing centralized tenders with customized ergonomic requirements, compressing distributor margins while rewarding direct manufacturing relationships. This pattern is most visible in the United States, where tour operator chains are achieving procurement scale unmatched in European fragmented waterways.
Kayak Seats Market Segmentation
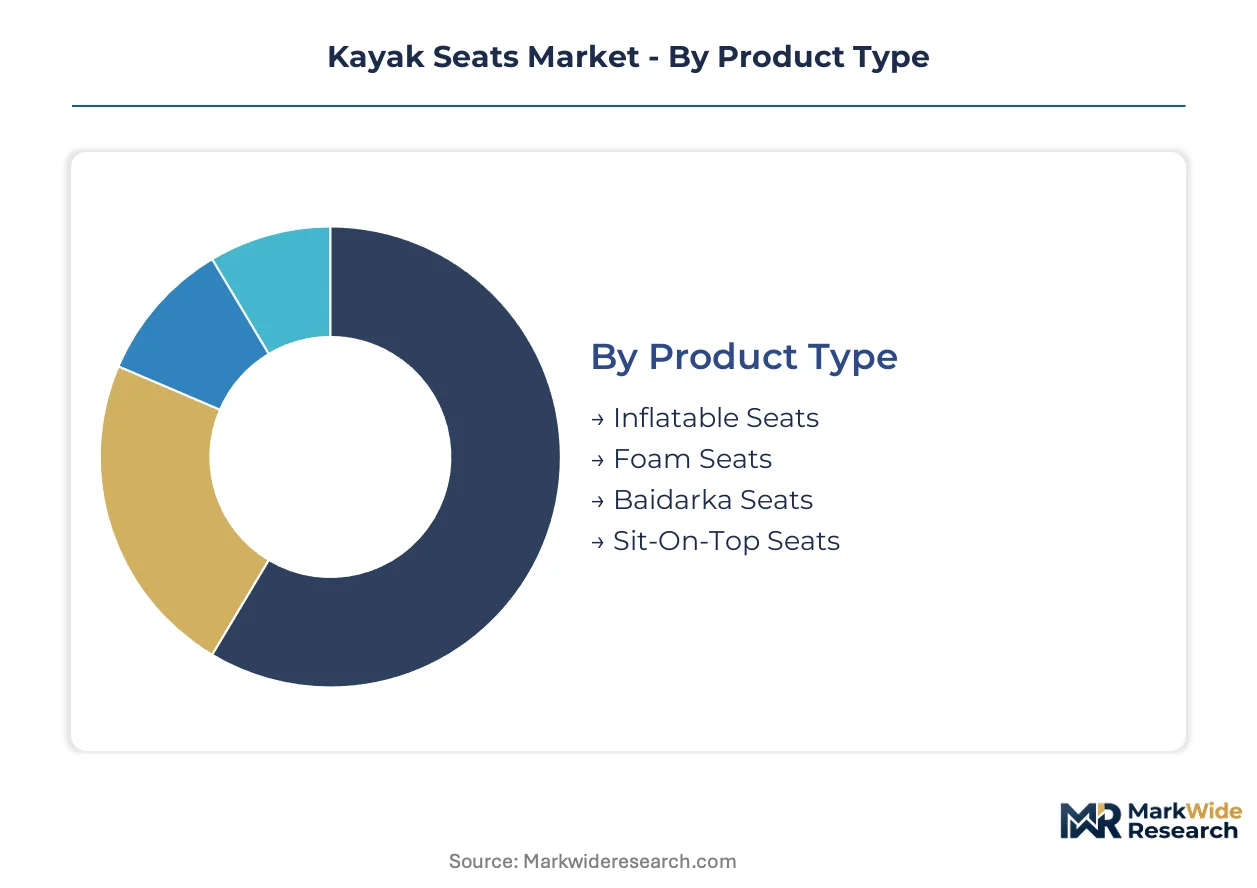
Kayak seat procurement splits sharply between fleet operators seeking durability certification and individual buyers prioritizing ergonomic customization. Material compliance requirements under EPA and REACH frameworks create divergent sourcing patterns across each segment boundary.
Product Type:
EPA material standards and ISO 8098 durability certification create divergent qualification thresholds across seat architectures.
- Foam Seats:Compression-molded foam construction dominates rental fleet procurement due to proven load-bearing endurance and straightforward replacement economics. United States tour operators along the Gulf Coast specify foam systems for high-rotation commercial use where maintenance downtime directly impacts revenue.
- Sit-On-Top Seats:Elevated backrest geometry and fully waterproof construction address saltwater fishing applications. Coastal recreational users in Florida and California drive specification demand where submersion resistance and drainage channel performance prove essential.
- Inflatable Seats:Air-chamber designs prioritize packability for backcountry expedition segments.
- Baidarka Seats:Traditional frame-and-skin configurations serve heritage craft builders and museum replication projects.
Established volume favors foam configurations; emerging adoption favors sit-on-top architectures.
Material:
REACH phthalate restrictions and evolving EPA thresholds force polymer substitution strategies with uneven supplier readiness.
- Neoprene:Marine-grade laminates deliver thermal insulation and abrasion resistance for professional paddler segments. European tour operators pay material premiums where multi-hour cold-water excursions demand performance justification.
- PVC:Plasticizer-dependent formulations face accelerated reformulation timelines under regulatory pressure. Saltwater fishing seat producers confront the steepest adjustment burden as waterproofing historically relied on restricted chemistries.
- Nylon:Marine-grade woven substrates balance durability against weight for mainstream recreational distribution.
- Polyester:Cost-positioned alternative for entry-level fleet procurement with shorter duty cycles.
Margin concentration clusters in neoprene laminates; regulatory vulnerability concentrates in legacy PVC supply chains.
Feature:
Ergonomic research convergence and corrosion-resistant hardware advances enable premium positioning in extended-use segments.
- Adjustable Backrest:Articulated support systems with marine-grade hardware capture professional paddler and tour operator specifications. Confluence Outdoor's R&D investment in this architecture demonstrates category leadership.
- Ergonomic Design:Pressure-mapping derived contours target multi-hour excursion comfort. Johnson Outdoors leverages captive foam supply to dominate this specification tier.
- Waterproof:Sealed construction and drainage channel integration essential for sit-on-top saltwater applications.
- Lightweight:AQUADESIGN's marine-grade configurations emphasize gram reduction for European expedition procurement.
Specification authority concentrates in adjustable architectures; fleet procurement prioritizes waterproof reliability.
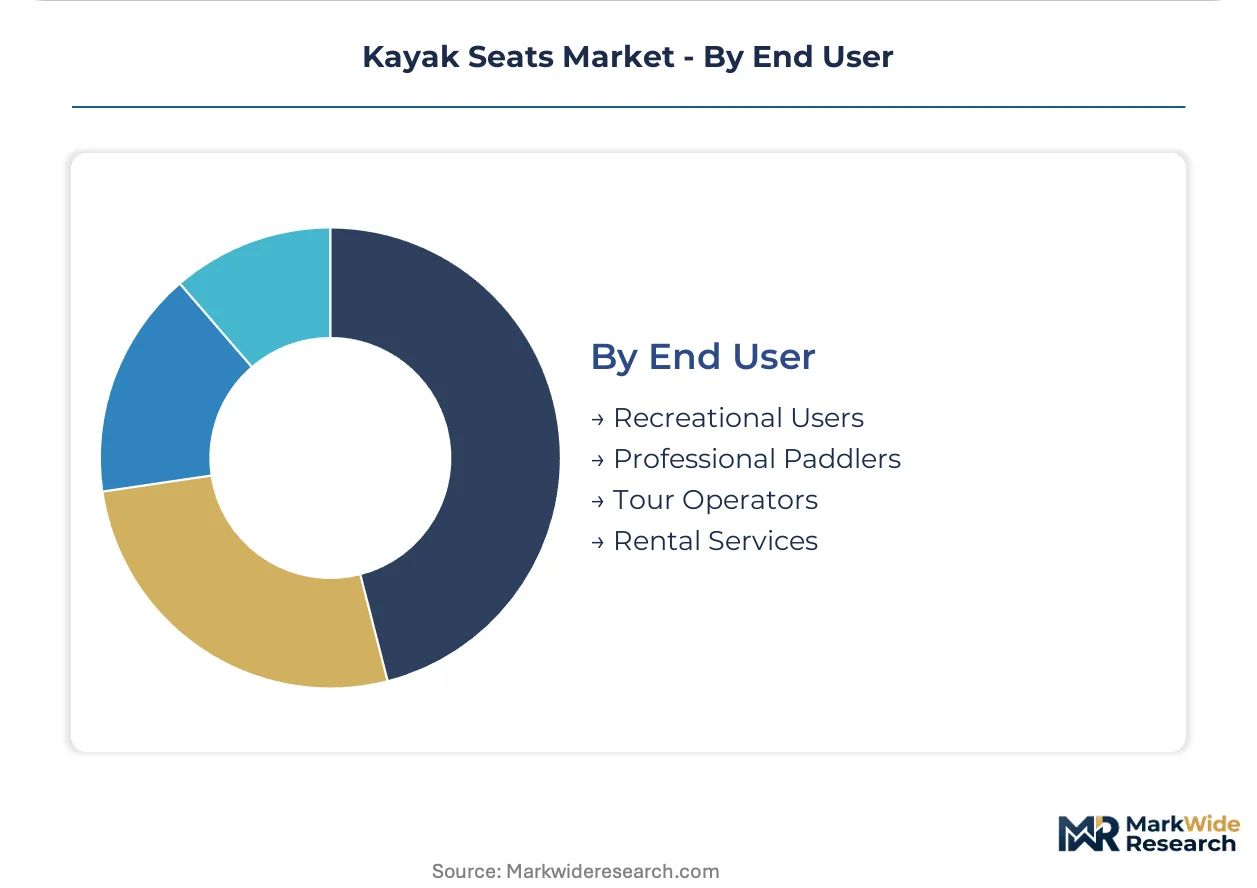
End User:
Procurement consolidation at regional operator level displaces decentralized purchasing through traditional marine retail channels.
- Rental Services:Large fleet operators issue centralized tenders with customized ergonomic requirements. Pacific Northwest tour chains achieve procurement scale that compresses distributor margins while rewarding direct manufacturing relationships.
- Recreational Users:Individual buyers drive bulk demand across North American waterways with preference for cost-efficient replacement cycles. Retail channel fragmentation persists in this segment against fleet-level consolidation.
- Tour Operators:Commercial excursion providers balance durability certification against customer retention metrics in seating refresh decisions.
- Professional Paddlers:Performance-oriented segment justifies material premiums for thermal and abrasion specifications.
Volume concentration favors rental services; margin expansion favors professional paddler specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA material standards and ISO 8098 durability certification are redirecting procurement flows toward jurisdictions with established testing infrastructure and reformulation capabilities. Fleet operators and recreational distributors now prioritize supply routes that can demonstrate regulatory pre-qualification.
United States
Gulf Coast tour operators and Pacific Northwest rental chains are driving fleet refresh demand with centralized procurement tenders. EPA foam formulation standards and PVC plasticizer thresholds compel domestic manufacturers to maintain dual-formulation capabilities. Florida and California coastal clusters concentrate saltwater fishing seat specifications where waterproof construction commands premium positioning.
Germany
REACH phthalate restrictions are accelerating bio-based plasticizer substitution across marine polymer supply chains. ECHA compliance deadlines force distributors to pre-qualify alternative foam formulations before legacy inventory strands. Bavaria and North Rhine-Westphalia host the densest concentration of recreational craft testing laboratories serving Central European distribution.
France
European tour operator procurement cycles favor lightweight marine-grade configurations for multi-hour excursion segments. ANSM oversight of material safety declarations adds documentation burden to import channels. The Brittany and Provence-Alpes-Côte d'Azur coastlines anchor domestic demand for adjustable backrest architectures in commercial paddling operations.
Canada
Cold-water recreational adoption sustains demand for thermal insulation specifications in professional paddler segments. Health Canada material safety guidelines align with evolving EPA thresholds, simplifying cross-border formulation strategies. British Columbia and Ontario waterways concentrate fleet operator scale sufficient to support direct manufacturing relationships.
Australia
TGA-aligned material safety frameworks govern import clearance for marine polymer components. Coastal recreational users in Queensland and New South Wales drive sit-on-top adoption for saltwater fishing applications. Sydney and Melbourne distribution hubs are consolidating specification authority previously held by decentralized marine retailers.
Kayak Seats Market Competitive Landscape
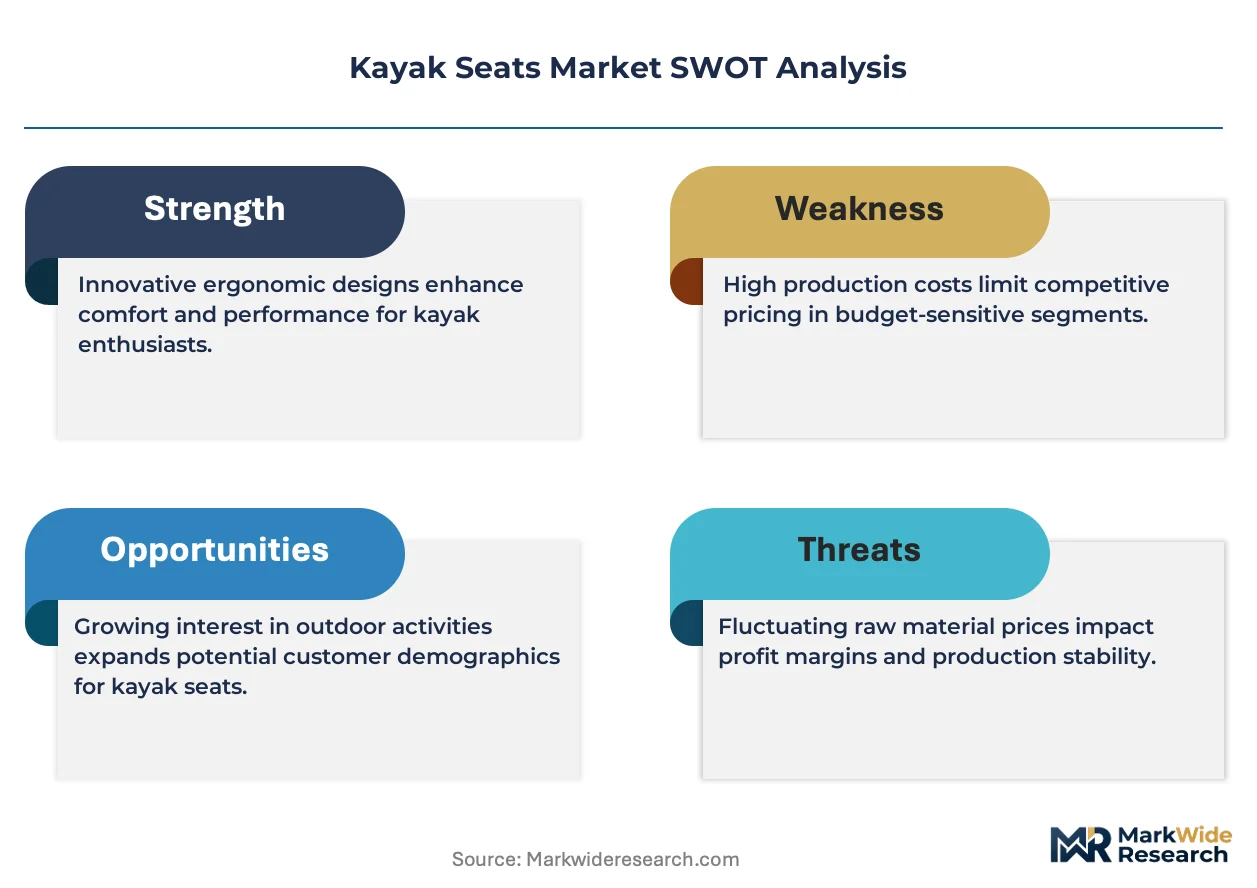
Player mix skews toward vertically integrated outdoor recreation conglomerates and specialized marine seating fabricators. Tiered competitive structure separates ISO 8098-certified suppliers from distributors dependent on third-party manufacturing. Three strategic archetypes dominate: captive foam production specialists, adjustable architecture innovators, and lightweight configuration exporters. Capacity expansion and direct-to-rental procurement platform development represent the dominant competitive moves reshaping channel relationships.
Among North American outdoor recreation conglomerates, Johnson Outdoors and Confluence Outdoor occupy positions exemplifying divergent strategic archetypes. Johnson Outdoors represents captive supply chain control over foam formulation and ergonomic design integration. Confluence Outdoor anchors the adjustable backrest architecture specialization visible in fleet operator specifications. AQUADESIGN, as a European marine seating specialist, exemplifies the lightweight configuration export model serving tour operator procurement cycles across multiple jurisdictions.
| Leading Market Players |
|---|
| Johnson Outdoors |
| Confluence Outdoor |
| AQUADESIGN |
| Nautiraid |
| Rotomod |
| Skwoosh |
| YakGear |
| Surf to Summit |
| GCI Outdoor |
| Others |
Pricing and Supply Chain Analysis
Bio-based plasticizer substitution for legacy phthalates in REACH-compliant foam formulations is redrawing supplier geography across European distribution channels while compressing margin structures for mid-tier manufacturers unable to absorb reformulation costs. This input transition simultaneously elevates pricing power for qualified polymer processors in Germany and Belgium while stranding pre-compliant inventory in distributor warehouses.
Pricing Analysis
Cost-plus contracts indexed to petrochemical feedstock benchmarks dominate procurement between Asian foam processors and European distributors, with quarterly adjustments passing through crude-linked volatility. Price differentiation hinges on ISO 8098 certification tier and volume scale, with certified suppliers commanding premium positioning over uncertified competitors. Pricing pressure stems from REACH compliance deadlines accelerating legacy inventory liquidation. Rental services exhibit highest price sensitivity due to fleet-scale procurement volumes, while professional paddlers show lowest sensitivity where thermal performance justifies material premiums.
Supply Chain Analysis
Eight-to-fourteen-month certification lead times for ISO 8098 durability testing have compressed safety stock buffers across European distributor networks, forcing just-in-sequence coordination with polymer processors. Supply concentrates in China, South Korea, and Germany for marine-grade neoprene and compression-molded foam substrates. Raw material dependencies include chloroprene rubber monomers, polyether polyols, and corrosion-resistant aluminum hardware. Single-source vulnerability pervades REACH-compliant foam formulations where qualified European processors remain limited. Distribution runs through direct-to-rental procurement platforms that displace traditional marine retail channels for fleet-scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation along the United States Gulf Coast and Pacific Northwest has shifted buyer power toward centralized tender specifications, fragmenting distributor influence while rewarding direct manufacturing relationships.
For Market Incumbents: Shield market position by accelerating captive foam formulation capabilities ahead of EPA plasticizer threshold tightening, and secure ISO 8098 pre-certification for adjustable backrest architectures before compliance deadlines eliminate competitor inventory. Vertical integration into polymer processing insulates margin structures from petrochemical index volatility. For New Entrants and Emerging Players: Anchor in modular compression-molded foam component systems serving Pacific Northwest tour operator refresh programs, where field-level cushion replacement reduces per-unit costs versus full-seat disposal. Target saltwater fishing sit-on-top configurations in Florida and California coastal clusters where waterproof construction specifications remain underserved by legacy PVC-dependent suppliers. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors reformulation-capable specialists with established testing infrastructure over distributors dependent on third-party manufacturing. Long-term viability centers on polymer science capabilities and direct fleet relationships rather than channel intermediation. Watch REACH compliance deadline adherence as the inflection signal separating stranded inventory holders from qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Investment | Bio-based plasticizer pre-qualification secures European market access before ECHA deadlines strand legacy inventory. |
| Direct-to-Rental Platform Development | Digital procurement channels capture Gulf Coast fleet volume previously flowing through marine retail distributors. |
| ISO 8098 Certification Acceleration | Durability testing pre-completion enables specification eligibility for Pacific Northwest operator tenders. |
| Modular Component Architecture Launch | Interchangeable density zones decompose replacement economics for tour operator field-level maintenance programs. |
| Adjustable Backrest R&D Expansion | Ergonomic hardware convergence captures professional paddler premiums in multi-hour excursion segments. |
Research Methodology
Desk research of marine polymer trade databases, EPA regulatory filings, and ECHA restriction timelines preceded structured interviews with foam formulation chemists, fleet procurement directors, and marine distribution channel managers. Primary fieldwork captured specification requirements from tour operators in Washington, Oregon, Florida, and California alongside validation from European tour operators in Brittany and Provence-Alpes-Côte d'Azur. Secondary sources included customs records for neoprene and PVC laminate imports, SEC filings from outdoor recreation conglomerates, and ISO certification registry data. Bottom-up segment sizing triangulated against top-down market value estimates.
Variance decomposition across material substitution scenarios, regulatory compliance timelines, and fleet refresh cycle assumptions shaped the analytical framework. Segmentation dimensions modeled include seat architecture type, material compliance tier, end-user procurement scale, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections and price trajectory assumptions for compliant versus non-compliant product tiers. Industry-specific inputs incorporated REACH phthalate restriction phase-in schedules and EPA foam formulation standard evolution patterns.
Material uncertainties — petrochemical price volatility, certification testing backlog extensions, and regulatory threshold adjustments — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding substitution timelines and fleet operator consolidation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
Electric Golf Cart Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Malaysia Trailer Market
Recreational Vehicles
Low-Speed Electric Vehicle Market
Recreational Vehicles
Snowmobile Trailer Axle Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
Caravan and Motorhome Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
United States RV Rental Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Leisure Boat Market
Recreational Vehicles
Material Buggy Market