
 Jon Boat Market | 2026-2036
Jon Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Jon Boat Market Analytics
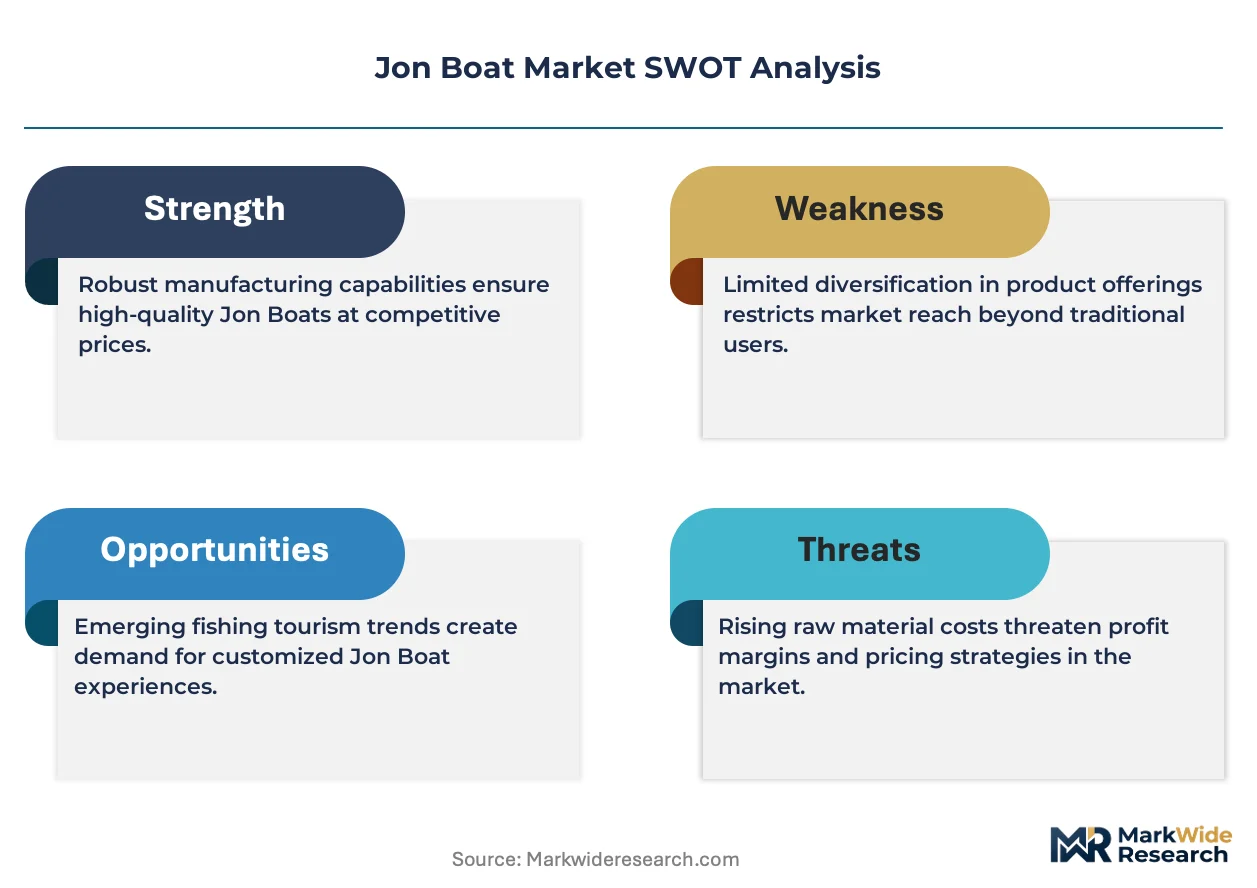
The capital-intensity divergence between high-volume manufacturers and custom builders is collapsing as automated welding and CNC cutting democratize aluminum hull production. Tracker Boats leverages its vertically integrated supply chain to dominate mass-market distribution through exclusive retail partnerships. Lowe Boats sustains competitive pressure through specialized welded-hull construction that commands premium positioning in the 14-16 foot segment. Crestliner anchors its position with R&D intensity focused on proprietary hull-form technologies for shallow-water stability.
A jon boat denotes a flat-bottomed, open-watercraft typically constructed from welded aluminum sheets or rotationally molded polyethylene, designed with a squared or slightly pointed bow to navigate shallow rivers, lakes, and marshes at draft depths under six inches. The aluminum segment leads unit volume due to durability and repairability, while the 12-14 foot size category captures the fastest-growing demand among solo and tandem anglers seeking trailering convenience. Fishing applications command the largest revenue pool, though utility configurations for dock maintenance and property management generate stable replacement cycles with lower price elasticity.
The US Coast Guard enforces flotation standards under 33 CFR 183, while the EPA regulates outboard engine emissions under Clean Air Act Title II, collectively elevating compliance costs for complete boat-motor packages. State wildlife agencies in Arkansas, Tennessee, and Louisiana impose aquatic nuisance species transport rules that mandate hull drainage and inspection protocols, reshaping buyer preferences toward self-bailing designs and removable floor systems. Stakeholders must monitor evolving state-level access fee structures and ramp infrastructure investments that determine addressable participation rates in freshwater angling.
Market Dynamics
Automated aluminum fabrication is collapsing the cost barrier between mass-market and custom hull production, redistributing competitive advantage toward capital-efficient mid-tier manufacturers who can match welded-hull quality at stamped-hull scale.
Growth Catalysts
- EPA Clean Air Act Title II:Emissions standards for outboard motors are accelerating four-stroke engine adoption, expanding addressable demand for complete boat-motor packages in regulated freshwater corridors.
- Rotationally molded polyethylene:Thermoplastic hull construction is penetrating price-sensitive segments through dent resistance and zero-corrosion maintenance profiles that reduce lifetime ownership costs.
- Arkansas-Tennessee-Louisiana corridor:Concentrated recreational angling participation in these three states is sustaining replacement-cycle velocity for 12-16 foot trailered configurations.
Market Restraints
- Aluminum sheet volatility:Primary aluminum input costs fluctuate with energy-intensive smelting economics, compressing margin stability for hull fabricators without captive metal supply.
- 33 CFR 183 flotation mandates:US Coast Guard compliance testing for level flotation adds fixed certification overhead that disproportionately burdens sub-14 foot manufacturers with thinner engineering benches.
- Polyethylene hull repairability:Thermoplastic damage requires specialized welding equipment unavailable at most rural marinas, limiting adoption in remote fishing access zones.
Strategic Opportunities
- Self-bailing hull designs:State aquatic nuisance species transport rules in Louisiana and Tennessee are creating preference pull for integrated drainage systems that eliminate manual bail requirements.
- Dock maintenance utilities:Property management firms and municipal harbor authorities represent an underpenetrated replacement-cycle segment with lower price elasticity than recreational buyers.
- Direct-to-consumer configurators:Digital hull-customization platforms are bypassing traditional dealer networks, capturing margin compression from retail markups in the 14-16 foot premium welded segment.
Industry Challenges
- TIG welding certification scarcity:Skilled aluminum hull welders require specialized aerospace-derived training that regional boatbuilders struggle to source outside established manufacturing clusters.
- State-by-state ramp fee fragmentation:Access cost heterogeneity across Arkansas, Tennessee, and Louisiana wildlife agency jurisdictions complicates national pricing strategies for entry-level package offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jon Boat Market |
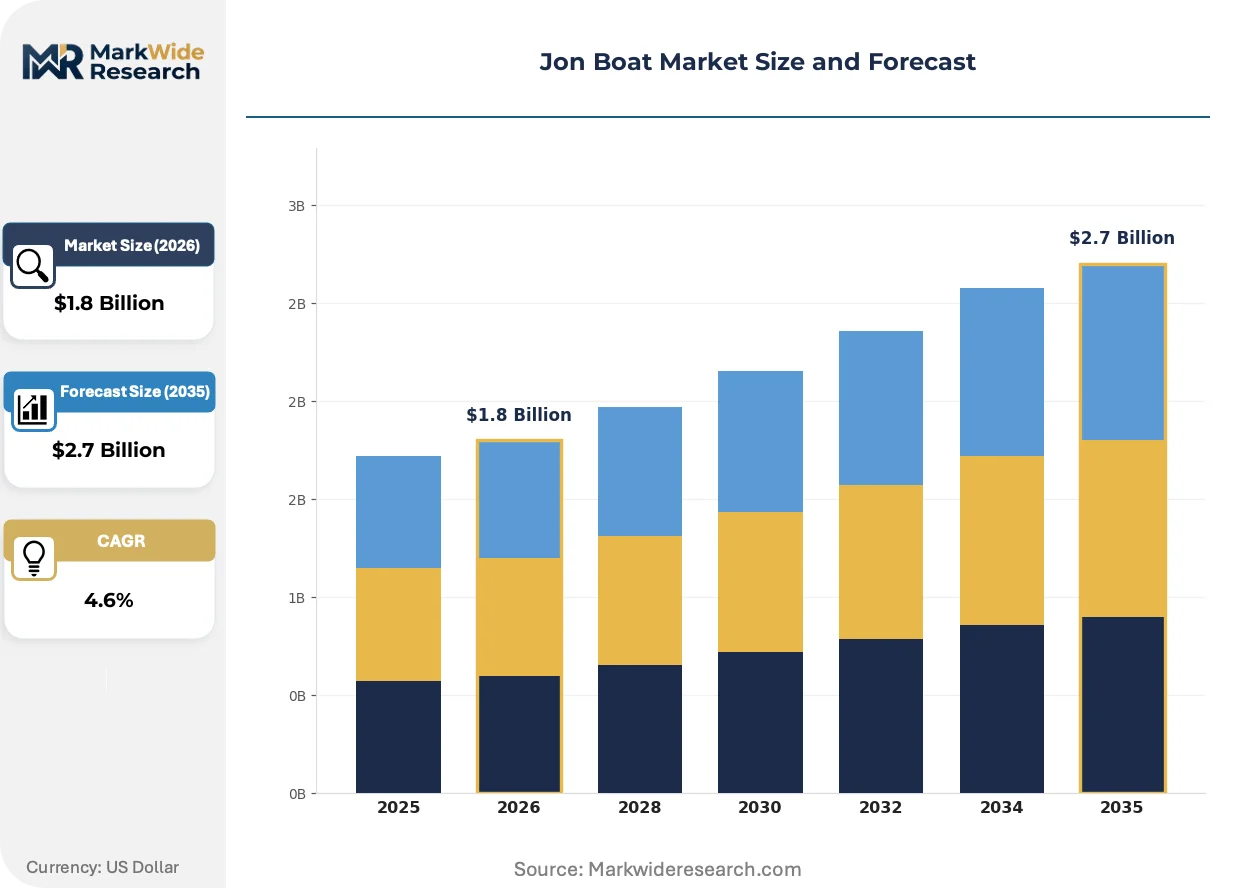
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Aluminum, Fiberglass, Plastic, Hybrid Application: Fishing, Recreation, Utility, Transport Size: 10-12 Feet, 12-14 Feet, 14-16 Feet, 16-18 Feet Capacity: 1-2 Persons, 3-4 Persons, 5-6 Persons, Others |
| Companies Covered | Tracker Boats, Lowe Boats, Crestliner, Lund Boats, SeaArk, War Eagle Boats, Alweld, G3 Boats, Excel Boats, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jon Boat Market Evolving Landscape
Hull fabrication methods and propulsion integration are converging to redefine value-chain positioning, with automation and regulatory compliance emerging as the primary axes of differentiation rather than raw material selection alone.
CNC plasma cutting systems paired with robotic MIG welding are displacing manual hull assembly in mid-volume fabrication shops. Regional manufacturers in the Ozarks and Mississippi Delta are adopting these systems to match Tracker Boats' production economics without equivalent vertical supply chain scale. The technology is displacing the traditional mass-market versus custom-builder segmentation that historically protected premium welded-hull positioning.
EPA enforcement of evaporative emissions standards under Clean Air Act Title II is tightening fuel system requirements for complete boat packages. Outboard motor manufacturers must now certify integral fuel tanks and lines, elevating compliance costs that favor integrated boat-motor bundling over aftermarket engine pairing. The 12-14 foot segment faces the steepest certification burden due to higher unit-volume exposure and thinner per-unit margin cushions.
Recreational angler purchasing is fragmenting across specialized sub-segments defined by species targeting and water body type. Bass-focused buyers in Tennessee reservoirs prioritize shallow-draft stability and trolling motor compatibility, while Arkansas river anglers demand snag-resistant hull geometries. This specialization is compressing the addressable market for generic multi-species configurations and rewarding R&D investment in purpose-built hull forms.
Jon Boat Market Segmentation
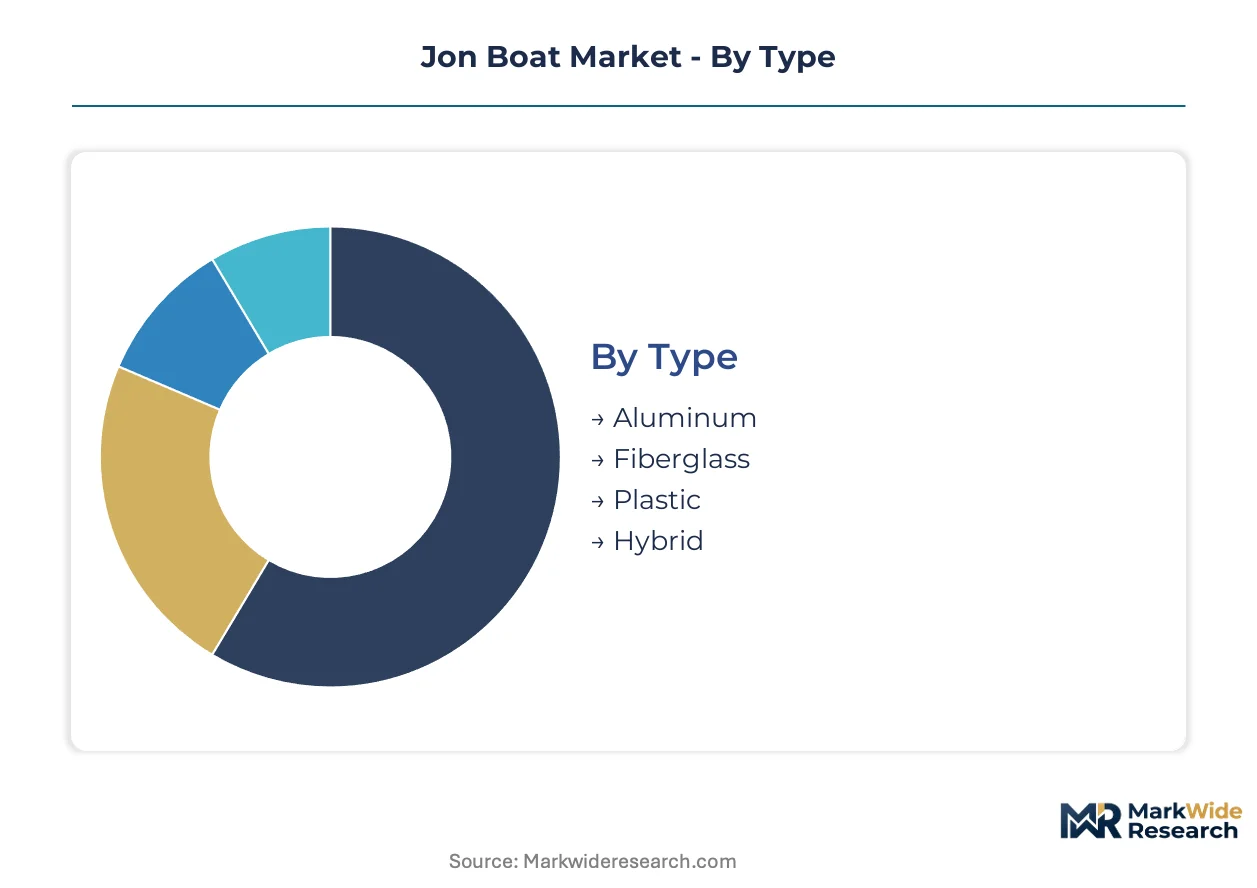
Jon boat manufacturers configure product portfolios across four distinct dimensions that govern procurement patterns, margin profiles, and channel economics. Each segmentation axis carries different implications for hull fabrication methods, distribution partnerships, and regulatory compliance burdens.
Type:
Domestic production concentrates heavily in aluminum fabrication clusters across the Ozarks and Mississippi Delta, while polyethylene hull sourcing draws on rotational molding capacity in the Southeast and Midwest. Export-oriented manufacturers in coastal states favor fiberglass and hybrid configurations for saltwater durability.
- Aluminum:Welded sheet construction dominates freshwater corridors through repairability and hull longevity. Demand clusters in Arkansas, Tennessee, and Louisiana where trailering convenience and shallow-draft navigation are non-negotiable. EPA emissions compliance for complete boat-motor packages reinforces aluminum's position as the default substrate for four-stroke outboard integration.
- Plastic:Rotationally molded polyethylene penetrates price-sensitive entry segments through dent resistance and zero-corrosion maintenance profiles. Rural buyers in remote fishing access zones face repairability constraints—thermoplastic damage requires specialized welding equipment unavailable at most local marinas.
- Fiberglass:Gelcoat finishes command coastal applications where saltwater exposure accelerates aluminum oxidation.
- Hybrid:Composite construction blends aluminum structural members with polymer or fiberglass skin panels for weight reduction.
Aluminum commands the established base. The steepest expansion runs through plastic as automated rotational molding collapses cost barriers.
Application:
Cost tier stratification separates recreational purchasers—who trade on features and brand—from utility buyers who prioritize replacement-cycle predictability and lower price elasticity.
- Fishing:Species-specific hull geometries now dominate R&D investment. Bass-focused configurations emphasize shallow-draft stability and trolling motor compatibility for Tennessee reservoir anglers. River-running variants for Arkansas waterways incorporate snag-resistant bow profiles and reinforced keel strips.
- Utility:Property management firms and municipal harbor authorities generate stable replacement demand for dock maintenance, debris removal, and infrastructure inspection. This segment exhibits lower price elasticity than recreational buyers and favors standardized 14-16 foot welded configurations.
- Recreation:Casual boating and family outings drive seasonal demand spikes tied to state wildlife agency ramp fee structures.
- Transport:Commercial shuttle and guide services require high-duty-cycle hulls with reinforced transoms for extended outboard operation.
Fishing commands the established base. Utility is climbing the fastest as property management outsourcing expands.
Size:
Volume concentration in the 12-14 foot band reflects solo and tandem angler preferences, while margin accretion concentrates in 14-16 foot welded configurations where premium positioning is defensible.
- 12-14 Feet:Trailering convenience and garage storage compatibility drive the steepest demand trajectory among individual anglers. This segment faces the steepest EPA certification burden for complete boat-motor packages due to higher unit-volume exposure and thinner per-unit margin cushions.
- 14-16 Feet:Tandem fishing and light utility work command premium welded-hull positioning. CNC plasma cutting and robotic MIG welding are collapsing the cost barrier between mass-market and custom production in this band.
- 10-12 Feet:Ultra-portable configurations serve bank-access fishing and pond hopping.
- 16-18 Feet:Heavy-duty utility and commercial transport applications require reinforced transoms and higher horsepower ratings.
14-16 Feet commands the established base. 12-14 Feet is gaining share fastest among recreational entrants.
Capacity:
Customer type fragmentation separates individual recreational purchasers from commercial operators and municipal fleet managers with different payload and duty-cycle requirements.
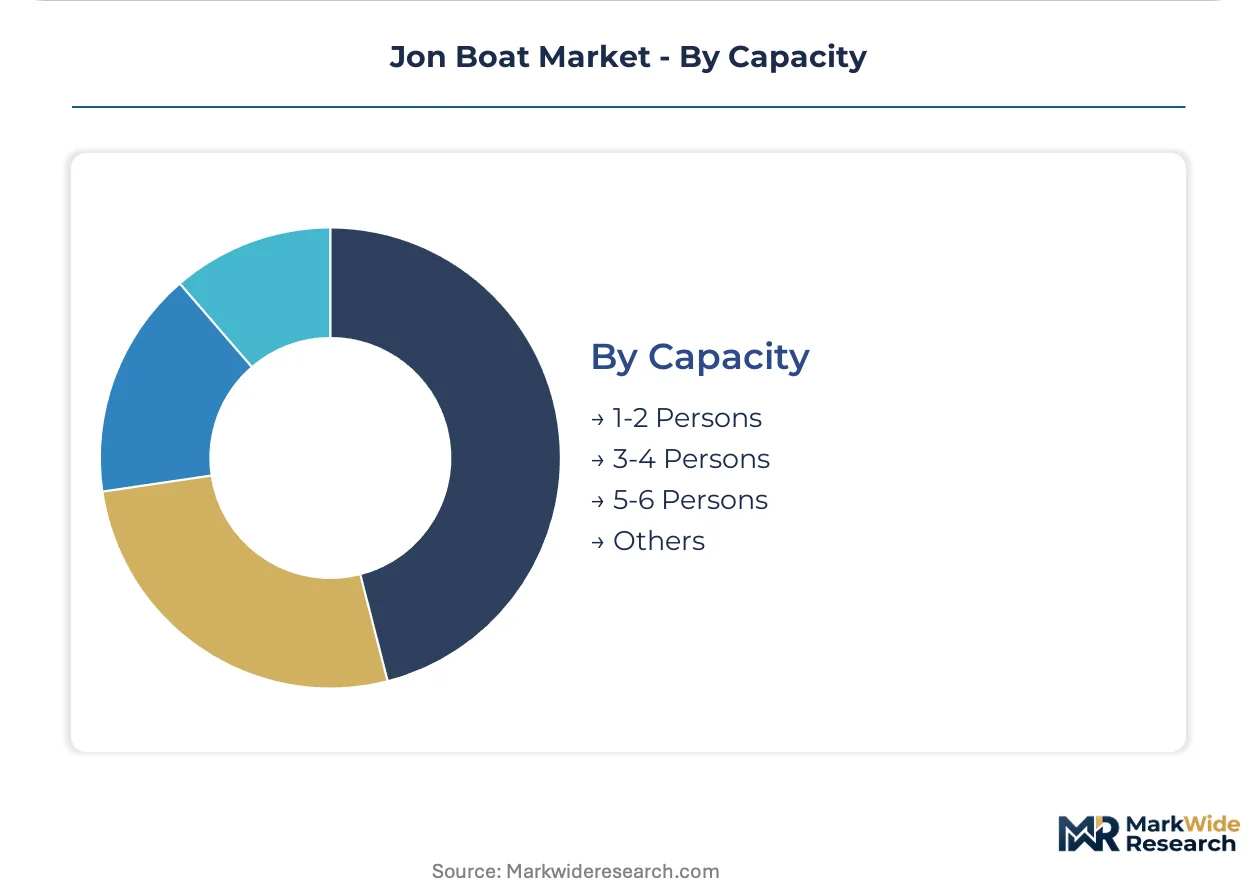
- 1-2 Persons:Solo and tandem angler configurations dominate unit volume through trailering convenience and lower total cost of ownership. Self-bailing hull designs with integrated drainage systems are penetrating this segment in response to Louisiana and Tennessee aquatic nuisance species transport rules.
- 3-4 Persons:Family recreation and light commercial use balance passenger capacity with maneuverability in shallow water.
- 5-6 Persons:Guide services and commercial shuttles require higher freeboard and stability certification.
- Others:Specialized configurations for law enforcement, search and rescue, and research applications.
1-2 Persons commands the established base. 3-4 Persons shows the steepest expansion trajectory as family participation in freshwater angling recovers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the southeastern United States where recreational angling density supports premium welded-hull positioning, while price-sensitive entry segments dominate in peripheral freshwater corridors with lower trailering infrastructure investment.
United States
Recreational angling participation in Arkansas, Tennessee, and Louisiana sustains replacement-cycle velocity for 12-16 foot trailered configurations. EPA Clean Air Act Title II emissions standards for outboard motors elevate compliance costs for complete boat-motor packages. Manufacturing clusters in the Ozarks and Mississippi Delta adopt CNC plasma cutting and robotic MIG welding to match production economics of vertically integrated competitors.
Canada
Freshwater fishing in Ontario and Quebec drives seasonal demand for aluminum hull durability in cold-climate storage conditions. Transport Canada enforces small vessel regulations under the Canada Shipping Act that parallel US Coast Guard flotation standards. Fabrication activity concentrates in southwestern Ontario near Windsor and Sarnia with cross-border supply chain integration into US Midwest aluminum distribution networks.
Mexico
Price-sensitive entry segments in northern border states absorb rotationally molded polyethylene hulls from US manufacturers seeking cost-advantaged production. SEMARNAT environmental regulations govern watercraft emissions in protected ecological zones including the Gulf of California. Assembly operations cluster in Nuevo León and Tamaulipas with logistics access to Texas and Louisiana retail corridors.
Australia
Aluminum jon boat adoption penetrates inland river systems in New South Wales and Queensland where shallow-draft navigation dominates recreational fishing. The Australian Maritime Safety Authority enforces National Standard for Commercial Vessels that influences design specifications for guide and rental fleet operators. Manufacturing presence remains limited with import dependence on US and Southeast Asian hull fabricators.
Brazil
Pantanal wetland fishing and Amazon basin navigation create demand for shallow-draft utility configurations with snag-resistant hull geometries. IBAMA environmental licensing requirements restrict outboard motor specifications in protected riverine ecosystems. Local fabrication remains fragmented with import concentration from US manufacturers serving affluent recreational segments in São Paulo and Rio de Janeiro.
Jon Boat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with automated fabrication specialists commanding premium positioning while vertically integrated mass-market operators capture volume share. The vendor base spans three tiers: large-scale manufacturers with captive retail networks, mid-volume fabricators leveraging robotic welding systems, and regional custom builders serving specialized shallow-water applications. Two dominant competitive moves define current positioning: exclusive distribution partnerships that lock dealer channel access, and backward integration into aluminum sheet supply to buffer raw material volatility.
Within the premium welded-hull tier, Tracker Boats and Lowe Boats anchor mass-market positioning through scale-driven production economics, while Crestliner exemplifies R&D-intensive specialization in proprietary hull-form technologies. SeaArk and War Eagle Boats occupy positions in the mid-volume segment where automated fabrication investments redistribute competitive advantage toward capital-efficient regional manufacturers.
| Leading Market Players |
|---|
| Tracker Boats |
| Lowe Boats |
| Crestliner |
| Lund Boats |
| SeaArk |
| War Eagle Boats |
| Alweld |
| G3 Boats |
| Excel Boats |
| Others |
Value Network & Pricing Analysis
Robotic MIG welding displacing manual hull assembly simultaneously redistributes manufacturing gravity toward Ozarks and Mississippi Delta fabrication clusters and compresses the customization-premium spread that historically separated mass-market stamped hulls from premium welded configurations.
Pricing Analysis
The customization-premium spread between configured-to-order welded hulls and standard stamped configurations narrows as CNC plasma cutting democratizes precision fabrication. Three-tier pricing structure across premium welded, standard stamped, and economy rotationally molded levels stratifies by hull construction method and certification grade. Cost compression in the 12-14 foot segment intensifies because EPA emissions compliance burdens concentrate on high-volume configurations with thinner margin cushions. Recreational anglers in Arkansas and Tennessee exhibit highest price sensitivity, while municipal harbor authorities purchasing utility configurations show lowest elasticity.
Supply Chain Analysis
Inbound logistics costs for primary aluminum sheet from domestic smelters fluctuate with energy-intensive production economics, elevating landed cost volatility for Ozarks and Mississippi Delta fabricators. Hull production draws from aluminum sheet mills in the United States, rotational molding capacity in the Southeast and Midwest, and specialty welding equipment manufacturers in Ohio and Michigan. Single-source vulnerability concentrates in qualified TIG welding labor pools with aerospace-derived certification requirements. Distribution runs through exclusive retail partnerships for mass-market manufacturers and direct-to-consumer digital configurators for premium welded segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: EPA emissions certification and US Coast Guard flotation testing create fixed overhead barriers that protect incumbents with established compliance infrastructure.
For Market Incumbents: Compound dealer network exclusivity through captive retail partnerships that lock channel access against mid-tier automated fabricators. Deepen backward integration into aluminum sheet supply to buffer primary metal volatility threatening margin stability. Prioritize R&D investment in proprietary hull-form technologies for shallow-water stability to defend premium positioning against robotic welding democratization.
For New Entrants and Emerging Players: EPA Clean Air Act Title II certification fast-track for complete boat-motor packages offers entry pathway through pre-certified engine bundling partnerships. White-space concentrates in dock maintenance utility configurations serving property management firms with lower price elasticity and predictable replacement cycles. Target direct-to-consumer digital configurators for 14-16 foot premium welded segments to bypass retail markup compression.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors automated fabrication specialists with capital-efficient mid-volume positioning. Long-term viability across the projection horizon hinges on regulatory compliance infrastructure and captive supply chain control. Acquisition target archetype: regional manufacturers with robotic welding investments and established EPA certification pathways. Signal to watch: state aquatic nuisance species rule expansion driving self-bailing hull design preference.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Welding Deployment | CNC plasma cutting and MIG automation collapses cost barriers between mass-market and custom hull production economics. |
| EPA Certification Investment | Clean Air Act Title II compliance infrastructure protects market position against uncertified aftermarket engine pairing. |
| Self-Bailing Hull Development | Integrated drainage systems capture preference pull from Louisiana and Tennessee aquatic nuisance species transport rules. |
| Direct-to-Consumer Configurator | Digital customization platforms bypass dealer markups and capture margin in premium welded segments. |
| Backward Aluminum Integration | Captive sheet supply buffers energy-intensive smelting volatility compressing fabricator margins. |
Research Methodology
A spread of perspectives from hull fabrication plant managers, recreational angler association directors, state wildlife agency administrators, and marine dealer operators converged on the working assumptions driving demand trajectories. Primary fieldwork combined structured interviews with secondary validation through US Coast Guard certification databases, EPA emissions filings, state wildlife agency ramp fee schedules, and aluminum trade association production statistics. Bottom-up hull shipment aggregation and top-down recreational angling participation rates were triangulated to anchor volume estimates.
Segmentation dimensions modeled include hull material substrate, end-use application, length category, and passenger capacity across the analysis window. CAGRs were derived from regression analysis against freshwater fishing license issuance trends and replacement-cycle velocity in established trailering corridors. Industry-specific forecast inputs incorporated EPA enforcement intensity projections and state-level aquatic invasive species regulatory expansion patterns.
Underlying assumptions cover stable aluminum input cost regimes and sustained recreational angling participation rates, with deviation risk concentrated in energy price volatility affecting smelting economics and state wildlife agency budget cycles determining ramp infrastructure investment. Recalibration cycles align with material shifts in EPA enforcement priorities and state regulatory adoption timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Australia Recreational Vehicle Rental Market
Recreational Vehicles
Recreational Boats Market
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
Malaysia Trailer Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
US Electric UTV and ATV Powertrain Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
Camping Trailer Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Electric Golf Cart Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market