
 Europe Healthcare Big Data Analytics Market | 2026-2036
Europe Healthcare Big Data Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Healthcare Big Data Analytics Market Intelligence
Platform licensing revenue is reshaping competitive economics in the Europe Healthcare Big Data Analytics Market, pulling margin pools away from perpetual software sales toward recurring subscription models. IBM Corporation leverages its Watson Health infrastructure to anchor enterprise contracts across Northern European hospital networks. Oracle Corporation competes through cloud-native analytics stacks that integrate with existing electronic health record ecosystems. Epic Systems Corporation specializes in clinical workflow analytics, dominating ambulatory care settings with embedded decision-support tools.
Healthcare Big Data Analytics encompasses the computational processing of structured and unstructured clinical, operational, and financial datasets exceeding terabyte scale, employing distributed computing architectures to extract actionable intelligence for care delivery optimization. The technology stack spans machine learning algorithms, artificial intelligence inference engines, cloud computing substrates, and data warehousing platforms that aggregate multi-source patient records in HIPAA-aligned and GDPR-compliant environments. Software and solutions segments capture the dominant share of procurement value, while services revenue accelerates fastest as health systems outsource implementation and governance complexity. Predictive analytics applications lead clinical adoption, though operational analytics is displacing legacy business intelligence in hospital administration departments seeking real-time capacity management.
EMA pharmacovigilance guidelines and GDPR data residency rules shape product design requirements, mandating on-premise or EU-sovereign cloud deployments for sensitive patient information. The EU AI Act risk classification framework forces vendors to reengineer diagnostic support algorithms for conformity assessment before market placement. Stakeholders must monitor evolving CE marking obligations for AI-enabled medical decision tools and calibrate partnership strategies between pure-play analytics firms and established health IT incumbents.
Market Dynamics
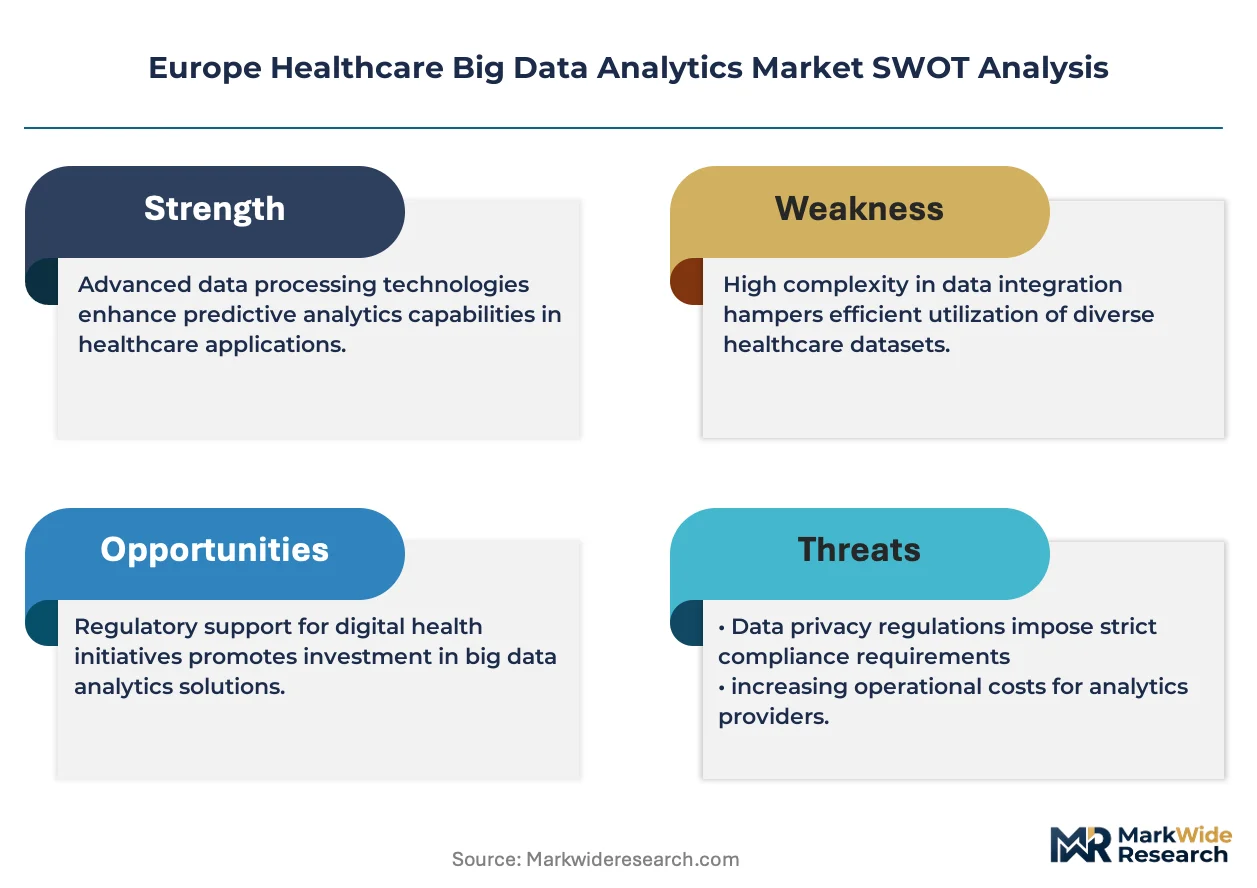
The EU AI Act risk classification framework is forcing vendors to reengineer diagnostic support algorithms for conformity assessment before market placement, compressing product development timelines and elevating compliance costs across European health systems.
Growth Catalysts
- GDPR-aligned data governance:Mandated on-premise or EU-sovereign cloud deployments for sensitive patient information create procurement pull for compliant infrastructure vendors.
- University hospital procurement concentration:Germany's clinical data integration projects command the largest budgets, anchoring demand for enterprise-scale predictive analytics platforms.
- Real-time operational analytics:Hospital administration departments seek capacity management tools that displace legacy business intelligence systems.
Market Restraints
- EMA pharmacovigilance compliance costs:Continuous algorithm validation requirements impose recurring expenditure burdens on vendors serving European markets.
- Cloud infrastructure vendor concentration:Reliance on hyperscale providers for EU-sovereign deployments creates supply-side dependency risks.
- Interoperability technical limitations:Fragmented electronic health record ecosystems impede seamless data aggregation across hospital networks.
Strategic Opportunities
- France's regional hospital digitization:Underpenetrated provincial health systems present expansion targets for analytics vendors with localized deployment capabilities.
- Federated learning architectures:Privacy-preserving machine learning techniques enable multi-site collaboration without centralizing raw patient data.
- CE marking pathway streamlining:Harmonized conformity assessment procedures for AI-enabled medical decision tools reduce time-to-market for compliant products.
Industry Challenges
- Clinical informatics talent scarcity:Shortage of professionals bridging healthcare domain expertise and data engineering skills constrains implementation velocity.
- Legacy system integration complexity:Proprietary data formats in entrenched hospital IT estates demand costly middleware development for analytics connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Healthcare Big Data Analytics Market |
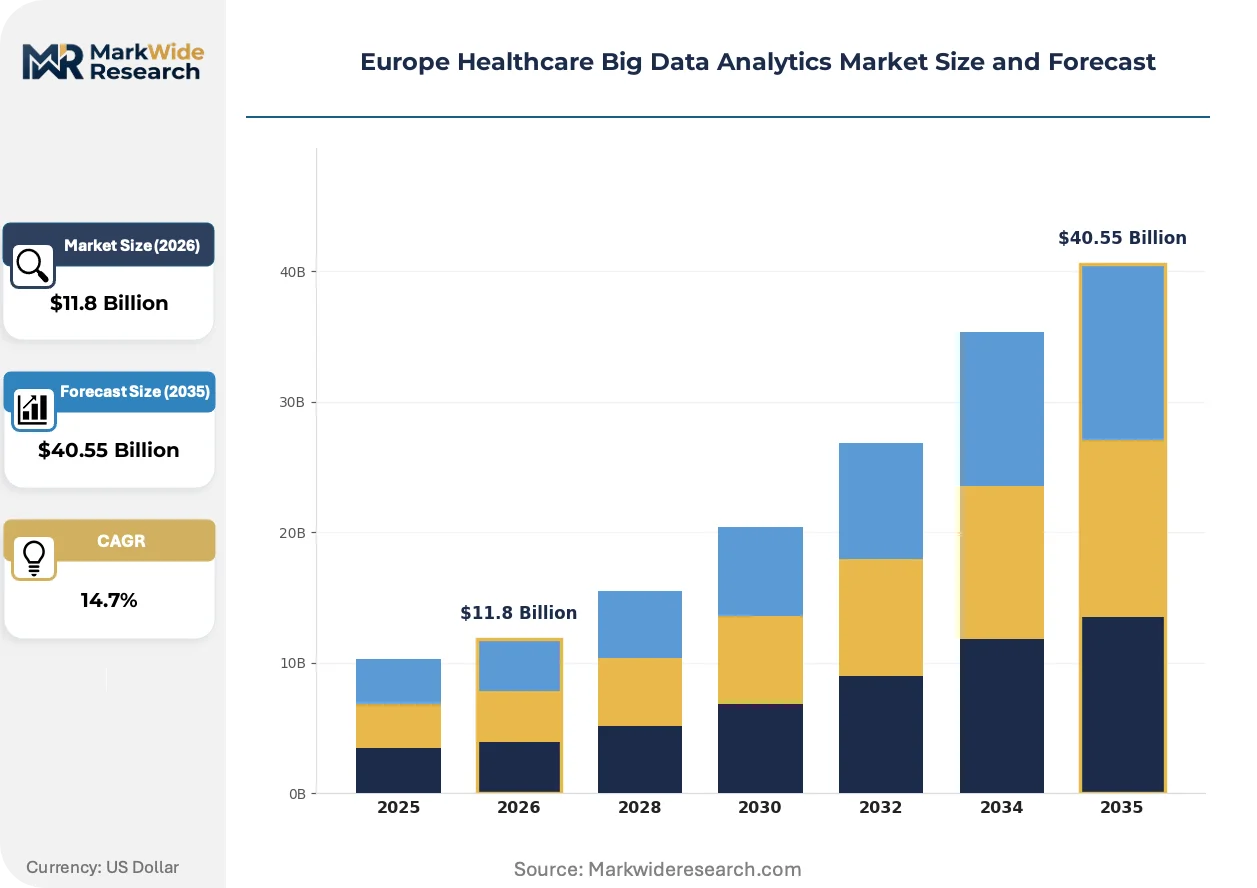
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $40.55 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Tools, Services, Solutions End User: Hospitals, Clinics, Research Institutes, Pharmaceutics Application: Predictive Analytics, Clinical Data Analysis, Financial Analytics, Operational Analytics Technology: Machine Learning, Artificial Intelligence, Cloud Computing, Data Warehousing |
| Companies Covered | McKesson Europe AG, GE HealthCare Technologies, Inc., IBM Corporation, Cognizant Technology Solutions Corporation, Epic Systems Corporation, Oracle Corporation, Optum, Inc., Wipro Ltd., Cerner Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Healthcare Big Data Analytics Market Strategic Shifts & Innovations
Platform economics are restructuring vendor revenue models across European health systems, pulling margin pools from perpetual licenses toward recurring subscriptions that embed ongoing compliance and algorithm retraining services.
Federated analytics architectures are digitizing multi-site clinical research by enabling computation across distributed datasets without raw data movement. Pharmaceutical sponsors and academic medical centers in the Netherlands and Scandinavia are piloting these networks for rare disease cohort analysis. The approach is digitizing regulatory submission pathways by preserving GDPR data residency while accelerating evidence generation.
The EU AI Act's high-risk system obligations are mandating conformity assessment procedures for diagnostic support algorithms before CE marking. Vendors must maintain technical documentation, risk management systems, and human oversight protocols throughout product lifecycles. Germany's notified bodies are experiencing capacity constraints as submission volumes surge ahead of enforcement deadlines.
Subscription-based platform licensing is displacing capital-intensive perpetual software purchases in hospital procurement departments. Finance directors prefer operational expenditure treatment that aligns analytics costs with utilization metrics. This shift is most pronounced in the United Kingdom's NHS trusts, where integrated care system budgets favor predictable recurring payments over lump-sum IT investments.
Europe Healthcare Big Data Analytics Market Segmentation
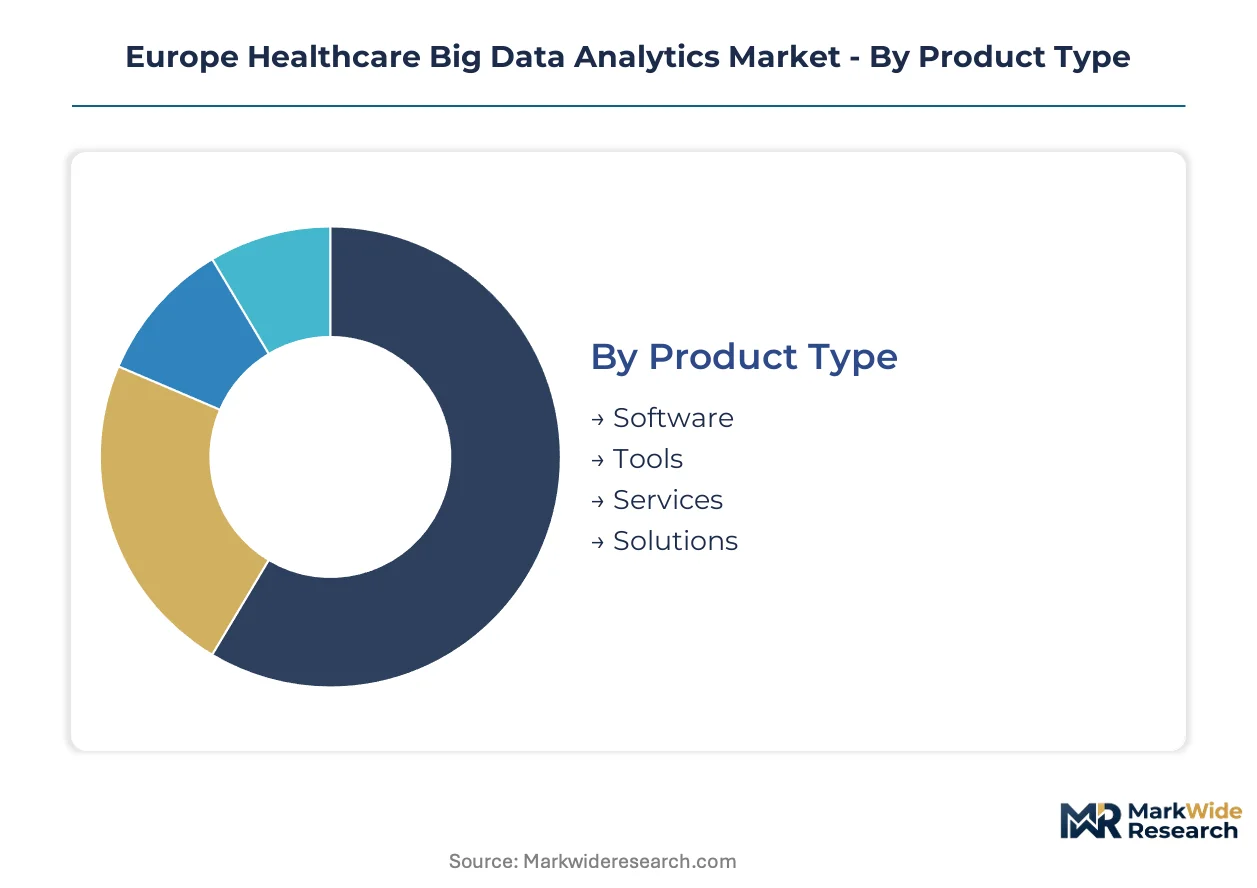
Healthcare analytics procurement in Europe fragments across four distinct dimensions that shape vendor go-to-market strategies and product architecture requirements. Each segmentation axis carries different compliance burdens, pricing dynamics, and integration complexity that determine competitive positioning.
Product Type:
Cost tier differentiation separates capital-intensive perpetual licenses from operational expenditure subscription models across European hospital procurement departments.
- Software:Embedded analytics modules integrate with electronic health record workflows, requiring GDPR-compliant data residency configurations. German university hospital networks anchor demand for enterprise-scale deployments with the largest procurement budgets.
- Tools:Standalone visualization and query platforms enable departmental self-service analytics without central IT dependency. France's regional hospital digitization programs concentrate adoption in underpenetrated provincial systems.
- Services:Implementation, governance, and algorithm retraining contracts accelerate fastest as health systems outsource technical complexity.
- Solutions:Integrated platform bundles combining software, infrastructure, and managed services command premium positioning.
Software holds installed capacity. Services is rotating up the share rankings.
End User:
Customer type determines data sovereignty requirements, interoperability standards, and procurement authority structures across European healthcare delivery organizations.
- Hospitals:Acute care networks deploy predictive analytics for capacity management and clinical decision support, navigating EU AI Act high-risk system obligations for diagnostic algorithms. United Kingdom NHS trusts favor subscription pricing aligned with integrated care system budgets.
- Clinics:Ambulatory settings prioritize embedded workflow analytics with lower compliance overhead than acute care environments.
- Research Institutes:Academic medical centers in the Netherlands and Scandinavia pilot federated learning architectures for multi-site cohort analysis without raw data centralization.
- Pharmaceutics:EMA pharmacovigilance guidelines mandate continuous algorithm validation, imposing recurring expenditure burdens on vendors serving this segment.
Hospitals dominate current procurement volume. Research institutes are expanding fastest.
Application:
Functional use case determines algorithm risk classification under EU AI Act frameworks and corresponding conformity assessment pathways.
- Predictive Analytics:Machine learning models forecast patient deterioration, readmission risk, and disease progression. Germany's clinical data integration projects concentrate demand for enterprise-scale platforms with the steepest expansion trajectory.
- Clinical Data Analysis:Structured and unstructured record processing enables population health management and precision medicine initiatives.
- Financial Analytics:Revenue cycle optimization and value-based care contracting tools address reimbursement complexity.
- Operational Analytics:Real-time capacity management displaces legacy business intelligence in hospital administration departments seeking bed utilization optimization.
Predictive analytics commands premium pricing. Operational analytics is gaining adoption velocity.
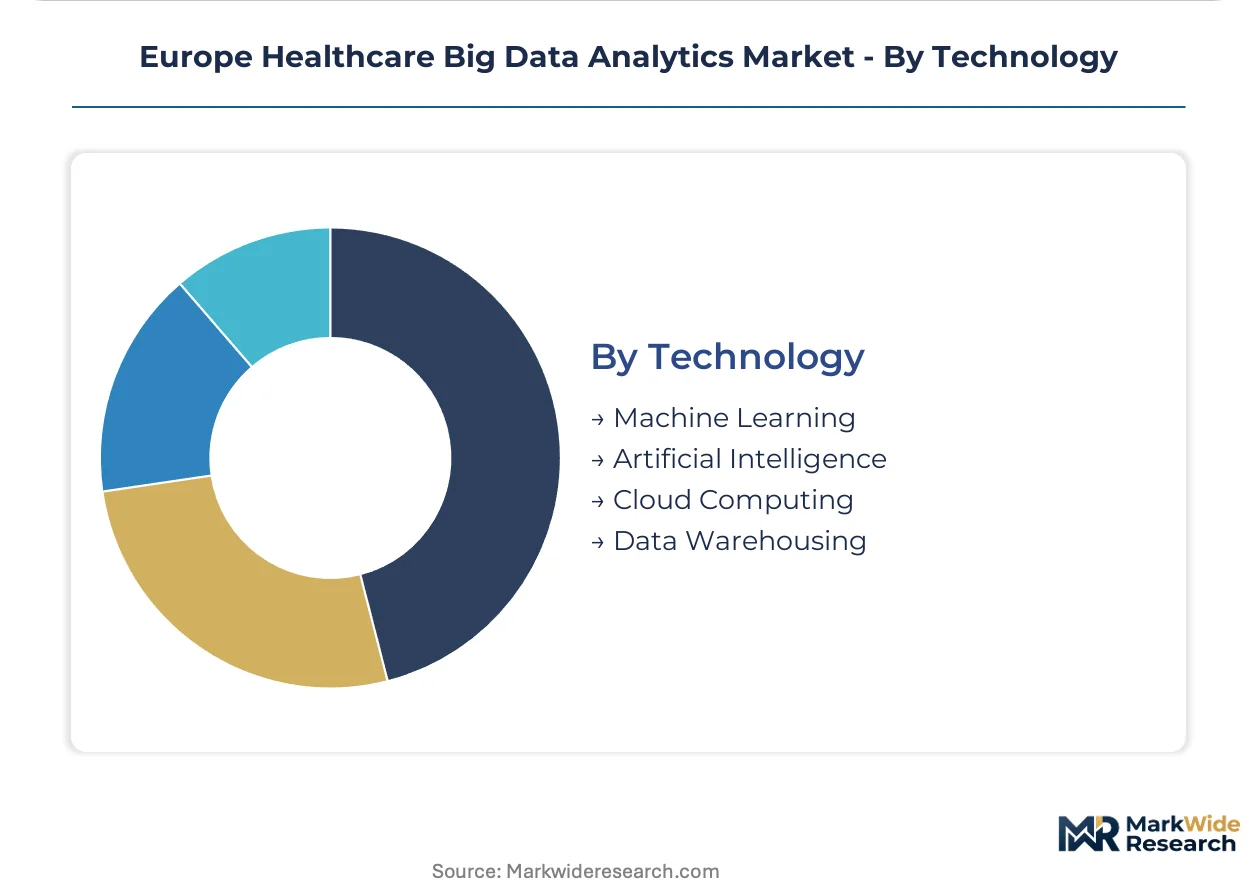
Technology:
Underlying infrastructure stack shapes deployment architecture, data residency compliance, and vendor partnership requirements.
- Machine Learning:Supervised and unsupervised algorithms extract patterns from clinical datasets exceeding terabyte scale, requiring distributed computing substrates.
- Artificial Intelligence:Inference engines for diagnostic support face EU AI Act high-risk system classification, forcing conformity assessment before CE marking.
- Cloud Computing:EU-sovereign cloud deployments satisfy GDPR data residency rules for sensitive patient information, creating procurement pull for compliant infrastructure vendors.
- Data Warehousing:Multi-source aggregation platforms integrate fragmented electronic health record ecosystems across hospital networks.
Cloud computing anchors current infrastructure investment. Artificial intelligence is climbing the regulatory compliance ladder fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor headquarters cluster in Germany, the United Kingdom, and France, with university hospital procurement budgets concentrating demand in specific metropolitan corridors. GDPR data residency rules and EU AI Act compliance timelines reshape deployment patterns across national boundaries.
Germany
University hospital systems in Berlin, Munich, and Heidelberg command the region's largest analytics procurement budgets for clinical data integration projects. The Bundesamt für Sicherheit in der Informationstechnik enforces stringent data localization standards for patient records. Bavaria's medical technology corridor anchors predictive analytics pilot programs at Charité and Ludwig-Maximilians-Universität München.
United Kingdom
NHS trusts favor subscription-based platform licensing aligned with integrated care system operational expenditure frameworks. The Medicines and Healthcare products Regulatory Agency oversees CE marking pathways for AI-enabled diagnostic tools. London's digital health cluster concentrates vendor implementation partnerships for federated learning architectures.
France
Regional hospital digitization programs in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur present expansion targets for localized deployment capabilities. The Agence Nationale de Sécurité du Médicament et des Produits de Santé governs pharmacovigilance algorithm validation requirements. Paris-Saclay's research institutes pilot privacy-preserving multi-site cohort analysis without raw data centralization.
Netherlands
Academic medical centers in Amsterdam and Rotterdam lead federated learning network pilots for rare disease research collaboration. The Autoriteit Persoonsgegevens enforces GDPR interpretation for cross-border health data flows. Eindhoven's health technology ecosystem concentrates cloud-native analytics infrastructure development for EU-sovereign deployments.
Sweden
Stockholm's university hospitals deploy real-time operational analytics for capacity management and bed utilization optimization. The Swedish Medical Products Agency aligns with EMA guidelines for continuous algorithm validation in clinical decision support. The Medicon Valley biotech corridor attracts pharmaceutical analytics vendors serving Nordic pharmacovigilance requirements.
Europe Healthcare Big Data Analytics Market Key Industry Players
Enterprise health IT incumbents and specialized analytics pure-plays split the market across distinct capability vectors. Consolidation pressure intensifies as compliance complexity elevates barriers for mid-tier vendors lacking regulatory infrastructure. Three archetypes dominate: cloud-native platform providers, embedded EHR analytics specialists, and federated learning infrastructure builders. Strategic moves center on partnership formations with notified bodies for EU AI Act conformity assessment and geographic expansion into underpenetrated regional hospital systems.
Within the enterprise platform tier, IBM Corporation and Oracle Corporation occupy positions anchored by existing cloud infrastructure relationships across Northern European hospital networks. Epic Systems Corporation exemplifies the embedded workflow analytics archetype, with Cerner Corporation representing the scale-driven consolidation play. Cognizant Technology Solutions Corporation and Wipro Ltd. sit within the implementation services layer, capturing procurement share as health systems outsource governance complexity.
| Leading Market Players |
|---|
| McKesson Europe AG |
| GE HealthCare Technologies, Inc. |
| IBM Corporation |
| Cognizant Technology Solutions Corporation |
| Epic Systems Corporation |
| Oracle Corporation |
| Optum, Inc. |
| Wipro Ltd. |
| Cerner Corporation |
| Others |
Cost & Logistics Intelligence
EU AI Act conformity assessment bottlenecks constitute the dominant supply-side risk vector, compressing vendor margins while simultaneously widening pricing spreads between CE-marked premium platforms and uncertified economy-tier alternatives. This regulatory chokepoint forces hospital procurement departments toward subscription models that embed ongoing compliance costs, fundamentally restructuring how analytics capabilities flow through European health systems.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European healthcare analytics procurement, separating high-risk diagnostic support platforms requiring notified body validation from lower-tier operational tools. Three-tier pricing stratification anchors on CE marking status, data residency configuration, and algorithm retraining service bundling. Pricing pressure stems from Germany's university hospital procurement concentration, which leverages scale to compress per-seat SaaS rates. United Kingdom NHS trusts exhibit highest price sensitivity due to integrated care system budget constraints, while pharmaceutical sponsors demonstrate lowest sensitivity given pharmacovigilance compliance mandates.
Supply Chain Analysis
Export controls on GPU-accelerated computing hardware limit hyperscaler capacity expansion for EU-sovereign cloud deployments, constraining infrastructure availability for GDPR-compliant analytics platforms. Supply concentration centers on Ireland, the Netherlands, and Germany for EU-sovereign data center capacity, with Taiwan and the United States anchoring specialized AI chip fabrication. Raw material dependencies span advanced semiconductors, high-bandwidth memory modules, and specialized cooling systems. Single-source vulnerability runs through NVIDIA's dominance in training-grade accelerators. Distribution feeds from direct enterprise sales teams into hospital procurement committees and GPO contracts managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European healthcare analytics sits in early-cycle expansion, with federated learning architectures unlocking multi-site collaboration that legacy centralized platforms cannot replicate. EU AI Act enforcement timelines create a narrow window for compliance-first positioning before market access gates slam shut.
For Market Incumbents: Harden regulatory infrastructure through notified body partnerships ahead of CE marking submission surges. Acquire specialized clinical informatics consultancies to address talent scarcity constraining implementation velocity. Vertical integration into algorithm retraining services captures recurring revenue streams as compliance obligations extend across product lifecycles.
For New Entrants and Emerging Players: Establish a beachhead in France's regional hospital digitization programs, where provincial health systems lack embedded vendor relationships. Target federated learning infrastructure for academic medical center networks in the Netherlands and Scandinavia. Pursue partnership-first go-to-market models with established EHR vendors to bypass legacy system integration complexity.
For Investors and Strategic Acquirers: EU AI Act high-risk system obligations reshape the acquisition landscape toward vendors with existing conformity assessment documentation. Five-to-ten-year viability favors pure-play analytics firms with vertical clinical domain depth over horizontal IT services players. Monitor notified body capacity expansion announcements as the critical inflection signal for market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU AI Act compliance unlocks market access for diagnostic support algorithms across German university hospitals. |
| Federated Learning Platform Launch | Privacy-preserving architectures enable GDPR-compliant multi-site research collaboration without raw data centralization. |
| Hospital System Partnership | Embedded EHR integration secures procurement preference within United Kingdom NHS integrated care system budgets. |
| Notified Body Alliance Formation | Conformity assessment capacity constraints in Germany create first-mover advantage for pre-qualified vendor submissions. |
| Algorithm Retraining Service Expansion | Recurring revenue capture aligns with EMA pharmacovigilance continuous validation mandates for pharmaceutical clients. |
Research Approach
A standing panel of hospital procurement directors, clinical informatics officers, regulatory affairs specialists, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EMA pharmacovigilance guidelines, EU AI Act implementation documents, NHS procurement databases, and hospital IT capital expenditure disclosures. Bottom-up triangulation across software licensing data and top-down reconciliation against national health IT spending aggregates anchored market sizing.
Scenario bracketing around EU AI Act enforcement timelines and GDPR data residency interpretation variations shaped the analytical framework across the projection horizon. Segmentation modeling spanned product type, end user category, application function, and deployment technology tier. CAGRs derived from regression analysis against hospital digitization budget trajectories and cloud infrastructure capex cycles, with algorithm regulatory risk classification as a primary forecast input.
Stress conditions across notified body capacity constraints, hyperscaler EU-sovereign expansion delays, and clinical informatics talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and procurement cycle stability. Material shifts in EU AI Act risk classification interpretation or GDPR cross-border data flow rulings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Hospital Management Software Market
Health Data Management
Healthcare Data Collection and Labeling Market
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Global Healthcare Compliance Software Market
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
Europe Healthcare Analytics Market