
 Healthcare Analytics Market | 2026-2036
Healthcare Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Analytics Market Analysis
The capability gap between cloud-native specialists and legacy on-premises vendors is collapsing as enterprise buyers demand hybrid deployment architectures. Oracle Corporation leverages its Cerner acquisition to anchor electronic health record integration pipelines. IQVIA Holdings, Inc. sustains dominance in real-world evidence analytics through proprietary physician-patient linked datasets. Epic Systems Corporation controls a closed-loop ecosystem that competes directly with third-party analytics overlays.
Healthcare analytics encompasses the computational processing of clinical, financial, and operational data to generate actionable intelligence for care delivery optimization, typically involving ETL pipelines, statistical modeling layers, and visualization dashboards with sub-second query response thresholds. Its primary commercial purpose is to reduce cost per episode while improving quality metrics for payers and providers. Predictive analytics commands the largest revenue share as health systems deploy machine learning models for sepsis detection and deterioration indexing. Cloud-based deployment is expanding fastest among mid-size hospital networks that lack capital for on-premises data center expansion. Prescriptive analytics remains the smallest segment but carries the highest margin profile due to scarce actuarial-clinical hybrid talent.
The US FDA, CMS, and ONC collectively shape demand through interoperability mandates, real-world evidence frameworks, and value-based reimbursement rules that require standardized outcome reporting. HIPAA and the 21st Century Cures Act create compliance baselines that filter vendor eligibility and inflate implementation timelines. Stakeholders must monitor how the TEFCA information-blocking provisions reshape data liquidity and whether emerging state-level AI governance creates fragmented certification requirements.
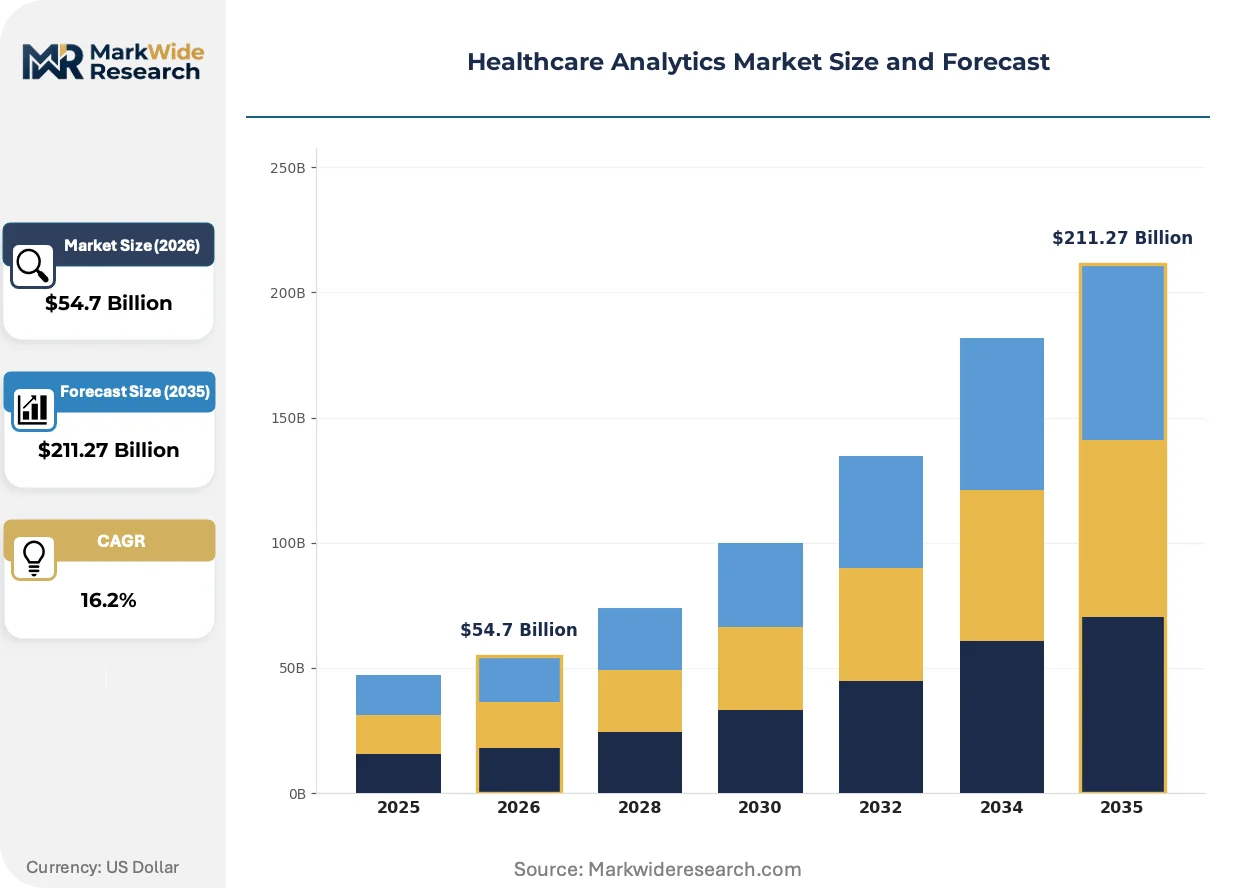
Market Dynamics
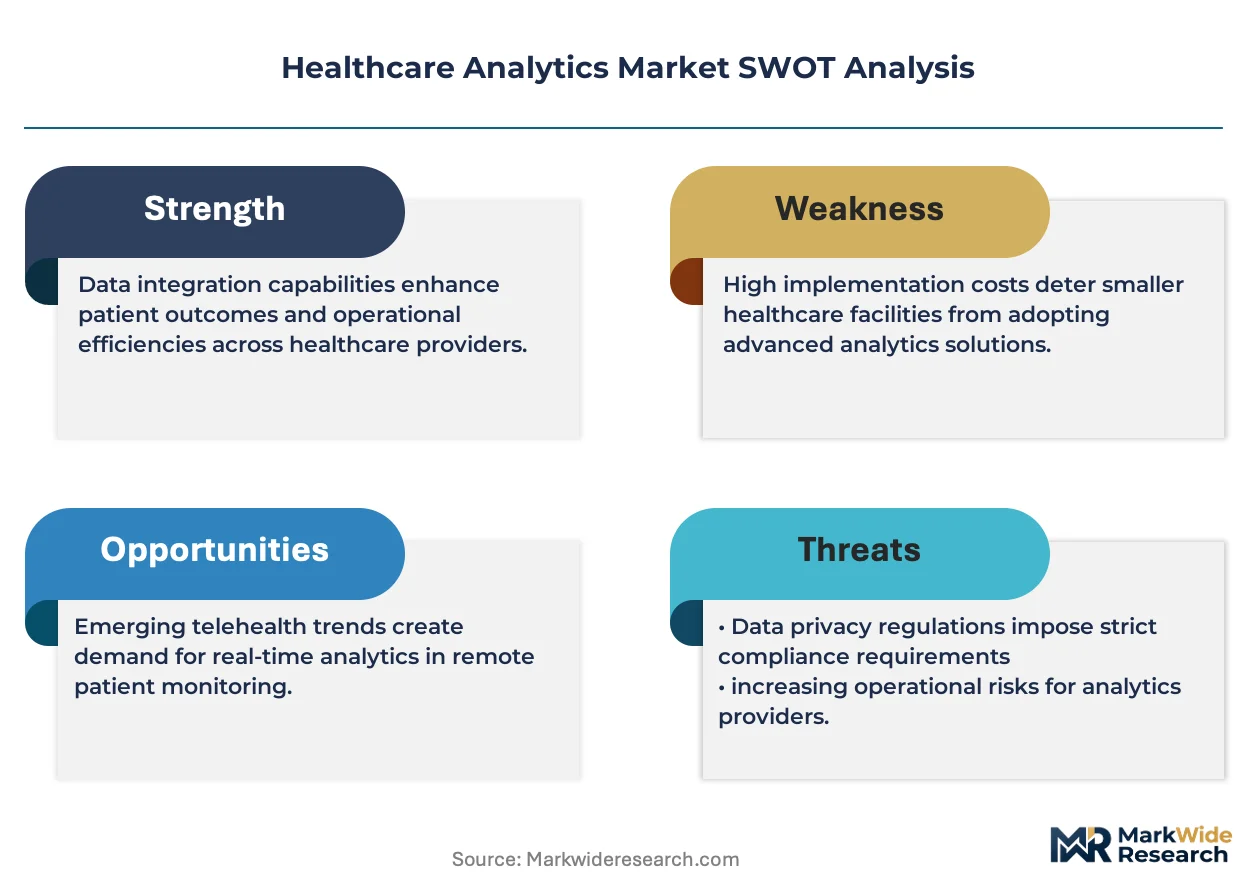
Federal interoperability mandates and value-based care contracts are compressing procurement cycles as hospital systems rush to deploy predictive platforms before reimbursement penalties phase in. The collision between cloud-native architectures and legacy electronic health record infrastructure creates vendor selection friction that shapes competitive outcomes.
Growth Catalysts
- CMS Hospital Readmissions Reduction Program:Penalty structures for excessive readmission rates compel health systems to invest in sepsis detection and deterioration indexing algorithms.
- Cloud infrastructure maturation:Mid-size hospital networks lacking capital for on-premises data center expansion now access enterprise-grade compute through subscription models.
- Real-world evidence frameworks:FDA guidance on regulatory decisions using observational data drives pharmaceutical firms to build proprietary data infrastructure.
Market Restraints
- HIPAA compliance architecture:Technical safeguards for protected health information inflate implementation timelines and require specialized legal-technical hybrid staffing.
- Legacy system entrenchment:Decades of customized electronic health record deployments create data extraction friction that slows analytics pipeline construction.
- Actuarial-clinical talent scarcity:The hybrid skill set combining statistical modeling with clinical workflow knowledge commands compensation premiums that constrain vendor margins.
Strategic Opportunities
- Rural health network penetration:Critical access hospitals in the United States remain underserved by predictive analytics vendors focused on academic medical centers.
- Federated learning architectures:Privacy-preserving machine learning enables multi-institutional model training without centralizing protected health information.
- TEFCA information-blocking provisions:Mandated data liquidity under the 21st Century Cures Act creates openings for interoperability-first platform vendors.
Industry Challenges
- Data normalization complexity:Inconsistent coding standards across health systems require expensive ETL pipeline customization for each deployment.
- Model drift management:Clinical prediction algorithms degrade as patient populations and treatment protocols evolve, demanding continuous retraining infrastructure.
- Physician workflow integration:Alert fatigue from poorly calibrated predictive systems risks user abandonment and wasted capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Analytics Market |
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $211.27 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Descriptive Analytics, Predictive Analytics, Prescriptive Analytics, Data Integration End User: Hospitals, Clinics, Insurance Companies, Pharmaceutical Firms Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Application: Population Health Management, Financial Management, Clinical Analytics, Operational Analytics |
| Companies Covered | Optum, Inc., IQVIA Holdings, Inc., Oracle Corporation, IBM Corporation, McKesson Corporation, Health Catalyst, Inc., Veradigm LLC, SAS Institute, Inc., Epic Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Analytics Market Emerging Trajectories
Machine learning deployment patterns are fragmenting as regulatory pressure and computational economics pull the market in divergent directions. The tension between centralized cloud platforms and edge-computing architectures is reshaping vendor roadmaps and buyer evaluation criteria.
Federated learning infrastructure is bifurcating the market between privacy-preserving collaborative models and traditional centralized training approaches. Academic medical centers in the United States are piloting cross-institutional algorithms for rare disease prediction without sharing raw patient records. This architecture is compressing the competitive advantage of proprietary dataset holders by enabling collective intelligence without data consolidation.
EU AI Act risk classification requirements are forcing healthcare analytics vendors to reengineer quality management systems for high-risk medical device software. The regulation mandates human oversight, accuracy testing, and post-market monitoring that extend development cycles by months. European health systems are delaying procurement decisions until vendor compliance certifications clarify liability allocation.
Subscription-based pricing for predictive analytics modules is displacing perpetual license models as hospital finance departments prioritize operational expenditure classification. Integrated delivery networks in the United States are bundling analytics subscriptions with electronic health record maintenance contracts. This shift concentrates vendor selection power with procurement teams rather than clinical informatics departments.
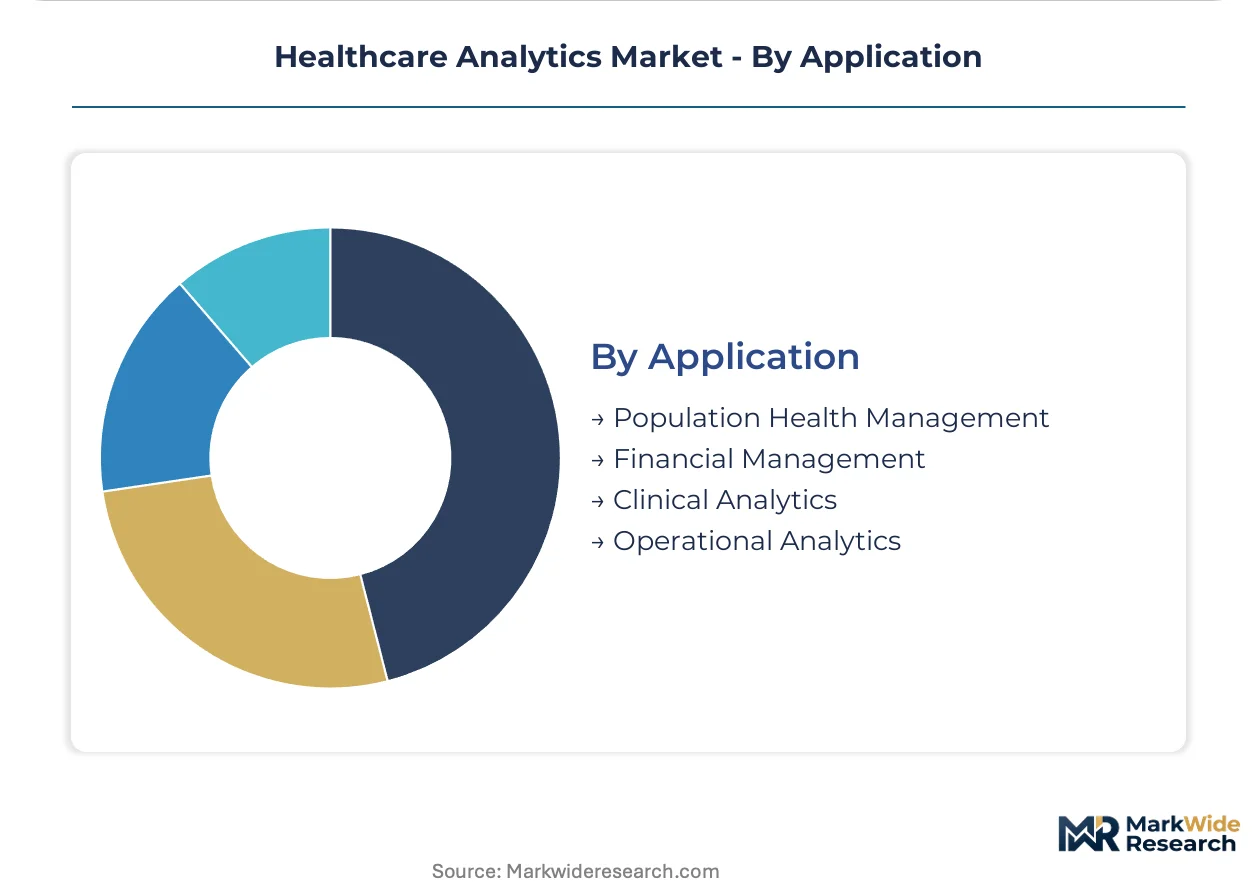
Healthcare Analytics Market Segmentation
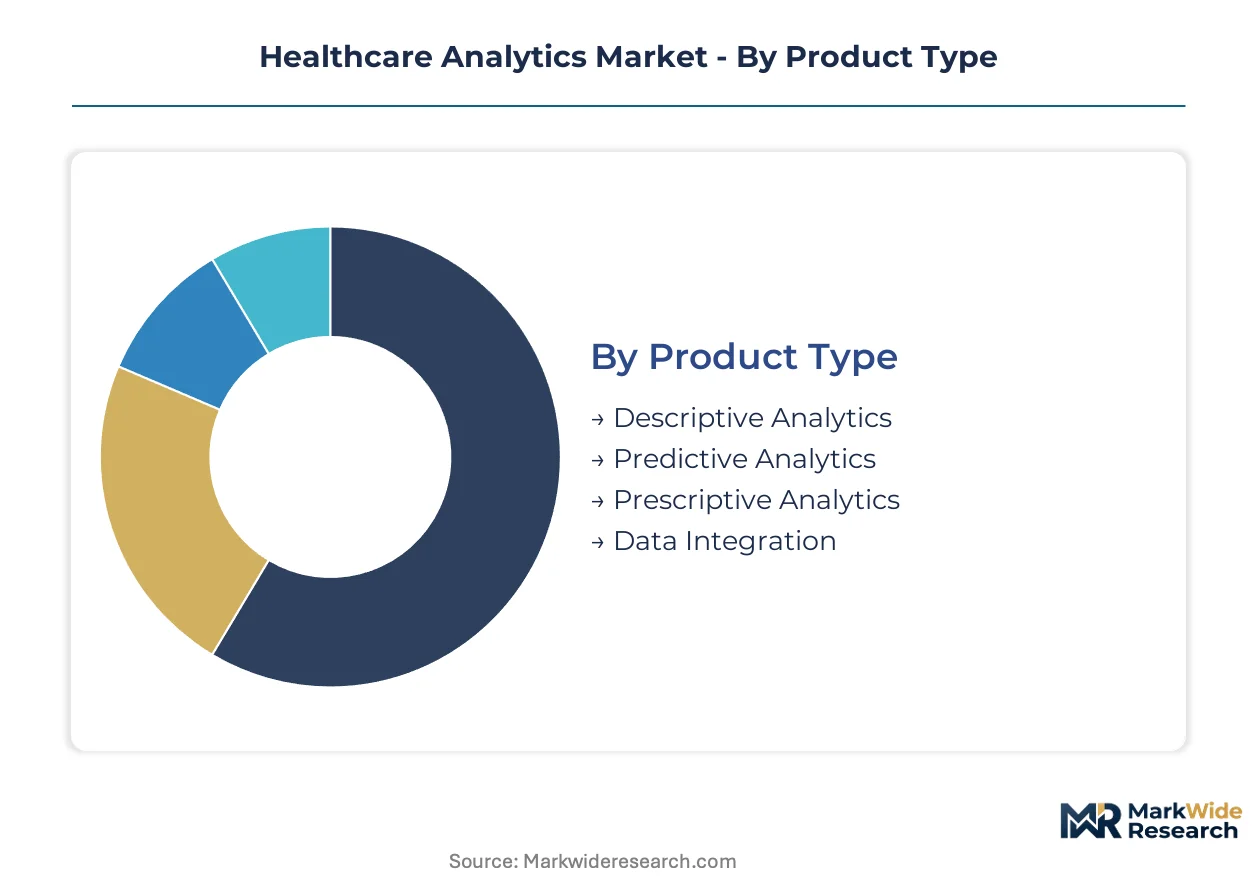
Healthcare analytics vendors structure product portfolios around distinct capability layers and buyer risk tolerances. Each segmentation dimension reveals divergent margin profiles, implementation timelines, and competitive intensity that shape go-to-market strategy.
Product Type:
Predictive and prescriptive modules flow through direct enterprise sales with professional services attachments, while descriptive tools and data integration components increasingly route through cloud marketplaces and EHR-embedded distribution.
- Predictive Analytics:Machine learning models for sepsis detection, readmission risk scoring, and clinical deterioration indexing. Demand concentrates in United States hospital systems facing CMS readmission penalties, with sepsis algorithms commanding the highest implementation urgency.
- Prescriptive Analytics:Optimization engines combining actuarial models with clinical protocols to recommend specific interventions. Academic medical centers in the United States drive procurement, constrained by scarce hybrid talent that inflates deployment costs.
- Descriptive Analytics:Retrospective dashboards and reporting tools for quality metrics and regulatory compliance.
- Data Integration:ETL pipelines and interoperability middleware for normalizing fragmented EHR data.
By volume, descriptive analytics leads due to baseline regulatory reporting requirements. By growth pace, predictive analytics is expanding most quickly as machine learning infrastructure matures.
End User:
Procurement authority varies sharply across buyer types, with hospital IT departments controlling capital budgets while pharmaceutical firms delegate real-world evidence investments to data science divisions with distinct vendor evaluation criteria.
- Hospitals:Integrated delivery networks and academic medical centers deploying enterprise-wide platforms. United States health systems with value-based care contracts show the most aggressive procurement timelines, driven by penalty avoidance.
- Pharmaceutical Firms:Manufacturers building proprietary data infrastructure for FDA real-world evidence submissions. Investment concentrates among oncology and rare disease portfolios where observational data can accelerate regulatory pathways.
- Insurance Companies:Payers applying risk stratification to member populations and provider network management.
- Clinics:Outpatient settings with limited IT staffing requiring simplified deployment models.
Hospital systems generate the largest contract values. Pharmaceutical firms are climbing the fastest as FDA guidance solidifies.
Deployment:
Architecture choices reflect capital availability, data sovereignty requirements, and existing infrastructure entrenchment, with subscription models displacing perpetual licenses across mid-size buyers.
- Cloud-Based:Scalable compute accessed through subscription contracts without data center capital expenditure. United States mid-size hospital networks lacking infrastructure investment capacity represent the fastest-expanding customer cohort.
- Hybrid:Split architectures keeping sensitive patient data on-premises while leveraging cloud analytics engines. Health systems with mixed risk tolerances favor this model.
- On-Premises:Fully controlled environments for organizations with legacy data center investments and stringent security requirements.
- Edge Computing:Distributed processing at point-of-care for low-latency clinical decision support.
Cloud-based deployment leads by new customer acquisition. Hybrid architectures are gaining share fastest as buyers seek risk-calibrated flexibility.
Application:
Use case prioritization follows reimbursement mechanics, with clinical quality metrics commanding investment precedence when tied to penalty structures or bonus payments.
- Clinical Analytics:Patient-level prediction and decision support embedded in provider workflows. United States hospitals facing CMS quality programs concentrate demand here, with sepsis and deterioration detection as primary entry points.
- Population Health Management:Risk stratification and care coordination across attributed patient panels. Accountable care organizations in the United States drive procurement.
- Financial Management:Revenue cycle optimization and cost-per-episode analysis for margin protection.
- Operational Analytics:Scheduling, staffing, and supply chain optimization for efficiency gains.
Clinical analytics leads by revenue concentration. Population health management is expanding most quickly as value-based contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems exhibit the lowest price elasticity, absorbing premium analytics subscriptions to avoid CMS penalties, while mid-size hospital networks in emerging markets delay procurement until cloud infrastructure costs compress further.
United States
Federal interoperability mandates and value-based care contracts accelerate procurement cycles for predictive platforms. The 21st Century Cures Act's information-blocking provisions reshape data liquidity requirements for vendors. Academic medical centers in Boston and the Research Triangle anchor sepsis detection algorithm deployments.
Germany
Hospital digitization funding under the Hospital Future Act drives analytics infrastructure investment. The EU AI Act's high-risk medical device classification forces quality management system reengineering. Industrial clusters in Bavaria and Baden-Württemberg concentrate pharmaceutical real-world evidence platform development.
United Kingdom
NHS England's federated data platform procurement concentrates demand for population health management tools. The Medicines and Healthcare products Regulatory Agency's software medical device guidance extends vendor compliance timelines. London's health tech corridor hosts cross-institutional machine learning pilots for rare disease prediction.
Japan
Ministry of Economy, Trade and Industry subsidies for AI healthcare adoption reduce procurement friction for mid-size hospitals. The Pharmaceuticals and Medical Devices Agency's real-world evidence guidelines reshape pharmaceutical data infrastructure investment. The Kansai region's biocluster drives observational data platform construction for oncology portfolios.
India
National Health Mission digitization targets expand the addressable market for cloud-based clinical decision support. The Central Drugs Standard Control Organization's medical device software regulations filter vendor eligibility. Hyderabad and Bengaluru's health tech corridors concentrate federated learning architecture development for multi-hospital networks.
Healthcare Analytics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where cloud-native specialists compete with legacy infrastructure incumbents. The market fragments across three strategic groupings: electronic health record ecosystem controllers, real-world evidence dataset holders, and interoperability-first platform vendors. M&A activity concentrates on EHR integration pipeline assets, while strategic partnerships between analytics vendors and cloud infrastructure providers reshape deployment economics.
Within the EHR ecosystem controller tier, Epic Systems Corporation and Oracle Corporation occupy positions that compete directly with third-party analytics overlays. IQVIA Holdings, Inc. exemplifies the real-world evidence archetype through proprietary physician-patient linked datasets. These three companies represent the dominant competitive anchors, with each archetype pursuing distinct defensive strategies against cloud-native challengers.
| Leading Market Players |
|---|
| Optum, Inc. |
| IQVIA Holdings, Inc. |
| Oracle Corporation |
| IBM Corporation |
| McKesson Corporation |
| Health Catalyst, Inc. |
| Veradigm LLC |
| SAS Institute, Inc. |
| Epic Systems Corporation |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure scale economies at hyperscale providers compress compute costs for mid-size hospital networks, concentrating supply-side power with AWS, Microsoft Azure, and Google Cloud while establishing subscription pricing floors that legacy on-premises vendors struggle to match. This dynamic reshapes procurement patterns as health systems trade capital expenditure for operational flexibility.
Pricing Analysis
Professional services and multi-year support contracts generate lifetime value exceeding initial software licensing. Three-tier pricing structure across premium, standard, and economy levels segments buyers by integration complexity and data volume. Price differentiation centers on HIPAA compliance certification tier and customization depth. Pricing pressure stems from subscription fatigue among hospital finance departments. Rural critical access hospitals exhibit highest price sensitivity; academic medical centers with value-based care contracts show lowest.
Supply Chain Analysis
Just-in-time provisioning dominates cloud-based deployment, while hybrid architectures require strategic stockpiling of on-premises hardware for data sovereignty. Supply concentrates in the United States for EHR integration pipelines, India for offshore analytics engineering talent, and Ireland for EU data residency compliance. Raw material dependencies include GPU clusters, proprietary physician-patient linked datasets, and FHIR-compliant interoperability middleware. Single-source vulnerability sits with Cerner and Epic API access controls. Distribution runs through direct enterprise sales with professional services attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare analytics is approaching a platform-economics inflection as TEFCA information-blocking provisions transform data liquidity from competitive moat to table stakes. EHR ecosystem controllers face existential pressure to open integration pathways or cede ground to interoperability-first vendors.
For Market Incumbents: Secure EHR integration pipeline assets through targeted acquisition of FHIR-native middleware specialists. Deepen backward integration into cloud infrastructure to defend margin position against hyperscale pricing pressure. Lock in academic medical center relationships with sepsis detection algorithm co-development agreements before federated learning erodes proprietary dataset advantages.
For New Entrants and Emerging Players: Differentiate on federated learning architecture for rural health network penetration. Target critical access hospitals in the United States with simplified deployment models bypassing enterprise sales complexity. Lead with population health management modules for accountable care organizations seeking risk stratification without full platform commitment.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors interoperability-first platform vendors over closed-loop EHR ecosystems. Long-term viability hinges on regulatory certification velocity and physician workflow integration depth. Acquisition targets should demonstrate live deployments with documented alert fatigue reduction. Watch FDA real-world evidence guidance expansion as inflection indicator for pharmaceutical-facing analytics demand.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Platform Development | TEFCA compliance accelerates procurement cycles for interoperability-first vendors. |
| Federated Learning Infrastructure | Privacy-preserving architecture enables multi-hospital model training without data consolidation. |
| Sepsis Detection Algorithm Co-Development | CMS penalty structures create urgency for clinical deterioration indexing partnerships. |
| Real-World Evidence Dataset Acquisition | FDA guidance on observational data drives pharmaceutical infrastructure investment. |
| Hybrid Deployment Architecture Investment | Mid-size hospital networks seek risk-calibrated flexibility between cloud and on-premises. |
Methodological Framework
The analysis maps predictive analytics platforms, prescriptive optimization engines, descriptive dashboards, and data integration middleware, each validated through hospital CIOs, clinical informaticists, pharmaceutical data science directors, and GPO contracts managers. Primary interviews combined with secondary validation against CMS Medicare cost reports, FDA 510(k) clearance databases, hospital procurement records, and hyperscaler healthcare vertical revenue disclosures. Bottom-up deployment counts triangulated against top-down market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, deployment architecture, and application use case, with regional regulatory cluster as an additional healthcare-specific dimension. CAGRs derived from fitted growth curves adjusted for interoperability mandate phase-in schedules and value-based care contract penetration trajectories. Forecast inputs incorporated EHR vendor market share dynamics and cloud infrastructure pricing elasticity.
Material uncertainties — regulatory delay in TEFCA enforcement, state-level AI governance fragmentation, and physician workflow adoption friction — sit outside the modeled envelope. Forecasts reflect assumptions on penalty structure continuity and cloud cost compression trajectories. Revision becomes warranted when federated learning adoption crosses threshold penetration in academic medical center procurement criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
Asia Pacific Healthcare Archiving and Ediscovery Market
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Global Healthcare Compliance Software Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
North America Clinical Data Analytics in Healthcare Market
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
United States Healthcare Big Data Analytics Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
Big Data Healthcare Market
Health Data Management
Global Precision Medicine Software Market
Health Data Management
Health Care Quality Management Software Market
Health Data Management
Point of Care (POC) Data Management Systems Market