
 Hospital Management Software Market | 2026-2036
Hospital Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Management Software Market Outlook
Multi-source procurement among large hospital networks is consolidating around fewer enterprise-grade vendors with full-stack capabilities. Epic Systems Corporation leverages deep integration across clinical and financial workflows to anchor academic medical center loyalty. Cerner Corporation competes through population health analytics and federal contract relationships. Oracle Health sustains cloud infrastructure advantages following its Cerner acquisition, though execution challenges persist.
Hospital management software encompasses integrated digital platforms that orchestrate patient registration, clinical documentation, revenue cycle operations, and resource scheduling across acute care facilities, typically deployed through client-server architectures or SaaS models with HL7 FHIR API connectivity. Electronic Health Records functionality commands the largest installed base and highest switching costs, while Cloud-Based deployment represents the fastest-expanding configuration as hospitals retire on-premise data centers. Billing Systems integration with real-time eligibility verification is emerging as a concentrated margin pool where specialized vendors differentiate from generalist suites.
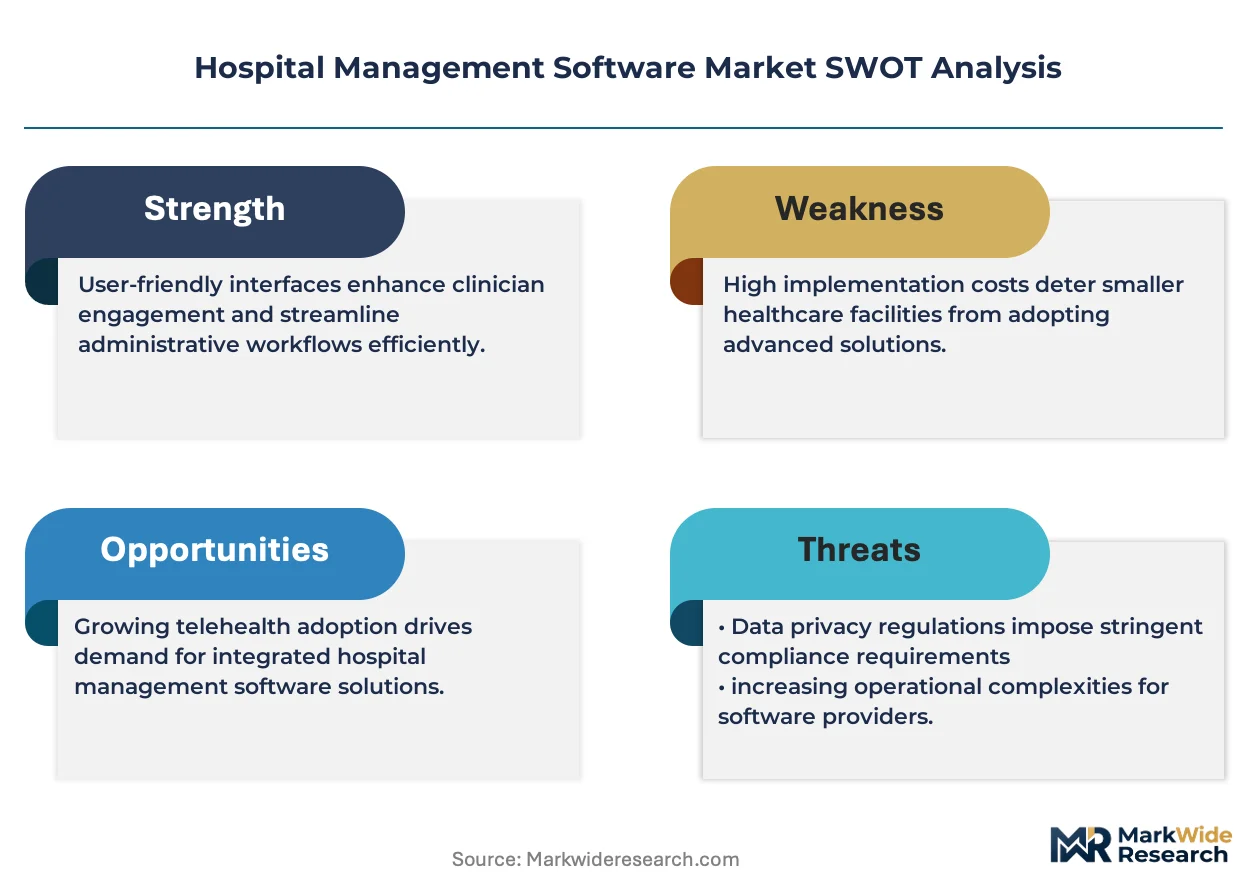
FDA oversight of software-as-medical-device classifications, HIPAA security rule enforcement by the Office for Civil Rights, and ONC certification requirements under the 21st Century Cures Act collectively elevate compliance costs and favor incumbent vendors with dedicated regulatory affairs infrastructure. CMS reimbursement policies increasingly tie quality reporting to EHR interoperability metrics, directly conditioning hospital purchasing decisions. Stakeholders must monitor ONC's forthcoming information blocking enforcement timelines and assess whether hybrid cloud architectures satisfy both latency requirements and data sovereignty obligations.
Market Dynamics
Health system consolidation across the United States is compressing vendor selection cycles as multi-facility networks demand unified data architectures spanning dozens of hospitals. This structural force privileges platforms with proven interoperability and federal certification credentials.
Growth Catalysts
- ONC Information Blocking Enforcement:The Office of the National Coordinator's penalties for data-sharing restrictions are compelling hospitals to replace siloed legacy systems with FHIR-compliant platforms.
- CMS Quality Payment Programs:Medicare reimbursement adjustments tied to digital quality reporting are accelerating EHR modernization in acute care facilities.
- Cloud infrastructure migration:Hospital IT departments are retiring on-premise data centers to reduce capital expenditure and enable remote workforce access.
Market Restraints
- Specialized technical talent scarcity:Health informatics professionals with HL7 FHIR and cybersecurity expertise command premium compensation, inflating implementation costs.
- Prolonged ONC certification timelines:Third-party testing for 21st Century Cures Act compliance extends product launch windows by twelve to eighteen months.
- Legacy system technical debt:Decades-old client-server architectures in community hospitals create integration friction that slows platform consolidation.
Strategic Opportunities
- Rural hospital network consolidation:Federally qualified health centers in underserved counties present white-space demand for subscription-based SaaS models.
- AI-augmented clinical decision support:Machine learning integration with diagnostic imaging workflows opens new revenue streams beyond core EHR licensing.
- Medicaid expansion states:States that expanded coverage under the Affordable Care Act are experiencing patient volume growth that strains existing administrative systems.
Industry Challenges
- Interoperability implementation complexity:Mapping disparate data dictionaries across acquired hospitals consumes eighteen to twenty-four months per integration.
- Cybersecurity certification burden:HITRUST and SOC 2 Type II audits require dedicated compliance staff that mid-tier vendors struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Management Software Market |
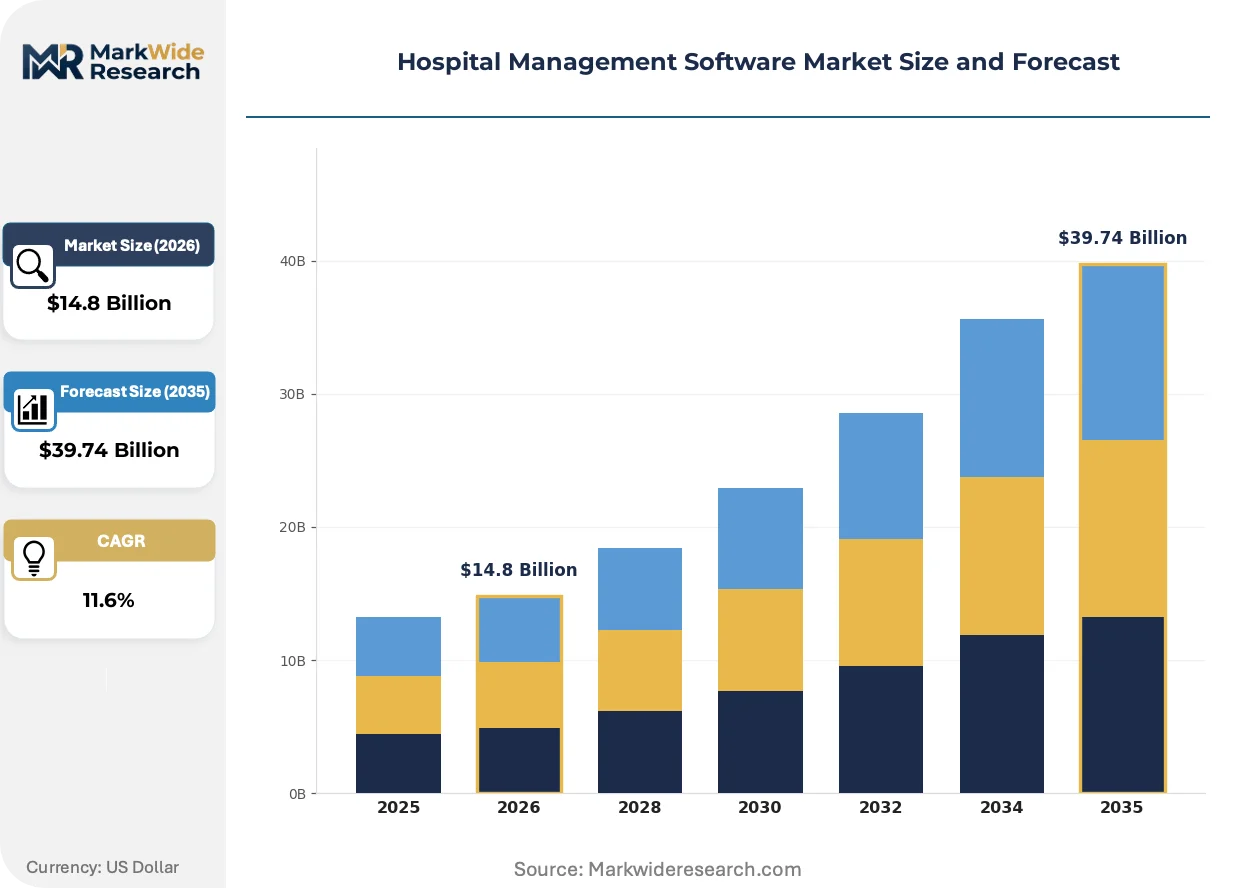
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Health Records, Patient Administration, Billing Systems, Staffing Management Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Solutions End User: Hospitals, Clinics, Nursing Homes, Rehabilitation Centers Functionality: Scheduling, Billing, Reporting, Analytics |
| Companies Covered | Epic Systems Corporation, Oracle Health, Cerner Corporation, Allscripts Healthcare Solutions, Inc., McKesson Corporation, athenahealth, Inc., GE Healthcare, Siemens Healthineers, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Management Software Market Strategic Shifts
Platform architecture decisions are converging around hybrid cloud models that balance latency-sensitive clinical workloads with elastic administrative capacity. Vendors are repositioning around data liquidity rather than functional module breadth.
HL7 FHIR APIs are unifying patient record exchange across previously incompatible vendor ecosystems. Academic medical centers are mandating FHIR-native platforms for new procurement cycles. This standardization is unifying competitive differentiation around analytics depth rather than interface customization.
The 21st Century Cures Act's information blocking provisions are reshaping vendor contractual terms. Prohibition on data export restrictions is forcing incumbents to dismantle proprietary data formats. Physician practices and outpatient clinics are benefiting most from mandated patient data portability.
Subscription pricing for core EHR modules is displacing perpetual license structures that dominated hospital procurement for two decades. Chief financial officers are favoring operating expenditure models that align vendor payments with activated user counts. This shift is most visible in the southeastern United States where private equity-backed hospital systems are standardizing SaaS procurement templates.
Hospital Management Software Market Segmentation
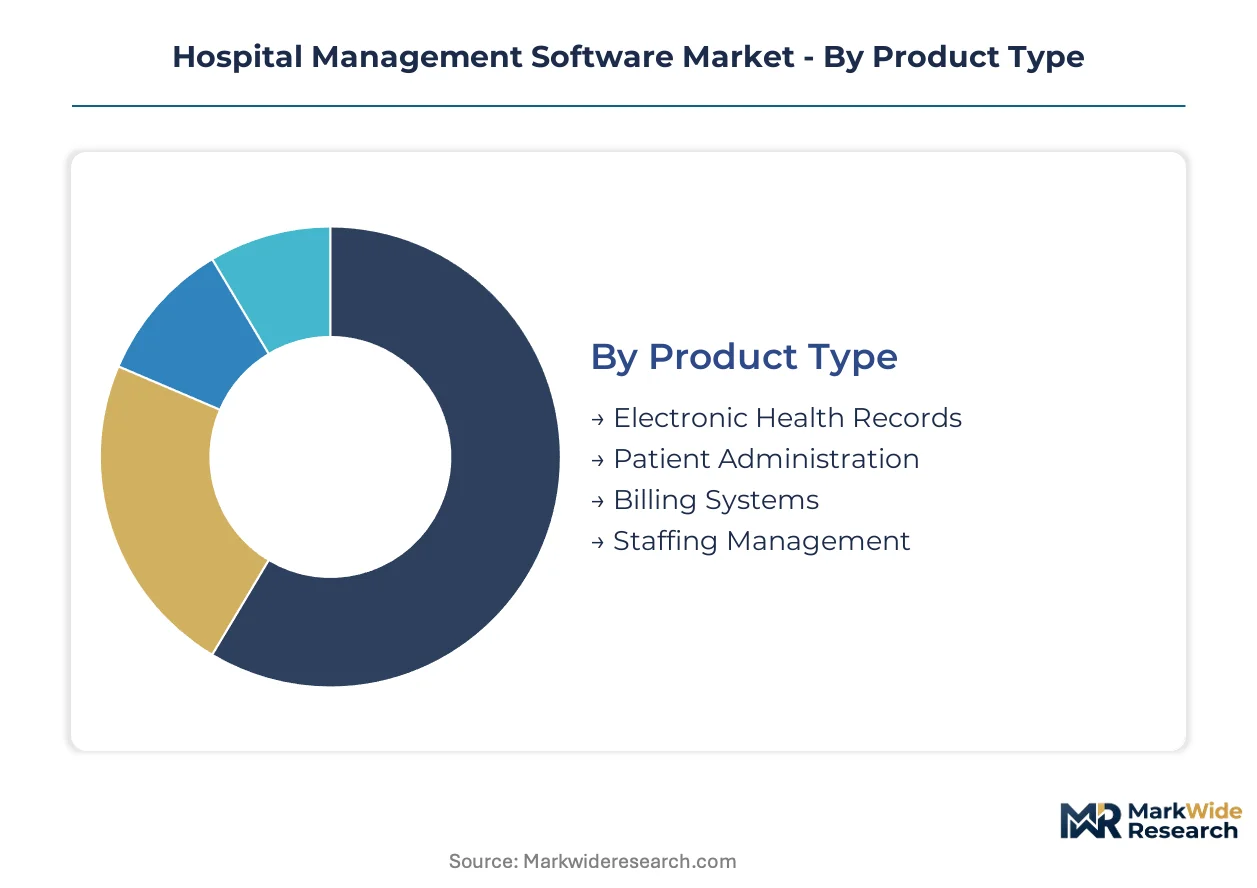
Hospital management software procurement decisions fragment across technical architecture choices, care setting requirements, and financial workflow complexity. Understanding segment-level dynamics reveals where vendor consolidation concentrates and which configurations command premium pricing.
Product Type:
Standalone modules address discrete operational pain points while integrated suites anchor enterprise health system standardization. Integration depth determines switching costs and vendor lock-in intensity.
- Electronic Health Records:Core clinical documentation platforms with CPOE, medication management, and longitudinal patient history tracking. Academic medical centers in the United States prioritize these systems for federal quality reporting compliance, though implementation cycles stretch thirty-six to forty-eight months.
- Billing Systems:Revenue cycle management platforms integrating real-time eligibility verification, claims scrubbing, and denial management. Community hospitals in Medicaid expansion states are prioritizing these modules as patient volume complexity outstrips legacy administrative capacity.
- Patient Administration:Registration, admission, discharge, and transfer coordination systems. These modules typically serve as the integration layer between clinical and financial workflows.
- Staffing Management:Workforce scheduling, credential tracking, and labor cost optimization tools. These solutions gain traction in nursing shortage environments where float pool management directly impacts margin performance.
Volume placements concentrate in Electronic Health Records; the faster expansion belongs to Billing Systems.
Deployment:
Capital expenditure constraints and cybersecurity risk tolerance shape infrastructure decisions across facility types. Cost tier stratification separates subscription-ready community hospitals from latency-sensitive trauma centers.
- Cloud-Based:Multi-tenant SaaS architectures with automatic patching and elastic compute scaling. Private equity-backed hospital systems in the southeastern United States are standardizing these deployments to convert capital expenditure to operating expenditure.
- Hybrid:Mixed architectures placing patient-identifiable data on-premise while administrative workloads run in public cloud. Health systems with acquired rural hospitals favor this model to satisfy both latency requirements and data sovereignty obligations.
- On-Premise:Client-server installations in hospital-owned data centers with dedicated hardware maintenance contracts. These configurations persist where internet connectivity reliability remains problematic.
- Mobile Solutions:Smartphone and tablet-native applications for bedside documentation and remote patient monitoring alerts. Physician adoption rates vary sharply by specialty and age demographic.
Procurement momentum sits with Cloud-Based configurations; Hybrid architectures capture the most complex integration scenarios.
End User:
Care setting acuity and regulatory exposure create divergent functional requirements. Application intensity scales with patient throughput and reimbursement complexity.
- Hospitals:Acute care facilities with emergency departments, surgical suites, and overnight beds. These institutions require full-stack platforms with FDA-regulated clinical decision support and CMS-certified quality reporting.
- Clinics:Outpatient facilities with same-day procedures and ambulatory surgical centers. Simpler workflow patterns allow lighter EHR implementations with emphasis on scheduling density.
- Nursing Homes:Long-term care facilities with medication administration records and minimum data set reporting. Medicaid reimbursement complexity drives specialized vendor relationships.
- Rehabilitation Centers:Post-acute facilities tracking functional improvement metrics and therapy minute documentation. These settings prioritize outcomes measurement for value-based contracting.
Vendor development resources concentrate on Hospitals; Clinics are climbing the fastest as retail health expansion accelerates.
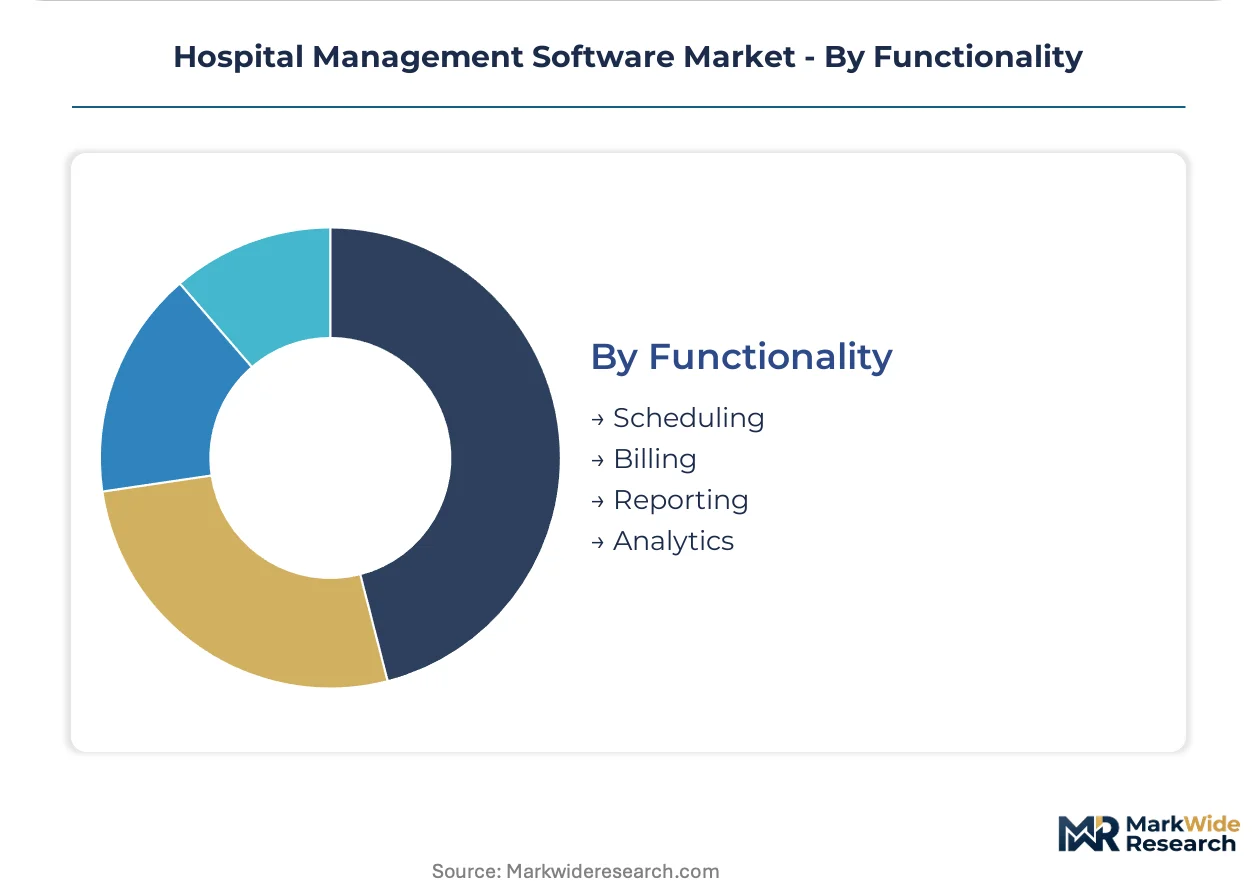
Functionality:
Workflow automation depth separates commodity modules from margin-generating analytics. Maturity curves vary by regulatory certification burden and AI integration readiness.
- Scheduling:Resource allocation systems for operating rooms, imaging equipment, and clinical staff. Optimization algorithms reduce idle capacity in high-fixed-cost environments.
- Billing:Claims generation, submission, and accounts receivable management with payer-specific rule engines. Real-time adjudication capabilities separate premium offerings from basic modules.
- Reporting:Regulatory compliance dashboards for CMS, state health departments, and quality improvement initiatives. These tools automate data extraction from clinical documentation.
- Analytics:Population health stratification, predictive readmission models, and operational efficiency scoring. Academic medical centers deploy these capabilities for research funding and risk contract performance.
Implementation density peaks in Scheduling; Analytics demonstrates the steepest expansion trajectory as value-based reimbursement matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's venture concentration anchors software innovation for hospital management platforms, though deployment scale concentrates in health system-dense metropolitan corridors across multiple continents.
United States
Federal reimbursement incentives and health system consolidation drive procurement velocity. HIPAA interoperability rules and ONC certification requirements under the 21st Century Cures Act elevate compliance barriers for new entrants. The Dallas-Fort Worth metroplex anchors multi-hospital network standardization projects, with private equity-backed systems converting capital expenditure to operating expenditure through SaaS migrations.
Germany
Hospital IT modernization funds from the Hospital Future Act (KHZG) accelerate EHR replacement cycles. The EU AI Act and GDPR impose dual compliance layers on clinical decision support modules. Bavaria's university hospital cluster leads FHIR-native platform adoption, with Munich and Erlangen serving as testbeds for cross-border patient data exchange with neighboring Austria and Switzerland.
United Kingdom
NHS England's federated data platform procurement reshapes vendor selection criteria for integrated care systems. The UK GDPR and NHS Digital's cybersecurity standards create certification bottlenecks. London's academic health science centers concentrate analytics-intensive deployments, while Greater Manchester's devolved health authority experiments with population health contracting models.
India
Ayushman Bharat's health insurance expansion strains administrative capacity in tier-2 and tier-3 cities. The Digital Information Security in Healthcare Act (DISHA) and CDSCO software-as-medical-device classifications elevate data governance requirements. Bengaluru's health-tech startup ecosystem supplies modular SaaS solutions to hospital chains, with Hyderabad's pharmaceutical corridor driving clinical trial management software demand.
Japan
Aging demographics and hospital bed reduction policies force efficiency investments in administrative automation. PMDA's software medical device regulations and METI's healthcare digitization subsidies shape procurement timelines. Tokyo's metropolitan hospital network leads cloud migration pilots, while Osaka's medical device manufacturing cluster generates demand for supply chain-integrated platforms.
Hospital Management Software Market Competitive Environment
Platform consolidation dominates the current landscape as multi-hospital networks compress vendor lists to unified data architectures. The market structure concentrates around three enterprise-grade incumbents with full-stack capabilities, mid-tier specialists in revenue cycle or population health niches, and cloud-native challengers attacking the ambulatory segment. Strategic archetypes separate deep-integration platform vendors from modular best-of-breed players and infrastructure-anchored cloud providers. M&A activity and cloud infrastructure partnerships constitute the dominant competitive moves, with acquisition premiums reflecting installed base switching costs.
Within the enterprise platform tier, Epic Systems Corporation and Oracle Health occupy positions defined by academic medical center loyalty and cloud infrastructure scale respectively. Cerner Corporation exemplifies the federal contract specialist archetype. Among cloud-native challengers, athenahealth, Inc. represents the subscription-first ambulatory model, while McKesson Corporation anchors the pharmaceutical supply chain-integrated segment.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| Cerner Corporation |
| Allscripts Healthcare Solutions, Inc. |
| McKesson Corporation |
| athenahealth, Inc. |
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Others |
Value Chain & Pricing Dynamics
Health informatics labor costs cascade through SaaS subscription tiers as hospitals convert capital expenditure to operating expenditure models. Cloud infrastructure fees from hyperscalers in the United States anchor the upstream cost base, while downstream buyers in Medicaid expansion states face acute price sensitivity against academic medical centers with federal research subsidies.
Pricing Analysis
Implementation and training services bundled into three-year enterprise contracts separate premium Epic deployments from unbundled athenahealth subscriptions where professional services carry separate line-item charges. Price differentiation hinges on ONC certification tier and FHIR API depth, with federal contract relationships commanding measurable premiums. Pricing pressure stems from private equity-backed hospital systems standardizing SaaS procurement templates across southeastern United States networks. Community hospitals in rural counties exhibit highest price sensitivity; academic medical centers with NIH funding demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler cloud infrastructure concentrated in United States East Coast and West Coast data center regions. Software development draws from India, Ireland, and Poland for engineering talent; clinical workflow design rests on United States-based physician informaticists. Supply chain risk centers on H-1B visa policy volatility constraining specialized health IT labor flows. Distribution runs through direct enterprise sales teams for hospital networks and channel partners for ambulatory clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where 21st Century Cures Act certification requirements erect barrier-to-entry moats favoring vendors with dedicated regulatory affairs infrastructure and ONC testing relationships.
For Market Incumbents: Acquire FHIR-native interoperability assets to neutralize cloud-native challengers attacking the ambulatory segment. Consolidate revenue cycle management capabilities through targeted capability additions in Medicaid expansion states where patient volume complexity outstrips legacy administrative capacity. ONC information blocking enforcement timelines compress vendor selection cycles, privileging platforms with proven federal certification credentials. For New Entrants and Emerging Players: Federally qualified health centers in rural hospital networks represent the most penetrable buyer archetype with subscription-based SaaS models displacing legacy client-server installations. AI-augmented clinical decision support modules for diagnostic imaging workflows open white-space revenue streams beyond core EHR licensing. Go-to-market positioning through regional health information exchanges bypasses direct competition with entrenched enterprise incumbents. For Investors and Strategic Acquirers: ONC's forthcoming information blocking penalty enforcement is the leading indicator that regulatory compliance capabilities will separate viable acquisition targets from stranded assets. Long-term viability over the next decade rests on hybrid cloud architecture execution satisfying both latency requirements and data sovereignty obligations. Target vendors with established HITRUST certification and proven FHIR implementation track records.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic's deep clinical-financial workflow integration anchors academic medical center loyalty against Oracle Health cloud infrastructure advantages. |
| Acquisition of Specialist Firm | Revenue cycle management vendors with real-time eligibility verification capabilities command premium valuations from hospital networks consolidating vendor lists. |
| Strategic Partnership | Hyperscaler alliances enable mid-tier vendors to compete on cloud infrastructure scale without captive data center capital expenditure. |
| Product Launch | FHIR-native platforms for new procurement cycles at academic medical centers displace legacy systems lacking API-first architectures. |
| Geographic Expansion | Subscription-based SaaS models in India and Japan capture hospital digitization subsidies without perpetual license sales friction. |
Study Parameters
Multi-period observation of hospital procurement database entries, ONC certification timelines, and CMS reimbursement policy shifts anchored the trend analysis, supplemented by interviews with hospital CIOs, health system purchasing committee chairs, GPO contracts managers, and biomedical informaticists. Secondary validation drew from CMS Medicare cost reports, hospital procurement filings, FDA software-as-medical-device classifications, and HHS Office for Civil Rights enforcement actions. Bottom-up facility-level deployment tracking triangulated against top-down vendor revenue segmentation.
Input-output matrices modeled deployment model transitions, health system consolidation patterns, and regulatory compliance cost burdens across the projection horizon. Segmentation dimensions included product type, deployment architecture, end-user setting, and functionality depth with regional adoption pattern overlays. CAGRs derived from facility-level activation trajectories and vendor pricing evolution. Forecast inputs incorporated cloud infrastructure migration pace and ONC information blocking penalty implementation intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to HITRUST certification timeline shifts and hyperscaler pricing volatility. Forecasts reflect documented assumptions regarding health system consolidation velocity and federal reimbursement policy stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Medical Record Management System Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Global Healthcare Content Management System Market
Health Data Management
Healthcare Data Annotation Tools Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
Data Democratization in Healthcare Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
North America Healthcare Analytics Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Global Big Data Analytics in Healthcare Market