
 Batten Disease Market | 2026-2036
Batten Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Batten Disease Market Outlook
Modular gene therapy platforms is expanding treatment access by allowing developers to swap payloads while retaining validated delivery vectors. Abeona Therapeutics leverages its AAV vector expertise to anchor its position in CLN3-directed programs. Amicus Therapeutics specializes in small-molecule chaperone approaches that compete alongside biologic modalities. BioMarin Pharmaceutical sustains manufacturing scale advantages through its in-house viral production capabilities.
Batten disease comprises a family of lysosomal storage disorders caused by mutations in CLN genes, characterized by progressive neurodegeneration, vision loss, and premature mortality, with diagnosis typically confirmed through enzyme assays, genetic sequencing, or electron microscopy of blood or tissue samples. Medication segments currently occupy the largest revenue share due to symptomatic management requirements, while gene therapy represents the fastest-growing category as intraventricular delivery programs advance through pivotal trials. Enzyme replacement therapy segments face structural constraints from blood-brain barrier penetration challenges, concentrating margin pools in delivery mode innovations.
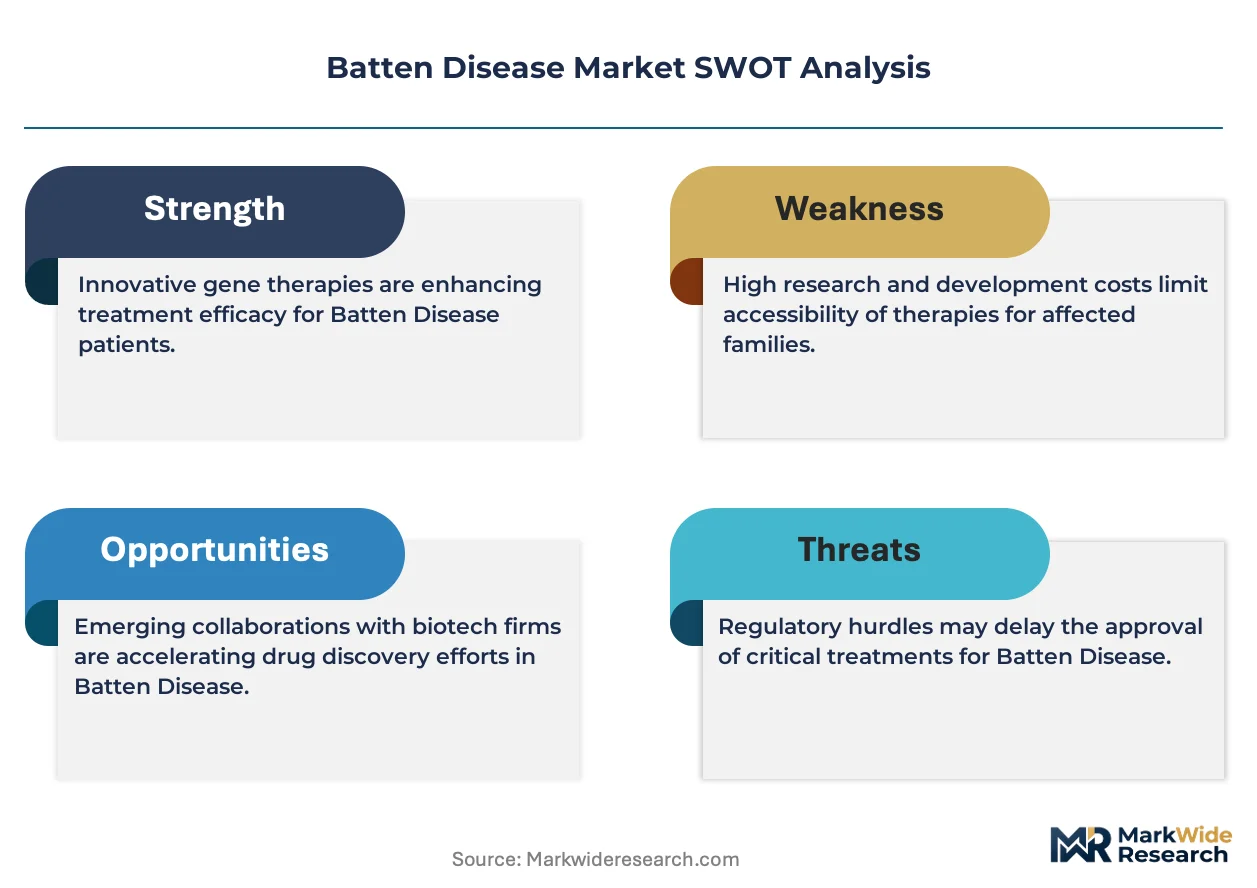
FDA orphan drug designations and EMA priority medicines frameworks shape demand by compressing development timelines and extending exclusivity periods for Batten disease therapies. The European F-Gas Regulation and US EPA manufacturing emission standards constrain viral vector production economics, favoring sponsors with captive supply chains. Stakeholders must monitor regulatory divergence between FDA accelerated approval pathways and EMA conditional marketing authorizations when structuring pivotal trial investments.
Market Dynamics
Gene therapy delivery vectors are compressing clinical development timelines while the FDA's accelerated approval pathways compress regulatory review periods, creating a dual squeeze on traditional small-molecule development economics in Batten disease therapeutics.
Growth Catalysts
- Orphan Drug Exclusivity:The FDA's orphan drug designation framework grants seven-year market exclusivity, attracting venture capital into CLN-directed programs that would otherwise face insufficient returns.
- AAV Manufacturing Scale-Up:Viral vector production platforms are achieving batch consistency improvements that reduce per-dose costs for intraventricular gene therapies.
- Pediatric Neurology Clinic Expansion:Academic medical centers in the United States are consolidating rare disease expertise into dedicated treatment hubs, concentrating eligible patient pools for trial recruitment.
Market Restraints
- European F-Gas Regulation:Perfluorocarbon emission limits constrain cold-chain sterilization processes for viral vector manufacturing, raising compliance costs for European production facilities.
- Blood-Brain Barrier Chemistry:Enzyme replacement therapies face fundamental pharmacokinetic limitations that prevent therapeutic concentrations from reaching central nervous system targets.
- Patient Pool Fragmentation:CLN gene variants distribute across ultra-rare mutation subtypes, complicating pivotal trial design and requiring transnational patient assembly.
Strategic Opportunities
- EMA Priority Medicines:The PRIME designation framework offers accelerated assessment and enhanced regulatory dialogue for Batten disease programs entering European markets.
- Next-Generation Sequencing Penetration:Newborn screening programs in the United States are expanding lysosomal storage disorder panels, enabling pre-symptomatic diagnosis and treatment initiation.
- Intrathecal Delivery Convergence:Combination of refined catheter technology with modified AAV capsids is opening direct CNS administration routes that bypass systemic exposure limitations.
Industry Challenges
- Gene Therapy Manufacturing Talent:Viral vector bioprocessing expertise concentrates at a handful of contract manufacturing organizations, creating recruitment bottlenecks for emerging sponsors.
- Longitudinal Trial Design:Neurodegenerative progression markers require multi-year observation periods, extending capital lock-up and complicating interim analysis planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Batten Disease Market |
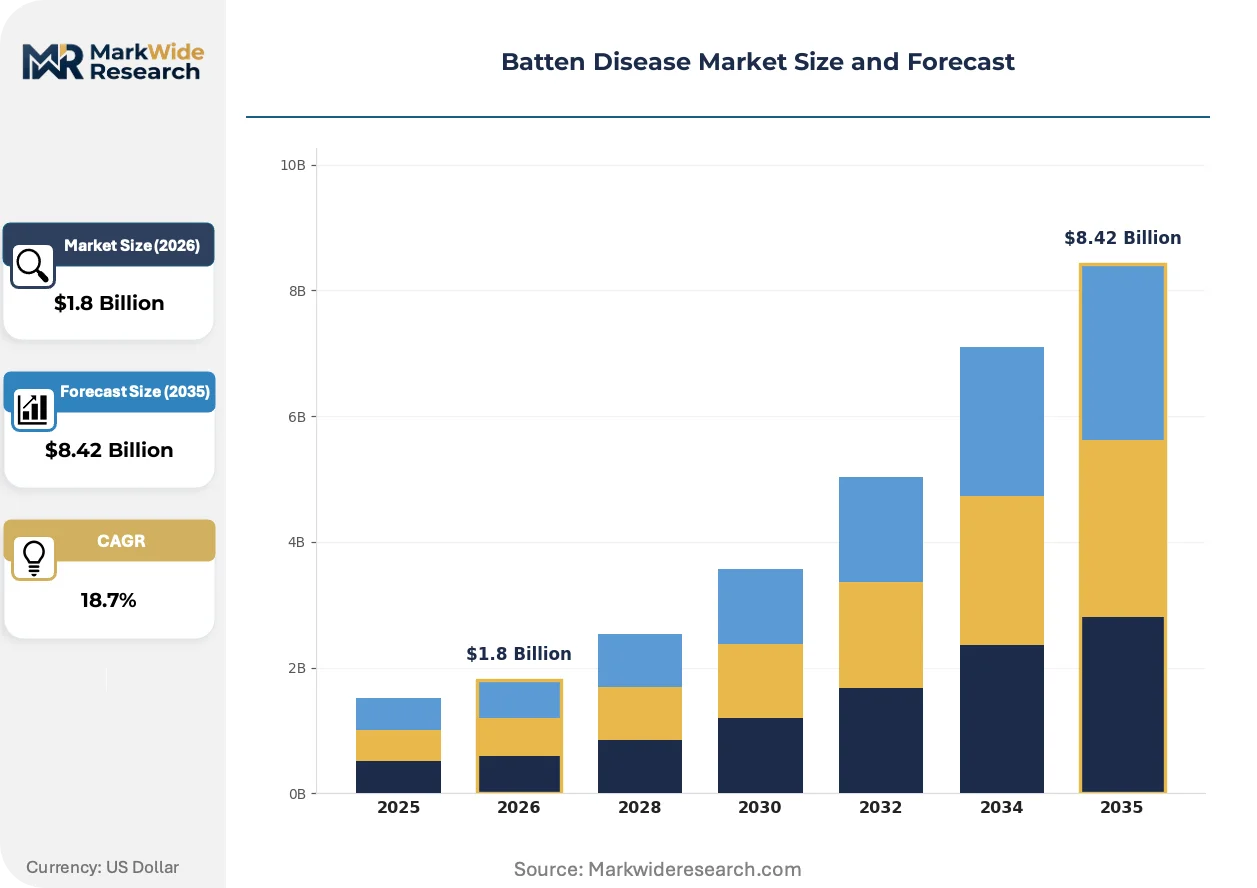
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Gene Therapy, Enzyme Replacement Therapy, Supportive Care Therapy Area: Neurological Disorders, Rare Diseases, Genetic Disorders, Pediatric Diseases Delivery Mode: Intravenous, Subcutaneous, Oral, Intraventricular End User: Hospitals, Clinics, Research Institutions, Homecare Settings |
| Companies Covered | Abeona Therapeutics, Alexion Pharmaceuticals, Amicus Therapeutics, REGENXBIO, Novartis AG, BioMarin Pharmaceutical, Lysogene, Orchard Therapeutics, Biogen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Batten Disease Market Strategic Shifts
Modular payload-swapping platforms are displacing fixed-vector development paradigms, while regulatory convergence around surrogate endpoints is reshaping how efficacy gets measured in neurodegenerative indications.
Self-complementary AAV vector engineering is integrating dual-strand DNA packaging that accelerates transgene expression kinetics. Pediatric neurology centers are adopting these constructs for CLN3 and CLN5 programs ahead of standard single-stranded alternatives. The structural consequence is compressing the therapeutic window between diagnosis and irreversible neuronal loss, forcing sponsors to reposition manufacturing capacity toward faster-producing formats.
The FDA's accelerated approval pathway is expanding acceptance of biomarker-based endpoints in lieu of clinical outcome measures for neurodegenerative diseases. This policy shift enables smaller pivotal trial designs and earlier commercial entry. Gene therapy developers targeting Batten disease variants are restructuring Phase II programs to capture cerebrospinal fluid enzyme level data as primary evidence packages.
Academic medical centers are consolidating procurement authority into centralized gene therapy committees that evaluate pipeline assets across multiple lysosomal storage disorders. This committee model displaces individual investigator-initiated selection, concentrating formulary access decisions at fewer institutional nodes. The United States exhibits the most pronounced concentration, with fifteen pediatric neurology hubs controlling the majority of patient access pathways.
Batten Disease Market Segmentation
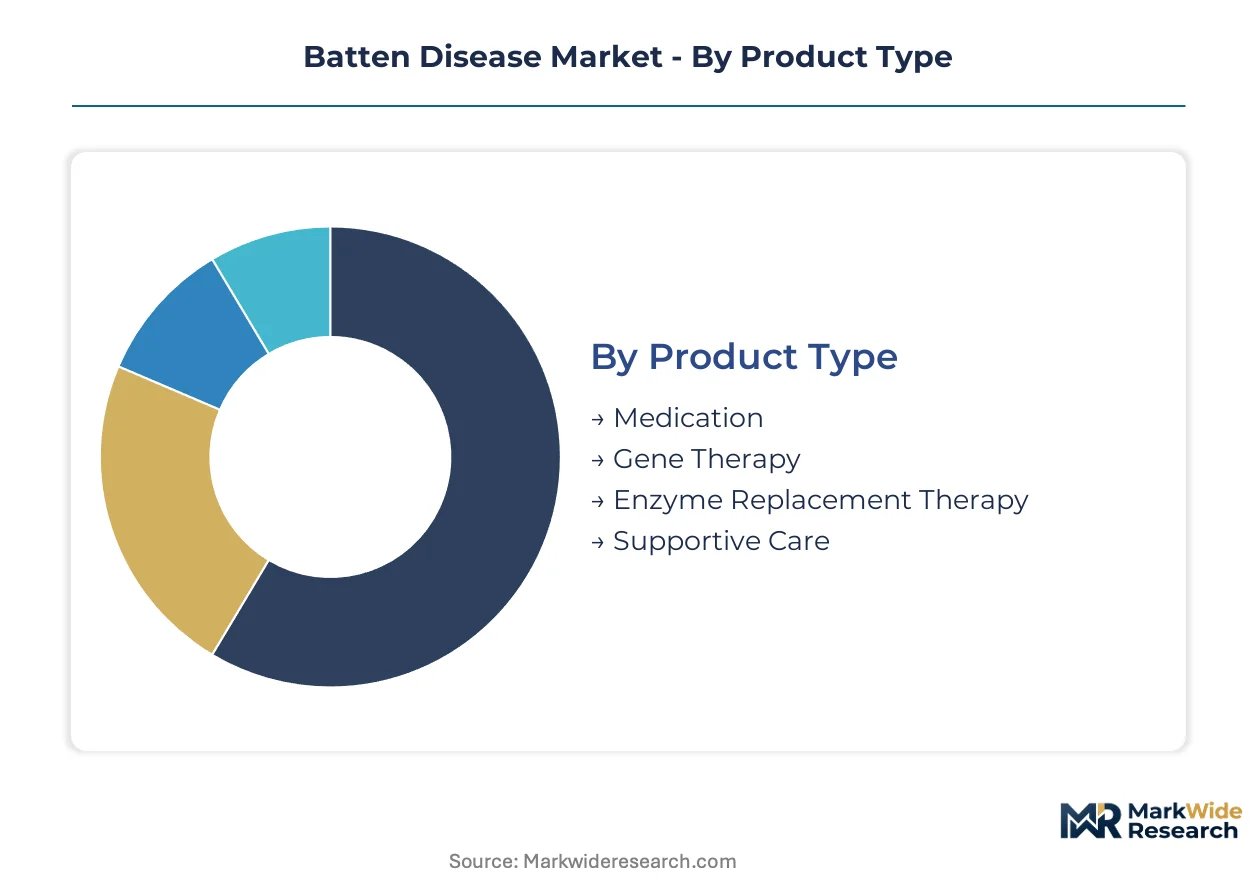
Segmentation in Batten disease therapeutics reveals how modality selection, delivery complexity, and care setting economics fragment addressable revenue pools. Treatment developers must align pipeline investments with the specific technical and regulatory requirements of each segment.
Product Type:
Customization intensity spans from standardized small-molecule formulations to patient-specific gene therapy constructs requiring individualized vector engineering.
- Medication:Symptomatic management compounds including anticonvulsants, antidepressants, and sleep aids address disease manifestations rather than underlying pathology. Demand concentrates in United States pediatric neurology clinics where insurance coverage for off-label prescribing remains most permissive.
- Gene Therapy:AAV-mediated CLN gene replacement programs target disease modification through intraventricular delivery of functional transgenes. Manufacturing scale-up constraints at contract development organizations limit supply availability for expanded access programs.
- Enzyme Replacement Therapy:Recombinant protein infusions compensate for deficient lysosomal hydrolase activity. Blood-brain barrier penetration failures restrict therapeutic efficacy to peripheral symptoms.
- Supportive Care:Nutritional support, physical therapy, and palliative interventions manage quality-of-life endpoints. Homecare reimbursement frameworks determine adoption velocity across Medicare and commercial payers.
Most installed capacity flows through Medication. Expansion is steepest in Gene Therapy.
Therapy Area:
Patient population definitions shift regulatory pathway eligibility and trial design complexity across this category.
- Neurological Disorders:Central nervous system degeneration drives the primary unmet medical need and shapes FDA accelerated approval endpoint selection. Academic medical centers in Boston, Philadelphia, and San Francisco anchor clinical trial recruitment.
- Rare Diseases:Orphan drug designation incentives compress development timelines and extend market exclusivity periods. EMA priority medicines status offers parallel European pathway acceleration.
- Genetic Disorders:Definitive molecular diagnosis requirements filter addressable populations through newborn screening expansion. CLN gene variant heterogeneity fragments eligible cohorts into ultra-rare subtypes.
- Pediatric Diseases:Age-restricted indication labels concentrate prescriber expertise at fifteen United States pediatric neurology hubs controlling formulary access.
Neurological Disorders captures the dominant share of gene therapy investment. Rare Diseases is climbing the fastest on regulatory incentive alignment.
Delivery Mode:
Route selection determines manufacturing requirements, administration site certification, and pharmacokinetic outcome profiles.
- Intravenous:Systemic circulation delivery enables enzyme replacement distribution to peripheral tissues. Infusion center capacity constraints limit patient throughput at academic medical centers.
- Subcutaneous:Depot-formulation injections extend dosing intervals for maintenance therapies. Home administration training programs reduce clinic burden.
- Oral:Small-molecule bioavailability challenges restrict CNS penetration for symptomatic agents. Patient compliance advantages support adherence in pediatric populations.
- Intraventricular:Direct cerebrospinal fluid administration bypasses blood-brain barrier limitations for gene therapy payloads. Neurosurgical catheter placement requirements concentrate treatment at specialized surgical centers.
Intravenous infrastructure dominates current treatment volume. Intraventricular capacity is gaining share fastest on gene therapy pipeline maturation.
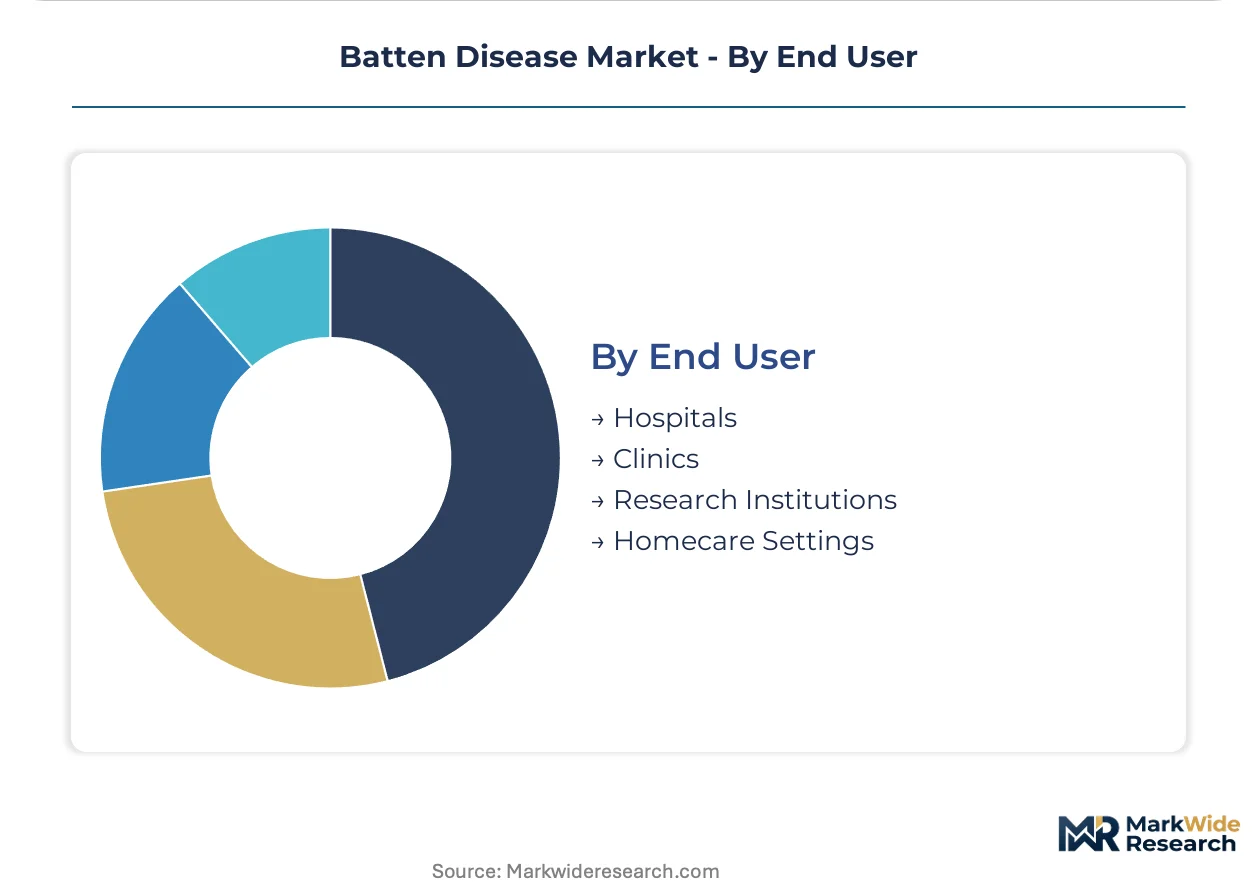
End User:
Care setting economics determine reimbursement rates, patient access pathways, and prescriber concentration patterns.
- Hospitals:Inpatient gene therapy administration requires neurosurgical suites and intensive monitoring capabilities. Major academic centers in New York, Houston, and Los Angeles consolidate complex case referrals.
- Clinics:Outpatient infusion centers manage enzyme replacement and symptomatic medication regimens. Pediatric neurology subspecialty certification filters eligible prescriber pools.
- Research Institutions:Investigator-initiated trials and natural history studies generate regulatory submission data packages. NIH-funded centers anchor longitudinal cohort assembly.
- Homecare Settings:Subcutaneous administration and supportive care services shift treatment location toward residential environments. Medicare home health benefit restrictions constrain pediatric coverage.
Hospitals retain the dominant installed base for disease-modifying therapies. Homecare Settings is expanding most quickly on reimbursement pressure for chronic management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Batten disease therapeutics originated in European academic medical centers during the 1990s, with foundational gene therapy research conducted at institutions in London and Hamburg. The United States subsequently built the largest treatment infrastructure through NIH-funded pediatric neurology networks.
United States
Fifteen pediatric neurology hubs in Boston, Philadelphia, and San Francisco concentrate eligible patient pools for clinical trial recruitment. The FDA's accelerated approval pathway compresses regulatory review timelines for gene therapies targeting neurodegenerative progression markers. Manufacturing scale-up at academic medical centers in Houston and New York anchors intraventricular delivery program expansion.
Germany
Heidelberg and Munich anchor European natural history study assembly for CLN gene variant characterization. The EMA's priority medicines framework offers parallel pathway acceleration for Batten disease programs entering European markets. Viral vector production facilities in Bavaria face structural cost pressures from the European F-Gas Regulation emission limits.
United Kingdom
London's Great Ormond Street Hospital pioneered early enzyme replacement protocols for lysosomal storage disorders. NHS England's specialized commissioning framework determines reimbursement for ultra-rare disease therapeutics. Research institutions in Cambridge and Oxford coordinate transnational patient assembly for fragmented CLN mutation subtypes.
Switzerland
Basel-based pharmaceutical infrastructure supports contract manufacturing organization capacity for viral vector bioprocessing. Swissmedic's streamlined assessment procedures attract sponsor submissions for orphan drug designations. The country's concentration of gene therapy talent creates recruitment competition with neighboring European facilities.
Japan
Tokyo and Osaka pediatric neurology centers participate in multinational pivotal trials for AAV-mediated CLN gene replacement. The PMDA's sakigake designation system offers priority review for innovative therapeutics addressing unmet medical needs. Manufacturing partnerships with domestic bioprocessors reduce import dependency for clinical supply.
Batten Disease Market Competitive Environment
The competitive structure tilts toward gene therapy specialists with captive viral vector production capabilities. Development-stage biotechs with modular AAV platforms occupy the premium tier, while established rare disease pharmaceutical companies leverage manufacturing scale for margin defense. Two archetypes dominate: vector-engineering boutiques and diversified lysosomal storage disorder incumbents. Competitive moves center on manufacturing capacity reservations at contract development organizations and strategic positioning for FDA accelerated approval pathway submissions.
Among the gene therapy-focused developers, Abeona Therapeutics and REGENXBIO exemplify the vector-engineering archetype through their specialized AAV platform investments. Amicus Therapeutics occupies a distinct position within small-molecule chaperone approaches, competing alongside biologic modalities rather than within them. BioMarin Pharmaceutical represents the diversified incumbent model, sustaining manufacturing scale advantages through in-house viral production capabilities that reduce dependency on external supply chains.
| Leading Market Players |
|---|
| Abeona Therapeutics |
| Alexion Pharmaceuticals |
| Amicus Therapeutics |
| REGENXBIO |
| Novartis AG |
| BioMarin Pharmaceutical |
| Lysogene |
| Orchard Therapeutics |
| Biogen |
| Others |
Value Chain & Pricing Dynamics
Pediatric neurology hub procurement committees in the United States are consolidating formulary decisions into centralized gene therapy evaluation boards, forcing supply chains to restructure around single-entry-point distribution and compressing pricing power for manufacturers lacking direct hospital relationships.
Pricing Analysis
Three-tier pricing structure across premium gene therapy, standard enzyme replacement, and economy symptomatic medication levels dominates the Batten disease market. Price differentiation separates intraventricular AAV-delivered treatments from peripheral enzyme infusions based on manufacturing complexity and neurosurgical administration requirements. Cost compression in the symptomatic medication tier is intensifying because of generic anticonvulsant competition and Medicaid rebate pressure. Hospital systems exhibit the lowest price sensitivity due to bundled reimbursement for complex neurological interventions, while homecare providers face acute margin pressure from Medicare pediatric coverage gaps.
Supply Chain Analysis
FDA current Good Manufacturing Practice certification and EMA advanced therapy medicinal product qualification gates concentrate viral vector production among captive bioprocessing facilities in the United States, Switzerland, and Germany. Raw material dependencies center on plasmid DNA, HEK293 cell lines, and perfluorocarbon cold-chain sterilization agents. Single-source vulnerability characterizes contract manufacturing organization capacity for scAAV vector engineering, with fewer than ten qualified facilities serving the global rare disease pipeline. Distribution runs through academic medical center pharmacy and therapeutics committees that control patient access pathways at fifteen major pediatric neurology hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Batten disease market reads as a late-cycle quality story where demand is concentrating toward disease-modifying gene therapies with demonstrated CNS penetration, displacing symptomatic management as the standard of care.
For Market Incumbents: Extend manufacturing scale advantages through captive viral vector bioprocessing capacity in Texas and North Carolina, insulating margin pools from European F-Gas Regulation compliance cost inflation. Secure long-term supply agreements with academic medical center gene therapy committees before competitor intraventricular programs reach pivotal trial readouts. For New Entrants and Emerging Players: Modular payload-swapping AAV platforms offer the most penetrable entry wedge for CLN gene variant programs outside the dominant CLN3 indication. Target the fragmented CLN5 and CLN6 subtypes where natural history data gaps have delayed incumbent pipeline prioritization, using investigator-initiated trial partnerships at NIH-funded centers as the primary go-to-market channel. For Investors and Strategic Acquirers: Asymmetric upside sits with development-stage biotechs possessing validated intraventricular delivery data packages and reserved manufacturing slots at qualified contract development organizations. The five-to-ten year viability window favors vector-engineering boutiques over diversified lysosomal storage disorder incumbents facing patent cliff exposure in adjacent rare disease franchises. Watch for FDA accelerated approval pathway acceptances of cerebrospinal fluid biomarker endpoints as the inflection signal for gene therapy valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Intraventricular delivery programs at Boston and Philadelphia hubs compress development timelines through concentrated patient recruitment. |
| Manufacturing Scale-Up | Captive viral vector bioprocessing in Houston and New York reduces per-dose cost exposure to European emission compliance. |
| Regulatory Approval Pathway | FDA accelerated approval submissions using CSF enzyme markers reshape pivotal trial economics for neurodegenerative indications. |
| Pipeline Diversification | CLN5 and CLN6 program expansion addresses mutation subtype fragmentation that constrains addressable patient pools. |
| Licensing Agreement | Academic medical center technology transfers from Cambridge and Oxford anchor transnational patient assembly capabilities. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gene therapy development executives, regulatory affairs leads at FDA and EMA, pediatric neurology formulary directors, and hospital procurement managers with secondary validation against ClinicalTrials.gov entries, FDA orphan drug designation filings, EMA PRIME status disclosures, and CMS Medicare reimbursement databases. Bottom-up patient population modeling and top-down revenue triangulation anchored market size estimates.
Comparable-period anchoring linked the projection horizon to historical gene therapy approval trajectories and natural history study enrollment velocities across the analysis window. Segmentation dimensions included product type, delivery mode, therapy area, and regional regulatory cluster. CAGRs were derived from weighted average of indication-specific growth curves and manufacturing capacity expansion schedules, with inputs from newborn screening panel expansion rates and intraventricular catheter placement training program scaling.
The model holds under stable FDA accelerated approval pathway policies and continued orphan drug exclusivity enforcement; deviation in EMA conditional marketing authorization convergence or European F-Gas Regulation enforcement intensity would shift manufacturing cost assumptions and regional revenue distribution. A model refresh is warranted upon material change in intraventricular gene therapy safety database maturation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Donohue Syndrome Treatment Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market
Rare Diseases
Arthrogryposis Management Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Von Hippel-Lindau Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Erdheim-Chester Disease Market