
 UK Pharmacovigilance Market | 2026-2036
UK Pharmacovigilance Market Size, Share, and Industry Trends Forecast 2026-2036
UK Pharmacovigilance Market Intelligence
Good Pharmacovigilance Practice (GVP) certification is reorganizing vendor eligibility across the UK, with only MHRA-registered Qualified Persons for Pharmacovigilance (QPPVs) able to anchor regulatory submission workflows. IQVIA leverages its integrated real-world evidence platform to dominate signal detection contracts with top-20 pharma sponsors. ICON plc sustains competitive positioning through specialized risk management services tailored to emerging biotech clients. PAREXEL International Corporation anchors its UK operations with deep expertise in post-authorization safety studies.
Pharmacovigilance encompasses the science and activities relating to the detection, assessment, understanding, and prevention of adverse effects or any other drug-related problems, with case processing turnaround times typically governed by 15-day expedited reporting deadlines for serious reactions to the MHRA. Its primary commercial purpose is ensuring patient safety while maintaining regulatory authorization for marketed medicines across their lifecycle. Cloud-based solutions lead technology adoption as sponsors prioritize scalable infrastructure for periodic safety update report submissions. Artificial Intelligence and machine learning represent the fastest-expanding capability layer, with natural language processing now automating literature surveillance that previously required manual MEDLINE screening. Data Management services occupy the largest service-type revenue pool, though Signal Detection commands premium pricing due to specialized statistical expertise requirements.
The Medicines and Healthcare products Regulatory Agency (MHRA) enforces UK-specific GVP modules that diverged from EU Volume IXA following Brexit, creating distinct compliance obligations for market authorization holders. The Human Medicines Regulations 2012, as amended, mandate direct MHRA reporting rather than EMA gateway submissions, forcing sponsors to maintain separate UK pharmacovigilance system master files. Stakeholders must monitor how MHRA recognition agreements with FDA and Health Canada evolve, as mutual reliance frameworks could reshape inspection priorities and data-sharing protocols for multinational safety databases.
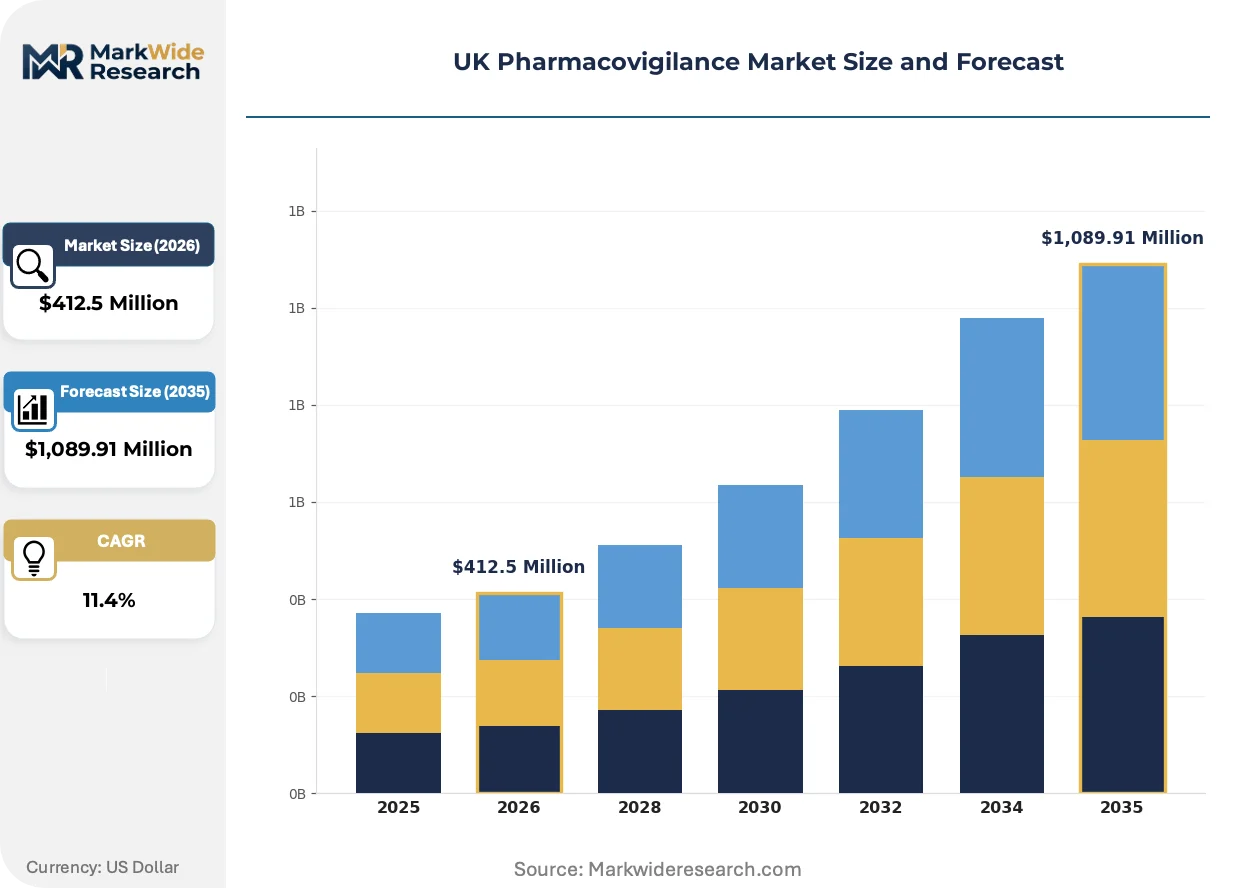
Market Dynamics
MHRA's post-Brexit regulatory autonomy forces sponsors to rebuild pharmacovigilance infrastructure around UK-specific master files and direct reporting gateways, creating immediate compliance expenditure spikes and vendor requalification cycles.
Growth Catalysts
- EMA divergence:The Human Medicines Regulations 2012 amendments mandate separate UK pharmacovigilance system master files, compelling sponsors to establish dedicated domestic safety operations.
- London biotech clustering:Emerging biopharma sponsors in the Golden Triangle generate concentrated demand for outsourced case processing and signal detection services.
- Artificial intelligence:Natural language processing tools automate literature surveillance workflows, reducing manual MEDLINE screening burdens and accelerating 15-day expedited reporting compliance.
Market Restraints
- QPPV scarcity:MHRA-registered Qualified Persons for Pharmacovigilance command premium compensation, inflating fixed costs for mid-cap sponsors establishing UK presence.
- Cloud vendor concentration:AWS and Azure dominance in adverse event processing hubs creates single-provider risk for London-based safety operations.
- Legacy system entanglement:EU-period safety databases require expensive reconfiguration for MHRA gateway compatibility, delaying UK-specific workflow activation.
Strategic Opportunities
- Scotland and Northern England:Untapped CRO capacity in Edinburgh and Manchester offers cost arbitrage against Southeast concentration for case processing scale-outs.
- Real-world evidence convergence:Integration of electronic health records with safety databases enables proactive signal detection beyond spontaneous reporting limitations.
- Wales life sciences corridor:Cardiff's emerging biotech manufacturing base generates adjacent pharmacovigilance service demand for post-authorization safety studies.
Industry Challenges
- Statistical programming talent:Signal detection expertise combining R programming with epidemiological methods remains scarce across UK labor markets.
- GVP certification timelines:MHRA inspection backlogs delay vendor qualification, compressing sponsor implementation windows for regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Pharmacovigilance Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,089.91 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Management, Risk Management, Signal Detection, Literature Review End User: Pharmaceutical Companies, Contract Research Organizations, Regulatory Authorities, Academic Institutions Technology: Cloud-Based Solutions, Artificial Intelligence, Machine Learning, Data Analytics Application: Adverse Event Reporting, Regulatory Compliance, Risk Assessment, Post-Marketing Surveillance |
| Companies Covered | IQVIA, ICON plc, Accenture, PAREXEL International Corporation, Capgemini, Cognizant, ArisGlobal, TAKE Solutions Ltd, IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Pharmacovigilance Market Strategic Shifts & Innovations
Automation layers are restructuring pharmacovigilance economics, compressing case processing timelines while elevating the strategic value of human expertise in signal interpretation and regulatory negotiation.
Natural language processing engines trained on adverse event narratives are supplanting manual medical coding workflows at top-20 pharma sponsors. Contract research organizations deploy these tools across London processing hubs to handle volume spikes from novel biologic launches. The technology compresses case intake-to-submission intervals from days to hours, enabling compliance with MHRA's 15-day expedited reporting mandate without proportional staff expansion.
The MHRA's post-Brexit GVP modules diverged from EU Volume IXA, creating distinct UK compliance obligations for market authorization holders. Sponsors must maintain separate pharmacovigilance system master files and direct MHRA gateway connections rather than EMA submissions. Large pharma sponsors absorb these costs through dedicated UK safety teams, while mid-cap biotechs outsource to MHRA-registered QPPV service providers.
Biopharma procurement departments now unbundle safety services from full-service CRO relationships, selecting specialized vendors for signal detection while retaining case processing incumbents. This disaggregation pressures integrated providers to defend pricing through outcome-based performance guarantees. The pattern concentrates in Southeast England, where sponsor proximity enables tighter vendor oversight and faster escalation protocols for regulatory inquiries.
UK Pharmacovigilance Market Segmentation
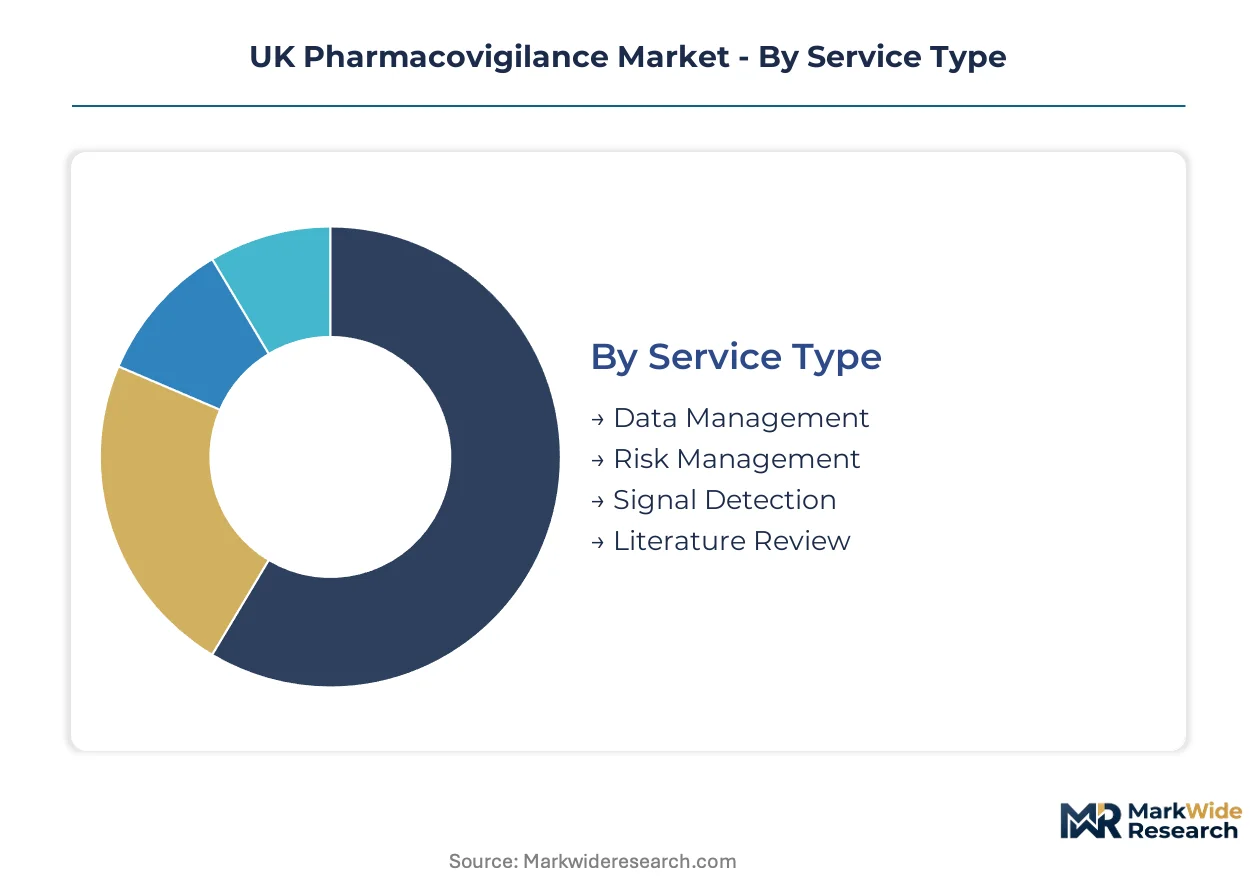
Segmentation reveals how MHRA's post-Brexit compliance architecture fragments purchasing decisions across service types, technologies, and end-user categories. Sponsors now procure pharmacovigilance capabilities through specialized vendor relationships rather than bundled CRO contracts.
Service Type:
Regulatory differentiation drives procurement fragmentation, with sponsors unbundling signal detection from case processing to access specialized statistical expertise.
- Data Management:Core infrastructure for adverse event intake, coding, and database administration underpins all pharmacovigilance workflows. London-based pharmaceutical sponsors concentrate demand here, driven by the need for MHRA-compatible master file architectures that diverged from EMA systems post-Brexit.
- Signal Detection:Statistical algorithms and epidemiological methods identify safety signals from spontaneous reporting databases. Southeast England biotech clusters generate premium-priced demand, constrained by scarcity of R-programming talent combining coding skills with regulatory science expertise.
- Risk Management:Development and maintenance of risk minimization materials and risk evaluation mitigation strategies for authorized medicines.
- Literature Review:Systematic surveillance of biomedical publications for individual case safety reports and emerging safety signals.
Data Management handles the majority of throughput; Signal Detection is the fastest mover on share.
End User:
Cost tier stratification separates enterprise sponsors with captive safety teams from outsourcing-dependent mid-cap biotechs.
- Pharmaceutical Companies:Large sponsors maintain dedicated UK pharmacovigilance departments with MHRA-registered QPPVs, absorbing fixed costs to protect regulatory authorization timelines. Manchester and Edinburgh emerging biotechs represent the fastest-expanding demand segment as Golden Triangle manufacturing scales.
- Contract Research Organizations:Specialized vendors deliver outsourced case processing and signal detection under QPPV governance structures. AWS and Azure concentration in London adverse event hubs creates single-provider vulnerability for these service providers.
- Regulatory Authorities:The MHRA itself procures pharmacovigilance infrastructure for its own surveillance systems and inspection protocols.
- Academic Institutions:Universities conduct post-authorization safety studies and method development research with industry sponsorship.
Pharmaceutical Companies dominate absolute spend; Contract Research Organizations capture the steepest expansion trajectory as unbundling accelerates.
Technology:
Volume concentration in cloud infrastructure creates procurement rigidity despite rapid capability layering at the analytics tier.
- Cloud-Based Solutions:Scalable adverse event processing hubs enable compliance with 15-day expedited reporting mandates without proportional infrastructure investment. London and Southeast England sponsor concentration drives geographic clustering of these deployments.
- Artificial Intelligence:Natural language processing engines automate medical coding and narrative assessment, compressing case intake-to-submission intervals from days to hours at top-20 pharma sponsors.
- Machine Learning:Predictive models enhance signal detection sensitivity beyond traditional disproportionality analysis methods.
- Data Analytics:Business intelligence tools support periodic safety update report generation and regulatory performance dashboards.
Cloud-Based Solutions anchor current infrastructure spend; Artificial Intelligence is gaining share fastest as automation economics improve.
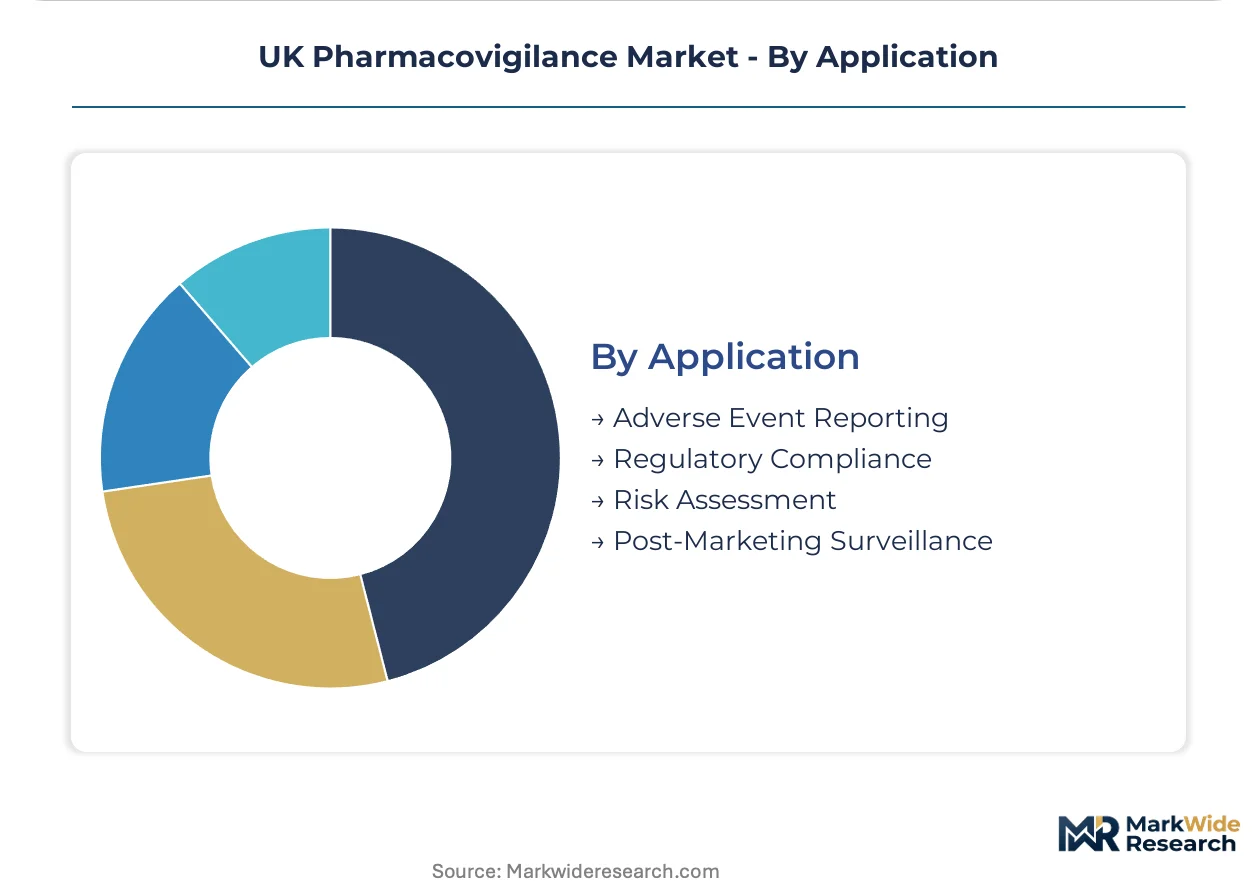
Application:
Customer type maturity separates reactive compliance functions from proactive safety science investments.
- Adverse Event Reporting:Collection, processing, and regulatory submission of individual case safety reports to the MHRA gateway. This foundational capability concentrates in London-based processing centers serving sponsor clusters across the Golden Triangle.
- Regulatory Compliance:Maintenance of pharmacovigilance system master files, periodic safety update reports, and direct MHRA correspondence. Post-Brexit divergence from EU Volume IXA forced complete infrastructure rebuilds for multinational sponsors.
- Risk Assessment:Evaluation of benefit-risk profiles throughout product lifecycles and preparation of risk management plans.
- Post-Marketing Surveillance:Active monitoring of authorized medicines through registries, epidemiological studies, and real-world evidence integration.
Adverse Event Reporting processes the highest case volumes; Post-Marketing Surveillance is climbing the fastest as real-world evidence convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The MHRA's regulatory autonomy post-Brexit has concentrated pharmacovigilance infrastructure investment in England's Golden Triangle, with emerging biotech clusters in Manchester and Edinburgh capturing service outsourcing flows as sponsors seek cost arbitrage against London premiums.
London and Southeast England
London anchors UK pharmacovigilance demand through its dense concentration of biopharma headquarters and MHRA-registered Qualified Persons for Pharmacovigilance. The Human Medicines Regulations 2012 amendments forced sponsors to establish UK-specific master files, driving cloud-based adverse event processing hub deployment in the capital. Cambridge and Oxford biotech corridors generate concentrated case processing volumes for novel biologic launches.
North England
Manchester's emerging life sciences campus attracts pharmacovigilance outsourcing from mid-cap sponsors seeking QPPV services at lower cost than London providers. The city's university hospitals supply clinical data partnerships for post-authorization safety studies. Health Innovation Manchester accelerates real-world evidence integration into safety databases through NHS data access agreements.
Scotland
Edinburgh's regulatory science cluster leverages Scottish Medicines Consortium relationships to capture pharmacovigilance contracts for medicines seeking UK-wide reimbursement. The BioQuarter development hosts contract research organizations specializing in signal detection for rare disease therapies. Scottish Enterprise funding supports AI-enabled literature surveillance tool development for 15-day expedited reporting compliance.
Wales
Cardiff's life sciences corridor generates pharmacovigilance demand from its emerging biotech manufacturing base, particularly for cell and gene therapy post-authorization monitoring. The Welsh Government's Life Sciences Hub facilitates MHRA gateway connectivity for sponsors establishing UK presence. Swansea University's health data research partnerships enable electronic health record integration with safety databases.
Midlands
Birmingham's clinical trials infrastructure supports pharmacovigilance service expansion through its NHS trust network and patient registry capabilities. The Midlands Engine investment program targets regulatory science talent development to address statistical programming scarcity in signal detection. Leicester's medical school supplies epidemiological expertise for risk management plan preparation.
UK Pharmacovigilance Market Key Industry Players
Listed leaders compete with private specialists across technology platform differentiation, with publicly traded contract research organizations and IT consultancies dominating cloud infrastructure contracts while privately held regulatory specialists capture QPPV governance mandates. The market structure reflects sponsor unbundling of safety services, fragmenting purchasing decisions across case processing, signal detection, and master file maintenance. Three archetypes predominate: integrated real-world evidence platforms, specialized risk management boutiques, and IT services conglomerates with life sciences verticals. Competitive moves center on AI capability acquisition and geographic expansion into Scotland and Northern England processing centers.
Within the integrated platform tier, IQVIA exemplifies the real-world evidence convergence strategy, while ICON plc occupies a position among specialized service providers tailored to emerging biotech capital constraints. PAREXEL International Corporation anchors the regulatory science specialist archetype through its post-authorization safety study expertise.
| Leading Market Players |
|---|
| IQVIA |
| ICON plc |
| Accenture |
| PAREXEL International Corporation |
| Capgemini |
| Cognizant |
| ArisGlobal |
| TAKE Solutions Ltd |
| IBM Corporation |
| Others |
Cost & Logistics Intelligence
Fifteen-day expedited reporting deadlines compress case processing timelines and concentrate pricing power among MHRA-registered QPPV service providers with established gateway connectivity. This lead-time constraint elevates certification premiums while forcing sponsors toward cloud-based processing hubs that amortize fixed infrastructure across volume tiers.
Pricing Analysis
MHRA GVP certification level creates the primary spread between premium QPPV-governed services and standard case processing tiers. Subscription-based SaaS pricing dominates cloud infrastructure contracts, while project-based fees attach to signal detection engagements requiring specialized statistical programming. Price differentiation hinges on QPPV registration status and real-world evidence platform integration depth. Cost compression in mid-tier case processing intensifies as automation tools reduce manual coding hours. Emerging biotech sponsors exhibit highest price sensitivity, prioritizing modular service unbundling over integrated CRO relationships.
Supply Chain Analysis
India and Ireland anchor global pharmacovigilance service delivery, supplying case processing capacity and regulatory science talent to UK sponsors. Cloud infrastructure draws from AWS and Azure data centers concentrated in London and Southeast England. Legacy database migration dependencies and single-provider cloud concentration create vulnerability for MHRA gateway compliance. Distribution runs through direct vendor-sponsor contracts with limited intermediary layering, reflecting the specialized governance requirements of pharmacovigilance outsourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
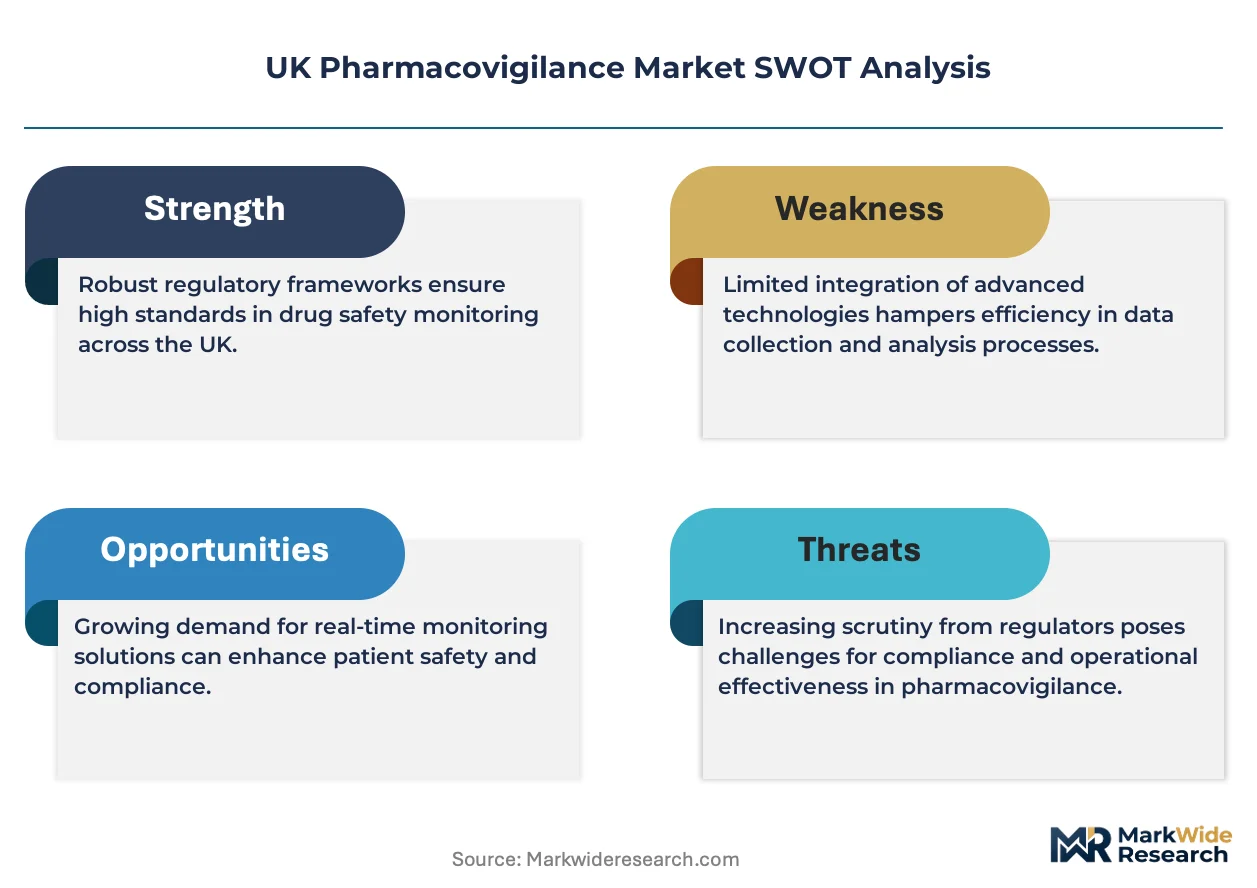
Post-Brexit regulatory divergence fragments purchasing decisions across specialized service tiers, creating white-space opportunities for vendors with targeted capability investments.
For Market Incumbents: Consolidate signal detection expertise through targeted capability acquisition in Scotland and Northern England, where statistical programming talent scarcity constrains competitor expansion. Deepen QPPV bench strength to defend against emerging regulatory technology vendors automating master file maintenance. Vertical integration into real-world evidence platforms protects pricing power as sponsors demand integrated safety-efficacy databases. For New Entrants and Emerging Players: Anchor in Manchester and Edinburgh processing centers to capture cost-sensitive mid-cap biotech demand fleeing London premium pricing. Target literature surveillance automation as the most penetrable technology layer, where natural language processing tools displace manual MEDLINE screening workflows. Pursue MHRA GVP certification early to qualify for vendor panels before inspection backlogs lengthen qualification timelines. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory complexity play because post-Brexit divergence from EU Volume IXA entrenches UK-specific compliance infrastructure requirements. Acquisition candidates combine QPPV governance capabilities with AI-enabled case processing tools serving emerging biotech clusters. Monitor MHRA recognition agreement negotiations with FDA and Health Canada as the signal indicating whether UK pharmacovigilance infrastructure investments retain standalone value or converge toward mutual reliance frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| QPPV Certification Investment | MHRA registration unlocks vendor eligibility for regulatory submission workflows serving top-20 pharma sponsors. |
| AI-Enabled Literature Surveillance | Natural language processing automation compresses case intake-to-submission intervals from days to hours for 15-day compliance. |
| Scotland Processing Center Expansion | Edinburgh's regulatory science cluster offers cost arbitrage against Southeast England concentration for case processing scale-outs. |
| Real-World Evidence Platform Integration | Electronic health record convergence enables proactive signal detection beyond spontaneous reporting database limitations. |
| Post-Authorization Safety Study Capability | Deep expertise in risk evaluation and mitigation strategies differentiates vendors for cell and gene therapy monitoring demand. |
Research Approach
Cross-validation between primary interviews with pharmacovigilance directors, regulatory affairs leads, QPPV service providers, and biotech outsourcing managers anchors the qualitative findings against secondary validation. FDA 483 inspection observations, MHRA GVP inspection reports, EMA post-authorization safety study databases, and sponsor 10-K pharmacovigilance expenditure disclosures provide quantitative grounding. Bottom-up service-type demand modeling and top-down market sizing triangulate volume estimates across the analysis window.
Sensitivity analysis tests forecast outputs against alternative scenarios for QPPV supply expansion and AI automation adoption rates. The analytical framework segments by service type, end-user category, technology deployment, and application across the projection horizon, with CAGRs derived from regression against regulatory filing volume trends and sponsor safety budget disclosures. Treatment line stratification and regional regulatory cluster differentiation refine the segmentation model for biologic versus small-molecule therapy monitoring intensity.
Underlying assumptions cover sustained MHRA regulatory autonomy, stable cloud infrastructure pricing, and gradual AI capability maturation, with deviation risk concentrated in mutual recognition agreement negotiations and statistical programming labor market tightness. Recalibration cycles align with material shifts in MHRA inspection priority announcements and major biologic launch volumes affecting case processing demand spikes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Ketoprofen API Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Influenza Medication Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Hypertension Drug Market
Pharmacology
Antitussive Drugs Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Cough Remedies Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Medication Adherence Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Hepatitis C Drug Market
Pharmacology
Drug Eruptions Treatment Market