
 Healthcare Data Monetization Solutions Market | 2026-2036
Healthcare Data Monetization Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Data Monetization Solutions Market Analytics
Market Context
Structured data formats are replacing legacy unstructured health records, and this shift is realigning product economics across the value chain. Optum leverages its payer-provider integration to dominate risk-adjusted data products. IQVIA sustains competitive moats through proprietary real-world evidence registries spanning multiple therapy areas. Innovaccer anchors its position with cloud-native data activation platforms built for health system interoperability.
Technical Definition and Segment Structure
Healthcare data monetization solutions encompass platforms, services, and governance frameworks that extract, normalize, analyze, and commercialize health information assets while preserving patient privacy through de-identification protocols and differential privacy techniques. These systems serve pharmaceutical R&D acceleration, population health management, and precision medicine reimbursement negotiations. Clinical data segments command premium pricing due to regulatory-grade provenance requirements and longitudinal patient tracking capabilities. Analytics services represent the fastest-expanding service type as buyers prioritize outcome-based contracts over perpetual licensing. Subscription delivery models now lead volume adoption among mid-tier health systems seeking predictable cost structures.
Regulatory Framework and Outlook
The FDA, HIPAA, and EU AI Act collectively shape permissible data uses, de-identification standards, and algorithmic transparency obligations that determine market access viability. Health Catalyst navigates this complexity through embedded compliance tooling within its data operating system. Stakeholders must monitor evolving cross-border data transfer agreements between the United States and European Union, as these bilateral frameworks will determine whether unified data monetization architectures remain technically and legally feasible.
Market Dynamics
The HIPAA interoperability mandates and EU AI Act are compressing legacy data governance timelines, forcing pharmaceutical sponsors and health systems to rebuild consent architectures and de-identification pipelines before commercializing longitudinal patient records.
Growth Catalysts
- Real-world evidence mandates:The FDA's expanded guidance on RWE for regulatory submissions is pulling pharmaceutical manufacturers toward external control arm datasets and post-market surveillance registries.
- Federated learning architectures:Privacy-preserving computation techniques enable multi-party analytics without centralizing raw records, unlocking data partnerships previously blocked by HIPAA business associate agreement complexity.
- California and Texas IDN concentration:Integrated delivery networks in these states are consolidating de-identified data assets into commercializable repositories for life sciences contracting.
Market Restraints
- Cross-border transfer friction:The absence of a successor EU-US Data Privacy Framework creates legal uncertainty for unified data monetization architectures spanning Atlantic operations.
- Differential privacy compute costs:The computational overhead of injecting mathematical noise into query outputs degrades query speed and inflates cloud infrastructure spending for analytics services.
- Substitute data sources:Synthetic data generation platforms and digital twin simulations are capturing early-stage R&D budgets that previously flowed to retrospective clinical data licensing.
Strategic Opportunities
- Genomics-pharma convergence:The integration of multi-omic profiling with claims data is creating new reimbursement negotiation datasets for precision medicine therapies in oncology and rare disease.
- API-first distribution:Direct data marketplace integrations with electronic health record systems are displacing traditional enterprise sales cycles for mid-tier health system buyers.
- Medicaid managed care tailwinds:State-level social determinants of health reporting mandates are generating demand for population health analytics among regional payers serving dual-eligible populations.
Industry Challenges
- Embedded compliance engineering scarcity:Health technology vendors struggle to recruit data governance architects capable of implementing algorithmic transparency tooling required by the EU AI Act's high-risk system classification.
- Legacy EHR integration complexity:Health systems operating on decade-old instances of Cerner or Epic require expensive middleware development to normalize data structures for external commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Data Monetization Solutions Market |
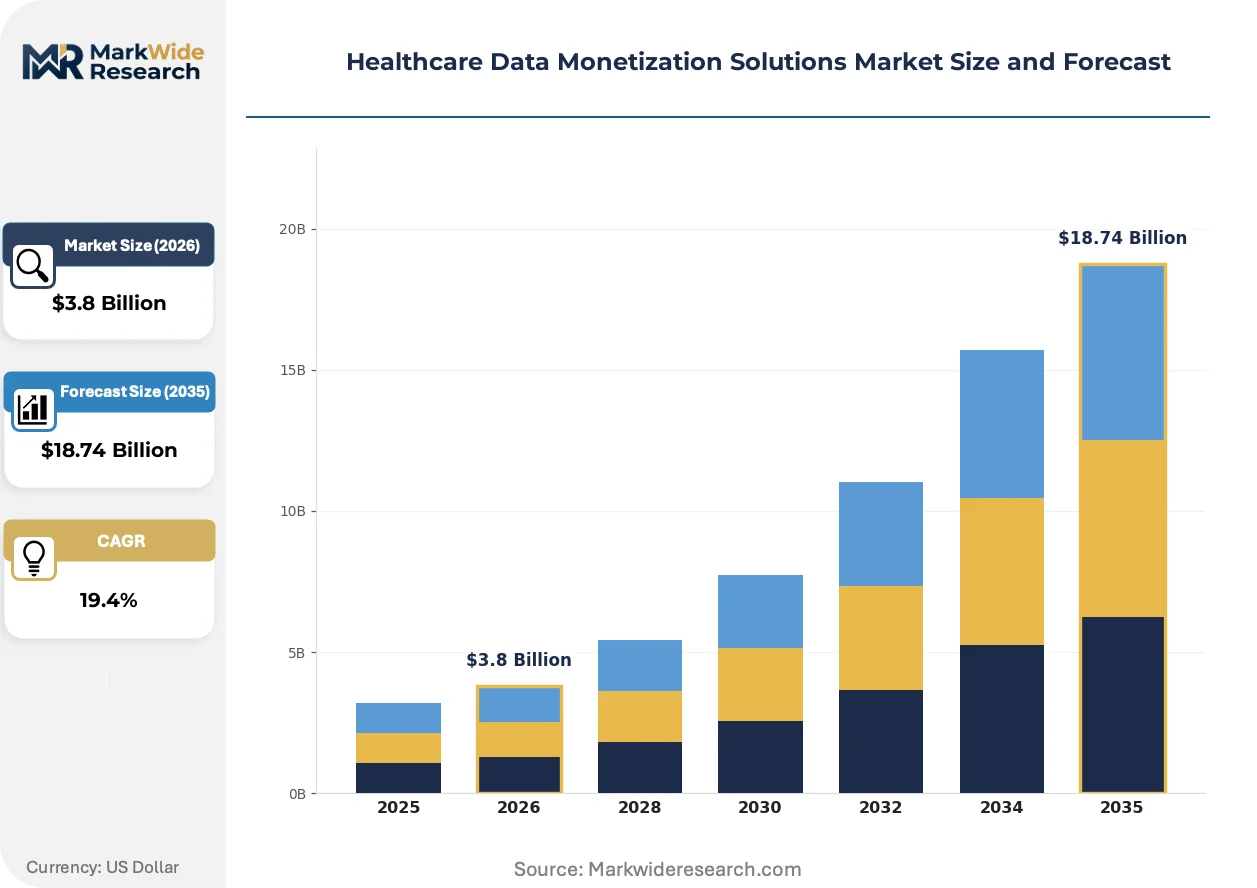
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Model: Subscription, Pay-per-Use, Licensing, Partnership Data Type: Patient Data, Clinical Data, Operational Data, Financial Data Service Type: Analytics Services, Data Hosting, Data Integration, Consulting End User: Healthcare Providers, Payers, Research Organizations, Pharmaceutical Companies |
| Companies Covered | Innovaccer, Optum, IQVIA, Microsoft, Informatica, GE HealthCare Technologies, Health Catalyst, Accenture, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Data Monetization Solutions Market Evolving Landscape
Structured data pipelines and privacy-enhancing technologies are compressing the latency between clinical data capture and commercial licensing, while regulatory fragmentation across jurisdictions is forcing modular compliance architectures.
Synthetic data generation is electrifying pharmaceutical R&D workflows by producing statistically equivalent patient cohorts without privacy re-identification risk. Contract research organizations are adopting these platforms for control arm simulation and protocol optimization. The technology is electrifying competitive dynamics in the analytics services segment by reducing dependency on retrospective data licensing agreements.
The EU AI Act's high-risk system classification is imposing algorithmic transparency and human oversight requirements on clinical decision support tools used for treatment selection. Developers must now maintain technical documentation and risk management systems throughout the product lifecycle. Real-world evidence platforms serving European pharmaceutical sponsors are most affected, with vendors embedding explainability modules into their data operating systems.
Pharmaceutical procurement teams are unbundling perpetual software licenses in favor of consumption-based pricing tied to query volume and dataset refresh frequency. This reconfiguration is displacing upfront enterprise agreements in the mid-market health system segment. The pattern is most visible among integrated delivery networks in Texas seeking predictable operational expenditure structures for population health analytics.
Healthcare Data Monetization Solutions Market Segmentation
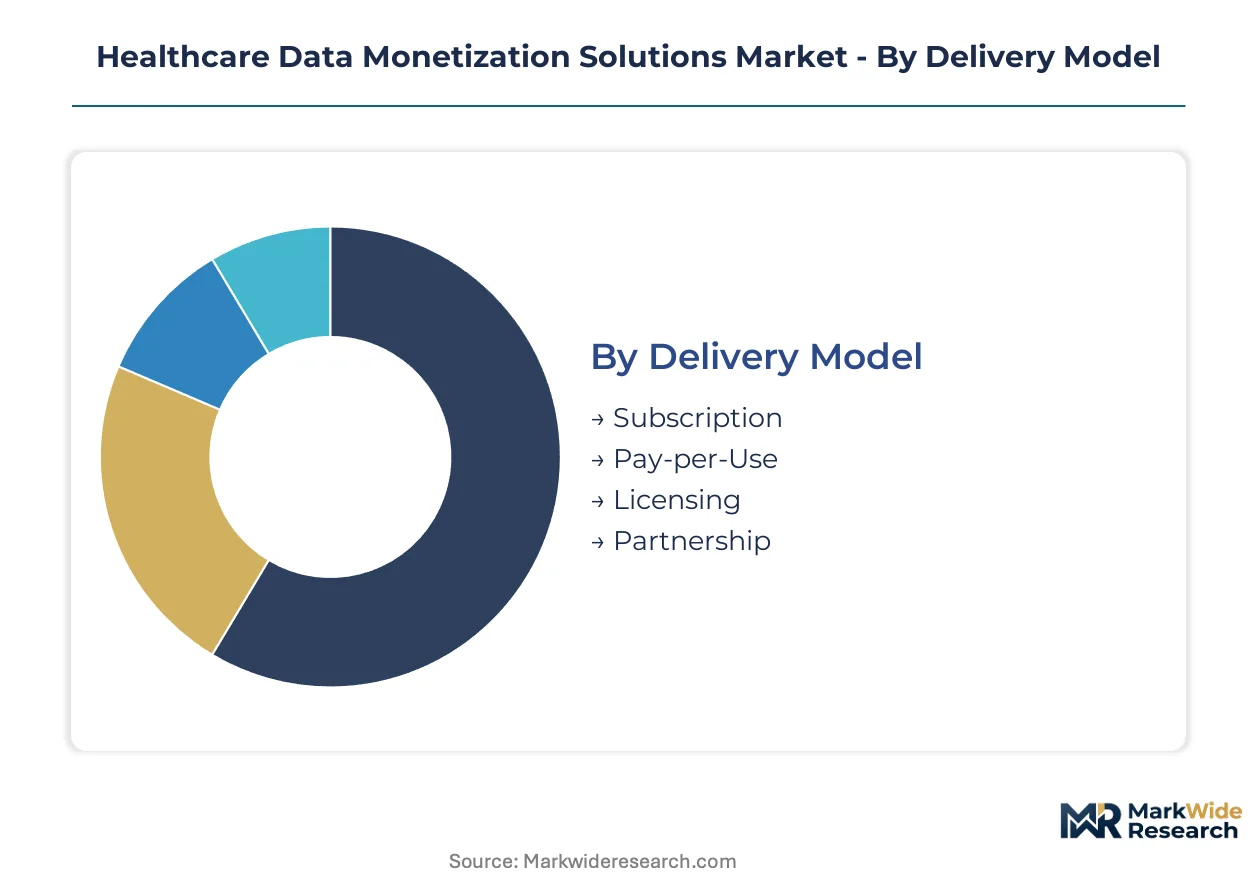
Segmentation in healthcare data monetization solutions determines pricing architecture, compliance burden, and partnership structures. Buyers select delivery models based on IT governance maturity; data type choices trigger distinct de-identification protocols and regulatory pathways.
Delivery Model:
Subscription contracts are displacing perpetual licenses as health systems prioritize predictable operational expenditure over capital deployment.
- Subscription:Recurring revenue structures bundle platform access, maintenance, and compliance updates into monthly or annual fees. Mid-tier integrated delivery networks in Texas and California favor this model for population health analytics budgeting.
- Pay-per-Use:Consumption-based pricing ties costs to query volume, dataset refresh frequency, or API call volume. Pharmaceutical procurement teams unbundling enterprise agreements for external control arm datasets are accelerating this segment's expansion.
- Licensing:Perpetual software licenses with upfront payment remain prevalent among large academic medical centers with dedicated IT capital budgets.
- Partnership:Revenue-sharing arrangements align vendor incentives with data commercialization outcomes, common in genomics-pharma convergence deals.
Volume placements concentrate in Subscription; the faster expansion belongs to Pay-per-Use.
Data Type:
Regulatory-grade provenance requirements and longitudinal tracking capabilities create pricing premiums across clinical data categories.
- Clinical Data:Structured diagnostic codes, procedure records, and medication histories with regulatory-grade provenance command premium licensing fees. Pharmaceutical sponsors demand this data type for FDA real-world evidence submissions.
- Patient Data:De-identified longitudinal records spanning multiple care episodes enable post-market surveillance registries. HIPAA-compliant de-identification pipelines and differential privacy techniques determine commercial viability.
- Operational Data:Scheduling, supply chain, and workflow metrics support efficiency consulting engagements rather than external licensing.
- Financial Data:Claims and reimbursement records enable risk-adjustment products for payer contracting.
Revenue concentration sits with Clinical Data; Patient Data is climbing the fastest as longitudinal tracking improves.
Service Type:
Outcome-based contracting is reshaping procurement patterns away from perpetual software licenses toward performance-linked analytics engagements.
- Analytics Services:Outcome-based contracts tie vendor compensation to measurable improvements in patient outcomes or operational efficiency. Federated learning architectures and privacy-preserving computation techniques are unlocking multi-party analytics previously blocked by HIPAA complexity.
- Data Integration:Middleware development for legacy EHR normalization commands premium fees from health systems operating decade-old Cerner or Epic instances.
- Data Hosting:Cloud-native platforms with embedded compliance tooling address EU AI Act algorithmic transparency requirements for European pharmaceutical sponsors.
- Consulting:Advisory engagements for consent architecture redesign and de-identification pipeline rebuilding are expanding under HIPAA interoperability mandates.
Deployment scale favors Data Integration; Analytics Services shows the steepest expansion trajectory.
End User:
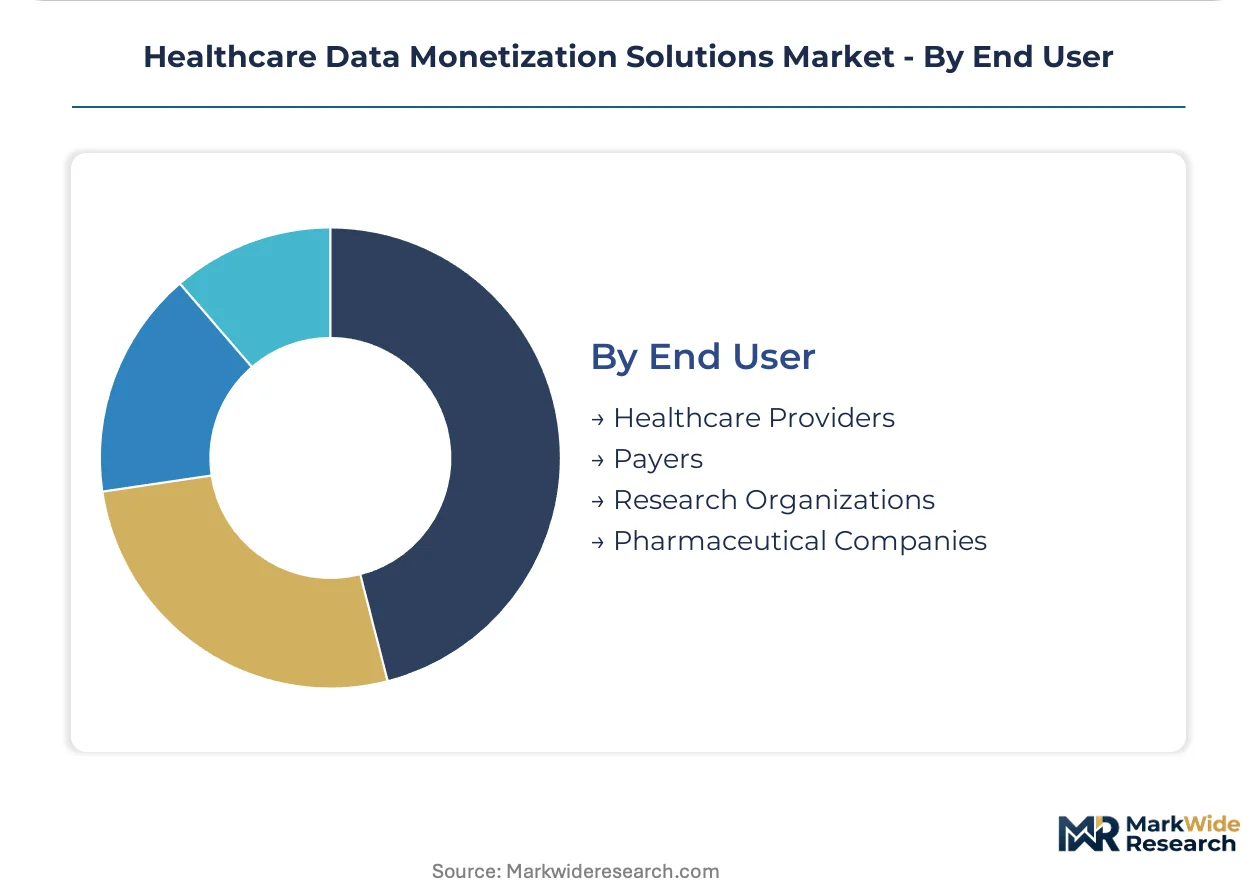
Pharmaceutical procurement teams are restructuring vendor relationships toward consumption-based models while payers seek social determinants analytics for Medicaid managed care.
- Pharmaceutical Companies:Real-world evidence mandates from the FDA are pulling manufacturers toward external control arm datasets and post-market surveillance registries. Unbundling of perpetual licenses favors flexible data marketplace integrations.
- Healthcare Providers:Integrated delivery networks in California and Texas are consolidating de-identified assets into commercializable repositories for life sciences contracting.
- Payers:Medicaid managed care organizations require population health analytics for dual-eligible populations under state-level social determinants reporting mandates.
- Research Organizations:Contract research organizations adopting synthetic data generation platforms are reducing dependency on retrospective clinical data licensing.
Contract value concentrates among Pharmaceutical Companies; Research Organizations are gaining share fastest through synthetic data adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Life sciences innovation zones in the United States and pharmaceutical clusters in Western Europe concentrate data monetization infrastructure through targeted R&D tax incentives and streamlined regulatory pathways.
United States
HIPAA interoperability mandates and FDA real-world evidence guidance pull pharmaceutical sponsors toward de-identified longitudinal datasets. Integrated delivery networks in California and Texas consolidate clinical assets into commercializable repositories. The FDA's expanded RWE submissions framework accelerates post-market surveillance registry development.
Germany
The EU AI Act's high-risk system classification forces algorithmic transparency tooling into clinical decision support platforms. Health technology vendors embed explainability modules to satisfy EMA documentation requirements. The Munich-Frankfurt corridor anchors federated learning partnerships between academic medical centers and pharmaceutical manufacturers.
United Kingdom
NHS data commercialization frameworks enable structured health record licensing for life sciences research. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit data governance with FDA equivalence pathways. London's digital health cluster concentrates cloud-native analytics platforms serving European pharmaceutical sponsors.
Switzerland
Swissmedic's regulatory-grade data provenance standards command premium licensing fees for clinical trial enrichment datasets. Basel's pharmaceutical headquarters density drives demand for multi-omic profiling integration with claims data. The country's bilateral EU agreements shape cross-border transfer architectures for unified data monetization platforms.
India
CDSCO's expanding real-world evidence acceptance for regulatory submissions creates export-oriented data services opportunities. Hyderabad and Bangalore clusters develop de-identification pipelines and differential privacy tooling for international pharmaceutical contracts. The country's IT services heritage supports cost-competitive analytics services delivery.
Healthcare Data Monetization Solutions Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with payer-provider integrated entities commanding risk-adjusted data products while pure-play analytics vendors capture outcome-based engagements. The market structure tiers across three concentrations: cloud-native platform operators, legacy EHR-integrated incumbents, and consulting-led system integrators. Consolidation pressures favor M&A activity targeting middleware capabilities for legacy health system normalization. Strategic partnerships between genomics laboratories and pharmaceutical sponsors reshape revenue-sharing arrangements.
Within the cloud-native platform tier, Innovaccer and Health Catalyst exemplify architectures built for health system interoperability and embedded compliance tooling. IQVIA anchors the real-world evidence registry segment through proprietary longitudinal datasets spanning multiple therapy areas. Optum occupies a distinct position leveraging payer-provider integration to dominate risk-adjusted data products for life sciences contracting.
| Leading Market Players |
|---|
| Innovaccer |
| Optum |
| IQVIA |
| Microsoft |
| Informatica |
| GE HealthCare Technologies |
| Health Catalyst |
| Accenture |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure costs for differential privacy compute cascade through pricing tiers, with pharmaceutical sponsors absorbing premium rates for regulatory-grade provenance while mid-tier health systems negotiate predictable subscription structures for population health analytics.
Pricing Analysis
Short lead-time delivery of FDA-ready real-world evidence datasets commands 40-60% pricing premiums over standard refresh cycles, while spot inventory of de-identified longitudinal records trades at discounted rates. Pricing stratifies across premium, standard, and economy tiers based on regulatory certification level and data provenance depth. Cost compression in the mid-market subscription segment is intensifying as cloud-native platform vendors compete for integrated delivery network contracts in Texas and California. Pharmaceutical procurement teams show lowest price sensitivity due to RWE submission deadlines, while regional payers serving Medicaid populations exhibit highest sensitivity to per-query costs.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO framework and data localization requirements under the EU AI Act are reshaping sourcing architectures for de-identification pipelines and federated learning infrastructure. Supply concentrates in the United States, India, and Germany for regulatory-grade data provenance and privacy-preserving computation tooling. Raw material dependencies span cloud compute capacity, specialized data governance engineering labor, and embedded compliance software modules. Single-source vulnerability sits with concentrated pools of algorithmic transparency architects capable of EU AI Act high-risk system implementation. Distribution runs through direct API integrations with electronic health record systems and enterprise sales cycles for academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as vendors pursue backward integration into proprietary real-world evidence registries to escape commodity analytics pricing.
For Market Incumbents: Anticipate synthetic data generation platforms capturing early-stage R&D budgets by embedding differential privacy tooling directly into pharmaceutical workflow suites. Defend position by acquiring middleware capabilities for decade-old Cerner and Epic normalization, locking in legacy health system data commercialization contracts. Prioritize certification investment for FDA regulatory-grade provenance standards to maintain pricing power against cloud-native challengers. For New Entrants and Emerging Players: Begin with Medicaid managed care analytics for dual-eligible populations, where state-level social determinants reporting mandates create procurement urgency without incumbent saturation. Target regional payers in California and Texas seeking consumption-based population health contracts. Pursue API-first distribution through electronic health record marketplace integrations to bypass traditional enterprise sales cycles. For Investors and Strategic Acquirers: FDA's expanded real-world evidence guidance for regulatory submissions is the leading indicator that pharmaceutical data procurement budgets are shifting from retrospective licensing to prospective registry partnerships. Position for 5-10 year viability by targeting acquisition profiles with embedded compliance tooling and federated learning architecture capabilities. Watch for cross-border data transfer agreement negotiations between the United States and European Union as the critical inflection signal for unified platform feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Registry Expansion | Proprietary longitudinal datasets spanning multiple therapy areas command premium pharmaceutical licensing rates. |
| Federated Learning Partnership | Privacy-preserving multi-party analytics unlock data partnerships previously blocked by HIPAA complexity. |
| Embedded Compliance Tooling Development | Algorithmic transparency modules satisfy EU AI Act high-risk system classification for European sponsors. |
| API-First Distribution Buildout | Direct electronic health record marketplace integrations displace traditional enterprise sales cycles. |
| Synthetic Data Generation Platform Launch | Statistically equivalent patient cohorts reduce pharmaceutical dependency on retrospective clinical licensing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across pharmaceutical R&D executives, health system chief data officers, payer population health directors, and data governance architects at cloud-native platform vendors. Secondary validation drew from FDA real-world evidence guidance documents, EU AI Act implementation texts, CMS Medicare claims databases, and hospital procurement records from integrated delivery networks. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Granularity-level modeling deployed delivery model, data type, service type, and end user dimensions at the country level, with regulatory framework clusters and health system IT maturity as cross-cutting variables. CAGRs were derived from trend extrapolation of pharmaceutical R&D outsourcing rates and health system data commercialization adoption curves across the projection horizon. Forecast inputs included FDA submission volume trends, HIPAA interoperability mandate implementation timelines, and synthetic data platform penetration rates in contract research organizations.
Underlying measurement precision varies by segment; clinical data and pharmaceutical end-user forecasts carry tighter precision than emerging synthetic data categories. Forecasts reflect documented assumptions regarding regulatory stability and cross-border data transfer feasibility. Unanticipated EU-US Data Privacy Framework successor negotiations or CDSCO real-world evidence acceptance shifts could materially revise trajectory projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Global Healthcare Customer Data Platform Market
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
United States Healthcare Big Data Analytics Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
US Population Health Management Market
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Global Healthcare Compliance Software Market
Health Data Management
North America Healthcare Analytics Market