
 Population Health Management (PHM) Market | 2026-2036
Population Health Management (PHM) Market Size, Share, and Industry Trends Forecast 2026-2036
Population Health Management (PHM) Market Intelligence
Platform unbundling into modular, best-of-breed components is rebalancing procurement decisions across health systems and physician groups. Epic Systems Corporation anchors inpatient electronic health record dominance while extending into ambulatory population health modules. Cerner Corporation leverages its federal health IT footprint to compete for government agency PHM contracts. Innovaccer specializes in cloud-native data aggregation layers that integrate disparate payer and provider sources into unified patient records.
Population health management encompasses the systematic application of data analytics, care coordination protocols, and patient engagement technologies to improve health outcomes across defined patient cohorts, typically operating through risk-stratification algorithms that segment populations by clinical complexity and cost trajectory. Cloud-based deployment modes are capturing the fastest expansion as health plans seek elastic infrastructure for seasonal enrollment fluctuations and predictive modeling workloads. Data analytics solutions occupy the deepest margin pools, particularly when bundled with utilization management applications that identify preventable emergency department visits and inpatient admissions.
FDA oversight of clinical decision support algorithms, HIPAA privacy and security requirements, and ONC interoperability certification standards collectively shape product architecture and market access for PHM vendors selling into US healthcare organizations. The Centers for Medicare & Medicaid Services value-based reimbursement rules, including the Medicare Shared Savings Program and MSSP direct contracting pathways, create compliance-driven demand for population-level reporting capabilities. Stakeholders must monitor how evolving federal algorithmic accountability requirements reshape vendor liability and platform validation protocols.
Market Dynamics
Cloud-native platform architectures are displacing on-premise PHM installations as health systems prioritize elastic infrastructure for seasonal enrollment spikes and predictive analytics workloads. This infrastructure shift compresses deployment timelines and forces legacy vendors to rearchitect around interoperability mandates.
Growth Catalysts
- Medicare Advantage enrollment expansion:CMS value-based reimbursement rules, including MSSP direct contracting pathways, compel provider networks to invest in population-level reporting infrastructure and risk-stratification capabilities.
- ONC interoperability certification standards:Federal mandates for seamless data exchange between disparate EHR systems accelerate platform modernization and create compliance-driven procurement cycles.
- Chronic disease management protocols:Healthcare provider networks deploy integrated PHM modules to coordinate care for diabetes, heart failure, and COPD populations across ambulatory and inpatient settings.
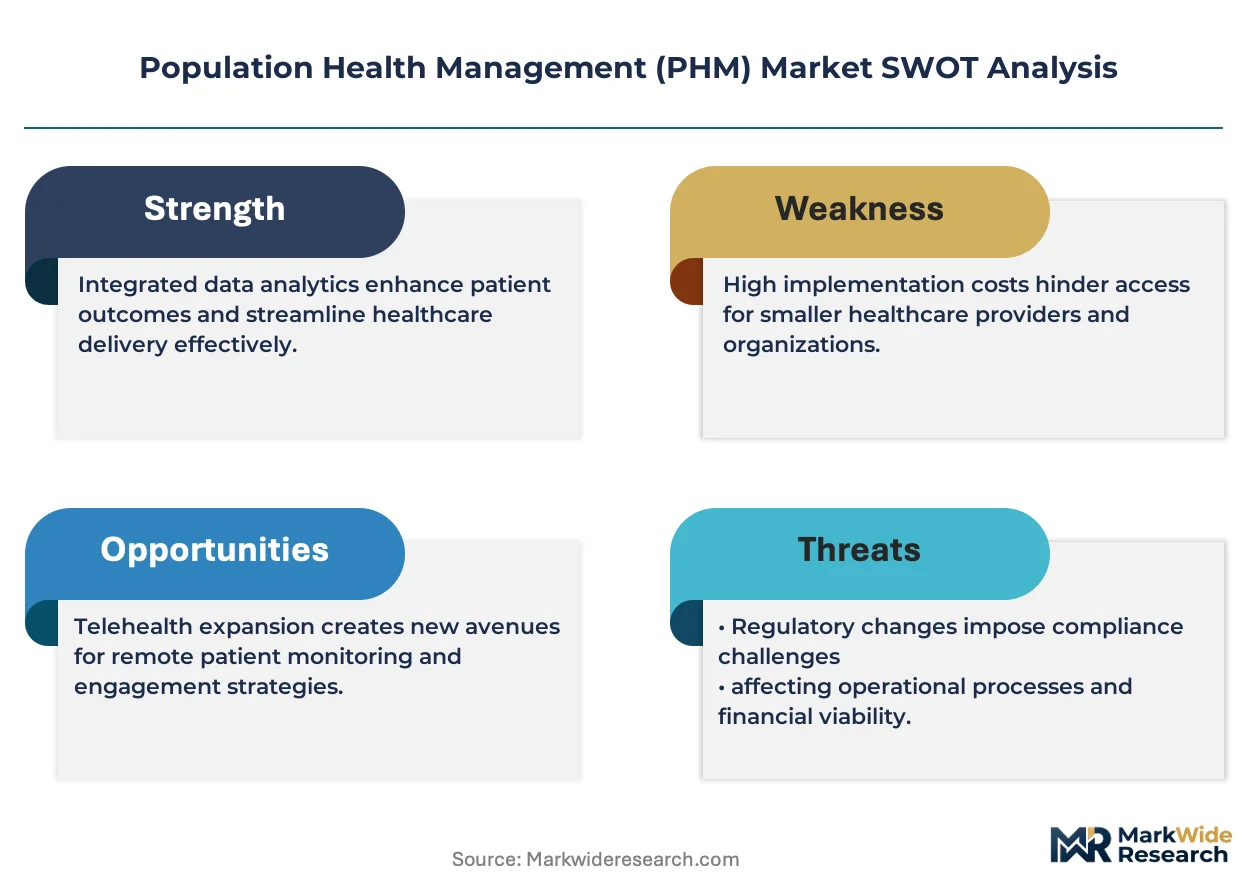
Market Restraints
- HIPAA privacy and security compliance costs:Encryption, audit trails, and breach notification infrastructure impose persistent operational overhead on cloud-based PHM deployments.
- Legacy system integration complexity:Health systems running decade-old EHR installations face prohibitive middleware costs when connecting to modern data aggregation layers.
- Specialized health informatics talent scarcity:Shortages of clinical data scientists and interoperability engineers constrain implementation velocity for mid-sized provider networks.
Strategic Opportunities
- Rural health clinic penetration:Federally qualified health centers in underserved US counties lack sophisticated PHM infrastructure, creating whitespace for modular, lower-cost deployments.
- Social determinants of health integration:Convergence of clinical EHR data with housing, transportation, and food security databases enables predictive models for readmission risk.
- Medicaid managed care expansion:State-level contracts for dual-eligible populations reward vendors delivering closed-loop referral management and community resource coordination.
Industry Challenges
- FDA algorithmic validation timelines:Clinical decision support tools embedded in PHM platforms face prolonged review cycles for software-as-medical-device classification.
- Multi-payer data normalization:Health systems must reconcile conflicting quality metrics from Medicare, Medicaid, and commercial payers within unified reporting dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Population Health Management (PHM) Market |
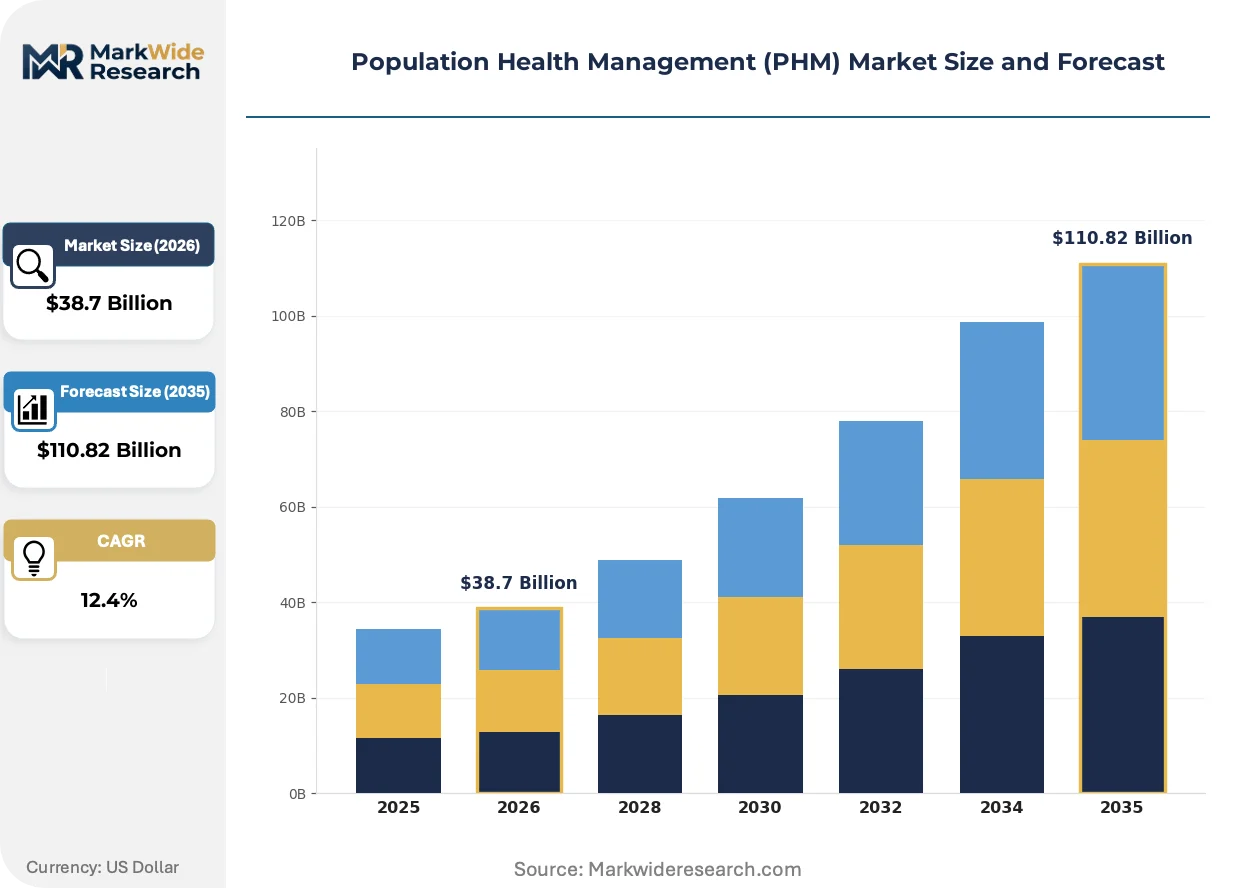
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $110.82 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Risk Stratification, Care Coordination, Patient Engagement, Data Analytics, Predictive Modeling Deployment Mode: On-Premise, Cloud-Based, Hybrid, SaaS, Managed Services Application Area: Chronic Disease Management, Wellness Programs, Population Analytics, Care Gap Identification, Utilization Management End User Segment: Health Plans, Physician Groups, Accountable Care Organizations, Employer Health Programs, Government Agencies |
| Companies Covered | Optum, Inc., McKesson Corporation, Athenahealth, Inc., Cerner Corporation, Oracle, Conifer Health Solutions, LLC, Epic Systems Corporation, Veradigm LLC, Innovaccer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Population Health Management (PHM) Market Strategic Shifts & Innovations
Artificial intelligence and machine learning capabilities are embedding into PHM workflows, transforming retrospective reporting into prospective intervention targeting. Vendors race to differentiate through predictive accuracy and explainable algorithmic outputs.
Real-world evidence platforms are expanding into prospective patient identification, enabling care managers to surface high-risk individuals before acute events. Medicare Advantage plans deploy these tools across millions of covered lives. The technology is compressing the gap between analytics insight and care team action.
ONC's 21st Century Cures Act information blocking rules mandate immediate patient record access, forcing PHM vendors to rebuild data pipelines around standardized APIs. Provider organizations face penalties for interoperability failures. Ambulatory networks with fragmented EHR estates experience the steepest compliance burden.
Subscription-based platform licensing is displacing perpetual software purchases as health systems prioritize operational expenditure flexibility. Physician groups and independent practice associations favor per-member-per-month pricing aligned with value-based contract revenue cycles. This shift concentrates most visibly in California and New York markets with mature accountable care organization penetration.
Population Health Management (PHM) Market Segmentation
PHM procurement patterns diverge sharply across buyer sophistication levels and technical infrastructure maturity. Solution architecture, hosting economics, clinical use case, and organizational scale each create distinct purchasing segments with incompatible vendor evaluation criteria.
Solution Type:
Provider networks select modules based on where they sit in value-based contract maturity.
- Data Analytics:Platforms aggregate claims, clinical, and social determinants data into unified dashboards for risk scoring. Medicare Advantage plans in Florida and Texas deploy these tools across millions of covered lives to identify high-cost cohorts before acute events.
- Care Coordination:Workflow engines route tasks across nursing teams, pharmacists, and community health workers. Large physician groups in California use these modules to close referral loops and reduce emergency department utilization among diabetic populations.
- Risk Stratification:Algorithms segment populations by predicted cost and clinical complexity.
- Patient Engagement:Portals and mobile applications drive adherence through automated outreach.
- Predictive Modeling:Machine learning forecasts readmission probability and disease progression.
Data analytics leads volumes today; predictive modeling is gaining share fastest.
Deployment Mode:
Hosting decisions track IT staff capacity and seasonal enrollment volatility.
- Cloud-Based:Elastic infrastructure scales compute resources during annual Medicare Advantage open enrollment periods. Health plans favor this architecture for predictive modeling workloads that spike quarterly.
- SaaS:Subscription licensing eliminates capital expenditure approval cycles. Independent practice associations in New York prefer per-member-per-month pricing aligned with value-based revenue timing.
- On-Premise:Legacy health systems with decade-old EHR investments retain controlled environments.
- Hybrid:Split architectures keep sensitive data local while pushing analytics to cloud.
- Managed Services:Vendors operate infrastructure and staff applications on behalf of buyers.
Cloud-based deployments dominate new procurement; SaaS pricing models are climbing fastest among physician groups.
Application Area:
Clinical priorities vary by payer mix and disease burden concentration.
- Chronic Disease Management:Integrated protocols coordinate diabetes, heart failure, and COPD care across ambulatory and inpatient settings. Federally qualified health centers deploy these modules to meet CMS quality metrics.
- Utilization Management:Real-time alerts flag preventable emergency department visits and inpatient admissions. Medicaid managed care plans use these tools to steer members toward lower-cost care settings.
- Population Analytics:Retrospective reporting identifies care gaps and cost drivers.
- Wellness Programs:Preventive interventions target lifestyle modification and screening compliance.
- Care Gap Identification:Automated queries surface missing screenings or vaccinations.
Chronic disease management anchors current spending; utilization management is expanding most quickly as value-based contracts mature.
End User Segment:
Organizational scale determines platform complexity and integration requirements.
- Health Plans:Medicare Advantage and Medicaid managed care organizations require enterprise-scale platforms spanning millions of members. These buyers prioritize predictive accuracy and regulatory reporting automation.
- Accountable Care Organizations:MSSP participants need population-level infrastructure to track shared savings performance. ACOs in Massachusetts and California drive demand for modular, best-of-breed components.
- Physician Groups:Independent practices seek lightweight, EHR-integrated tools.
- Employer Health Programs:Self-insured corporations contract directly for employee population management.
- Government Agencies:Federal health IT and state Medicaid programs procure through specialized contracting vehicles.
Health plans command the largest contract values; accountable care organizations are adding users fastest as MSSP enrollment expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Population health management platforms first achieved scale in the United States through Medicare Advantage risk-contracting pilots. Geographic expansion now tracks value-based reimbursement maturity and interoperability infrastructure readiness.
United States
Medicare Advantage enrollment growth and MSSP direct contracting pathways drive provider investment in risk-stratification infrastructure. HIPAA privacy requirements and ONC interoperability certification standards shape procurement decisions. The Boston-Cambridge corridor hosts concentrated health informatics talent pools developing predictive modeling capabilities.
Germany
Statutory health insurance funds are piloting integrated care contracts modeled on US accountable care organizations. The EU AI Act and GDPR compliance frameworks constrain algorithmic clinical decision support deployment. Berlin hosts emerging digital health clusters focused on chronic disease management protocols.
United Kingdom
NHS Integrated Care Systems are consolidating fragmented primary care data into population-level analytics platforms. NHS Digital interoperability standards and MHRA software-as-medical-device guidance regulate platform architecture. London's health tech corridor attracts vendors targeting NHS Long Term Plan targets.
Canada
Provincial health authorities are modernizing chronic disease registries through cloud-native data aggregation layers. Health Canada and provincial privacy commissioners enforce sector-specific health information protection standards. Toronto-Waterloo corridor clusters concentrate PHM implementation expertise serving Ontario Health Teams.
Australia
Primary Health Networks are deploying care coordination platforms to manage regional chronic disease burdens. The Australian Digital Health Agency interoperability framework and TGA software regulations shape vendor market access. Melbourne and Sydney host concentrated digital health implementation capacity.
Population Health Management (PHM) Market Key Industry Players
Premium-margin players sit above commodity-margin players across data analytics sophistication and care coordination workflow depth. The vendor base stratifies between enterprise-scale platform consolidators and modular best-of-breed specialists. Three archetypes dominate: EHR-anchored incumbents extending into population modules, cloud-native data aggregation specialists, and payer-owned integrated service platforms. Competitive moves concentrate on interoperability certification racing and value-based contract outcome guarantees.
Within the EHR-anchored tier, Epic Systems Corporation and Cerner Corporation exemplify platform consolidation strategies extending inpatient dominance into ambulatory population health. Cloud-native specialists include Innovaccer, which occupies a position representing modular data layer approaches integrating disparate payer and provider sources. Optum, Inc. anchors the payer-integrated archetype combining insurance operations with technology platform ownership.
| Leading Market Players |
|---|
| Optum, Inc. |
| McKesson Corporation |
| Athenahealth, Inc. |
| Cerner Corporation |
| Oracle |
| Conifer Health Solutions, LLC |
| Epic Systems Corporation |
| Veradigm LLC |
| Innovaccer |
| Others |
Cost & Logistics Intelligence
Cloud-native platform migrations are compressing infrastructure economics while redistributing vendor margin pools toward interoperability-certified modules. This technology shift simultaneously lowers deployment barriers for mid-sized buyers and concentrates pricing power among vendors with federal certification credentials.
Pricing Analysis
Subscription-based SaaS licensing with per-member-per-month tiers anchors PHM procurement across health plans and physician groups. Price differentiation hinges on ONC certification status and predictive model accuracy guarantees, with premium tiers commanding substantial markups for real-time risk scoring. Cost compression in standard-tier offerings is intensifying as cloud infrastructure commoditizes base analytics capabilities. Federally qualified health centers exhibit highest price sensitivity, while Medicare Advantage plans prioritize outcome guarantees over unit cost.
Supply Chain Analysis
Direct-to-health-system channels handle enterprise-scale deployments, while value-added resellers serve independent practice associations. Software development concentrates in the United States, India, and Germany, with clinical data science talent pools anchoring delivery capacity. Platform architecture draws from open-source analytics libraries, cloud hyperscaler infrastructure, and proprietary algorithmic IP. Single-source vulnerability in specialized health informatics labor constrains implementation velocity. Distribution runs through EHR vendor marketplaces, GPO contracting vehicles, and direct sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PHM vendor margins are expanding through outcome-based contract structures that align platform fees with shared savings realization. Cloud delivery economics and modular componentization enable tiered service models that capture premium pricing from sophisticated buyers.
For Market Incumbents: Lock in EHR-anchored positions by accelerating interoperability certification for 21st Century Cures Act compliance. Deepen cloud-native rearchitecture to defend against modular specialists encroaching on data aggregation layers. Priority lever: vertical integration into care coordination workflow engines. For New Entrants and Emerging Players: Enter via rural health clinic whitespace where legacy infrastructure gaps create low-competition deployment opportunities. Target Federally Qualified Health Centers in underserved counties with modular, lower-cost chronic disease management modules. Go-to-market angle: per-member-per-month pricing aligned with Medicaid managed care contract cycles. For Investors and Strategic Acquirers: Roll-up economics work for cloud-native data aggregation specialists because health system demand for unified payer-provider records outstocks organic vendor development capacity. Long-term viability centers on platforms with proven Medicare Advantage outcomes. Acquisition target archetype: interoperability-certified modules with established MSSP track records. Signal to watch: FDA software-as-medical-device classification timelines for clinical decision support tools.| Strategic Initiative | Industry Significance |
|---|---|
| ONC Interoperability Certification | Federal certification unlocks Medicare Advantage procurement and shields against information blocking penalties. |
| Cloud-Native Platform Rebuild | Elastic infrastructure captures seasonal enrollment volatility and predictive analytics workload spikes. |
| Social Determinants Data Integration | Convergence with housing and food security databases enables readmission risk models that differentiate pricing. |
| Care Coordination Workflow Acquisition | Closed-loop referral management capabilities secure Medicaid managed care contracts in dual-eligible populations. |
| AI/ML Explainability Investment | Transparent algorithmic outputs satisfy emerging federal accountability requirements and reduce liability exposure. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from health system CIOs, Medicare Advantage plan actuaries, ONC policy specialists, and care coordination program directors. Secondary validation drew from CMS Medicare data releases, hospital procurement databases, GPO contract filings, and ONC certification records. Bottom-up deployment tracking and top-down reimbursement trend analysis were triangulated against vendor revenue disclosures.
Segment-weighting applied deployment mode, solution type, and end user scale dimensions across the projection horizon. Modeled categories included cloud-based versus on-premise hosting, data analytics versus care coordination modules, and health plan versus ACO versus physician group procurement patterns. CAGRs were derived from elasticity modeling against Medicare Advantage enrollment trajectories and MSSP participation curves.
Inputs from federal health IT agencies and state Medicaid programs were available through the study window; gaps in proprietary vendor pricing data introduce uncertainty bands around contract value estimates. Forecasts reflect assumptions regarding interoperability mandate enforcement timelines and value-based reimbursement expansion velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
North America Healthcare Analytics Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Healthcare Data Annotation Tools Market
Health Data Management
Big Data Healthcare Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
US Mobile Health Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
Master Data Management in Healthcare Market