
 Global Healthcare Fraud Analytics Market | 2026-2036
Global Healthcare Fraud Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Fraud Analytics Market Foresight
Modular bundling of fraud detection with payment integrity suites is restructuring how payers evaluate vendor proposals. SAS Institute Inc. leverages deep statistical heritage to anchor high-complexity government contracts. Cotiviti Inc. specializes in payment accuracy layers that extend into adjacent revenue integrity functions. International Business Machines Corporation competes through Watson Health integrations that occupy enterprise-scale infrastructure bids.
Healthcare fraud analytics encompasses algorithmic systems that examine claims patterns, provider behaviors, and enrollment data to identify financial abuse or waste in health financing. These platforms apply machine learning classifiers, network graph analysis, and rules-based scoring to flag suspicious transactions before payment settlement, with latency requirements often measured in sub-second response windows for real-time claims adjudication. Predictive analytics solutions dominate current revenue pools as mature regression and ensemble methods command established pricing premiums. Cloud-based deployment modes represent the fastest-expanding configuration as HIPAA-compliant infrastructure from Amazon Web Services and Microsoft Azure reduces capital barriers for mid-market payers. Claims management applications sustain the largest addressable spend because every processed claim generates a scoring event that consumes software capacity.
The Centers for Medicare & Medicaid Services enforces mandatory fraud detection protocols through its Unified Program Integrity Contractors, while the Department of Justice coordinates civil monetary penalties that create direct financial exposure for non-compliant insurers. State insurance commissioners in California, New York, and Texas supplement federal requirements with distinct prior authorization monitoring rules that fragment vendor certification pathways. Stakeholders must monitor how artificial intelligence disclosure requirements from the FDA and emerging state-level algorithmic accountability statutes reshape model documentation burdens and procurement specifications.
Market Dynamics
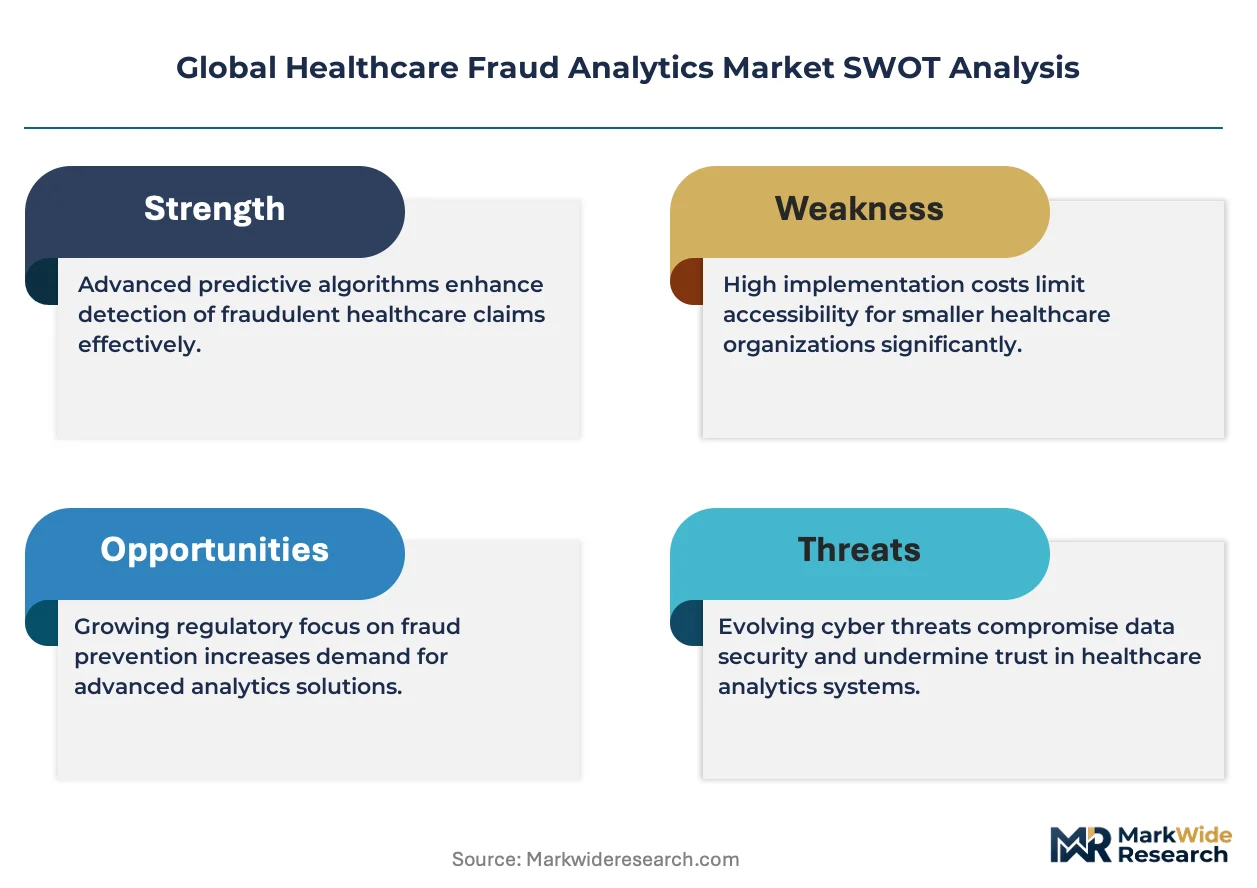
Cloud-native deployment architectures are compressing procurement cycles for mid-market payers while mandating sub-second latency thresholds that reshape vendor technical requirements.
Growth Catalysts
- HIPAA-compliant infrastructure expansion:Amazon Web Services and Microsoft Azure reduce capital barriers for regional insurers. Cloud eligibility unlocks real-time claims scoring for previously excluded payers.
- United States fraud detection mandates:The Centers for Medicare & Medicaid Services enforces mandatory protocols through Unified Program Integrity Contractors. Direct financial exposure from civil monetary penalties accelerates vendor adoption.
- Graph neural network classifiers:These algorithms detect collusion rings and phantom billing patterns with higher precision than rules-based systems. Payers in Germany deploy them for provider network monitoring.
Market Restraints
- Data localization requirements:India's data protection rules and Germany's Federal Data Protection Act fragment cloud hosting architectures. Vendors must replicate infrastructure across sovereign jurisdictions.
- Model explainability deficits:Black-box ensemble methods face rejection from state insurance commissioners requiring audit trails. California's prior authorization monitoring rules demand interpretable scoring logic.
- Specialized talent scarcity:Health informaticists with dual expertise in clinical coding and machine learning engineering command premium compensation. Recruitment friction delays implementation timelines.
Strategic Opportunities
- India's fraud detection mandate expansion:The Insurance Regulatory and Development Authority strengthens claim verification requirements. Domestic insurers seek affordable cloud-native platforms.
- Convergence of fraud analytics with revenue integrity:Payment accuracy layers extend into clinical documentation improvement and contract modeling. Cotiviti Inc. anchors this bundling strategy.
- Real-time prior authorization integration:Texas and New York require automated decision support for high-cost procedures. Vendors embedding scoring into authorization workflows capture sticky relationships.
Industry Challenges
- Legacy claims platform integration:Core administrative processing systems from the 1990s lack API architectures. Middleware development consumes 40% of implementation budgets.
- Algorithmic accountability documentation:The FDA's artificial intelligence disclosure requirements and emerging state statutes impose model lineage burdens. Engineering teams must retrofit audit infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Fraud Analytics Market |
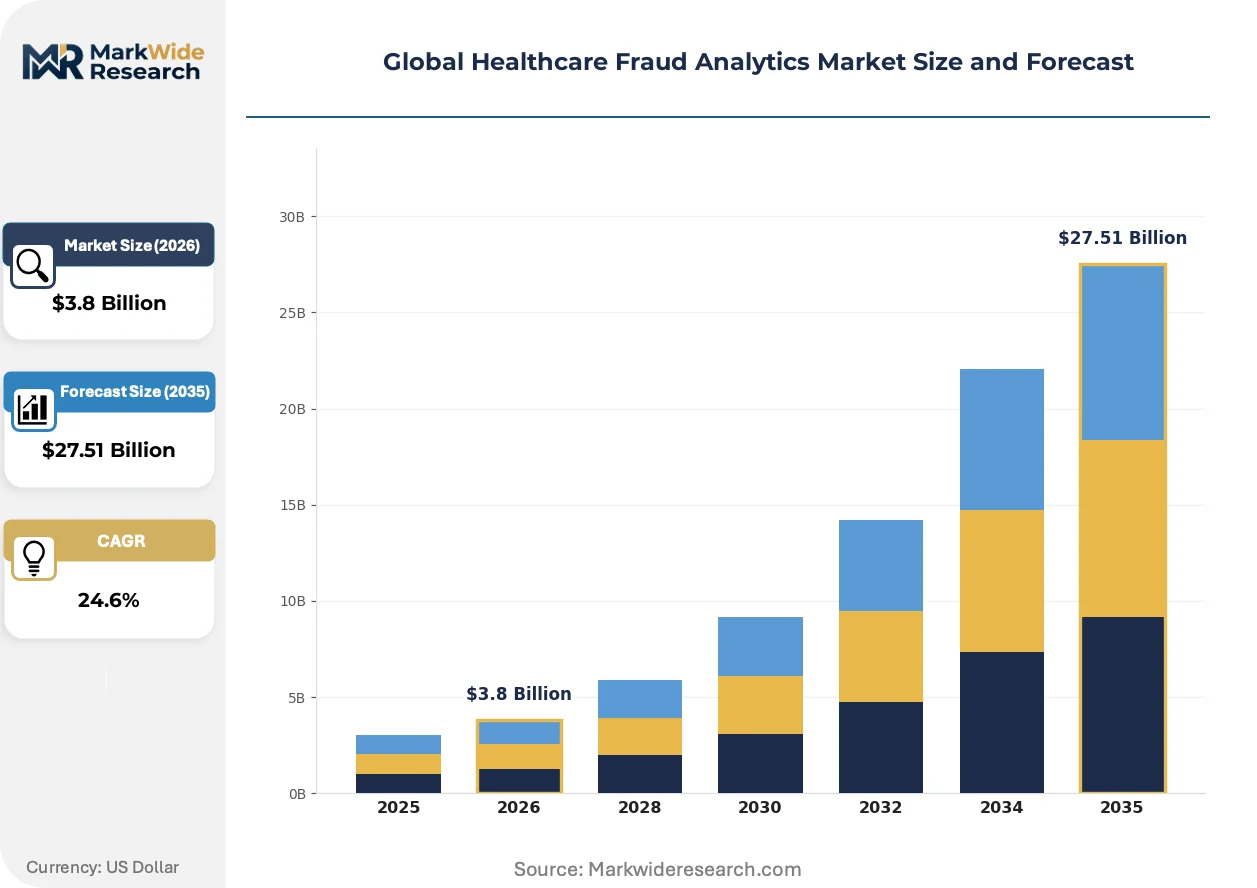
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Predictive Analytics, Anomaly Detection, Risk Scoring, Natural Language Processing, Machine Learning, Data Mining Application: Claims Management, Member Enrollment Verification, Provider Credentialing, Payment Integrity, Utilization Review, Compliance Monitoring Deployment Mode: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Insurance Companies, Government Agencies, Healthcare Providers, Third-Party Administrators, Regulatory Authorities |
| Companies Covered | SAS Institute Inc., Cotiviti Inc., International Business Machines Corporation, Change Healthcare, Wipro Limited, Optum Inc., EXL Service Holdings Inc., Fair Isaac Corporation, DXC Technology Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Fraud Analytics Market Shifts & Advancements
Machine learning operations pipelines and federated learning architectures are compressing model deployment cycles while fragmenting how payers source analytical capabilities.
Federated learning is integrating sensitive claims data across payer networks without centralizing raw records. Large national insurers in the United States pilot this architecture for cross-plan fraud pattern detection. The technology is integrating privacy-preserving analytics that previously required prohibitive data-sharing agreements.
The EU AI Act imposes risk classification requirements on automated decision systems affecting insurance eligibility. Healthcare fraud scoring algorithms face mandatory conformity assessments and human oversight provisions. European payers are restructuring procurement specifications to include algorithmic impact documentation.
Subscription-based platform licensing is displacing perpetual software purchases among mid-market payers. Vendor commercial teams in Germany and India now lead with consumption-priced tiers tied to claim volume. This shift concentrates contract value in implementation services and ongoing model retraining engagements.
Global Healthcare Fraud Analytics Market Segmentation
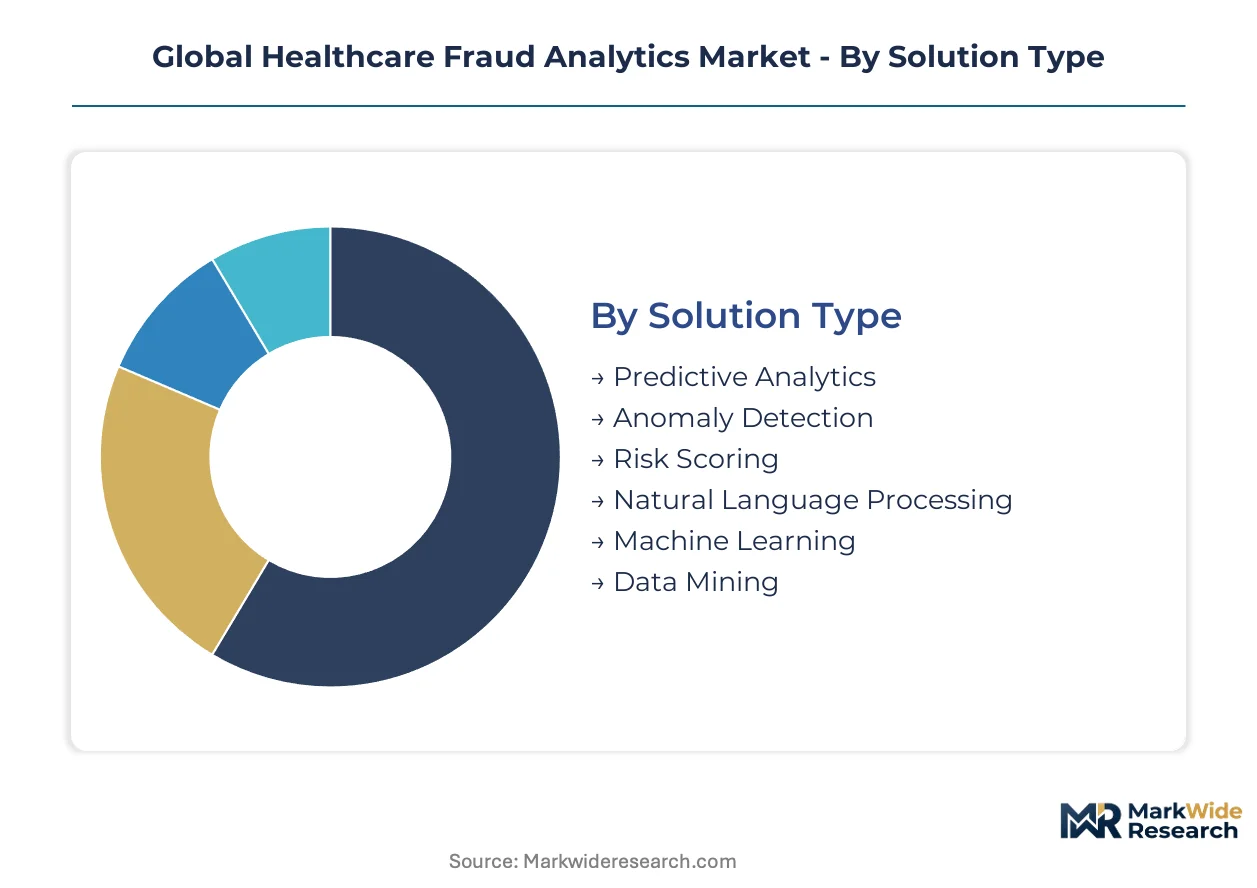
Healthcare fraud analytics vendors configure product architectures around distinct operational workflows and infrastructure constraints. Procurement patterns diverge sharply between real-time claims adjudication systems and retrospective audit platforms. Buyers prioritize solution bundles that align with their existing IT maturity and regulatory exposure profiles.
Solution Type:
Payers differentiate procurement priorities based on algorithmic sophistication requirements and explainability mandates.
- Predictive Analytics:Regression and ensemble methods forecast fraud probability before claim settlement. United States Medicare Advantage plans deploy these systems for pre-payment scoring under CMS Unified Program Integrity Contractor protocols.
- Anomaly Detection:Statistical deviation algorithms flag outliers in provider billing patterns. German sickness funds apply these tools for phantom billing detection within statutory health insurance networks.
- Risk Scoring:Composite indices aggregate multiple fraud indicators into tiered alert classifications.
- Natural Language Processing:Text mining extracts suspicious patterns from clinical documentation and provider correspondence.
- Machine Learning:Supervised and unsupervised classifiers automate pattern recognition across high-volume claims datasets.
- Data Mining:Exploratory analytics uncover hidden relationships in historical claims archives.
Predictive analytics leads volumes today; machine learning is gaining share fastest.
Application:
Functional use cases map directly to payer operational cost centers and regulatory audit exposure.
- Claims Management:Real-time scoring engines evaluate every transaction during adjudication workflows. United States commercial insurers process billions of annual claims through these systems to satisfy sub-second latency requirements.
- Member Enrollment Verification:Identity validation algorithms prevent synthetic identity fraud during plan onboarding. India's Insurance Regulatory and Development Authority mandates enhanced verification for government-sponsored health schemes.
- Provider Credentialing:Automated verification of practitioner licenses and exclusion list screening.
- Payment Integrity:Post-payment recovery analytics identify overpayments and coordinate clawback workflows.
- Utilization Review:Clinical appropriateness algorithms flag services exceeding evidence-based guidelines.
- Compliance Monitoring:Continuous surveillance against federal and state fraud detection mandates.
Claims management anchors current procurement budgets; payment integrity is expanding most quickly.
Deployment Mode:
Infrastructure choices reflect data sovereignty requirements and capital expenditure constraints.
- Cloud-Based:HIPAA-compliant infrastructure from Amazon Web Services and Microsoft Azure eliminates server procurement cycles. Mid-market United States payers adopt these configurations to access real-time scoring without legacy modernization costs.
- On-Premises:Self-hosted installations satisfy strict data localization mandates. German Federal Data Protection Act requirements drive this preference among statutory health insurers.
- Hybrid:Split architectures process sensitive data locally while leveraging cloud compute for non-critical analytics.
- Managed Services:Vendor-operated deployments transfer operational responsibility to specialized service teams.
Cloud-based deployment leads new contract signings; hybrid architectures are climbing fastest among multi-national payers.
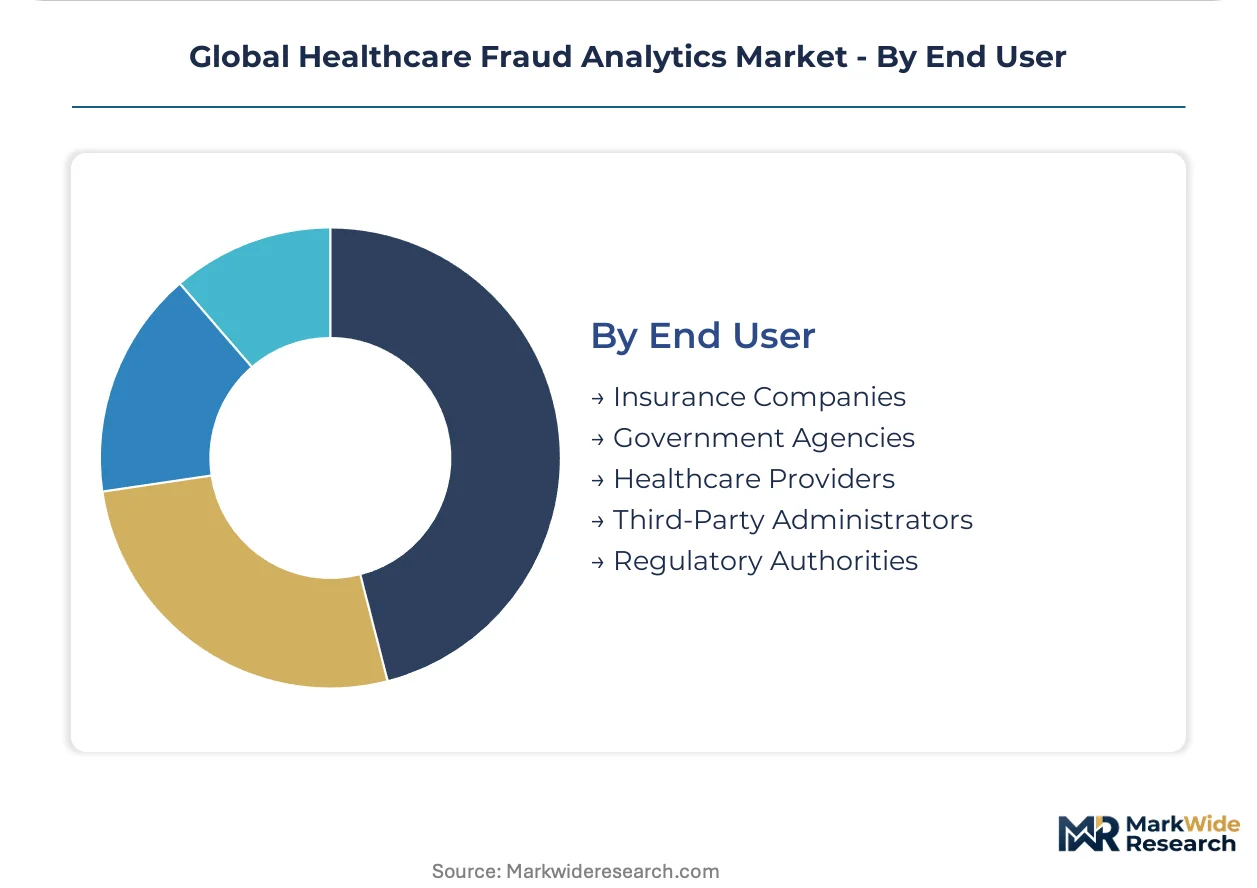
End User:
Stakeholder categories vary by procurement authority and fraud detection mandate intensity.
- Insurance Companies:Commercial and government-sponsored plans represent the primary revenue pool. United States Blue Cross Blue Shield plans and German BARMER dominate vendor contract values through enterprise-scale implementations.
- Government Agencies:National health programs and social insurance administrations mandate standardized detection protocols. India's National Health Authority deploys centralized fraud analytics for Ayushman Bharat scheme integrity.
- Healthcare Providers:Hospital systems and physician networks implement defensive analytics to preempt audit exposure.
- Third-Party Administrators:Benefits management firms embed fraud detection into outsourced claims processing services.
- Regulatory Authorities:State insurance commissioners and fraud control units deploy surveillance tools for market oversight.
Insurance companies dominate current spending; government agencies are expanding procurement most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The healthcare fraud analytics industry originated in the United States during the 1990s commercial insurance digitization wave, then expanded through German statutory health insurance reforms and India's recent universal health coverage initiatives.
United States
Commercial insurers and Medicare Advantage plans drive procurement volumes through real-time claims adjudication mandates. The Centers for Medicare & Medicaid Services enforces detection protocols via Unified Program Integrity Contractors with civil monetary penalty exposure. Healthcare technology clusters in Boston and Minneapolis-St. Paul host vendor implementation teams serving Blue Cross Blue Shield plans.
Germany
Statutory health insurers deploy graph neural networks for phantom billing detection across regional provider networks. The Federal Data Protection Act mandates on-premises data hosting for sickness funds. Berlin and Munich concentrate vendor development centers serving BARMER and other major insurers with hybrid cloud architectures.
India
Domestic insurers seek affordable cloud-native platforms as the Insurance Regulatory and Development Authority tightens claim verification for Ayushman Bharat. National data localization rules require sovereign infrastructure replication. Hyderabad and Bengaluru emerge as implementation hubs for National Health Authority fraud surveillance systems.
United Kingdom
NHS Digital procurement frameworks prioritize algorithmic explainability for clinical decision support integration. The EU AI Act conformity assessments reshape vendor documentation requirements for automated eligibility scoring. London health technology clusters attract platform vendors serving integrated care systems.
Canada
Provincial health plans pilot federated learning architectures for cross-jurisdictional fraud pattern detection without centralized data pooling. Health Canada coordinates federal-provincial alignment on AI disclosure standards. Toronto-Waterloo corridor hosts machine learning operations specialists serving Ontario Health and provincial insurers.
Global Healthcare Fraud Analytics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across implementation complexity and regulatory certification depth. The vendor base stratifies between enterprise-scale platform providers and specialized payment integrity boutiques. Three archetypes dominate: statistical heritage specialists anchoring government contracts, payment accuracy layer extenders bundling adjacent revenue functions, and cloud-native challengers compressing procurement cycles for mid-market payers. Consolidation pressure intensifies through strategic partnerships with hyperscale cloud providers and vertical capability acquisitions.
Within the statistical heritage tier, SAS Institute Inc. occupies a position exemplifying deep methodological anchoring in high-complexity government procurement. Cotiviti Inc. and International Business Machines Corporation represent divergent bundling strategies—Cotiviti exemplifying payment accuracy layer extension into revenue integrity, IBM occupying enterprise-scale infrastructure bids through Watson Health integrations. These three anchors illustrate how vendor archetypes map to distinct buyer risk profiles and IT maturity levels across United States, German, and Indian payer markets.
| Leading Market Players |
|---|
| SAS Institute Inc. |
| Cotiviti Inc. |
| International Business Machines Corporation |
| Change Healthcare |
| Wipro Limited |
| Optum Inc. |
| EXL Service Holdings Inc. |
| Fair Isaac Corporation |
| DXC Technology Company |
| Others |
Supply & Pricing Matrix
Performance-grade bifurcation between real-time claims scoring engines and retrospective audit platforms manifests in both pricing stratification and supply chain sourcing patterns. Premium-tier vendors command subscription multiples tied to sub-second latency guarantees and HIPAA-compliant cloud infrastructure, while commodity audit tools compete on per-claim processing fees.
Pricing Analysis
Consumption-priced SaaS tiers tied to claim volume dominate new contract signings among mid-market United States payers. Price differentiation rests on algorithmic explainability certification and cloud-native architecture maturity. Pricing pressure stems from hyperscale cloud providers bundling fraud detection into broader healthcare data platforms. Regional insurers in India exhibit highest price sensitivity; Medicare Advantage plans demonstrate lowest sensitivity due to civil monetary penalty exposure.
Supply Chain Analysis
Freight costs for specialized hardware accelerators and edge computing nodes remain negligible relative to total procurement spend in this software-intensive market. Algorithm development concentrates in the United States, Germany, and India. Cloud infrastructure draws from Amazon Web Services and Microsoft Azure data centers. Single-source vulnerability rests on NVIDIA GPU supply constraints for graph neural network training. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as payers shift procurement criteria toward algorithmic auditability and real-time integration depth over raw detection accuracy.
For Market Incumbents: Anticipate margin compression from hyperscale cloud providers embedding fraud detection into platform bundles. Defend position by deepening vertical integration into clinical documentation improvement workflows and securing Unified Program Integrity Contractor recertification ahead of CMS mandate expansions. Prioritize MLOps infrastructure investments that compress model retraining cycles for sticky payer relationships. For New Entrants and Emerging Players: Capture white-space in India's Ayushman Bharat fraud surveillance systems where domestic insurers seek affordable cloud-native platforms. Target mid-market United States regional carriers excluded from legacy vendor enterprise pricing tiers. Lead with federated learning architectures that resolve data-sharing friction across payer networks without centralizing raw claims records. For Investors and Strategic Acquirers: Consolidation pressure builds where payment integrity boutiques lack capital to fund HIPAA-compliant cloud infrastructure and MLOps platform development. Long-term viability favors vendors with dual expertise in clinical coding and machine learning engineering. Watch for inflection when state insurance commissioners mandate interpretable scoring logic as a procurement prerequisite.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Architecture Deployment | Enables cross-payer fraud pattern detection without centralized data pooling under HIPAA constraints. |
| HIPAA-Compliant Cloud Infrastructure Expansion | Unlocks real-time claims scoring for mid-market payers previously excluded by capital barriers. |
| Graph Neural Network Classifier Development | Detects collusion rings and phantom billing with precision exceeding rules-based CMS protocols. |
| Payment Integrity Suite Bundling | Extends fraud detection into clinical documentation improvement and contract modeling revenue streams. |
| Algorithmic Explainability Certification | Satisfies California prior authorization monitoring rules and emerging EU AI Act conformity assessments. |
Research Methodology
Direct dialogue with fraud analytics product managers, health informaticists, CMS program integrity contractors, and hospital GPO contracts managers grounded qualitative findings. Secondary validation drew from CMS Medicare data, SEC 10-K filings of publicly traded vendors, and Insurance Regulatory and Development Authority mandate documentation. Bottom-up sizing of vendor contract values triangulated against top-down payer IT spending benchmarks across the analysis window.
Segmented outputs across solution type, deployment mode, and end-user category informed the analytical framework throughout the projection horizon. CAGRs derived from regression against historical adoption curves and regulatory mandate implementation timelines. Industry-specific inputs included Unified Program Integrity Contractor procurement volumes and cloud infrastructure capex disclosures from Amazon Web Services and Microsoft Azure.
Regulatory mandate delays, hyperscale cloud provider bundling acceleration, and specialized talent scarcity are the dominant revision risks for forecast trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
Global Healthcare Content Management System Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
US Population Health Management Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
Point-Of-Care Data Management Software Market
Health Data Management
Big Data Healthcare Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
Clinical Data Management Systems (CDMS) Market
Health Data Management
United States Healthcare Big Data Analytics Market
Health Data Management
Patient Data Management Software Market