
 Healthcare Data Collection and Labeling Market | 2026-2036
Healthcare Data Collection and Labeling Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Data Collection and Labeling Market Intelligence
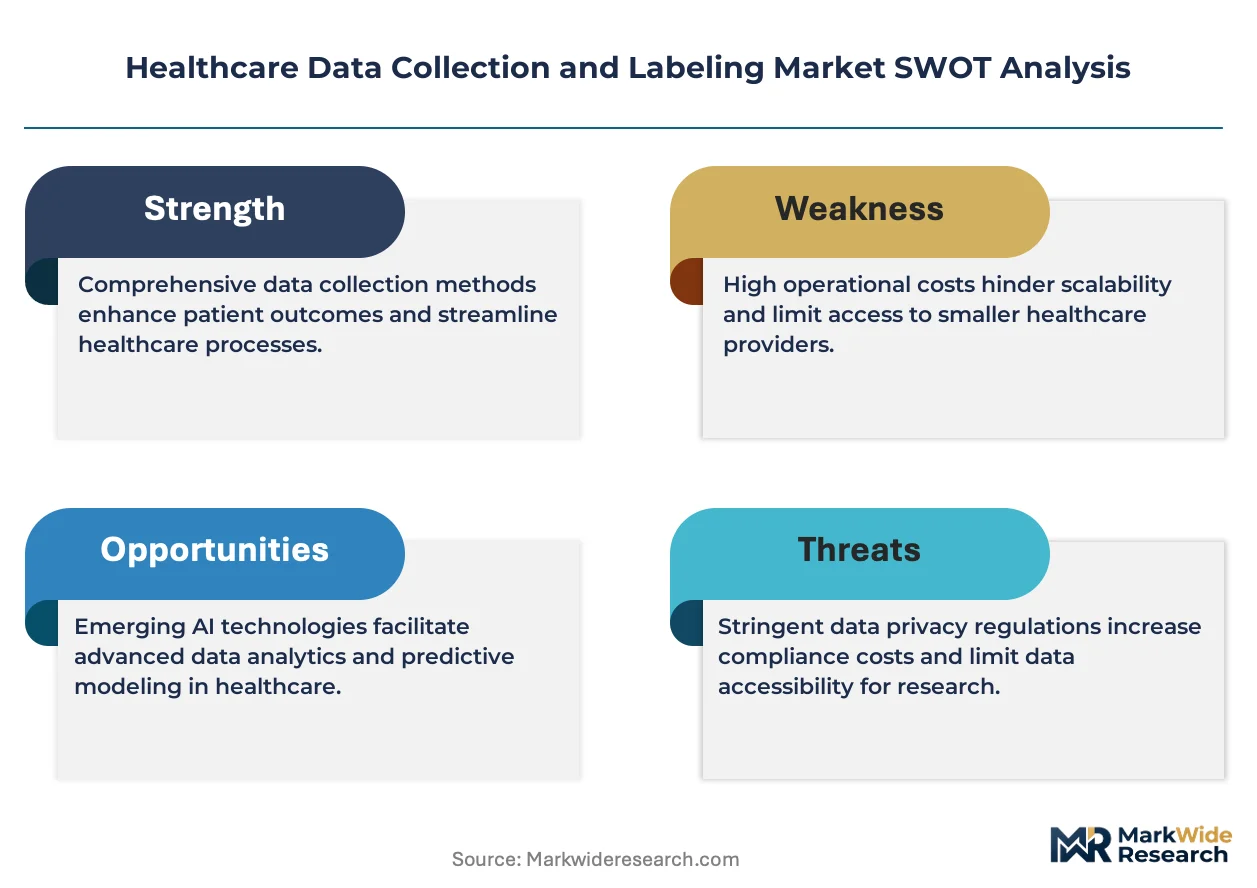
HIPAA's expanded enforcement on de-identification standards is realigning the cost-of-entry calculus for healthcare data vendors. Scale AI leverages its contractor network to sustain high-volume annotation throughput for medical imaging workloads. Labelbox anchors its platform around enterprise-grade audit trails that compete on compliance rigor.
Healthcare data collection and labeling encompasses the systematic acquisition, categorization, and semantic tagging of clinical information into machine-readable formats, typically requiring pixel-level precision for radiological annotations and SNOMED CT or ICD-10 coding for structured clinical narratives. Its primary purpose is to generate training corpora and ground-truth datasets that enable supervised learning models to recognize pathological patterns, predict patient outcomes, and automate clinical documentation. Data annotation services currently dominate revenue as health systems outsource the labor-intensive task of labeling millions of imaging studies, while natural language processing technology represents the fastest-expanding segment as electronic health record vendors demand extraction capabilities for unstructured physician notes. Medical imaging applications command the deepest margin pools due to the specialized expertise required for radiological interpretation and the premium pricing attached to FDA-submission-ready datasets.
The FDA governs algorithm validation datasets through its Software as a Medical Device framework, while HIPAA mandates chain-of-custody documentation for any labeled data derived from covered entities. The European Medicines Agency's Medical Device Regulation imposes additional clinical evidence standards on AI training data, creating divergent compliance architectures for vendors serving multiple jurisdictions. Stakeholders must monitor whether regulators will mandate prospective data collection standards that retroactively invalidate historically labeled datasets.
Market Dynamics
The FDA's Software as a Medical Device framework is compressing validation timelines for training datasets, forcing vendors to reengineer annotation workflows around prospective data collection standards rather than retrospective labeling of historical clinical archives.
Growth Catalysts
- Diagnostic algorithm deployment:Hospitals are scaling annotated imaging dataset procurement to train computer vision models for radiological screening programs.
- HIPAA de-identification enforcement:Tighter standards on safe harbor compliance are professionalizing vendor capabilities and raising barriers to informal data monetization.
- NLP extraction mandates:Electronic health record vendors require structured coding from unstructured physician notes to meet quality reporting requirements.
Market Restraints
- Specialized labor scarcity:Radiological interpretation expertise commands premium wages, compressing margins on imaging annotation services.
- Supply concentration risk:High-volume annotation throughput depends on contractor networks concentrated in specific labor markets.
- EMA MDR divergence:European clinical evidence standards for AI training data create parallel compliance architectures that fragment vendor R&D budgets.
Strategic Opportunities
- Federated learning architectures:Multi-site model training without centralizing raw patient data addresses HIPAA chain-of-custody constraints.
- SNOMED CT expansion:Clinical terminology standardization enables cross-border dataset interoperability for multinational pharmaceutical trials.
- Synthetic data generation:Generative adversarial networks produce privacy-preserving training corpora that bypass de-identification bottlenecks entirely.
Industry Challenges
- Inter-annotator variability:Pixel-level precision requirements for pathological pattern recognition demand rigorous quality assurance protocols that extend project timelines.
- Legacy EHR integration:Unstructured clinical narratives reside in proprietary formats that resist automated extraction without costly system reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Data Collection and Labeling Market |
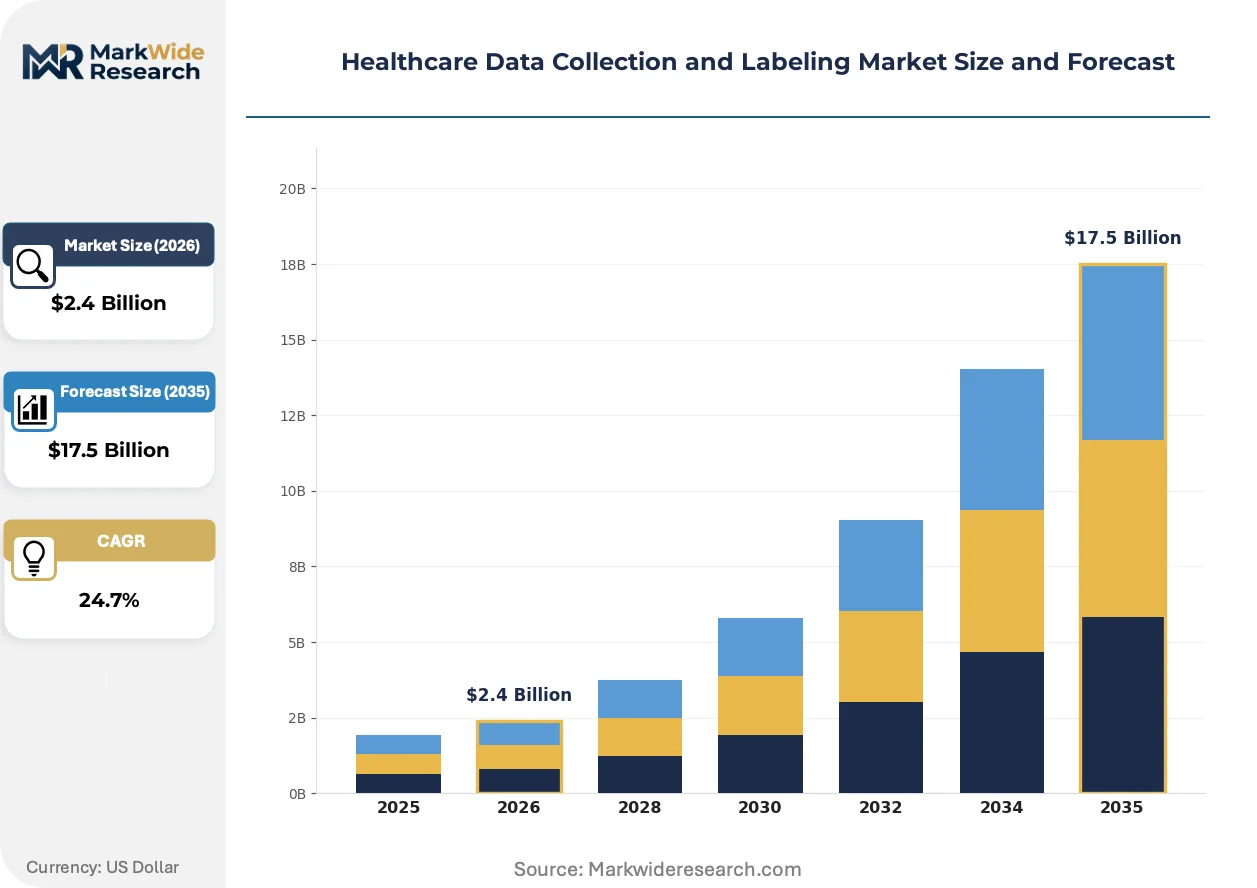
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $17.5 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Annotation, Data Enrichment, Data Validation, Data Transcription End User: Hospitals, Research Institutions, Diagnostic Centers, Pharmaceutical Companies Technology: Machine Learning, Natural Language Processing, Computer Vision, Cloud Computing Application: Medical Imaging, Clinical Trials, Patient Records, Telemedicine |
| Companies Covered | Scale AI, Labelbox, Alegion, iMerit, Appen Limited, Shaip, Snorkel AI, Centaur Labs, Anolytics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Data Collection and Labeling Market Strategic Shifts & Innovations
Annotation tooling is pivoting from labor arbitrage to computational efficiency, with automated pre-labeling and active learning loops reducing human-in-the-loop hours per imaging study.
Active learning algorithms are consolidating market power among vendors with sufficient training data to initialize accurate model-assisted annotation. Academic medical centers with million-study archives are licensing these pre-trained models to commercial partners. The technology is consolidating annotation throughput into fewer platforms that can amortize infrastructure costs across health system networks.
The EU AI Act's risk-based classification system is recalibrating dataset documentation requirements for high-risk medical applications. Manufacturers must maintain technical files demonstrating training data quality management throughout the model lifecycle. Radiology AI submissions face expanded conformity assessment obligations that favor vendors with established quality management systems.
Hospital procurement departments are bundling annotation services into enterprise AI implementation contracts rather than sourcing point solutions. Health systems are consolidating vendor relationships to simplify FDA submission support and audit trail management. This concentration is most visible in United States integrated delivery networks that centralize technology purchasing across dozens of affiliated hospitals.
Healthcare Data Collection and Labeling Market Segmentation
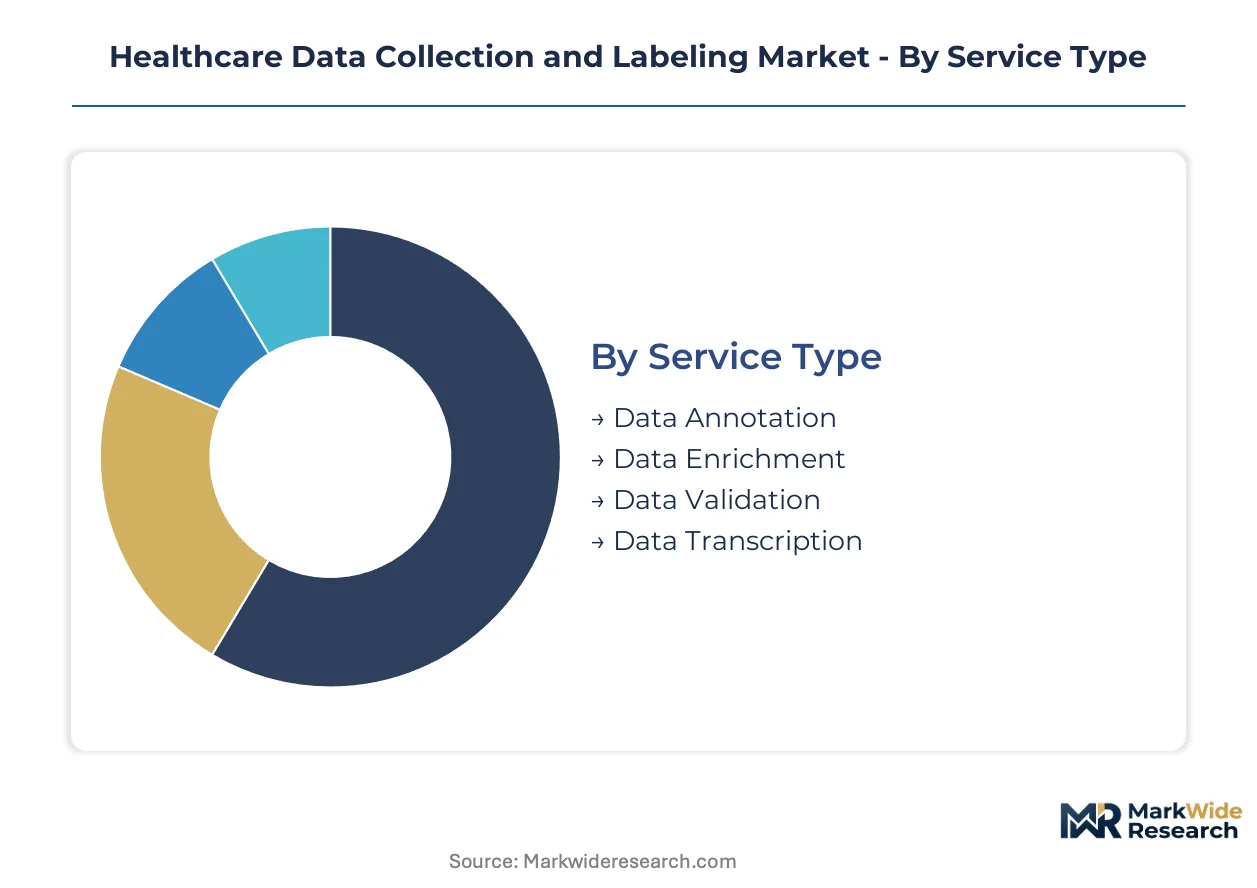
Healthcare data collection and labeling segments diverge sharply by technical complexity, regulatory exposure, and buyer procurement sophistication. Understanding these fault lines clarifies where vendors must specialize versus where scale economics dominate.
Service Type:
Buyers differentiate primarily by internal AI maturity—health systems with deployed models need validation-heavy partnerships, while early-stage adopters require full annotation build-outs.
- Data Annotation:Pixel-level labeling of radiological studies and pathology slides demands specialized clinical expertise. United States hospitals with million-study imaging archives currently concentrate procurement here, though HIPAA de-identification enforcement is extending vendor onboarding timelines. The segment commands premium pricing tied to FDA submission readiness.
- Data Enrichment:Semantic tagging of unstructured clinical narratives with SNOMED CT and ICD-10 codes enables downstream NLP model training. Electronic health record vendors in the United States drive demand as quality reporting mandates harden. The work requires less specialized labor than imaging annotation, compressing margins but expanding addressable volume.
- Data Validation:Ground-truth verification and inter-annotator discrepancy resolution for algorithm validation datasets. Pharmaceutical sponsors of FDA-submission-bound diagnostics require this for Software as a Medical Device compliance.
- Data Transcription:Conversion of audio clinical encounters and handwritten notes into structured formats. Telemedicine platforms expanding their documentation automation capabilities represent the core demand pool.
Volume sits with Data Annotation; growth tilts toward Data Enrichment.
End User:
Procurement sophistication scales with regulatory exposure—diagnostic algorithm developers face the strictest dataset provenance requirements.
- Hospitals:Integrated delivery networks in the United States centralize annotation procurement across dozens of affiliated facilities, favoring vendors with enterprise-grade audit trails. These buyers bundle labeling services into broader AI implementation contracts rather than sourcing point solutions.
- Research Institutions:Academic medical centers with million-study archives license pre-trained annotation models to commercial partners. Their procurement emphasizes federated learning architectures that preserve HIPAA chain-of-custody without centralizing raw patient data.
- Diagnostic Centers:Independent radiology groups and pathology laboratories outsource labeling for niche screening programs. Their smaller scale limits vendor negotiation leverage.
- Pharmaceutical Companies:Multinational sponsors of AI-enabled diagnostics require cross-border dataset interoperability for regulatory submissions spanning FDA and EMA jurisdictions. SNOMED CT standardization investments dominate their technical specifications.
Procurement concentration favors Hospitals; capability requirements expand fastest for Pharmaceutical Companies.
Technology:
Technology selection tracks the underlying data modality—imaging workflows demand computer vision infrastructure, while clinical text extraction requires NLP stacks.
- Machine Learning:Active learning algorithms that prioritize human-in-the-loop hours for uncertain cases. Vendors with sufficient training data to initialize accurate model-assisted annotation are consolidating throughput into fewer platforms.
- Natural Language Processing:Extraction and structuring of unstructured physician notes. This segment is expanding most quickly as EHR vendors automate clinical documentation to meet quality reporting requirements.
- Computer Vision:Automated pre-labeling of radiological studies with pathological pattern recognition. The specialized expertise required for radiological interpretation sustains premium pricing.
- Cloud Computing:Scalable infrastructure for distributed annotation teams and multi-site model training. Federated learning implementations depend on this backbone to address HIPAA constraints.
Deployment scale clusters with Cloud Computing; algorithmic sophistication advances fastest in Computer Vision.
Application:
Application segmentation reflects the downstream regulatory pathway—FDA-submission-ready datasets for diagnostic algorithms versus internal quality improvement use cases.
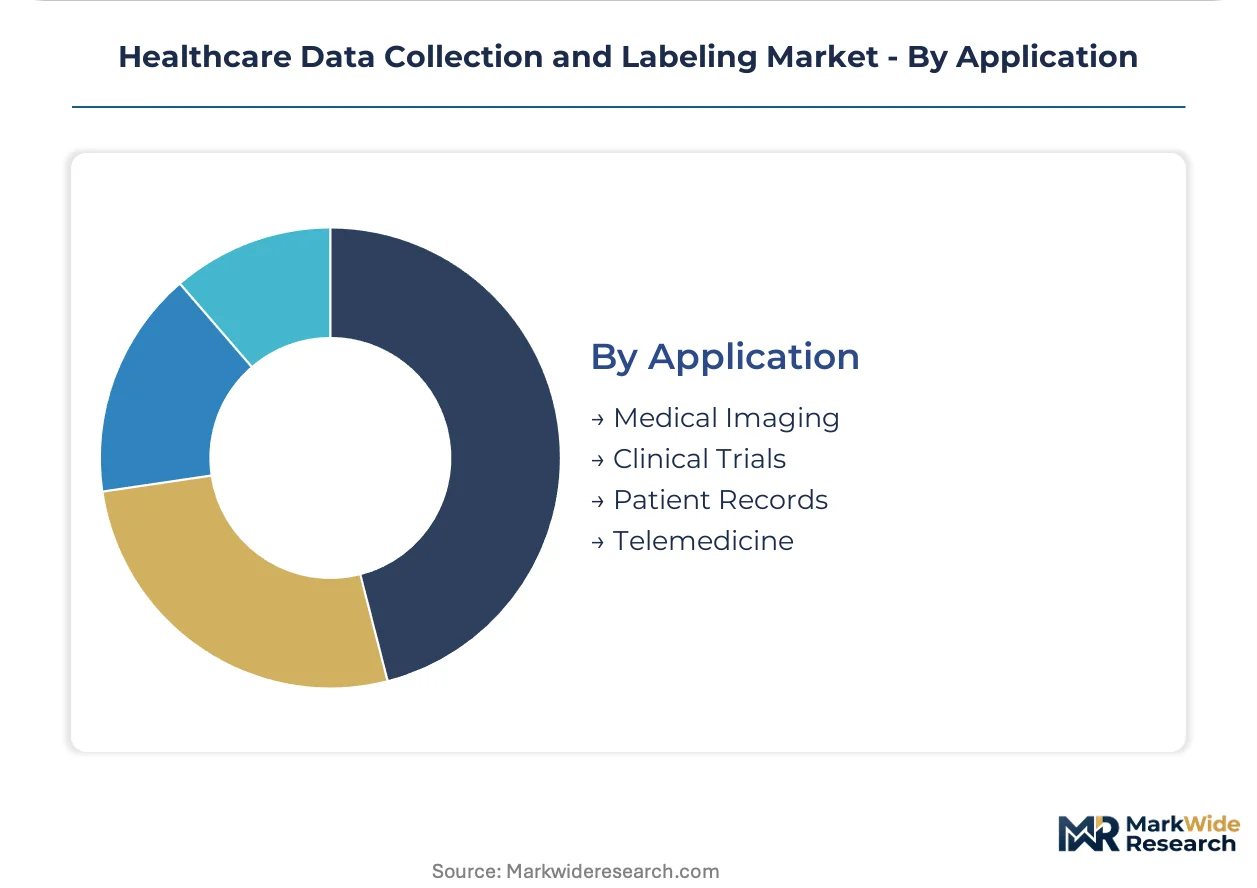
- Medical Imaging:Training corpora for computer vision models detecting pathological patterns in radiological screening. The segment commands the deepest margin pools due to specialized radiological expertise requirements and premium pricing for FDA-submission-ready datasets.
- Clinical Trials:Structured coding of adverse events, patient-reported outcomes, and biomarker data for regulatory submissions. EMA Medical Device Regulation divergence is fragmenting vendor R&D budgets across parallel compliance architectures.
- Patient Records:De-identification and semantic structuring of longitudinal clinical histories for population health analytics. HIPAA expanded enforcement on safe harbor compliance is professionalizing vendor capabilities.
- Telemedicine:Real-time annotation of virtual consults for quality assurance and automated documentation. Synthetic data generation using generative adversarial networks is emerging to bypass de-identification bottlenecks in this segment.
Margin depth concentrates in Medical Imaging; regulatory complexity expands fastest in Clinical Trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized healthcare data zones in Massachusetts and California concentrate annotation infrastructure near academic medical centers with million-study imaging archives. Tax incentives for AI R&D in these clusters accelerate vendor co-location with hospital networks.
United States
Integrated delivery networks in Texas and Florida centralize procurement across dozens of affiliated hospitals. HIPAA's expanded safe harbor enforcement extends vendor onboarding timelines. The Boston-Cambridge corridor anchors federated learning development for multi-site model training without centralizing raw patient data.
Germany
Diagnostic algorithm developers in Bavaria and North Rhine-Westphalia demand EMA Medical Device Regulation-compliant datasets. The country's national pharmaceutical regulator imposes clinical evidence standards that fragment vendor R&D budgets. Berlin's health AI cluster specializes in SNOMED CT standardization for cross-border pharmaceutical trials.
United Kingdom
NHS trusts in London and the Midlands outsource radiological annotation for screening programs. GDPR mandates chain-of-custody documentation that competes with HIPAA rigor. The Oxford-Cambridge arc licenses pre-trained models from academic medical center archives to commercial partners.
China
Hospital groups in Beijing and Shanghai scale computer vision training for radiological screening. NMPA guidance on AI-enabled diagnostics tightens data provenance requirements. The Yangtze River Delta concentrates cloud infrastructure for distributed annotation teams serving domestic health systems.
India
Telemedicine platforms in Karnataka and Telangana automate clinical documentation from virtual consults. The country's national pharmaceutical regulator aligns with FDA submission standards for outsourced annotation. Hyderabad's health tech corridor specializes in NLP extraction from unstructured physician notes.
Healthcare Data Collection and Labeling Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across annotation service tiers. The market structure tilts toward consolidation as hospital procurement departments bundle labeling into enterprise AI contracts. Three archetypes dominate: contractor-network operators sustaining high-volume throughput, compliance-first platforms competing on audit trail rigor, and academic spin-outs licensing pre-trained models. M&A activity targets federated learning capabilities; strategic partnerships anchor SNOMED CT standardization for multinational trials.
Within the contractor-network tier, Scale AI exemplifies labor arbitrage at scale, while Labelbox occupies a position anchored around enterprise-grade compliance infrastructure. Appen Limited sits within the diversified data services archetype, representing geographic breadth across healthcare and adjacent verticals.
| Leading Market Players |
|---|
| Scale AI |
| Labelbox |
| Alegion |
| iMerit |
| Appen Limited |
| Shaip |
| Snorkel AI |
| Centaur Labs |
| Anolytics |
| Others |
Cost & Logistics Intelligence
Outsourced contractor networks anchor supply positioning for annotation services, with vendors leveraging distributed labor pools to sustain throughput while HIPAA-compliant infrastructure investments lock in pricing power for audit-trail-heavy platforms. This integration choice separates high-volume throughput operators from compliance-first competitors, concentrating margin capture among vendors with dual capabilities.
Pricing Analysis
Short lead times for FDA-submission-ready datasets command substantial premiums, while spot inventory of pre-labeled imaging studies trades at discounts due to de-identification uncertainty. Project-based pricing dominates, with differentiation anchored in certification tier (FDA-ready versus internal-use) and radiologist expertise level. Cost compression in standard-tier annotation is intensifying as automated pre-labeling reduces human-in-the-loop hours. Diagnostic centers exhibit highest price sensitivity; pharmaceutical sponsors show lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Certification gating through HIPAA safe harbor and FDA Software as a Medical Device frameworks concentrates qualified supply in the United States, India, and Germany. Raw inputs include clinical imaging archives, unstructured EHR narratives, and specialized radiologist labor pools. Single-source vulnerability runs through contractor networks concentrated in specific South Asian labor markets. Distribution feeds through enterprise AI implementation contracts bundled by integrated delivery networks rather than point-solution procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Healthcare Data Collection and Labeling Market functions as a cost-of-compliance story, with HIPAA's expanded de-identification enforcement and FDA's tightening data provenance requirements erecting barrier-to-entry moats that favor incumbents with established audit infrastructure.
For Market Incumbents: Deepen federated learning capabilities to address multi-site model training demand without centralizing raw patient data, while consolidating contractor network relationships to defend throughput position against emerging automated pre-labeling competitors. Certification investment in EU AI Act conformity assessment pathways represents the priority defensive lever. For New Entrants and Emerging Players: Independent diagnostic centers in secondary United States markets represent an underserved buyer archetype with limited vendor negotiation leverage and unmet demand for niche screening program annotation. Synthetic data generation capabilities offer the most penetrable technical wedge, with go-to-market anchored through telemedicine platform partnerships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by enterprise AI platforms seeking vertical integration into healthcare verticals. Long-term viability favors vendors with million-study archive licensing relationships and established quality management systems. The signal to watch is EMA-FDA regulatory convergence or divergence on training data standards.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway Investment | Positions vendors for diagnostic algorithm developer procurement tied to Software as a Medical Device compliance. |
| Federated Learning Architecture Deployment | Enables multi-site model training without HIPAA chain-of-custody violations across hospital networks. |
| SNOMED CT Standardization Partnership | Unlocks cross-border dataset interoperability for multinational pharmaceutical trial sponsors. |
| Synthetic Data Generation Capability | Bypasses de-identification bottlenecks entirely using generative adversarial networks for privacy-preserving corpora. |
| Hospital System Enterprise Contract | Bundles annotation services into AI implementation contracts, simplifying procurement for integrated delivery networks. |
Research Approach
FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records formed the secondary backbone, supplemented by primary interviews with radiology department chairs, GPO contracts managers, biomedical engineers, and AI implementation leads at integrated delivery networks. Bottom-up and top-down triangulation validated segment sizing across service types and end-user categories.
Bottom-up modeling anchored volume estimates in health system imaging archive sizes and annotation throughput rates, while top-down cross-checks applied spending ratios from enterprise AI implementation budgets. Segmentation dimensions included service type complexity tier, end-user regulatory exposure level, and technology deployment model. CAGRs were derived from algorithmic adoption curves and compliance timeline compression.
Revisions become necessary when FDA guidance on AI/ML-based medical devices materializes with retroactive dataset invalidation provisions, or when HIPAA enforcement actions reshape safe harbor compliance costs. A model refresh is warranted upon material change in EMA Medical Device Regulation divergence from FDA standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
US Mobile Health Market
Health Data Management
Americas Healthcare Archiving and Ediscovery Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Medical Record Management System Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
Health Care Quality Management Software Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
North America Clinical Data Analytics in Healthcare Market
Health Data Management
Global Precision Medicine Software Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
United States Healthcare Big Data Analytics Market
Health Data Management
Global Healthcare Data Storage Market