
 Olivopontocerebellar Atrophy Treatment Market | 2026-2036
Olivopontocerebellar Atrophy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Olivopontocerebellar Atrophy Treatment Market Analytics
Specialized symptomatic management protocols for progressive cerebellar dysfunction is collapsing the gap between off-label prescribing and evidence-based care standards. H Lundbeck A/S leverages its movement disorder franchise to sustain commercial traction in ataxia-adjacent indications. Biogen competes through its neurodegeneration R&D infrastructure, while Ionis Pharmaceuticals anchors its position with antisense oligonucleotide platforms targeting rare neurological diseases.
Olivopontocerebellar atrophy treatment encompasses pharmacological interventions, rehabilitative therapies, and supportive care modalities directed at a sporadic or familial neurodegenerative syndrome characterized by progressive cerebellar ataxia, autonomic failure, and parkinsonism, with disease-modifying approaches targeting alpha-synuclein aggregation or mitochondrial dysfunction pathways. The medications segment dominates current revenue as symptomatic management with agents such as riluzole or amantadine remains the clinical standard, while the disease modification solution category is expanding fastest as pharmaceutical developers advance neuroprotective candidates through Phase II trials. Injectable delivery modes command premium positioning for hospital-administered neuroprotective therapies, whereas oral formulations occupy the volume base for chronic symptomatic regimens.
The FDA orphan drug program and EMA's protocol assistance for rare neurological diseases shape clinical trial design and market exclusivity timelines for developers targeting olivopontocerebellar atrophy. The NIH's Rare Diseases Clinical Research Network coordinates natural history studies that establish endpoints regulators accept, while the European Medicines Agency's adaptive pathway pilot accelerates conditional approvals for therapies demonstrating early efficacy signals. Stakeholders must monitor biomarker validation progress and payer willingness to fund multidisciplinary rehabilitation programs as these factors determine accessible market size beyond pharmaceutical revenue alone.
Market Dynamics
The FDA's orphan drug designation pathway is compressing development timelines for neuroprotective candidates while specialized ataxia treatment centers concentrate patient access around major academic medical institutions in the United States.
Growth Catalysts
- EMA Adaptive Pathway Pilot:The European Medicines Agency's conditional approval mechanism accelerates market entry for therapies demonstrating early efficacy signals in rare neurodegenerative indications.
- Multidisciplinary Care Expansion:Neurology clinics are formalizing integrated rehabilitation protocols that bundle pharmacological management with physical and occupational therapy for progressive ataxia patients.
- NIH Rare Diseases Network:Coordinated natural history studies establish regulatory-accepted endpoints that de-risk clinical trial design for disease-modifying interventions.
Market Restraints
- Biomarker Validation Gaps:Absence of validated surrogate endpoints prolongs Phase III trial duration and inflates development costs for neuroprotective candidates.
- Payer Reimbursement Uncertainty:Medicare and commercial insurers exhibit inconsistent coverage determination for multidisciplinary rehabilitation programs beyond pharmaceutical interventions.
- Patient Pool Fragmentation:Sporadic and familial disease subtypes with heterogeneous phenotypes complicate trial enrollment and regulatory pathway standardization.
Strategic Opportunities
- Antisense Oligonucleotide Platforms:Convergence of nucleic acid chemistry with CNS delivery technologies opens addressable pathways for genetic subtype targeting.
- Academic Medical Center Clustering:Untapped patient concentration in Germany, Japan, and the United Kingdom offers expansion potential for specialized treatment protocols.
- Remote Rehabilitation Monitoring:Telehealth integration enables geographic reach extension for movement disorder specialists beyond physical clinic constraints.
Industry Challenges
- Movement Disorder Specialist Scarcity:Fellowship-trained neurologists with cerebellar ataxia expertise remain concentrated at fewer than fifty academic institutions across the United States.
- Cross-Functional Trial Coordination:Integration of gait analysis laboratories, autonomic testing facilities, and neuroimaging cores demands capital-intensive site qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Olivopontocerebellar Atrophy Treatment Market |
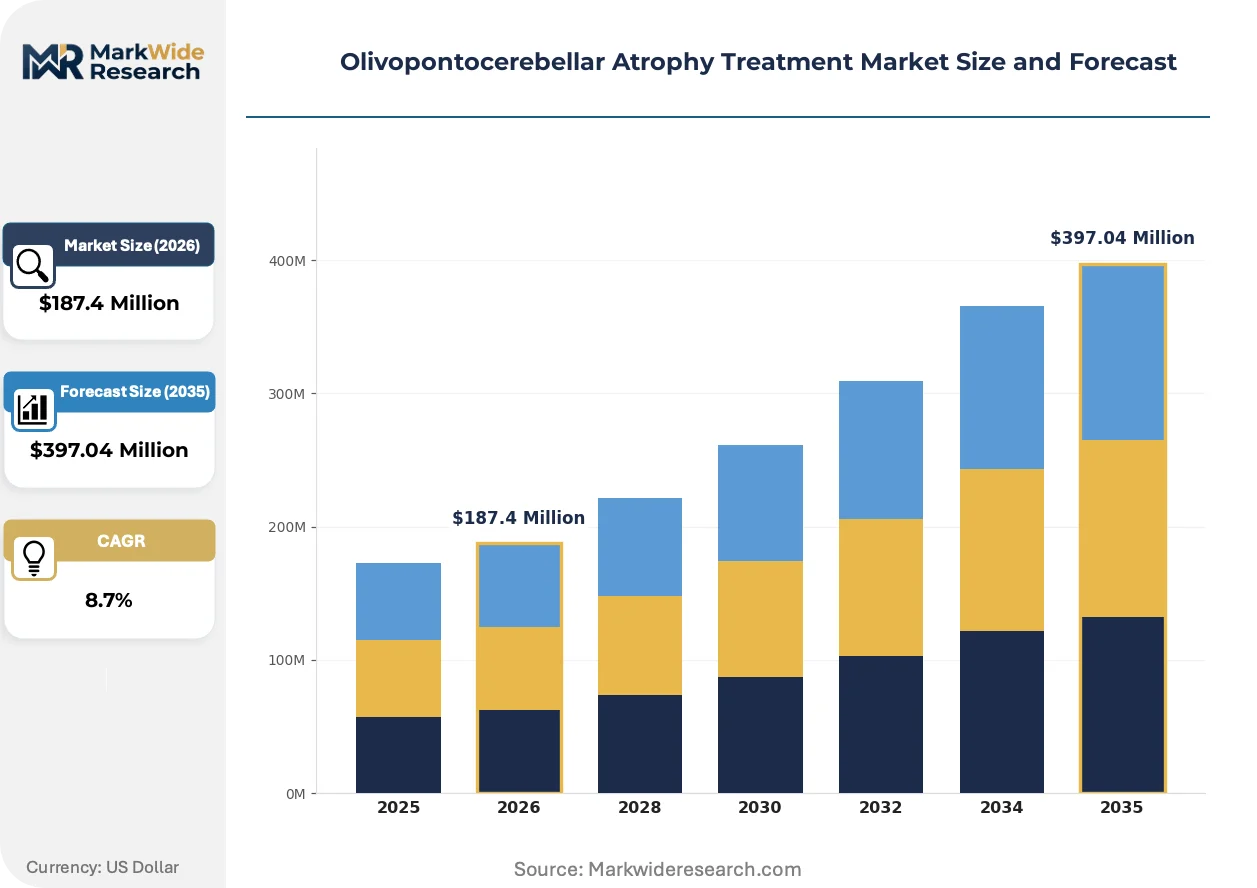
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Physiotherapy, Occupational Therapy, Supportive Care End User: Neurology Clinics, Rehabilitation Centers, Hospitals, Home Care Delivery Mode: Oral, Injectable, Transdermal, Intravenous Solution: Symptomatic Management, Disease Modification, Patient Education, Family Support |
| Companies Covered | H Lundbeck A/S, Ionis Pharmaceuticals, Teva Pharmaceutical Industries Ltd, AstraZeneca, MODAG GmbH, Alterity Therapeutics, Biogen, Takeda Pharma, Theravance Biopharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Olivopontocerebellar Atrophy Treatment Market Evolving Landscape
Neuroprotective drug development is pivoting from symptomatic management toward disease-modifying mechanisms, while regulatory frameworks adapt to accelerate rare disease therapeutic access.
Alpha-synuclein targeting immunotherapies is fragmenting the traditional symptomatic management paradigm for parkinsonian subtypes of olivopontocerebellar atrophy. Biopharmaceutical developers with neurodegeneration infrastructure are advancing passive immunization candidates through Phase II trials. Hospital-administered infusion protocols are creating premium positioning separate from oral chronic regimens.
REACH authorization requirements for novel chemical entities are tightening toxicology documentation standards for blood-brain barrier penetrant small molecules. EMA's protocol assistance mandates earlier pediatric investigation planning even for adult-onset neurodegenerative indications. European sponsors are front-loading CMC development to avoid conditional approval delays.
Academic medical centers are unbundling traditional comprehensive care packages into discrete reimbursable service lines. Gait analysis and autonomic function testing are separating from bundled evaluation codes. This restructuring is most visible in United States Medicare Advantage plan contracting, where prior authorization requirements increasingly specify facility-based versus outpatient settings.
Olivopontocerebellar Atrophy Treatment Market Segmentation
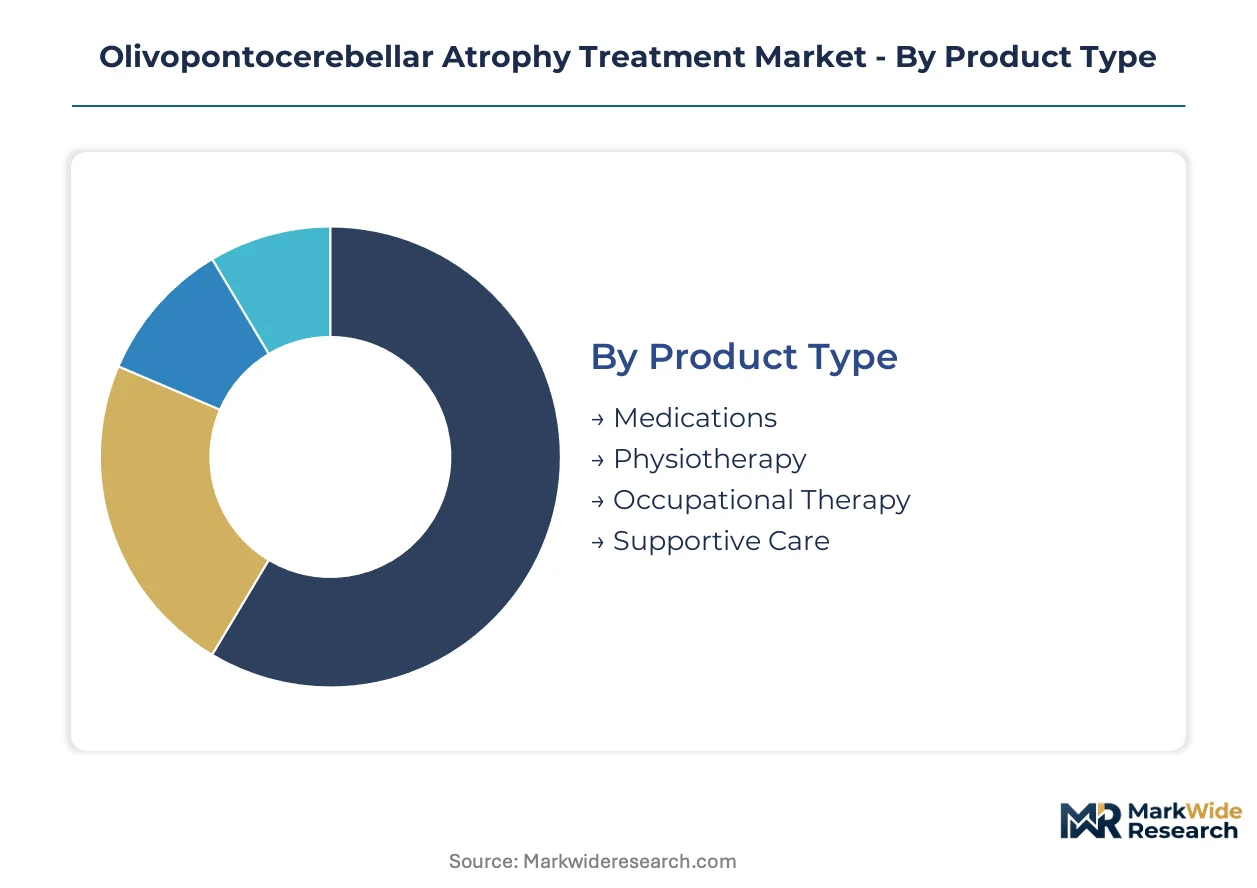
Segmentation in olivopontocerebellar atrophy treatment reveals how clinical practice fragments across intervention intensity and care setting. Understanding these divisions exposes where pharmaceutical revenue concentrates versus where service-based reimbursement dominates.
Product Type:
Substitute pressure intensifies where non-pharmacological interventions demonstrate comparable functional outcomes to drug therapy, forcing product-level strategic repositioning.
- Medications:Small-molecule agents including riluzole and amantadine target glutamatergic modulation and dopaminergic pathways. Demand clusters at academic medical centers in the United States where movement disorder specialists prescribe off-label with institutional protocol backing. Payer prior authorization requirements create access friction that pharmaceutical developers must navigate through specialty pharmacy networks.
- Physiotherapy:Gait training and balance rehabilitation protocols slow functional decline in cerebellar ataxia patients. Medicare Advantage plans in the United States increasingly require facility-based delivery with measurable outcome documentation, compressing margins for outpatient providers.
- Occupational Therapy:Adaptive equipment training and activities-of-daily-living modification preserve independence. Reimbursement bundling with physical therapy services limits standalone program viability.
- Supportive Care:Nutritional support, speech therapy, and psychosocial services address multisystem degeneration. Hospice eligibility determination creates late-stage revenue concentration.
Medications anchors the volume base while physiotherapy gains share at the steepest rate as evidence accumulates for structured rehabilitation protocols.
End User:
Cost tier stratification separates high-acuity hospital encounters from longitudinal outpatient management, with reimbursement rate differentials driving site-of-care migration.
- Neurology Clinics:Multidisciplinary ataxia centers coordinate pharmacological and rehabilitative interventions under single specialty oversight. The United States concentrates approximately fifty such centers at major academic institutions, creating geographic access deserts.
- Rehabilitation Centers:Inpatient and outpatient facilities deliver intensive gait and balance training. Bundled payment pilots for neurodegenerative conditions create episode-based revenue models that reward functional improvement metrics.
- Hospitals:Acute care encounters address aspiration pneumonia, falls, and autonomic crises. Emergency department utilization spikes in disease later stages.
- Home Care:Skilled nursing and personal care services extend institutional protocols to residential settings. State Medicaid waiver programs determine accessible service intensity.
Neurology clinics capture the premium reimbursement tier while home care expands most quickly as telehealth integration reduces geographic barriers.
Delivery Mode:
Application requirements for blood-brain barrier penetration and chronic administration convenience create irreconcilable trade-offs between efficacy and adherence.
- Oral:Chronic symptomatic regimens prioritize patient self-administration and pharmacy distribution efficiency. Amantadine and riluzole tablets dominate prescription volume through retail and mail-order channels.
- Injectable:Subcutaneous and intramuscular neuroprotective candidates require clinical administration infrastructure. Hospital outpatient departments command premium pricing for infusion services.
- Transdermal:Patch-based delivery bypasses first-pass metabolism for selected agents. Limited CNS penetration restricts applicability in cerebellar indications.
- Intravenous:Hospital-administered immunotherapies targeting alpha-synuclein aggregation demand specialized infusion center capacity. Site qualification requirements concentrate administration at academic medical centers.
Oral formulations sustain the volume foundation while intravenous delivery climbs the fastest as disease-modifying biologics advance through regulatory pathways.
Solution:
Customer type differentiation separates acute symptomatic relief seekers from proactive disease-modification adopters, with information asymmetry shaping segment migration patterns.
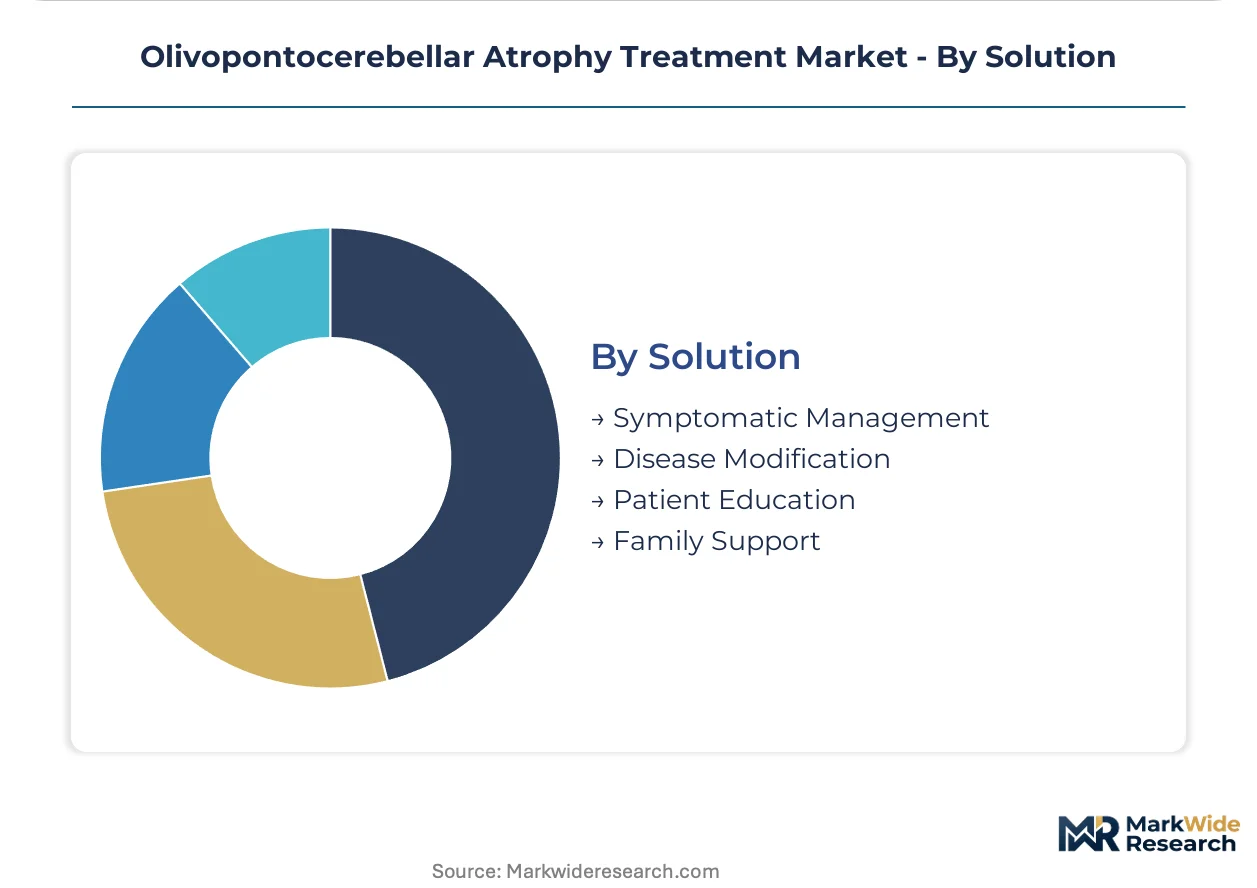
- Symptomatic Management:Established protocols address ataxia, parkinsonism, and autonomic dysfunction through pharmacological and non-pharmacological means. Clinical practice guidelines from the National Ataxia Foundation standardize off-label prescribing.
- Disease Modification:Neuroprotective candidates targeting mitochondrial dysfunction or protein aggregation represent pipeline concentration. FDA orphan drug designation accelerates development timelines for sponsors.
- Patient Education:Structured programs address disease trajectory understanding and advance care planning. Non-profit foundation sponsorship reduces direct revenue capture.
- Family Support:Caregiver training and respite services address informal care burden. State-specific Medicaid waivers create patchwork funding availability.
Symptomatic management retains the dominant revenue share while disease modification attracts the steepest investment trajectory as biomarker validation progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of specialized neurodegenerative therapeutics into the United States exceed domestic production capacity, while European and Asian markets develop indigenous clinical trial infrastructure. Export intensity concentrates on finished pharmaceutical products and research services rather than raw materials.
United States
FDA orphan drug designations for olivopontocerebellar atrophy candidates reached record velocity, compressing development timelines through priority review vouchers. The NIH Rare Diseases Clinical Research Network coordinates natural history studies that establish regulatory endpoints. Massachusetts and California academic medical centers cluster movement disorder specialists, with Boston's Mass General Brigham and Stanford Medicine anchoring multidisciplinary ataxia protocols.
Germany
EMA protocol assistance accelerates conditional approval pathways for neuroprotective candidates targeting mitochondrial dysfunction. REACH authorization requirements tighten toxicology documentation for blood-brain barrier penetrant small molecules. Heidelberg and Munich university hospitals concentrate patient enrollment for Phase II trials, with the German Center for Neurodegenerative Diseases coordinating biomarker validation consortia.
Japan
PMDA's Sakigake designation system fast-tracks regenerative medicine and gene therapy candidates for rare neurological diseases. METI funding for precision medicine infrastructure supports patient registry development. Tokyo and Osaka medical school hospitals integrate gait analysis laboratories with autonomic testing facilities, creating capital-intensive site networks for multinational trials.
Switzerland
Swissmedic's adaptive licensing framework permits early access to disease-modifying therapies demonstrating preliminary efficacy signals. Federal funding for neurodegeneration research clusters around the University Hospital Zurich and University Hospital Geneva. Basel's pharmaceutical ecosystem provides contract manufacturing capacity for antisense oligonucleotide production serving European trial supply.
United Kingdom
MHRA post-Brexit recognition of EMA scientific opinions streamlines parallel regulatory submissions for rare disease indications. NHS England's specialized commissioning framework determines access to high-cost neurological interventions. London's National Hospital for Neurology and Neurosurgery and Cambridge's Addenbrooke's Hospital coordinate the Ataxia UK patient registry informing natural history studies.
Olivopontocerebellar Atrophy Treatment Market Competitive Landscape
Concentration sits with neurodegeneration-focused biopharmaceutical developers possessing integrated R&D infrastructure and rare disease regulatory expertise. The competitive terrain fragments across three tiers: multinational neurology franchises with movement disorder portfolios, antisense oligonucleotide platform specialists, and emerging biotechs targeting protein aggregation pathways. Strategic archetypes include disease-modification pioneers advancing neuroprotective candidates through accelerated approval pathways, and symptomatic management incumbents defending market position through institutional protocol penetration. Dominant competitive moves encompass portfolio diversification into adjacent ataxia indications and geographic expansion through academic medical center clustering.
Within the platform-technology tier, Ionis Pharmaceuticals exemplifies antisense oligonucleotide capability deployment against rare neurological targets, while Biogen occupies a position bridging neurodegeneration infrastructure with gene therapy adjacencies. H Lundbeck A/S represents the movement disorder franchise archetype, leveraging existing commercial relationships with neurology specialists. MODAG GmbH anchors the European emerging biotech segment, reflecting Germany's concentration of mitochondrial dysfunction research. These entities collectively illustrate how competitive positioning derives from regulatory pathway mastery and patient access concentration rather than manufacturing scale.
| Leading Market Players |
|---|
| H Lundbeck A/S |
| Ionis Pharmaceuticals |
| Teva Pharmaceutical Industries Ltd |
| AstraZeneca |
| MODAG GmbH |
| Alterity Therapeutics |
| Biogen |
| Takeda Pharma |
| Theravance Biopharma |
| Others |
Value Network & Pricing Analysis
Oral riluzole substitution for intravenous neuroprotective candidates is simultaneously redistributing manufacturing capacity toward contract tablet producers in India and compressing reimbursement premiums for hospital-administered infusion services. This substitution dynamic concentrates pricing power with specialty pharmacy networks managing chronic oral regimens while fragmenting margin capture across site-of-care settings.
Pricing Analysis
Academic medical center buyers anchor a three-tier pricing structure across premium infusion services, standard oral formulations, and economy generic substitutions. Price differentiation hinges on FDA orphan drug exclusivity status and institutional protocol adoption depth. Cost compression in the economy tier intensifies as Medicare Advantage plans tighten prior authorization requirements for off-label prescribing. Neurology clinics at major academic institutions exhibit lowest price sensitivity due to bundled reimbursement contracts, while community hospitals face acute margin pressure.
Supply Chain Analysis
Just-in-time inventory strategies dominate antisense oligonucleotide production, with sponsors maintaining minimal finished goods stockpiles due to cold-chain stability constraints and personalized medicine batch sizes. Active pharmaceutical ingredient sourcing concentrates in Switzerland, Germany, and the United States, with Basel-based contract manufacturers feeding European trial supply. Supply chain risk centers on single-source vulnerability for blood-brain barrier penetration enhancers. Distribution runs through specialty pharmacy networks with hub-and-spoke logistics for patient home delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where multidisciplinary rehabilitation program fees expand faster than pharmaceutical product revenue, with bundled care protocols capturing recurring reimbursement streams beyond drug margins.
For Market Incumbents: Shield formulary position by deepening vertical integration into patient registry data assets that inform natural history study design and regulatory endpoint validation. Prioritize certification investment for gait analysis laboratories to secure site-of-care control against emerging telehealth competitors. Defend against antisense oligonucleotide platform entrants by locking academic medical center exclusive distribution agreements. For New Entrants and Emerging Players: Anchor in the United Kingdom and Germany patient populations where NHS specialized commissioning and EMA protocol assistance create accelerated access pathways. Target disease modification segments with mitochondrial dysfunction candidates where biomarker validation gaps still permit competitive entry. Pursue go-to-market angles through Ataxia UK and German Center for Neurodegenerative Diseases registry partnerships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rare disease platform companies holding FDA orphan drug designations without Phase III initiation. Five-to-ten year viability hinges on successful biomarker qualification converting conditional approvals to full licensure. Monitor NIH Rare Diseases Clinical Research Network endpoint acceptance decisions as the critical inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA priority review vouchers compress development timelines for neuroprotective candidates. |
| Academic Medical Center Clustering | Patient concentration at Mass General Brigham and Stanford Medicine accelerates trial enrollment. |
| Antisense Platform Expansion | Ionis Pharmaceuticals' nucleic acid chemistry anchors genetic subtype targeting capabilities. |
| Biomarker Validation Consortium | German Center for Neurodegenerative Diseases coordinates surrogate endpoint acceptance. |
| Telehealth Rehabilitation Integration | Remote monitoring extends geographic reach beyond fifty US movement disorder specialist centers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists; and secondary validation against FDA orphan drug filings, EMA protocol assistance records, ClinicalTrials.gov entries, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical revenue estimates across the analysis window.
Across the projection horizon, the analytical framework segmented by treatment line, administration route, patient population subtype, and regional regulatory cluster. CAGRs derived from epidemiology-adjusted prevalence projections and pricing elasticity assumptions. Forecast inputs incorporated NIH Rare Diseases Clinical Research Network natural history study enrollment trajectories and EMA adaptive pathway pilot acceptance rates.
Decision-makers should treat outputs as directional under assumptions of stable orphan drug exclusivity periods and continued Medicare Advantage bundled payment expansion; material deviation in biomarker validation timelines or payer coverage determinations would warrant model refresh. Revision becomes warranted when FDA breakthrough therapy designation velocity crosses thresholds that alter competitive development timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Ulnar Nerve Treatment Market
Neurology
Chronic Brain Damage Management Market
Neurology
China Neurology Devices Market
Neurology
Netherlands Neurology Devices Market
Neurology
Mild Traumatic Brain Injury Treatment Market
Neurology
Coma Diagnosis and Treatment Market
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
Cluster Headache Syndrome Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
CNS Treatment and Therapy Market
Neurology
Amnestic Disorders Therapeutics Market
Neurology
Cervical Dystonia Treatment Market
Neurology
Neurology Software Market
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
Acute Repetitive Seizures Market
Neurology
Tourette Syndrome Market