
 Point of Care (POC) Data Management Systems Market | 2026-2036
Point of Care (POC) Data Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Point of Care (POC) Data Management Systems Market Intelligence
The shift from multi-vendor, disparate software solutions to single-source, integrated platforms is consolidating the market. This trend favors large, established vendors with comprehensive portfolios. Siemens Healthineers leverages its existing diagnostic hardware footprint to bundle data management software. Abbott Laboratories competes on the strength of its Alinity and ID NOW platforms, offering seamless data integration, while F. Hoffmann-La Roche Ltd differentiates through its cobas infinity IT solutions, which support extensive laboratory automation.
Point of care (POC) data management systems are software solutions designed to capture, process, and integrate test results generated from devices outside the central laboratory. These systems often utilize connectivity protocols like POCT1-A to ensure interoperability with various diagnostic instruments and electronic health records (EHRs). The primary purpose is to provide immediate, actionable clinical data at the patient's bedside or in remote settings. Within the application segments, clinical diagnostics remains the largest, while patient monitoring shows significant expansion due to chronic disease management programs.
Regulatory frameworks significantly influence system design and market access. In the United States, FDA clearance and HIPAA compliance are mandatory for patient data handling, while in Europe, GDPR and the MDR impose strict rules on data privacy and device interoperability. These regulations compel vendors to invest heavily in security and validation. A vendor's ability to navigate complex, multi-jurisdictional compliance requirements will dictate its long-term market viability.
Market Dynamics
The central dynamic shaping the market is the tension between the need for universal device interoperability and the increasing stringency of data security mandates. This conflict forces vendors to build open, flexible platforms that simultaneously incorporate robust, jurisdiction-specific security protocols.
Growth Catalysts
- Telemedicine Expansion:The proliferation of remote patient monitoring and telehealth services, particularly for chronic disease management programs, directly stimulates demand for systems that can integrate data from home-use or mobile POC devices into central patient records.
- Connectivity Standardization:Adoption of industry standards like the POCT1-A communication protocol simplifies the integration of diverse, multi-vendor instruments, lowering implementation barriers for healthcare providers and encouraging broader system deployment within hospital networks.
- Regulatory Compliance Drivers:Data privacy frameworks such as HIPAA in the United States and GDPR in Europe compel healthcare organizations to invest in validated data management systems that ensure auditable, secure handling of sensitive patient information.
Market Restraints
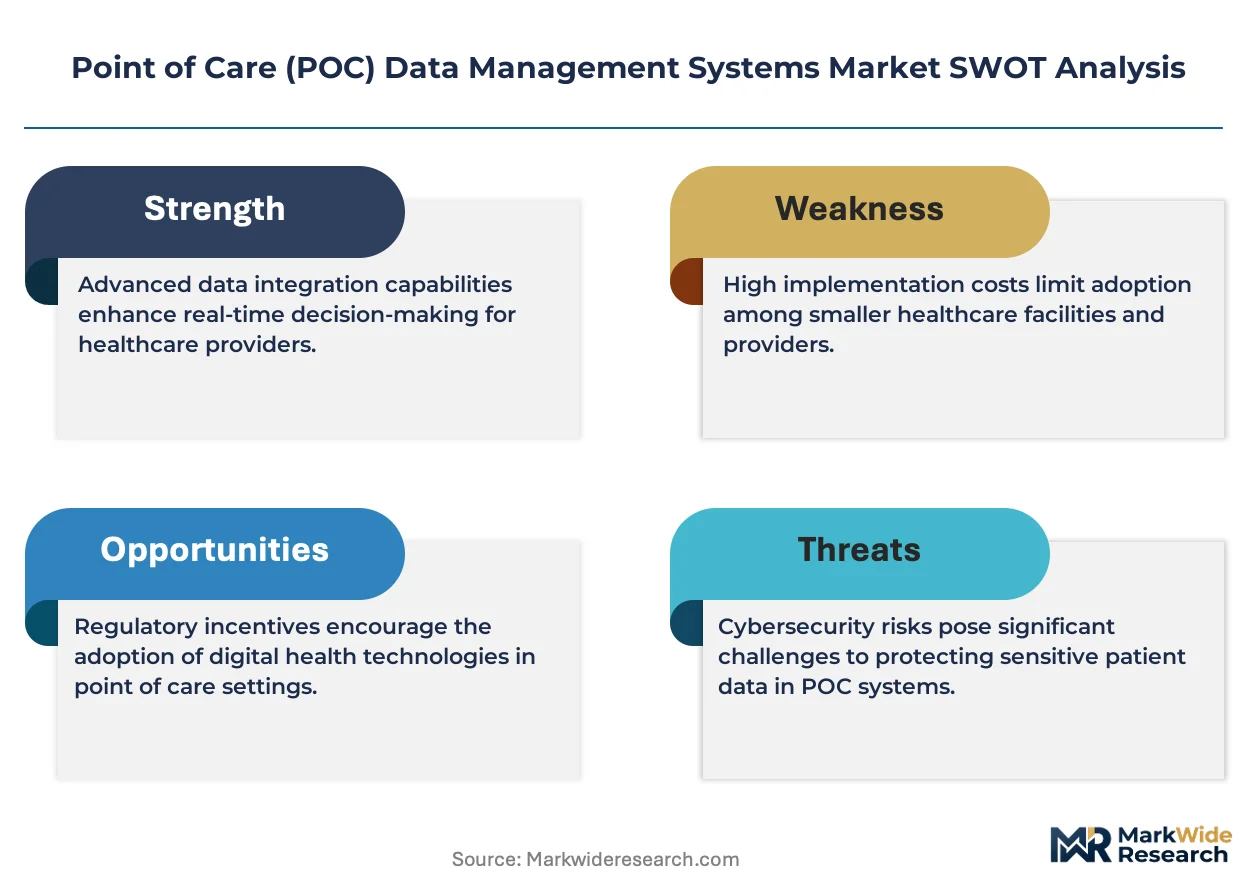
- High Implementation Costs:The significant upfront capital investment required for integrated software platforms, including licensing, hardware upgrades, and IT staff training, can be prohibitive for smaller clinics, independent laboratories, and healthcare facilities in developing economies.
- Legacy System Integration:Many healthcare facilities operate on older, proprietary Electronic Health Record (EHR) systems that lack modern APIs, creating substantial technical hurdles and costs associated with achieving seamless data flow from new POC management systems.
- Vendor Lock-In Concerns:Market consolidation around a few large vendors with end-to-end hardware and software ecosystems creates concerns among buyers about a lack of interoperability with third-party devices and reduced long-term pricing leverage.
Strategic Opportunities
- Emerging Market Infrastructure:Developing healthcare systems in regions like Southeast Asia and Latin America represent significant growth opportunities as they build out new hospital infrastructure and leapfrog directly to modern, integrated data management solutions.
- Decentralized Clinical Trials (DCTs):The pharmaceutical industry's shift towards DCTs creates a new demand vector for compliant POC data systems capable of capturing and securely transmitting trial data from participants' homes to clinical research organizations.
- AI and Predictive Analytics:Integrating artificial intelligence and machine learning algorithms into data management platforms offers a major value-add opportunity, enabling predictive alerts for patient deterioration or identifying population health trends from aggregated POC test results.
Industry Challenges
- Interoperability with Diverse Devices:A primary operational hurdle is the immense variety of POC instruments in the field, each with unique data formats and connectivity requirements, making the development of a truly universal connectivity solution exceptionally complex.
- Cross-Jurisdictional Compliance:Vendors face the significant challenge of designing and maintaining a single software platform that can simultaneously adhere to the disparate and evolving data privacy and medical device regulations across North America, Europe, and Asia.
- Specialized Talent Shortage:A deficit of IT professionals who possess a hybrid skillset in clinical informatics, cybersecurity, and network engineering complicates the deployment, management, and security of these sophisticated systems within healthcare organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point of Care (POC) Data Management Systems Market |
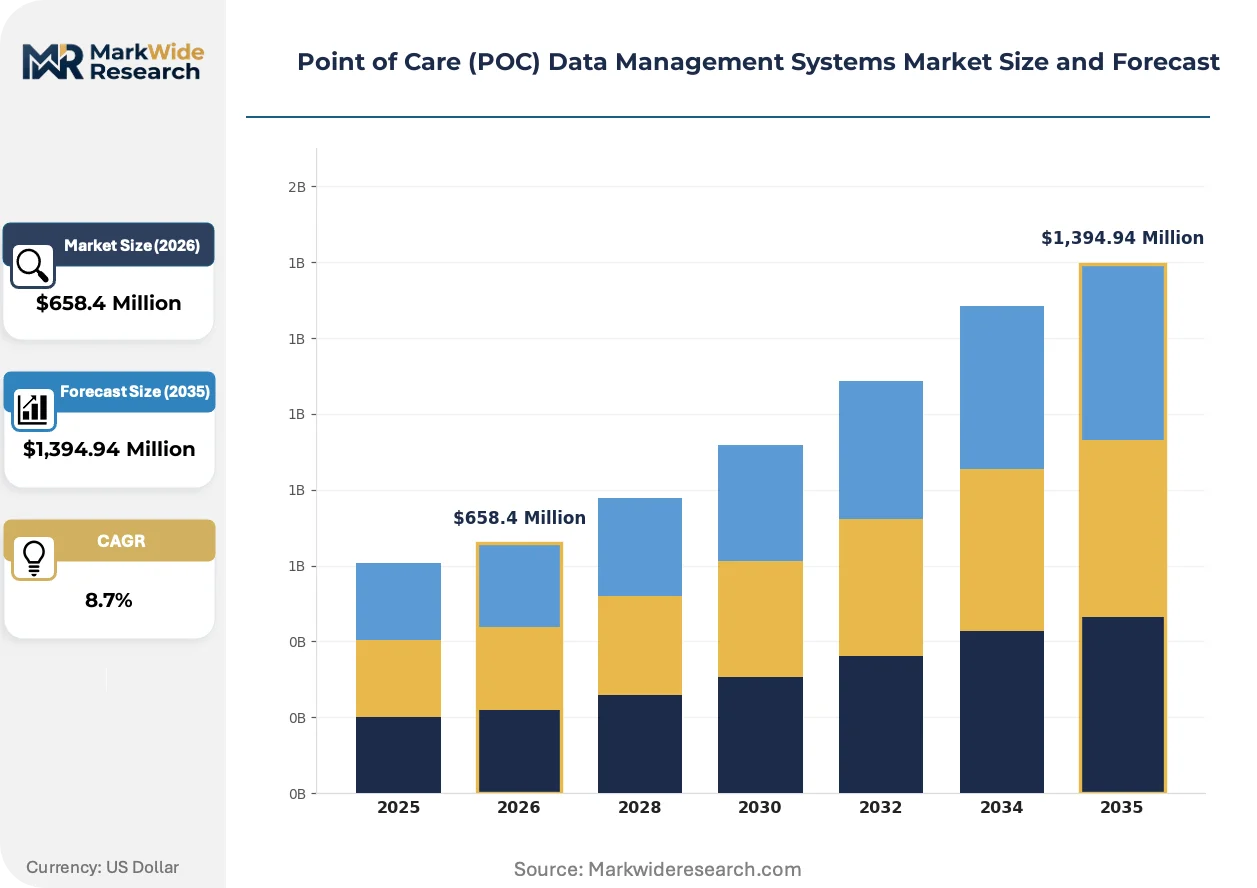
| Market Size in 2026 | $658.4 Million |
| Market Size in 2035 | $1,394.94 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
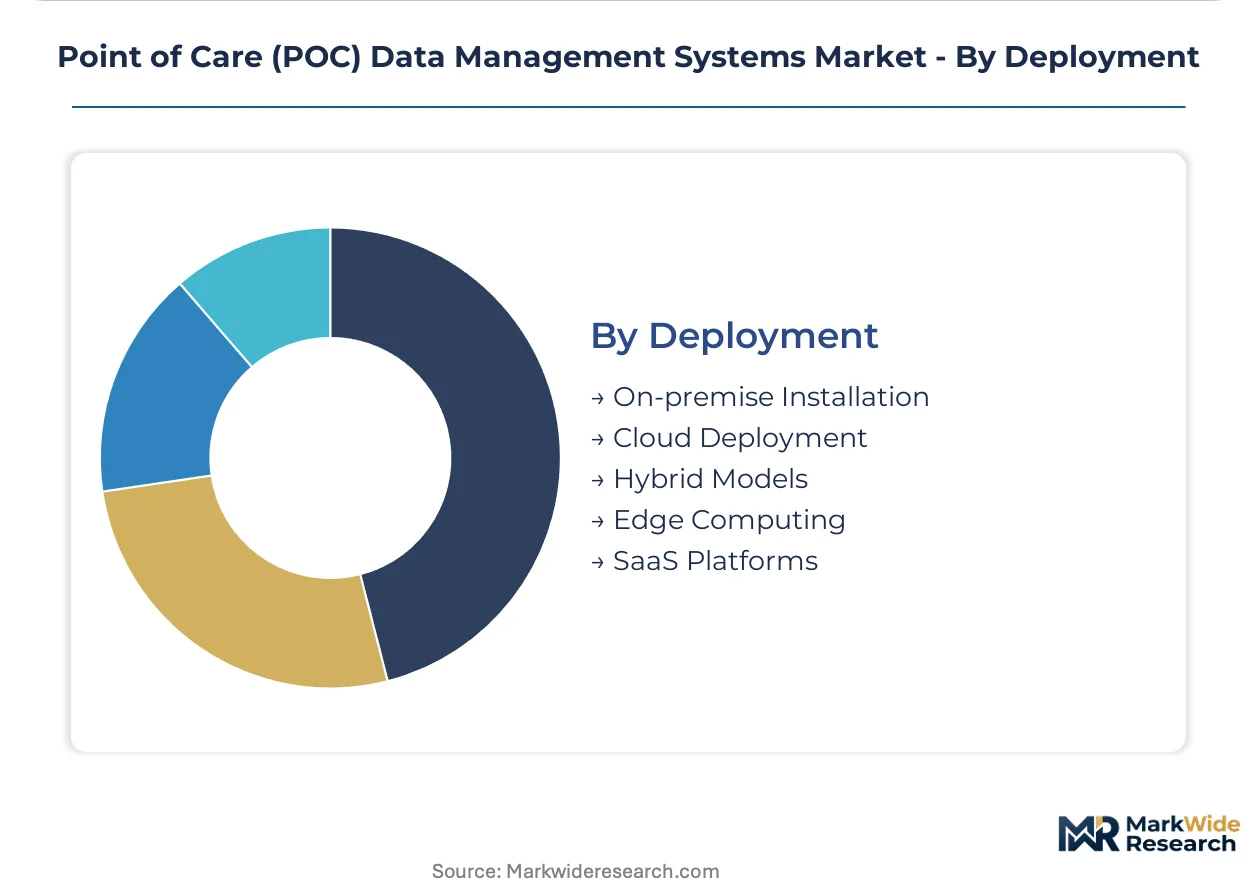
| Segmentation | Product Type: Real-time Data Management, Remote Monitoring Systems, Integrated Software Platforms, Cloud-based Solutions, Mobile Data Collection Application: Clinical Diagnostics, Patient Monitoring, Laboratory Information Management, Medication Management, Emergency Response End User: Diagnostic Laboratories, Home Healthcare Providers, Blood Banks, Ambulatory Surgical Centers, Telemedicine Services Deployment: On-premise Installation, Cloud Deployment, Hybrid Models, Edge Computing, SaaS Platforms |
| Companies Covered | Siemens Healthineers, Abbott Laboratories, Danaher Corporation, F. Hoffmann-La Roche Ltd, TELCOR Inc., Thermo Fisher Scientific, Radiometer Medical ApS, Randox Laboratories Ltd, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point of Care (POC) Data Management Systems Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward intelligent automation and enhanced data security at the network edge. This movement prioritizes real-time decision support and analytical capabilities directly at the point of care, rather than simple data aggregation.
Edge computing is gaining traction as a core architectural component in modern POC data management. This technology enables on-device or near-device data processing, reducing latency for critical results and minimizing the transmission of raw patient data over networks. Large hospital systems are adopting edge solutions to bolster security and ensure faster turnaround times in emergency departments and intensive care units. This architecture is converging with centralized cloud platforms, enabling a hybrid model that provides immediate local analysis while supporting large-scale, long-term analytics.
The European Union's Medical Device Regulation (MDR) is fundamentally altering software development and validation processes. It classifies many data management systems as medical devices, subjecting them to stricter requirements for clinical evaluation, risk management, and post-market surveillance. This regulatory pressure is forcing vendors to increase their investment in quality management systems and clinical validation to maintain CE marking and access the European market. The clinical diagnostics segment, in particular, is heavily impacted by these heightened documentation and traceability demands.
A notable behavioral shift is occurring in how healthcare systems acquire this technology, moving from one-time perpetual license purchases to subscription-based models. This change aligns software costs with operational budgets rather than capital expenditures, providing greater financial flexibility. The trend disrupts the traditional sales cycle, favoring vendors who can offer scalable, cloud-hosted solutions with predictable recurring revenue streams. This model is most prevalent in North American and German hospital networks seeking to standardize technology across multiple facilities without a massive initial outlay.
Point of Care (POC) Data Management Systems Market Segmentation
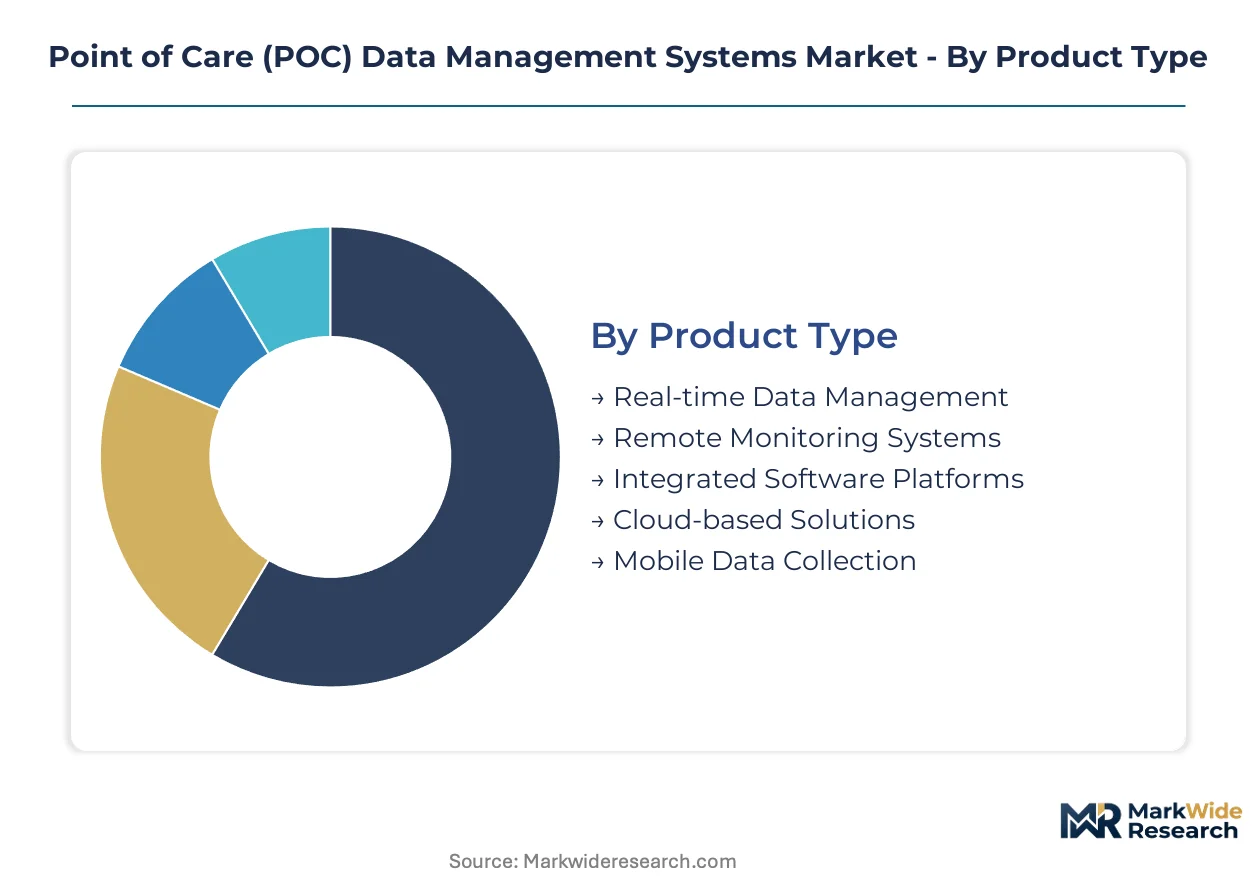
The Point of Care (POC) Data Management Systems market is analyzed across several key dimensions, revealing the intricate landscape of technological offerings and user adoption. Understanding these segments provides clarity on market demand patterns and the strategic emphasis for vendors. Each category highlights distinct functional requirements and operational considerations for healthcare providers.
Product Type:
Product types within POC data management systems face varying regulatory scrutiny, with some requiring stringent medical device certifications from bodies like the FDA or for CE marking under the EU MDR.
- Integrated Software Platforms:These platforms consolidate disparate solutions into unified systems, streamlining data flow across hospital networks. Demand for these integrated offerings is strong in Germany's hospital networks, driven by regulatory compliance and efficiency needs.
- Cloud-based Solutions:Cloud-based solutions offer scalable and accessible data storage and processing, reducing on-premise IT infrastructure demands. Adoption is accelerating in the United States and the United Kingdom, particularly among large healthcare systems adopting subscription models.
- Real-time Data Management:These systems focus on immediate data capture and processing, crucial for rapid clinical decision-making at the point of care.
- Remote Monitoring Systems:Solutions designed to collect and transmit patient data from devices in home or remote settings, supporting chronic disease management.
- Mobile Data Collection:This segment includes applications and tools for gathering POC data via mobile devices, enhancing flexibility for healthcare professionals.
Integrated Software Platforms currently sit at the top of the volume ranking, with Cloud-based Solutions climbing the fastest.
Application:
Applications for POC data management systems range across the clinical workflow, each addressing specific operational needs and data integration challenges within healthcare settings.
- Clinical Diagnostics:This application segment supports the capture and integration of results from various diagnostic POC devices, ensuring data availability for patient records. The European Union's MDR significantly impacts system design and validation for these diagnostic applications.
- Patient Monitoring:Systems in this segment manage data from continuous patient monitoring devices, crucial for tracking vital signs and managing chronic conditions. Telemedicine expansion in Canada and Australia drives significant demand for these capabilities.
- Laboratory Information Management:These systems extend central laboratory capabilities to POC settings, enabling seamless integration with existing lab workflows.
- Medication Management:This application focuses on tracking medication administration and adherence data collected at the point of care.
- Emergency Response:POC data management supports rapid data collection and transmission during emergency situations, aiding critical care decisions.
Clinical Diagnostics maintains its position as the market share leader, while Patient Monitoring demonstrates particularly rapid expansion.
End User:
End-user segments reflect diverse organizational structures and patient care models, influencing the specific features and scalability required from POC data management solutions.
- Telemedicine Services:These services directly leverage POC data management systems to integrate remote patient data into virtual care platforms. The proliferation of telehealth in India and Brazil is a significant demand driver.
- Home Healthcare Providers:This segment utilizes POC data systems for managing patient information and test results collected during in-home visits. Growth in home-based care in Japan and France increases demand for these solutions.
- Diagnostic Laboratories:Traditional laboratories integrate POC data to centralize patient records and improve operational efficiency.
- Ambulatory Surgical Centers:These facilities require efficient POC data management for pre-operative assessments and post-operative monitoring.
- Blood Banks:POC data systems assist blood banks in managing donor information, testing results, and inventory control.
Diagnostic Laboratories constitute the largest user base, with Telemedicine Services exhibiting dynamic growth in adoption.
Deployment:
Deployment models vary significantly based on IT infrastructure, security preferences, and the scale of data processing required by healthcare organizations.
- Cloud Deployment:This model hosts POC data management solutions on remote servers accessed via the internet, offering scalability and reduced infrastructure costs. Healthcare systems in the United States and Singapore increasingly prefer cloud-native solutions for their flexibility.
- Edge Computing:Edge computing processes data closer to the source, reducing latency and enhancing data security for critical POC applications. Large hospital systems in Germany and Sweden adopt edge solutions for emergency departments.
- On-premise Installation:This traditional deployment involves hosting software and data on local servers within the healthcare facility.
- Hybrid Models:Hybrid deployments combine elements of both on-premise and cloud solutions, balancing control with scalability.
- SaaS Platforms:Software-as-a-Service platforms offer subscription-based access to POC data management solutions, simplifying procurement and maintenance.
Cloud Deployment represents the dominant deployment model, while Edge Computing is emerging as a preferred architectural choice for specific use cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospital networks drive significant demand for integrated data management solutions, reflecting a broader trend across developed healthcare systems. These regions prioritize robust data handling capabilities and strict regulatory compliance. The global market shows varied adoption patterns influenced by local infrastructure and healthcare priorities.
Germany
Demand for integrated software platforms in Germany stems from stringent regulatory compliance and a focus on operational efficiency within hospital networks. The EU MDR heavily influences system design and validation, demanding increased investment in quality management. Major hospital systems in cities like Berlin and Munich are actively adopting edge computing solutions for critical applications.
United States
The United States market for POC data management systems benefits from the expansion of telemedicine services and chronic disease management programs. HIPAA compliance and FDA clearance are mandatory for patient data handling, compelling significant vendor investment in security. Large healthcare systems across California and the Northeast are increasingly preferring cloud-native solutions with subscription models.
Canada
Telemedicine expansion in Canada drives significant demand for patient monitoring systems capable of integrating data from remote POC devices. Health Canada regulations mandate secure and interoperable solutions for medical devices and patient data. Healthcare facilities in provinces like Ontario and British Columbia are implementing advanced systems to support virtual care delivery.
India
India represents a significant growth opportunity due to the proliferation of telehealth services and the development of new healthcare infrastructure. Guidelines from the CDSCO shape the regulatory landscape for medical devices and software in the country. Major metropolitan areas like Mumbai and Bangalore are seeing substantial investment in modern, integrated data management solutions.
Japan
The growth of home-based care and an aging population are key demand drivers for remote monitoring systems in Japan. PMDA approval is essential for market access, ensuring device safety and efficacy. Integrated healthcare providers in regions such as Tokyo and Osaka are implementing sophisticated POC data systems to manage patient information efficiently.
Point of Care (POC) Data Management Systems Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces like AI-driven analytics and decentralized trial support. This market undergoes consolidation, favoring vendors with comprehensive portfolios and strong integration capabilities. Strategic archetypes include specialized connectivity solution developers, comprehensive platform providers, and niche application specialists. Competitive moves center on portfolio diversification and strategic partnerships to expand market reach.
On the integrated platform vector, Siemens Healthineers, a German multinational, leverages its extensive diagnostic hardware footprint to bundle data management software. Abbott Laboratories, a US-based corporation, represents a strong contender with its Alinity and ID NOW platforms, enabling seamless data integration. F. Hoffmann-La Roche Ltd, a Swiss healthcare company, occupies a distinct position through its cobas infinity IT solutions, supporting extensive laboratory automation.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Abbott Laboratories |
| Danaher Corporation |
| F. Hoffmann-La Roche Ltd |
| TELCOR Inc. |
| Thermo Fisher Scientific |
| Radiometer Medical ApS |
| Randox Laboratories Ltd |
| Becton, Dickinson and Company |
Cost & Logistics Intelligence
Family-owned mid-caps and large multinational corporations influence both the supply of integrated POC data platforms and their associated pricing discipline. Their extensive R&D budgets allow for comprehensive software development and regulatory compliance. This market structure often favors vendors with established hardware footprints, enabling bundling strategies that impact overall solution costs.
Pricing Analysis
Input-cost pass-through primarily affects vendors through specialized talent acquisition and ongoing regulatory compliance expenses. Subscription-based models are becoming the dominant pricing structure, aligning software costs with operational budgets for healthcare providers. Price differentiation stems from the level of integration with existing EHRs and the depth of after-sales support. Pricing softness runs through smaller clinics due to high implementation costs, while large hospital networks demonstrate less price sensitivity for compliant, integrated solutions.
Supply Chain Analysis
Reverse-logistics for POC data management systems primarily involves software updates and data migration processes, rather than physical returns. The supply of core software development talent concentrates in technology hubs across the United States, Germany, and Switzerland. Raw material dependencies include highly skilled software engineers, cybersecurity experts, and cloud infrastructure services. A specialized talent shortage represents a structural risk to continuous innovation and system deployment. Distribution runs through direct sales teams targeting large healthcare systems and strategic partnerships with diagnostic hardware manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with frameworks like the EU MDR directly compelling significant investment in compliant data management systems. This regulatory pressure ensures sustained demand for validated solutions.
For Market Incumbents: Anchor existing diagnostic hardware footprints by deeply integrating data management software into device ecosystems. Leverage comprehensive portfolios to offer end-to-end solutions, mitigating threats from niche application specialists. Prioritize investment in quality management systems and clinical validation to maintain regulatory access across diverse jurisdictions. Focus R&D on AI and predictive analytics to enhance value propositions and differentiate from emerging players.
For New Entrants and Emerging Players: Capture white-space opportunities in emerging market infrastructure, particularly in regions building out new hospital networks. Target decentralized clinical trials with compliant POC data systems capable of secure data capture from remote settings. The most penetrable segment remains cloud-native, subscription-based solutions offering robust cybersecurity for smaller clinics. Go-to-market strategies should emphasize ease of integration and lower upfront capital expenditure.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized connectivity solution developers or niche application specialists with strong intellectual property in AI. Long-term viability is strong for platforms demonstrating superior cross-jurisdictional compliance and robust integration capabilities. Acquisition targets should possess proven AI/ML algorithms or established compliance track records in critical regions like Europe. Monitor the adoption rates of edge computing in emergency departments for early signals of architectural shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates disparate software solutions, streamlining data flow for healthcare providers. |
| Strategic Partnership | Expands market reach and interoperability with diverse diagnostic instruments and EHRs. |
| Acquisition of Specialist Firm | Enhances AI/ML capabilities or strengthens compliance expertise in specific regulatory domains. |
| Geographic Expansion | Accesses growing demand in telemedicine services within emerging healthcare systems. |
| Product Launch (AI/Predictive Analytics) | Offers advanced value-add services for real-time decision support and population health trends. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and internal databases — were reconciled to build a comprehensive market view. This involved engaging with clinical informatics specialists, hospital procurement managers, regulatory affairs leads, and software architects. Secondary data sources included FDA filings, EU MDR guidelines, healthcare IT vendor reports, and medical device databases. Bottom-up and top-down triangulation methods were applied to ensure data accuracy and consistency.
Data-stream reconciliation informed the analytical framework, which modeled volume and value outputs across the analysis window. Segmentation dimensions included product type, application, end-user, deployment model, and regional regulatory landscape. Compound annual growth rates were derived from historical trends and projected market dynamics, incorporating specific industry inputs. Key forecast inputs included telemedicine adoption rates and investments in regulatory compliance.
Evolving regulatory frameworks, technological advancements in AI, and cybersecurity threats are the dominant revision risks to market projections. Forecasts reflect assumptions regarding market dynamics and technological progression. Practitioners should monitor regulatory updates and vendor investment in security for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Global Healthcare Content Management System Market
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
Point-Of-Care Data Management Software Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
Global Healthcare Customer Data Platform Market
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
North America Healthcare Analytics Market
Health Data Management
Global Precision Medicine Software Market
Health Data Management
Healthcare Data De-Identification Assurance Market