
 Global Healthcare Compliance Software Market | 2026-2036
Global Healthcare Compliance Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Compliance Software Market Foresight
Multi-source procurement of compliance modules is consolidating as health systems abandon fragmented point solutions. Healthicity leverages cloud-native architecture to compete in policy automation, while RLDatix anchors incident management workflows across integrated delivery networks. Symplr differentiates through credentialing specialization, and MedTrainer sustains training compliance revenue in ambulatory settings.
Healthcare compliance software comprises integrated platforms that automate regulatory adherence, risk assessment, and audit documentation through configurable rule engines, real-time monitoring dashboards, and encrypted data pipelines designed for HIPAA and GDPR interoperability. Cloud-based deployment leads adoption among hospitals seeking scalable infrastructure without capital expenditure, while SaaS models capture recurring revenue from telemedicine providers building compliance from inception. Risk management applications dominate value pools as cyber threats and billing fraud investigations intensify, though data security modules are expanding fastest among diagnostic centers handling cross-border patient information.
FDA 21 CFR Part 11, HIPAA Security Rule, and EU AI Act compliance requirements are reshaping product roadmaps and procurement criteria across the sector. The EU's CSRD reporting obligations and India's Digital Information Security in Healthcare Act are forcing vendors to embed jurisdiction-specific audit trails. Stakeholders must evaluate whether platform architectures can adapt to divergent regulatory timelines without costly reconfiguration.
Market Dynamics
Health systems are abandoning fragmented point solutions for unified compliance platforms as HIPAA Security Rule audits and EU AI Act enforcement intensify documentation requirements. This procurement consolidation is compressing vendor margins while elevating architecture flexibility as the primary competitive differentiator.
Growth Catalysts
- EU AI Act enforcement:Automated audit trails for algorithmic decision-making in diagnostic imaging are becoming mandatory across European hospitals, forcing replacement of legacy documentation systems.
- Diagnostic center expansion:Cross-border patient data flows between Germany, Switzerland, and Austria are requiring GDPR-interoperable encryption modules that cloud-native platforms uniquely provide.
- Telemedicine provider proliferation:SaaS compliance suites allow virtual care startups to embed HIPAA-compliant data pipelines from inception without capital expenditure.
Market Restraints
- Specialized talent scarcity:Health informaticists with dual expertise in clinical workflows and regulatory engineering command premium compensation, inflating implementation costs.
- Input concentration risk:Cloud infrastructure dependencies on hyperscale providers in the United States create jurisdictional data sovereignty conflicts for EU-based health systems.
- Technical debt burden:On-premise legacy systems in Japanese hospitals resist API-based integration with modern compliance dashboards, extending deployment timelines.
Strategic Opportunities
- India's DISHA implementation:The Digital Information Security in Healthcare Act mandates audit-ready data governance for 1.4 billion patient records, creating localized platform demand.
- Convergence of AI and blockchain:Immutable audit trails for machine-learning model versioning address FDA 21 CFR Part 11 requirements in pharmaceutical manufacturing compliance.
- Embedded insurance partnerships:Cyber liability underwriters in Germany are mandating real-time compliance monitoring as a condition of coverage, creating channel-integrated revenue streams.
Industry Challenges
- Interoperability certification delays:ONC Health IT Certification timelines for 21st Century Cures Act compliance extend sales cycles for US-based vendors by 8-14 months.
- Legacy EHR integration friction:Epic and Cerner installations in academic medical centers resist third-party compliance module embedding without costly professional services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Compliance Software Market |
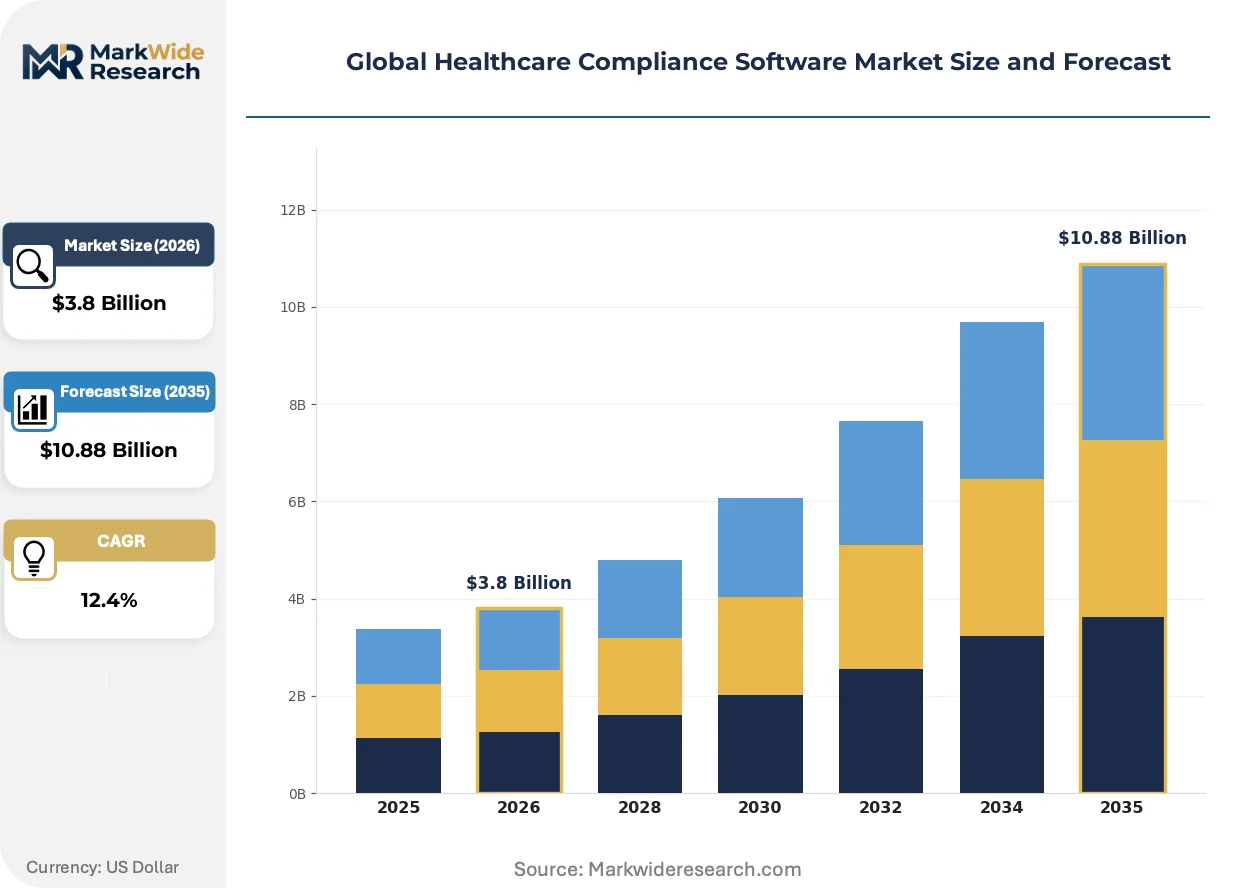
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Risk Management, Policy Management, Training Management, Incident Management, Audit Management Deployment: Cloud-Based, On-Premise, Web-Based, Hybrid, SaaS Application: Patient Records Auditing, Regulatory Reporting, Staff Credentialing, Quality Assurance, Data Security End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Rehabilitation Facilities, Telemedicine Providers |
| Companies Covered | Healthicity, Compliancy Group, RLDatix, HealthStream, ConvergePoint, Accountable HQ, Symplr, MedTrainer, Sprinto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Compliance Software Market Shifts & Advancements
Natural language processing engines are transforming how compliance documentation gets generated, reviewed, and submitted to regulators. This automation wave is compressing audit preparation timelines while raising the bar for platform intelligence.
Machine learning-based policy interpretation engines are automating the translation of regulatory text into configurable workflow rules. Hospital legal departments in the United States are adopting these tools to reduce manual policy review cycles from weeks to hours. The structural consequence is a shift from reactive compliance audits to continuous automated monitoring that flags deviations before they become violations.
The EU AI Act's risk classification framework for medical devices is forcing vendors to embed jurisdiction-specific audit trails by design. Manufacturers must now document algorithmic training data provenance and performance drift for high-risk diagnostic applications. German notified bodies are requiring this documentation as a precondition for CE marking, compressing product launch timelines for AI-enabled imaging tools.
Consolidated purchasing by integrated delivery networks is displacing departmental point-solution procurement. US-based health systems with 10+ hospitals are mandating enterprise-wide compliance platforms that span credentialing, incident management, and training. This concentration is visible most acutely in Texas and Florida, where hospital mergers have created mega-systems with standardized vendor requirements.
Global Healthcare Compliance Software Market Segmentation
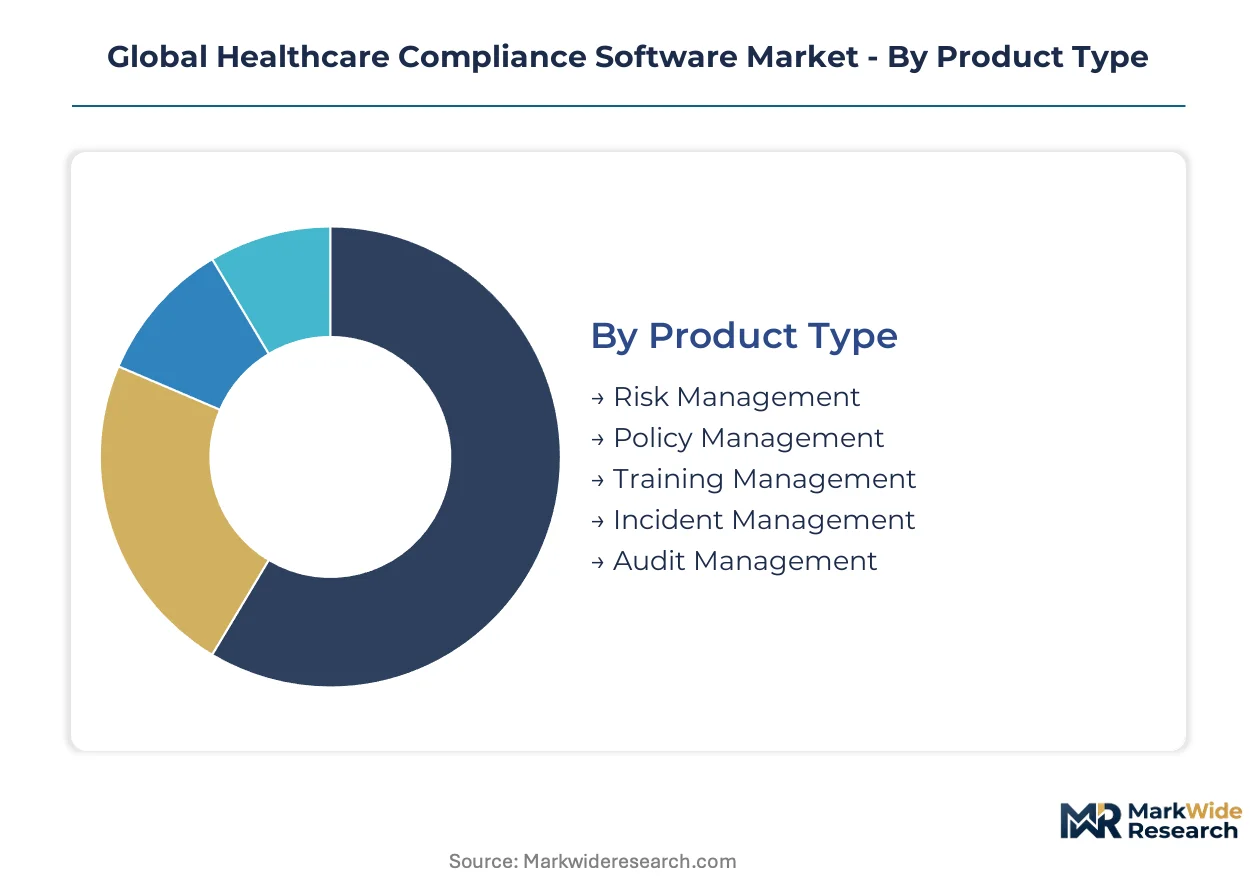
Healthcare compliance software segments reflect divergent upgrade cycles across infrastructure maturity levels. Procurement patterns vary sharply between institutions replacing legacy on-premise systems and cloud-native entrants building compliance stacks from inception.
Product Type:
Replacement cycles accelerate where audit complexity outpaces legacy system capabilities.
- Risk Management:Platforms integrating predictive analytics for cyber threats and billing fraud detection. United States hospitals facing intensified HIPAA Security Rule enforcement are prioritizing these modules over standalone policy tools.
- Policy Management:Cloud-native rule engines translating regulatory text into executable workflows. German hospital networks under EU AI Act pressure are consolidating fragmented documentation systems into unified policy automation suites.
- Training Management:LMS modules tracking certification status across clinical and administrative staff.
- Incident Management:Workflow tools for adverse event reporting and root-cause analysis.
- Audit Management:Documentation engines preparing evidence packages for regulator inspection.
Volume placements concentrate in Risk Management; the faster expansion belongs to Policy Management.
Deployment:
Cost tier stratification separates capital-constrained ambulatory settings from enterprise health systems with infrastructure budgets.
- Cloud-Based:Scalable architectures eliminating server procurement and maintenance overhead. India's diagnostic chains preparing for DISHA implementation are adopting these deployments to avoid data center capital expenditure.
- SaaS:Subscription models embedding compliance from telemedicine platform inception. United States virtual care startups use these suites to satisfy HIPAA requirements without dedicated IT departments.
- On-Premise:Air-gapped installations serving Japanese hospitals with legacy EHR dependencies resisting API integration.
- Web-Based:Browser-accessible platforms for mid-sized rehabilitation facilities with limited technical staff.
- Hybrid:Configurations splitting sensitive data on-premise while leveraging cloud analytics.
Cloud-Based deployments dominate current procurement volume; SaaS models are climbing the fastest among new market entrants.
Application:
Application selection tracks where regulatory enforcement creates immediate liability exposure.
- Data Security:Encryption modules and access control systems for cross-border patient information flows. Diagnostic centers in Germany, Switzerland, and Austria handling GDPR-interoperable data are driving specialized demand.
- Regulatory Reporting:Automated submission engines for FDA, EMA, and national healthcare authority documentation. Pharmaceutical manufacturers under 21 CFR Part 11 requirements anchor this segment.
- Patient Records Auditing:Tools verifying HIPAA and GDPR compliance in EHR access patterns.
- Staff Credentialing:Verification systems tracking licensure status and continuing education completion.
- Quality Assurance:Modules monitoring clinical pathway adherence and outcome metrics.
Data Security applications command the largest implementation budgets; Regulatory Reporting is gaining share fastest as AI Act enforcement tightens.
End User:
Customer type determines platform complexity requirements and integration depth.
- Hospitals:Enterprise-grade suites spanning credentialing, incident management, and training across integrated delivery networks. Texas and Florida mega-systems with 10+ facilities are mandating standardized vendor selection.
- Telemedicine Providers:Lightweight SaaS stacks built for HIPAA compliance from platform launch. These entrants lack legacy technical debt and prioritize rapid deployment over feature breadth.
- Diagnostic Centers:Specialized modules for imaging AI audit trails and cross-border data governance.
- Ambulatory Surgical Centers:Focused tools for procedure-specific quality assurance and staff certification tracking.
- Rehabilitation Facilities:Simplified platforms emphasizing outcome documentation for payer reimbursement.
Hospitals account for the greatest absolute procurement volume; telemedicine providers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center infrastructure in Northern Virginia and hyperscale cloud regions across the United States anchor the geographic foundation for healthcare compliance software deployment. Regulatory divergence between HIPAA enforcement and EU AI Act mandates creates distinct procurement patterns across national boundaries. Vendor architectures must accommodate these jurisdictional fractures without reconfiguration penalties.
United States
Texas and Florida hospital mega-systems with standardized vendor requirements are consolidating enterprise-wide compliance platform procurement. HIPAA Security Rule audits and FDA 21 CFR Part 11 enforcement intensify documentation automation demand. The Dallas-Fort Worth corridor hosts integrated delivery networks replacing fragmented point solutions with unified credentialing and incident management suites.
Germany
Diagnostic imaging AI manufacturers face compressed CE marking timelines as notified bodies mandate algorithmic audit trails for high-risk applications. EU AI Act risk classification frameworks and GDPR-interoperable encryption requirements reshape platform specifications. The Munich-Stuttgart axis concentrates pharmaceutical manufacturing compliance vendors adapting to CSRD reporting obligations.
India
Diagnostic chains preparing for DISHA implementation are adopting cloud-native deployments to avoid data center capital expenditure. The Digital Information Security in Healthcare Act mandates audit-ready governance for patient records across 1.4 billion population coverage. Bengaluru and Hyderabad clusters host telemedicine startups embedding HIPAA-compliant SaaS stacks from platform inception.
Japan
Academic medical centers with legacy EHR dependencies resist API-based compliance module integration, extending deployment timelines. METI guidance on healthcare data sovereignty creates friction with hyperscale cloud infrastructure concentration. The Tokyo-Osaka corridor concentrates hospitals maintaining air-gapped installations for sensitive patient data while leveraging cloud analytics for non-critical workflows.
Switzerland
Cross-border patient data flows between German, Austrian, and Swiss diagnostic centers require specialized GDPR-interoperable encryption modules. Swissmedic oversight of medical device software creates dual-track compliance requirements for AI-enabled diagnostic tools. The Basel-Zurich corridor anchors pharmaceutical manufacturing compliance platforms addressing FDA and EMA simultaneous submission requirements.
Global Healthcare Compliance Software Market Competitive Landscape
Global majors compete with regional champions across architecture flexibility and jurisdiction-specific certification depth. The vendor base stratifies into three tiers: cloud-native entrants building compliance stacks from inception, legacy platform modernizers bridging on-premise technical debt, and specialized credentialing or training module providers. Two dominant competitive moves are consolidating procurement across integrated delivery networks and embedding real-time compliance monitoring as cyber liability insurance preconditions.
Within the cloud-native tier, Healthicity and Sprinto exemplify architecture-first positioning for policy automation and continuous control monitoring. RLDatix anchors the incident management workflow specialization segment across North American hospital networks. These three companies represent distinct archetypes: Healthicity occupies the regulatory translation engine position, Sprinto sits within the automated audit trail automation category, and RLDatix exemplifies adverse event reporting platform consolidation.
| Leading Market Players |
|---|
| Healthicity |
| Compliancy Group |
| RLDatix |
| HealthStream |
| ConvergePoint |
| Accountable HQ |
| Symplr |
| MedTrainer |
| Sprinto |
| Others |
Supply & Pricing Matrix
Cloud-native platform migration simultaneously compresses data center infrastructure costs and concentrates vendor bargaining power among hyperscale providers in the United States. This technology shift reshapes procurement economics as health systems trade capital expenditure for recurring subscription commitments, altering how compliance software vendors structure margins and pass through infrastructure savings.
Pricing Analysis
Implementation support and ongoing regulatory update subscriptions are increasingly bundled into base SaaS tiers rather than unbundled as professional services. Pricing stratifies across enterprise, mid-market, and entry-level tiers based primarily on audit trail retention depth and jurisdiction-specific certification coverage. Cost compression in the entry tier is intensifying because telemedicine startups demand HIPAA-ready configurations at minimal upfront commitment. Ambulatory surgical centers exhibit the highest price sensitivity, while integrated delivery networks in Texas and Florida prioritize comprehensive coverage over per-seat economics.
Supply Chain Analysis
Health informaticists with dual clinical and regulatory engineering expertise are scarcest in Bengaluru, Hyderabad, and Dallas-Fort Worth, constraining deployment velocity for complex implementations. Cloud infrastructure draws from hyperscale data centers concentrated in Northern Virginia, Frankfurt, and Mumbai, with encryption module development anchored in Germany and Switzerland. Single-source vulnerability runs through AWS and Azure dominance in healthcare workloads. Distribution runs through direct enterprise sales teams for hospital systems and channel partners for ambulatory settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EU AI Act enforcement and HIPAA audit intensification force smaller point-solution vendors toward acquisition or exit. Procurement standardization across merged health systems is accelerating this Darwinian pressure.
For Market Incumbents: Extend policy automation capabilities into adjacent risk management workflows before cloud-native entrants capture integrated delivery network standardization mandates. Defend position by embedding real-time compliance monitoring as cyber liability insurance preconditions, creating switching costs that protect recurring revenue streams against modular competitors. For New Entrants and Emerging Players: Capture India's DISHA implementation window by localizing audit-ready data governance architectures for diagnostic chains avoiding capital expenditure. Target telemedicine providers in the United States with lightweight SaaS stacks that embed HIPAA compliance from platform inception without dedicated IT infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by cloud-native platform consolidators seeking credentialing or incident management specialization. Long-term viability favors vendors with jurisdiction-specific certification depth spanning HIPAA, EU AI Act, and DISHA requirements. Watch FDA 21 CFR Part 11 enforcement intensity in pharmaceutical manufacturing as the inflection signal for compliance documentation automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified compliance suites displace fragmented point solutions across merged hospital systems. |
| Regulatory Certification Investment | EU AI Act and DISHA audit trail mandates create jurisdictional moats for certified vendors. |
| Strategic Partnership | Cyber liability underwriters in Germany mandate real-time monitoring as coverage precondition. |
| Acquisition of Specialist Firm | Credentialing and training module providers fill capability gaps in enterprise platform portfolios. |
| Geographic Expansion | India's diagnostic chains seek cloud-native deployments to satisfy DISHA without data center capex. |
Research Methodology
Document review covered FDA 21 CFR Part 11 guidance documents, EU AI Act implementation texts, and hospital procurement databases, complemented by interviews with compliance officers, health informaticists, GPO contracts managers, and biomedical engineers at integrated delivery networks. Secondary validation drew from CMS Medicare data, SEC filings of publicly traded health IT vendors, and hyperscaler healthcare cloud capex disclosures. Bottom-up deployment estimates across cloud, SaaS, and on-premise models were triangulated against top-down health system IT budget allocations.
Market size outputs reflect segment-level modeling across risk management, policy management, training management, incident management, and audit management product types, deployment modes, application areas, and end-user categories over the projection horizon. CAGRs were derived from regression analysis of historical procurement velocity against regulatory enforcement intensity and cloud infrastructure adoption curves. Forecast inputs incorporated HIPAA audit frequency projections, EU AI Act phased implementation timelines, and DISHA readiness assessments across Indian states.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA enforcement unpredictability, EU AI Act delegated act revisions, and hyperscale cloud data sovereignty disputes. Forecasts reflect documented assumptions about regulatory timeline adherence and health system merger momentum. A small set of named triggers—FDA warning letter volume, notified body CE marking backlog, and Indian state-level DISHA pilot outcomes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Americas Healthcare Archiving and Ediscovery Market
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Healthcare Data Annotation Tools Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Global Healthcare Customer Data Platform Market
Health Data Management
Health Care Quality Management Software Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
Global Healthcare Content Management System Market
Health Data Management
Healthcare Data Collection and Labeling Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Hospital Management Software Market