
 Europe Healthcare Analytics Market | 2026-2036
Europe Healthcare Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Healthcare Analytics Market Foresight
Germany is tilting toward centralized health data infrastructure with substantial federal investment in interoperable electronic health record systems. IBM Corporation leverages its Watson Health platform to anchor clinical AI deployments across university hospitals in Berlin and Munich. Siemens Healthineers AG sustains deep R&D intensity in radiology analytics, while Oracle Corporation competes aggressively on cloud-based enterprise health data architectures for multi-hospital networks.
Healthcare analytics denotes the computational analysis of clinical, operational, and financial health data using statistical algorithms, machine learning models, and natural language processing to extract actionable intelligence for care delivery optimization. Systems typically process structured diagnostic codes alongside unstructured clinical notes, requiring FHIR-compliant data pipelines and sub-second query latency for real-time alerting. Predictive analytics leads segment value generation through early warning scores and readmission risk models that command premium licensing fees. Cloud-Based deployment is expanding fastest as NHS trusts and Scandinavian hospital networks migrate from legacy on-premise data warehouses, though On-Premise systems retain dominance in jurisdictions with strict data localization mandates.
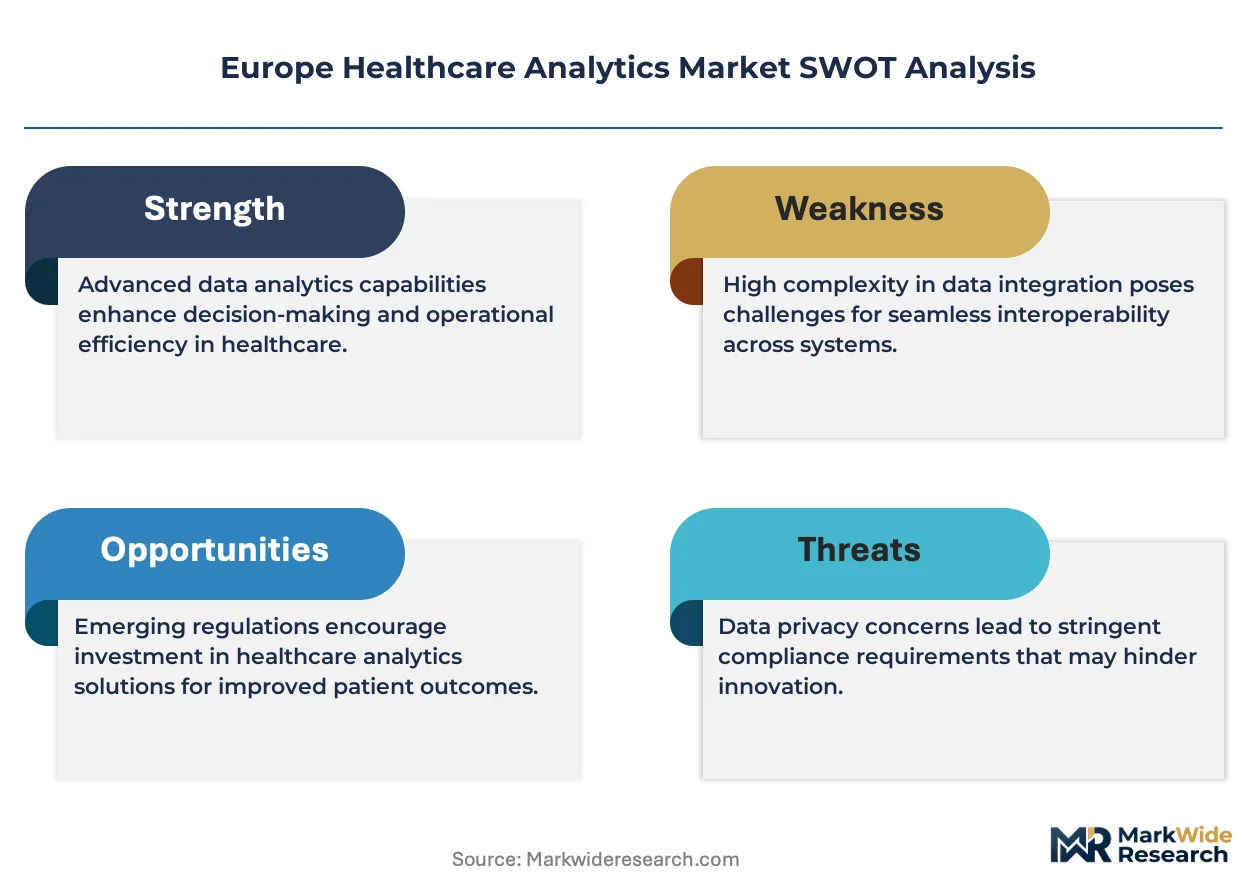
EMA guidelines on real-world evidence and the EU AI Act's risk-classification framework for medical software are tightening validation requirements for algorithmic diagnostic tools, directly shaping vendor product roadmaps and hospital procurement criteria. GDPR and national implementations such as Germany's BDSG impose granular consent management and pseudonymization standards that increase implementation complexity for cross-border analytics platforms. Stakeholders must monitor how the European Health Data Space regulation evolves data portability rules and whether interoperability mandates will commoditize underlying infrastructure layers or concentrate value in specialized clinical AI applications.
Market Dynamics
The EU AI Act's risk-classification framework for medical software is forcing vendors to restructure product validation pipelines and hospital procurement committees to rewrite algorithmic procurement criteria across university hospital networks.
Growth Catalysts
- Chronic Disease Surveillance:NHS trusts in England deploy predictive readmission risk models for heart failure and COPD cohorts, commanding premium licensing fees from specialized clinical AI vendors.
- GDPR-Compliant Cloud Migration:Scandinavian hospital networks accelerate migration from legacy on-premise data warehouses to FHIR-compliant cloud architectures with sub-second query latency for real-time alerting.
- Federal Interoperability Mandates:Germany's BDSG implementation drives substantial federal investment in interoperable electronic health record systems connecting Berlin and Munich university hospitals.
Market Restraints
- Granular Consent Architecture:GDPR pseudonymization standards and national implementations increase implementation complexity for cross-border analytics platforms processing unstructured clinical notes.
- Validation Timeline Compression:EMA guidelines on real-world evidence tighten validation requirements for algorithmic diagnostic tools, extending product roadmaps by 18-24 months.
- Data Localization Requirements:Strict data localization mandates in select jurisdictions retain dominance of On-Premise systems despite cloud expansion.
Strategic Opportunities
- Underpenetrated Eastern European Networks:Hospital systems in Poland and Romania present white space for radiology analytics deployment with limited incumbent vendor presence.
- European Health Data Space:Evolving data portability rules under this regulation may commoditize infrastructure layers while concentrating value in specialized clinical AI applications.
- Real-Time Monitoring Convergence:Integration of IoT sensor streams with natural language processing of clinical notes enables continuous patient deterioration detection in French ICU networks.
Industry Challenges
- Specialized Talent Scarcity:Shortage of biostatisticians and clinical informaticists capable of bridging FHIR data pipelines with machine learning model deployment in hospital IT departments.
- Legacy System Integration Friction:Decades-old hospital information systems in German Krankenhaus networks resist seamless API connectivity with modern analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Healthcare Analytics Market |
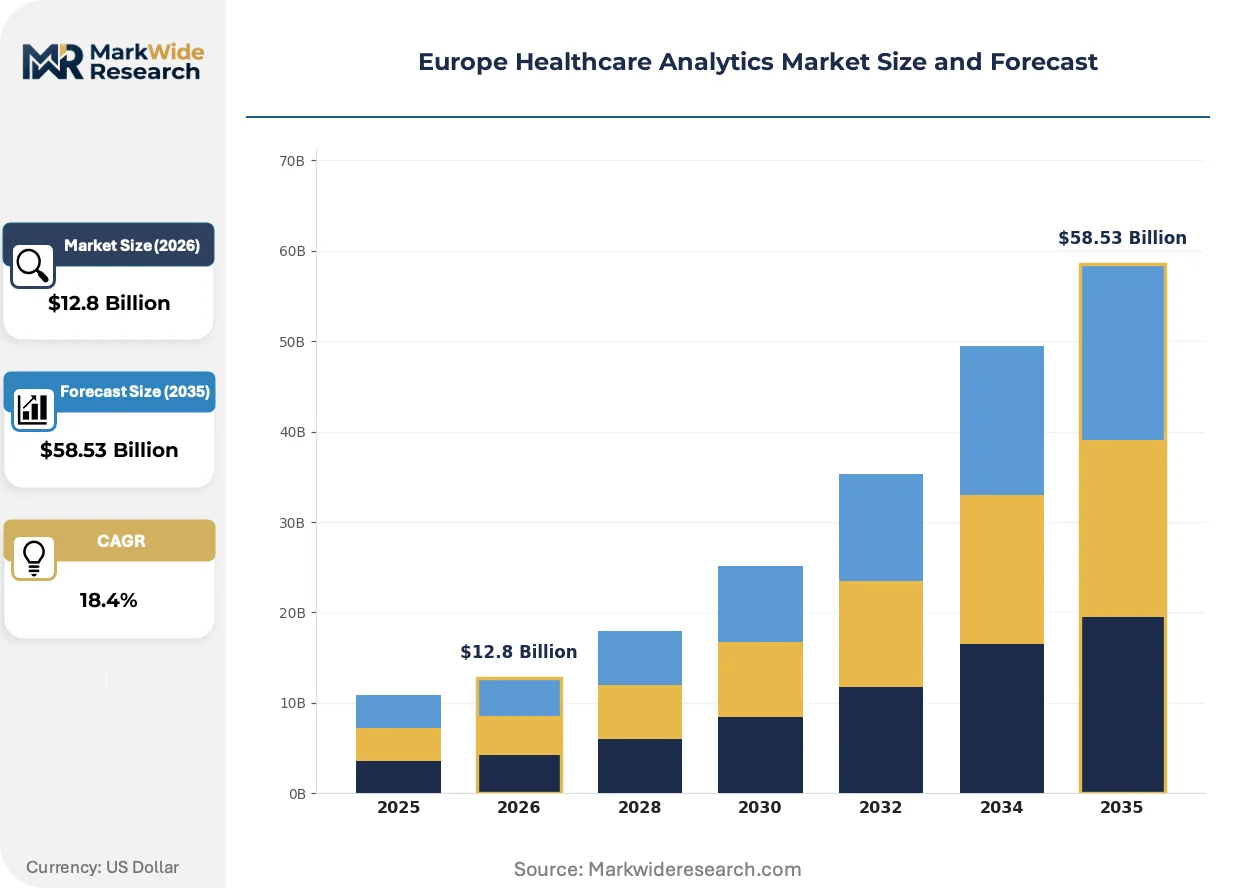
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $58.53 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Descriptive Analytics, Predictive Analytics, Prescriptive Analytics, Risk Analytics End User: Hospitals, Clinics, Research Institutions, Insurance Providers Deployment: On-Premise, Cloud-Based, Hybrid, Software as a Service Application: Patient Management, Regulatory Compliance, Financial Analytics, Operational Efficiency |
| Companies Covered | IBM Corporation, SAS Institute Inc., Optum, Inc., Koninklijke Philips N.V., Merative, Inc., Oracle Corporation, Cerner Corporation, Siemens Healthineers AG, McKesson Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Healthcare Analytics Market Shifts & Advancements
Computational methods for clinical data extraction are converging with regulatory pressure on algorithmic transparency, reshaping how European hospital networks evaluate and deploy decision-support tools.
Natural language processing engines trained on multilingual clinical corpora are digitizing unstructured physician notes into structured diagnostic codes at scale. University hospitals in France and the Netherlands deploy these systems for automated coding and billing reconciliation. This capability is digitizing operational workflows previously requiring manual clinical documentation review.
The EU AI Act's risk-based classification for medical device software imposes conformity assessment obligations on clinical decision support algorithms. Vendors must now maintain technical documentation and post-market surveillance systems comparable to traditional medical devices. High-risk diagnostic applications face the steepest compliance burden, with several German AI radiology startups restructuring quality management systems.
Hospital procurement committees increasingly unbundle analytics licensing from enterprise EHR contracts, creating direct vendor relationships with specialized clinical AI firms. NHS trusts and independent hospital groups in Spain conduct separate competitive tenders for predictive analytics modules. This pattern is most visible in the United Kingdom, where NHS England's digital transformation funding enables discrete purchasing decisions outside monolithic system contracts.
Europe Healthcare Analytics Market Segmentation
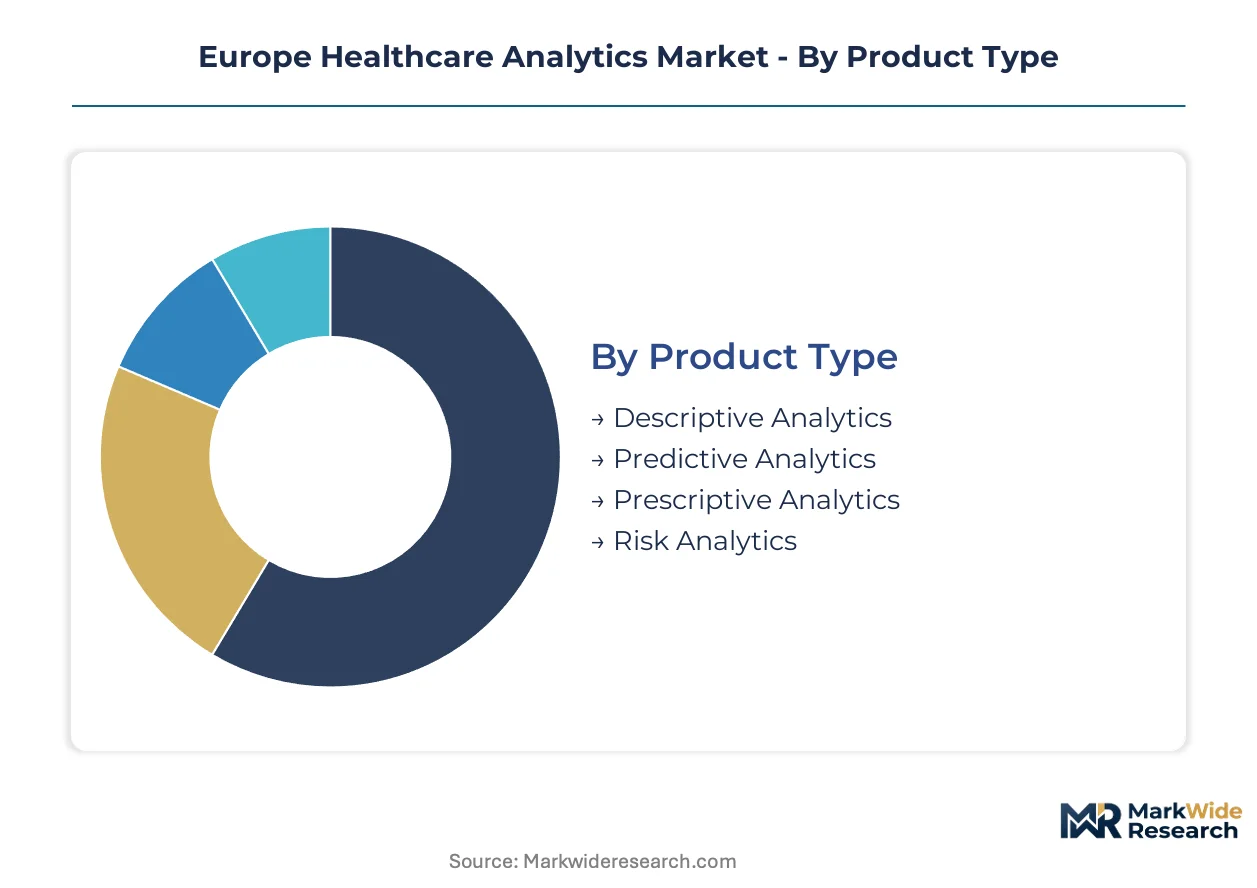
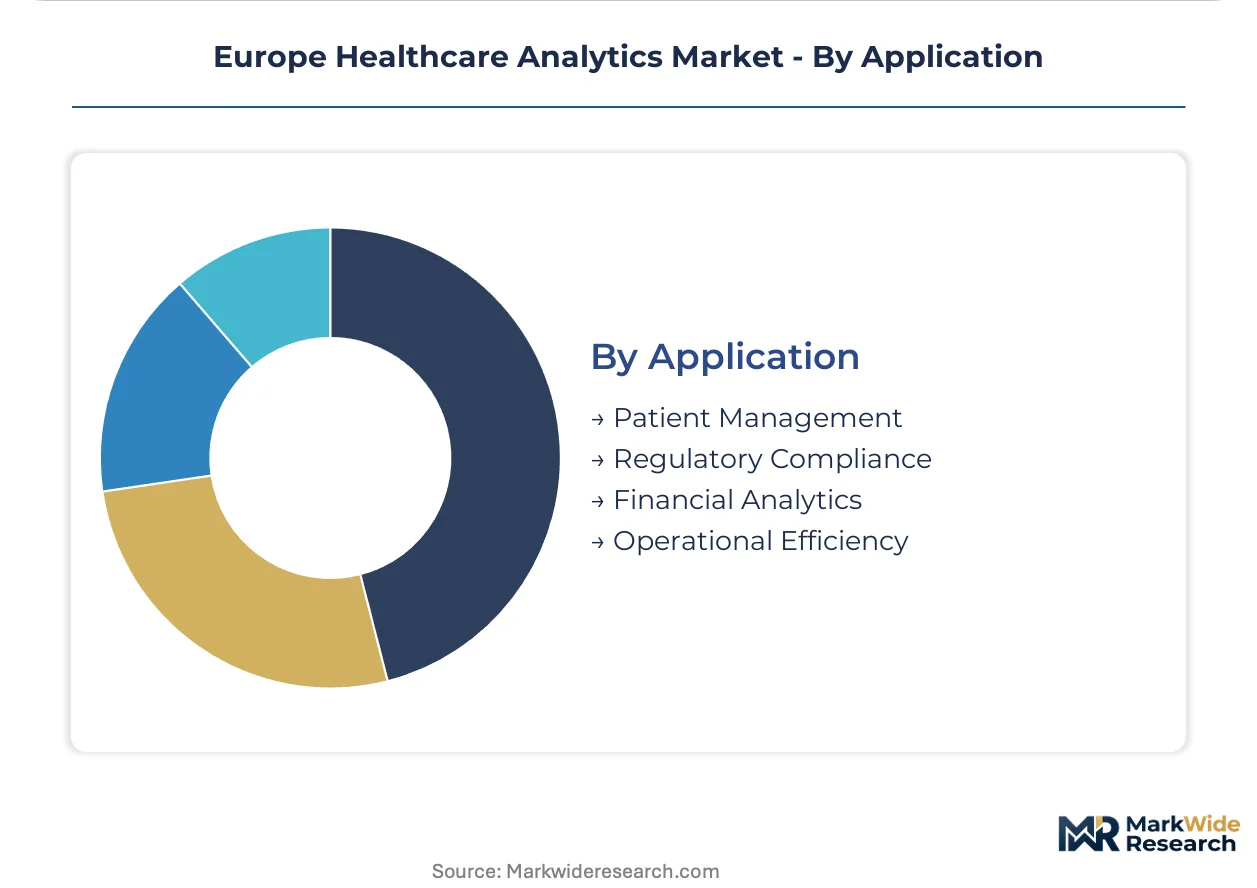
Healthcare analytics in Europe fragments across multiple technical and operational dimensions, each commanding distinct procurement criteria and compliance architectures. Vendors structure product portfolios around these divides to capture discrete budget lines within hospital IT departments and pharmaceutical operations.
Product Type:
Mature descriptive platforms anchor installed bases while prescriptive engines emerge as the capability frontier reshaping clinical decision workflows.
- Descriptive Analytics:Retrospective dashboards aggregate historical patient encounters, billing cycles, and operational metrics into standardized reporting formats. German university hospitals in Berlin and Munich deploy these systems for regulatory reporting to federal health authorities, though procurement committees now demand FHIR-native architectures to reduce integration friction with legacy EHR infrastructure.
- Predictive Analytics:Machine learning models forecast patient deterioration, readmission probability, and disease progression using real-time vital streams and structured diagnostic codes. NHS trusts in England command premium licensing fees for heart failure and COPD cohort risk stratification, with EMA guidelines on real-world evidence tightening validation requirements for algorithmic outputs.
- Prescriptive Analytics:Optimization engines recommend specific therapeutic interventions and resource allocation decisions. French ICU networks integrate these with IoT sensor streams for continuous monitoring.
- Risk Analytics:Quantification engines assess clinical, financial, and operational exposure for insurance underwriting and hospital accreditation.
Descriptive Analytics retains volume leadership across European installations; Prescriptive Analytics holds the steepest expansion curve as EU AI Act compliance matures.
End User:
Procurement sophistication varies sharply across institutional categories, with research institutions demanding open API architectures while hospitals prioritize validated clinical workflows.
- Hospitals:Acute care networks constitute the dominant deployment environment, requiring sub-second query latency for real-time alerting and seamless integration with radiology PACS. Scandinavian hospital networks accelerate migration from legacy on-premise data warehouses to FHIR-compliant cloud architectures.
- Clinics:Ambulatory settings prioritize lightweight, modular implementations with lower total cost of ownership and simplified consent management for smaller patient panels.
- Research Institutions:Academic medical centers in the Netherlands and France demand federated learning capabilities and granular pseudonymization controls for multi-site clinical trials.
- Insurance Providers:Payers deploy population-level risk stratification for premium pricing and care management program targeting.
Hospitals dominate current procurement volume; Research Institutions are expanding most quickly as European Health Data Space regulations clarify cross-border data portability frameworks.
Deployment:
Cloud migration accelerates where GDPR implementations permit, though strict data localization mandates preserve on-premise dominance in select jurisdictions.
- On-Premise:Hardware-resident systems retain preference in German Krankenhaus networks and jurisdictions with explicit data localization requirements. Germany's BDSG implementation drives substantial federal investment in interoperable electronic health record systems that favor controlled infrastructure.
- Cloud-Based:Scalable architectures with elastic compute resources enable predictive model training on large-scale clinical corpora. NHS trusts and Scandinavian networks lead migration from legacy warehouses.
- Hybrid:Split architectures segregate sensitive patient identifiers on-premise while pushing anonymized analytics workloads to cloud environments.
- Software as a Service:Subscription models reduce capital expenditure barriers for mid-tier clinics and independent hospital groups in Spain.
On-Premise systems retain volume leadership in regulated European markets; Cloud-Based deployment gains share fastest as NHS England digital transformation funding enables infrastructure modernization.
Application:
Functional use cases align with distinct stakeholder priorities, from clinical operations to financial sustainability and regulatory adherence.
- Patient Management:Care coordination platforms integrate predictive risk scores with scheduling optimization and discharge planning. Real-time patient monitoring dashboards spread across German and French hospital networks.
- Regulatory Compliance:Automated reporting engines map clinical documentation to EMA pharmacovigilance requirements and national quality registries.
- Financial Analytics:Revenue cycle management and cost accounting systems align billing codes with DRG reimbursement frameworks.
- Operational Efficiency:Resource utilization analytics optimize bed management, staff scheduling, and supply chain procurement across multi-hospital networks.
Patient Management commands the largest installed base; Regulatory Compliance is climbing the fastest as EU AI Act and MDR requirements reshape vendor product roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare analytics vendors cluster around established health technology corridors where hospital density intersects with regulatory clarity. Germany, the United Kingdom, France, the Netherlands, and Sweden constitute the primary deployment theaters, each presenting distinct procurement rhythms and compliance architectures.
Germany
Federal investment in interoperable electronic health record systems drives demand for FHIR-compliant analytics platforms across Berlin and Munich university hospitals. The BDSG implementation imposes granular pseudonymization standards that favor on-premise and hybrid deployment models. Siemens Healthineers AG anchors radiology analytics R&D in Erlangen, while Oracle Corporation competes for multi-hospital network contracts in North Rhine-Westphalia.
United Kingdom
NHS trusts command premium licensing fees for predictive readmission risk models targeting heart failure and COPD cohorts across England. NHS England's digital transformation funding enables discrete procurement of specialized clinical AI modules outside monolithic EHR contracts. London and Manchester hospital networks accelerate migration from legacy data warehouses to cloud-native architectures with sub-second query latency.
France
Hospital networks deploy real-time patient monitoring dashboards integrating IoT sensor streams with ICU workflow optimization. ANSM and CNIL oversight shapes consent management architectures for cross-border analytics platforms processing unstructured clinical notes. Paris and Lyon academic medical centers lead adoption of prescriptive analytics for continuous patient deterioration detection.
Netherlands
Research institutions demand federated learning capabilities and granular pseudonymization controls for multi-site clinical trials spanning Amsterdam and Rotterdam medical centers. GDPR-compliant cloud migration accelerates as hospital networks modernize infrastructure. Dutch procurement committees increasingly unbundle analytics licensing from enterprise EHR contracts, creating direct vendor relationships with specialized AI firms.
Sweden
Scandinavian hospital networks pioneer GDPR-compliant cloud architectures with elastic compute resources for predictive model training on large-scale clinical corpora. Stockholm and Gothenburg health systems favor FHIR-native platforms reducing integration friction with legacy infrastructure. National interoperability mandates support cross-regional analytics deployment while preserving strict data localization protocols.
Europe Healthcare Analytics Market Competitive Landscape
Enterprise technology conglomerates and specialized health informatics firms split the market across distinct capability layers. Consolidation pressure intensifies as hospital procurement committees rewrite algorithmic procurement criteria under EU AI Act conformity assessment obligations. Three archetypes dominate: full-stack cloud providers with health data architectures, medical device manufacturers with embedded analytics, and pure-play clinical AI vendors with disease-specific models. Competitive dynamics center on strategic partnerships with university hospital networks and portfolio diversification into prescriptive analytics engines.
Among enterprise technology conglomerates, IBM Corporation and Oracle Corporation exemplify the cloud-platform archetype, anchoring clinical AI deployments through infrastructure-scale contracts. Siemens Healthineers AG occupies a position bridging medical device manufacturing with radiology analytics specialization. These three entities represent contrasting strategic postures: Watson Health platform integration, aggressive cloud-based enterprise architecture competition, and sustained deep R&D intensity in imaging analytics respectively.
| Leading Market Players |
|---|
| IBM Corporation |
| SAS Institute Inc. |
| Optum, Inc. |
| Koninklijke Philips N.V. |
| Merative, Inc. |
| Oracle Corporation |
| Cerner Corporation |
| Siemens Healthineers AG |
| McKesson Corporation |
| Others |
Supply & Pricing Matrix
EU AI Act conformity assessment obligations create a dual chokepoint that widens pricing spreads between validated clinical AI modules and unvalidated analytics infrastructure while compressing procurement timelines for hospital networks. This regulatory anchor determines both tier differentiation and vendor consolidation patterns across European health data architectures.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for clinical decision support software, separating high-risk diagnostic applications requiring full conformity assessment from lower-risk operational analytics. Premium licensing fees concentrate in predictive readmission risk models for heart failure and COPD cohorts validated under EMA real-world evidence guidelines, while standard-tier descriptive dashboards face cost compression from FHIR-native commoditization. NHS trusts exhibit acute price sensitivity for modular procurement outside monolithic EHR contracts, whereas German university hospitals prioritize compliance-grade premiums over unit economics.
Supply Chain Analysis
Single-source dependency on NVIDIA GPU clusters for machine learning model training dominates supply chain risk for European clinical AI vendors, with hardware concentration in Ireland and the Netherlands feeding cloud compute demand. Software dependencies center on FHIR-compliant data pipelines, multilingual NLP engines trained on clinical corpora, and sub-second query latency architectures. Distribution runs through direct enterprise contracts with hospital procurement committees increasingly unbundled from EHR vendor relationships, supplemented by NHS England digital transformation funding channels and GPO aggregation for mid-tier clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Healthcare Analytics Market sits at an inflection where EU AI Act enforcement is restructuring competitive boundaries faster than vendor compliance capabilities can adapt. This regulatory velocity creates asymmetric opportunity for entities with pre-positioned conformity assessment infrastructure.
For Market Incumbents: Insulate installed base relationships by accelerating vertical integration into FHIR-native data pipeline ownership, reducing third-party dependency for real-time alerting architectures. Prioritize certification investment for high-risk diagnostic classifications before smaller competitors can complete quality management system restructuring, leveraging existing hospital procurement committee access to extend contract renewal timelines.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated Eastern European hospital networks in Poland and Romania where radiology analytics deployment lacks incumbent saturation. Target federated learning capabilities for Dutch and French research institutions demanding granular pseudonymization controls, using open API architectures as the primary go-to-market wedge against legacy platform vendors.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized clinical AI vendors with disease-specific model validation over horizontal infrastructure plays. Long-term viability hinges on regulatory moat depth rather than feature velocity, positioning EU AI Act conformity assessment completion as the critical acquisition screen. Watch EMA guideline evolution on real-world evidence requirements as the signal for which model categories will command sustained premium pricing.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment Completion | Unlocks high-risk diagnostic licensing tiers under EMA oversight frameworks. |
| FHIR-Native Platform Integration | Reduces German hospital network procurement friction against legacy EHR infrastructure. |
| Hospital System Partnership Expansion | Secures direct procurement relationships outside monolithic enterprise contracts in NHS trusts. |
| Specialized Clinical AI Acquisition | Captures disease-specific model validation assets for heart failure and COPD risk stratification. |
| GDPR-Compliant Cloud Architecture Deployment | Enables Scandinavian network migration with sub-second query latency guarantees. |
Research Methodology
Desk research of EMA regulatory filings, NHS procurement databases, and EU health policy directives preceded structured interviews with hospital CIOs, clinical informaticists, biomedical engineers, and GPO contracts managers across Berlin, London, Paris, and Amsterdam. Secondary validation drew from hospital system annual reports, CE marking databases, and digital health funding disclosures. Bottom-up sizing of vendor licensing revenue and top-down reconciliation against national health IT expenditure estimates provided cross-verification.
Assumptions held fixed include EU AI Act enforcement timelines and GDPR implementation consistency across member states, while variables included NHS England digital transformation funding allocation rates and German BDSG pseudonymization technical interpretation evolution. Segmentation modeling spanned product type, deployment architecture, end-user institution category, and application function across the analysis window. CAGR derivation rested on installed base penetration curves for predictive analytics modules and cloud migration velocity in Scandinavian networks.
Sensitivities concentrate around EMA guideline revision on real-world evidence standards and European Health Data Space regulation finalization on cross-border data portability rules. Forecasts reflect these documented assumptions with explicit acknowledgment that regulatory timeline acceleration or delay could materially shift vendor revenue recognition patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
Clinical Data Management Systems (CDMS) Market
Health Data Management
Patient Data Management Software Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
Data Democratization in Healthcare Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
US Population Health Management Market
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
Medical Record Management System Market
Health Data Management
Health Care Quality Management Software Market
Health Data Management
North America Healthcare Analytics Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Healthcare Data Interoperability Market