
 Global Big Data Analytics in Healthcare Market | 2026-2036
Global Big Data Analytics in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Big Data Analytics in Healthcare Market Analysis
Subscription-based cloud financing is reshaping competitive entry in healthcare analytics, allowing mid-sized hospital networks to access enterprise-grade tools without capital expenditure burdens. IBM Corporation leverages its Watson Health architecture to anchor hybrid deployment contracts with major academic medical centers. Oracle Corporation sustains dominance in on-premises data warehousing for health systems navigating strict patient privacy protocols. Microsoft Corporation competes through Azure-based managed services that integrate with existing electronic health record workflows.
Big data analytics in healthcare encompasses the computational processing of multi-terabyte clinical, genomic, operational, and financial datasets using distributed computing frameworks, machine learning algorithms, and real-time stream processing to generate actionable intelligence for patient care optimization and institutional efficiency. The primary commercial purpose centers on converting fragmented health information into predictive models that reduce readmission rates, personalize treatment pathways, and identify population-level disease patterns before acute intervention becomes necessary. Software solutions command the deepest margin pools as health systems prioritize algorithmic tools over hardware refresh cycles. Cloud-based deployment expands fastest among research institutes requiring elastic compute for genomic sequencing workloads. Predictive analytics leads solution demand as pharmaceutical companies seek biomarker discovery acceleration.
The FDA enforces algorithm transparency requirements under its software-as-medical-device framework, compelling vendors to document training data provenance and model drift monitoring protocols. HIPAA security rules and the ONC's information blocking provisions jointly shape procurement specifications, restricting vendors that cannot demonstrate certified interoperability. The EU AI Act classifies clinical decision-support tools as high-risk systems, imposing conformity assessments that filter market access for non-compliant platforms. Stakeholders must monitor evolving liability frameworks that assign accountability when algorithmic recommendations produce adverse patient outcomes.
Market Dynamics
Cloud-native architectures are compressing deployment cycles for health analytics platforms, forcing incumbents to abandon perpetual licensing models in favor of consumption-based pricing that aligns vendor revenue with client utilization patterns.
Growth Catalysts
- FDA 21st Century Cures Act:Mandates for interoperability standards compel health systems to modernize data infrastructure, creating immediate procurement pipelines for analytics vendors with certified FHIR capabilities.
- Pharmaceutical predictive modeling:Biomarker discovery workloads require elastic compute resources that on-premises infrastructure cannot provision, accelerating migration to managed cloud environments for genomic sequencing pipelines.
- United States hospital consolidation:Merged networks achieve scale economies in data lake investments, centralizing purchasing authority for enterprise analytics contracts across multi-state systems.
Market Restraints
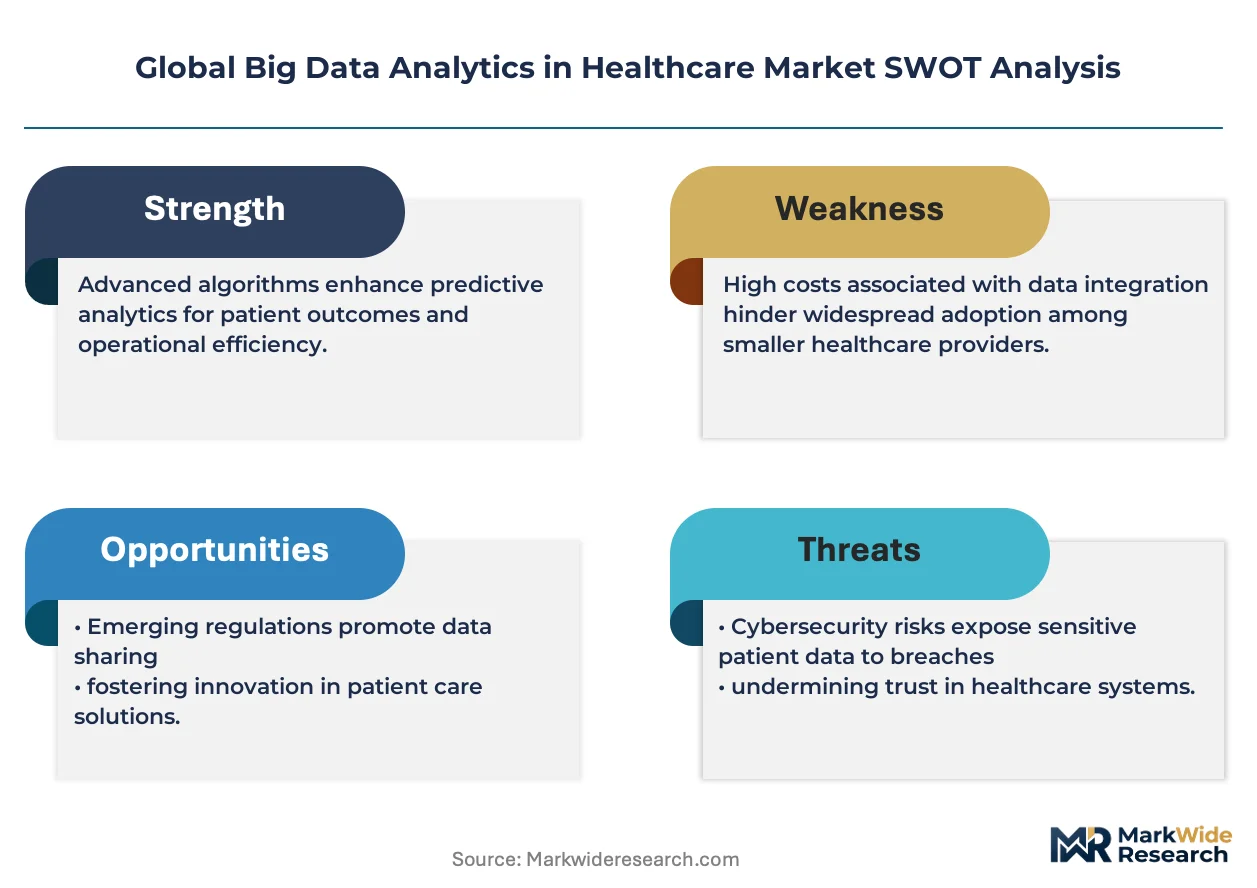
- HIPAA compliance architecture:Technical requirements for encrypted data lineage and access auditing add substantial engineering overhead to product development timelines, favoring established vendors with dedicated compliance teams.
- Specialized talent scarcity:Health informaticists with dual expertise in clinical workflows and distributed systems command premium compensation, constraining vendor expansion velocity.
- On-premises legacy lock-in:Oracle and IBM maintain entrenched positions in data warehousing for institutions with strict patient privacy protocols, creating switching friction for cloud-native competitors.
Strategic Opportunities
- EU AI Act high-risk classification:Conformity assessment requirements for clinical decision-support tools create certification barriers that filter non-compliant platforms, rewarding early investment in documentation infrastructure.
- India's digital health stack:National health identifier systems and open API standards enable population-scale analytics deployment for disease surveillance and resource allocation optimization.
- Federated learning architectures:Privacy-preserving computation across institutional boundaries without data centralization addresses cross-border patient data restrictions while enabling multi-site model training.
Industry Challenges
- Model drift monitoring:Continuous validation requirements for algorithmic performance degradation demand dedicated MLOps infrastructure that many health systems lack internal capability to maintain.
- EHR integration complexity:Proprietary data formats from Epic and Cerner require custom connector development for each deployment, extending implementation timelines and professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Big Data Analytics in Healthcare Market |
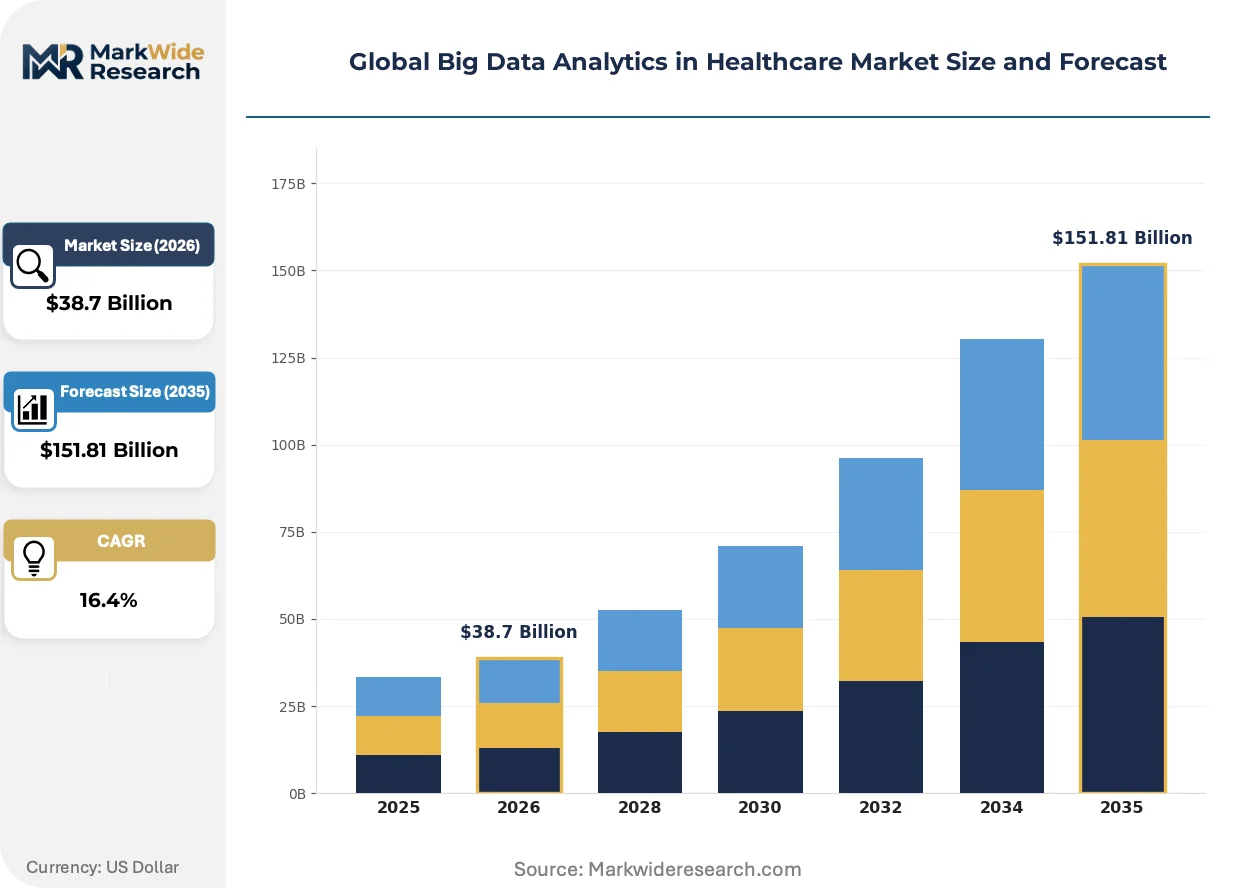
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Services, Hardware, Platforms End User: Hospitals, Clinics, Research Institutes, Pharmaceutical Companies Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Solution: Predictive Analytics, Data Mining, Querying, Visualization |
| Companies Covered | IBM Corporation, Oracle Corporation, Microsoft Corporation, Epic Systems Corporation, Cerner Corporation, Allscripts Healthcare Solutions, GE HealthCare, SAS Institute, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Big Data Analytics in Healthcare Market Emerging Trajectories
Real-time stream processing capabilities are displacing batch-oriented analytics in critical care environments, compressing the latency between data generation and clinical intervention.
Edge computing deployments for ICU monitoring devices is rendering obsolete centralized cloud-only architectures for time-sensitive physiological signal analysis. Hospital networks in Germany and Japan are piloting on-premise inference nodes that process continuous telemetry locally, reducing round-trip latency to sub-100 milliseconds for arrhythmia detection algorithms. This distributed topology is rendering obsolete the assumption that all health analytics must traverse wide-area networks to centralized data centers.
The EU AI Act's high-risk system classification imposes conformity assessments on clinical decision-support tools, forcing vendors to document training data provenance and implement post-market surveillance protocols. European health technology procurement specifications now embed these requirements as mandatory evaluation criteria, filtering market access for platforms lacking certified quality management systems. French and Dutch hospital consortia have established joint pre-certification frameworks to amortize compliance costs across member institutions.
Subscription-based managed services are displacing perpetual software licenses in mid-sized hospital network procurement. United States regional health systems now prioritize operational expenditure models that transfer infrastructure scaling risk to vendors, particularly for genomic analytics workloads with unpredictable compute demands. This financing shift favors Microsoft Azure and Amazon Web Services managed service offerings over traditional on-premises deployment contracts.
Global Big Data Analytics in Healthcare Market Segmentation
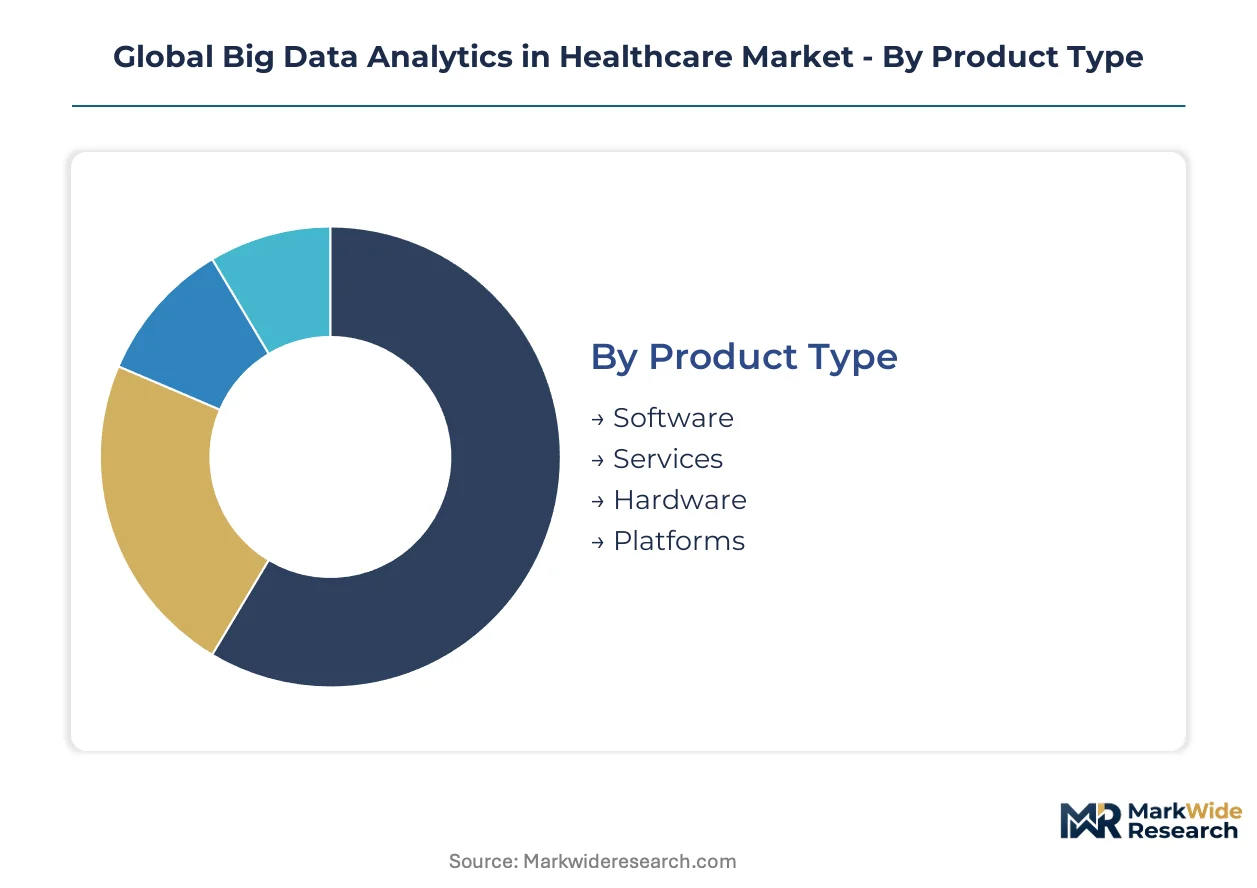
Segmentation in healthcare analytics reflects divergent procurement capabilities across institutional types, with cloud-readiness and regulatory exposure determining technology selection. Mature hospital networks prioritize integrated platforms, while emerging research institutes favor elastic compute services for unpredictable genomic workloads.
Product Type:
Mature segments dominate revenue concentration, though emerging categories capture procurement attention from institutions navigating budget constraints.
- Software:Algorithmic tools for clinical decision support and population health management command premium licensing fees. United States hospital networks prioritize predictive modeling software for readmission reduction, constrained by FDA software-as-medical-device documentation requirements.
- Services:Professional implementation and managed analytics operations transfer infrastructure risk to vendors. Research institutes in Germany and Japan contract specialized services for federated learning deployments that comply with EU AI Act conformity assessments.
- Hardware:Specialized servers and storage arrays for on-premises genomic data lakes.
- Platforms:Integrated development environments combining compute, storage, and analytics tools.
Software handles the majority of throughput; platforms are expanding most quickly on share.
End User:
Customer type segmentation maps directly to procurement authority concentration and data sensitivity protocols.
- Hospitals:Consolidated health systems in the United States centralize enterprise analytics purchasing across multi-state networks. Epic and Cerner EHR integration complexity extends implementation timelines, favoring vendors with established connector libraries.
- Pharmaceutical Companies:Biomarker discovery pipelines require elastic compute for genomic sequencing that on-premises infrastructure cannot provision. FDA 21st Century Cures Act interoperability mandates accelerate cloud migration for real-world evidence generation.
- Clinics:Smaller patient volumes limit dedicated analytics staffing.
- Research Institutes:Academic medical centers pilot edge computing for ICU telemetry analysis.
Hospitals control the largest procurement volume; pharmaceutical companies are gaining share fastest.
Deployment:
Cost tier differentiation separates capital-intensive ownership models from operational expenditure alternatives.
- Cloud-Based:Elastic compute provisioning aligns vendor revenue with actual utilization, eliminating stranded capacity risk. India's national health identifier infrastructure enables population-scale cloud analytics for disease surveillance without legacy system encumbrance.
- Managed Services:Subscription financing transfers scaling responsibility to vendors, particularly attractive for mid-sized United States regional health systems with unpredictable genomic workload demands.
- On-Premises:Strict patient privacy protocols in French and Dutch hospital consortia maintain local data sovereignty requirements.
- Hybrid:Split architectures preserve sensitive records on-premises while pushing anonymized analytics to cloud.
Cloud-based deployment captures the steepest expansion trajectory; on-premises retains entrenched positions in privacy-sensitive environments.
Solution:
Application focus determines margin structure, with forward-looking capabilities commanding premium positioning.
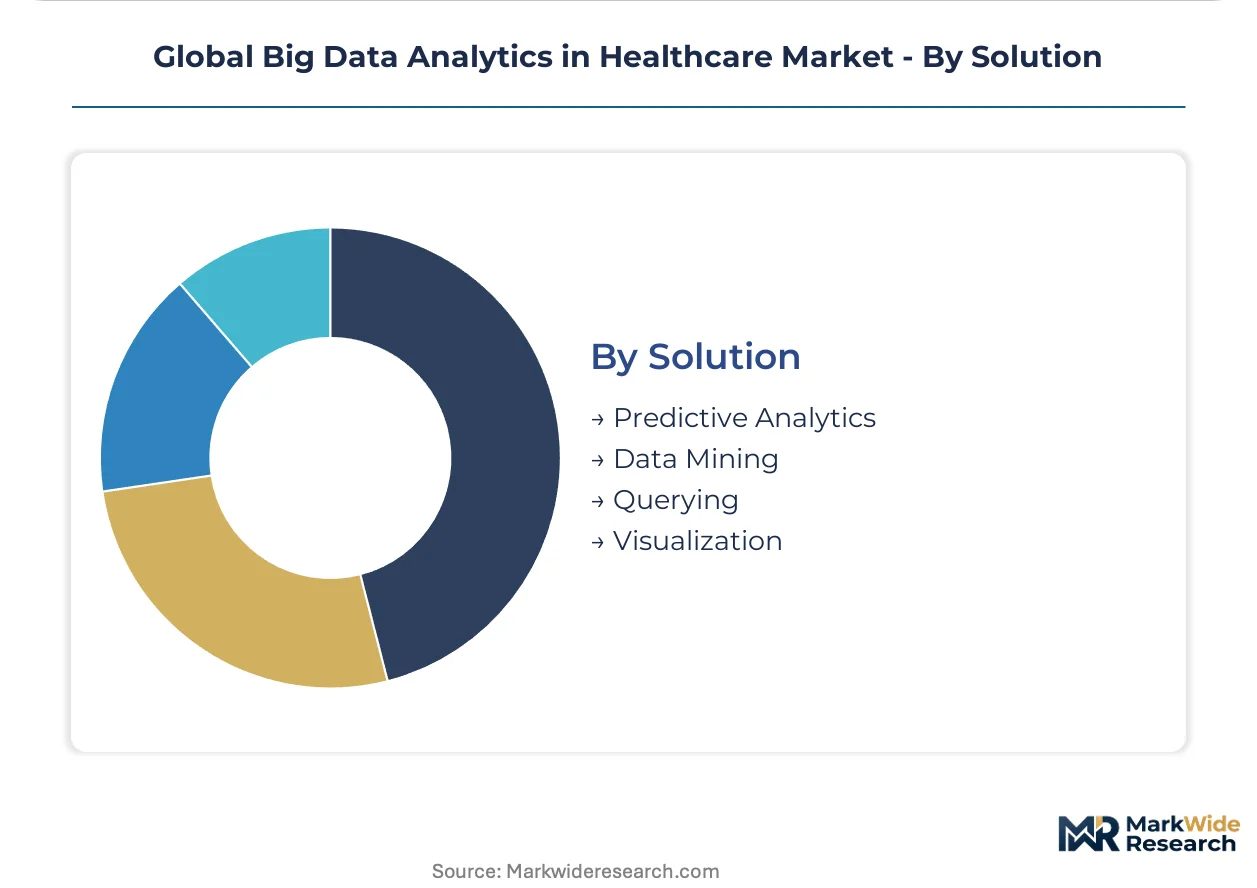
- Predictive Analytics:Machine learning models for disease progression forecasting and treatment response prediction. Pharmaceutical companies accelerate adoption to compress drug discovery timelines, constrained by continuous model drift monitoring requirements.
- Data Mining:Pattern extraction from unstructured clinical notes and imaging metadata. United States academic medical centers deploy mining tools for population-level disease identification before acute intervention becomes necessary.
- Querying:Structured search across federated data repositories.
- Visualization:Dashboard interfaces for operational efficiency monitoring.
Predictive analytics leads commercial value capture; data mining is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's 21st Century Cures Act interoperability mandates have triggered infrastructure modernization across United States hospital networks, while EU AI Act conformity assessments reshape procurement specifications in European health systems.
United States
Hospital consolidation into multi-state networks centralizes enterprise analytics purchasing authority. The FDA enforces algorithm transparency requirements under its software-as-medical-device framework. Academic medical centers in Boston and the Research Triangle pilot edge computing deployments for ICU telemetry analysis.
Germany
French and Dutch hospital consortia establish joint pre-certification frameworks to amortize EU AI Act compliance costs. The country's national health technology regulator mandates post-market surveillance protocols for clinical decision-support tools. Medical technology clusters in Munich and Heidelberg advance federated learning architectures for privacy-preserving computation.
India
National health identifier infrastructure enables population-scale cloud analytics for disease surveillance without legacy system encumbrance. The country's central drugs regulator accelerates digital health stack deployment through open API standards. Bangalore and Hyderabad host specialized services for genomic analytics workloads with unpredictable compute demands.
Japan
Academic medical centers pilot on-premise inference nodes that process continuous telemetry locally for arrhythmia detection algorithms. The country's ministry of economy and trade supports edge computing standardization for time-sensitive physiological signal analysis. Tokyo and Osaka hospital networks reduce round-trip latency to sub-100 milliseconds through distributed topology deployment.
United Kingdom
Research institutes contract specialized services for federated learning deployments that comply with EU AI Act conformity assessments. The country's data protection framework shapes procurement specifications for cross-border patient data restrictions. London and Cambridge medical centers prioritize algorithmic tools for biomarker discovery acceleration.
Global Big Data Analytics in Healthcare Market Vendor Landscape
On the supply side, the industry is consolidating around hybrid cloud-native architectures that displace perpetual licensing models. Established technology conglomerates and specialized health informatics vendors compete through consumption-based pricing aligned with client utilization patterns. Three strategic archetypes dominate: full-stack platform providers, EHR-integrated analytics specialists, and managed cloud service operators. Competitive moves center on M&A for connector library expansion and strategic partnerships for federated learning infrastructure.
Within the full-stack platform tier, IBM Corporation exemplifies hybrid deployment contracting with major academic medical centers, while Oracle Corporation anchors on-premises data warehousing positions for privacy-sensitive institutions. Microsoft Corporation represents the managed cloud service archetype through Azure-based offerings that integrate with existing electronic health record workflows.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Microsoft Corporation |
| Epic Systems Corporation |
| Cerner Corporation |
| Allscripts Healthcare Solutions |
| GE HealthCare |
| SAS Institute |
| Accenture |
| Others |
Supply Flow & Price Mechanics
Undercapacity in specialized GPU clusters across United States cloud regions drives both vendor pricing power and buyer migration toward managed service contracts. Health systems face extended provisioning delays for genomic analytics workloads, forcing procurement committees to accept premium tier commitments or sacrifice processing priority.
Pricing Analysis
Certification level under FDA software-as-medical-device and EU AI Act conformity frameworks creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with FDA-validated algorithms commanding substantial premiums over uncertified alternatives. Cost compression in mid-tier subscriptions is intensifying because hyperscaler managed services commoditize infrastructure layers. Mid-sized regional hospital networks exhibit highest price sensitivity, while pharmaceutical companies demonstrate lowest sensitivity due to timeline pressures in biomarker discovery.
Supply Chain Analysis
Export control restrictions on advanced AI accelerators limit hardware flows into Chinese and Russian markets, reshaping vendor allocation strategies. Supply concentrates in United States, Taiwan, and South Korea for specialized inference chips that power clinical decision-support workloads. Component dependencies include high-bandwidth memory modules, custom ASIC designs, and liquid cooling systems. Single-source vulnerability around TSMC's advanced node production creates concentration risk for vendors dependent on leading-edge silicon. Distribution runs through direct enterprise sales teams for large hospital networks, with channel partners serving mid-market clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source federated learning frameworks threaten proprietary platform margins, forcing incumbents to defend subscription renewal rates through integration depth rather than algorithm exclusivity alone.
For Market Incumbents: Pre-empt substitution by embedding workflow connectors directly into Epic and Cerner EHR architectures, creating switching costs that offset open-source flexibility. Anchor hybrid deployment contracts that preserve on-premises data sovereignty for privacy-sensitive institutions while capturing cloud analytics revenue. Vertical integration into specialized health informatics talent pipelines addresses scarcity constraints that constrain expansion velocity. For New Entrants and Emerging Players: Pursue India's digital health stack as the most penetrable geography, where national health identifier infrastructure eliminates legacy system encumbrance. Target federated learning services for EU hospital consortia navigating cross-border patient data restrictions. Lead with consumption-based pricing that transfers infrastructure scaling risk from mid-sized regional health systems. For Investors and Strategic Acquirers: Capital is best deployed toward platform vendors with certified interoperability libraries and established FDA documentation infrastructure. Long-term viability hinges on regulatory moat depth rather than algorithmic performance alone. Watch for EU AI Act enforcement patterns as the inflection signal for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Algorithm transparency requirements under FDA enforcement create certification barriers that filter non-compliant competitors from hospital procurement pipelines. |
| EU AI Act Conformity Assessment | High-risk system classification forces vendors to document training data provenance, rewarding early investment in quality management infrastructure. |
| Hospital System Partnership | Epic and Cerner integration complexity extends implementation timelines, favoring vendors with established connector libraries and professional services depth. |
| Federated Learning Architecture Deployment | Privacy-preserving computation across institutional boundaries addresses HIPAA cross-border restrictions while enabling multi-site model training. |
| Reimbursement Strategy Development | CMS value-based care metrics align hospital purchasing authority with predictive analytics tools that demonstrate measurable readmission reduction. |
Methodological Framework
Desk research of FDA 510(k) filings, EU MDR submissions, hospital procurement databases, and GPO contracts preceded structured interviews with hospital purchasing committee members, biomedical engineers, health informaticists, and pharmaceutical R&D directors. Primary fieldwork combined with secondary validation through SEC filings of publicly traded vendors, hyperscaler healthcare vertical disclosures, and CMS Medicare data releases. Bottom-up sizing of software licensing revenue and top-down cross-check against cloud infrastructure spending produced convergent estimates.
Assumptions held fixed include FDA software-as-medical-device enforcement trajectory, HIPAA security rule technical requirements, and EU AI Act implementation timelines; variables included hospital consolidation velocity, pharmaceutical R&D budget allocation shifts, and cloud migration pace among mid-sized networks. Segmentation modeling covered deployment model, end-user type, solution category, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical adoption patterns, with genomic sequencing volume and EHR interoperability certification counts as healthcare-specific inputs.
Sensitivities concentrate around FDA algorithm transparency rulemaking, EU AI Act conformity assessment cost trajectories, and hospital network consolidation patterns. Forecasts reflect documented assumptions without contingency for unannounced regulatory shifts. Material changes in FDA software-as-medical-device classification scope or EU AI Act high-risk system definitions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Americas Healthcare Archiving and Ediscovery Market
Health Data Management
Patient Data Management Systems Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
Point-Of-Care Data Management Software Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
US Mobile Health Market
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Healthcare Data Annotation Tools Market
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
United States Healthcare Big Data Analytics Market
Health Data Management
North America Clinical Data Analytics in Healthcare Market
Health Data Management
Patient Data Management Software Market
Health Data Management
Clinical Data Management Systems (CDMS) Market
Health Data Management
Healthcare Archiving and Ediscovery Market