
 Reduced Iron Powder Market | 2026-2036
Reduced Iron Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Reduced Iron Powder Market Analytics
High-purity specification grades above 99.5% iron content is unwinding legacy commodity positioning across the reduced iron powder sector. Höganäs AB leverages its atomization expertise to command premium positioning in automotive powder metallurgy. JFE Steel Corporation anchors Asian supply through integrated steelmaking-to-powder operations in Japan. Rio Tinto Metal Powders differentiates via direct reduced iron feedstock traceability for European OEM qualification programs.
Reduced iron powder consists of sponge or granular metallic iron produced through solid-state reduction of iron oxide, typically exhibiting apparent densities between 2.0 and 3.0 g/cm³ and particle sizes from 45 to 150 microns, serving primarily as feedstock for powder metallurgy compaction, sintered structural components, and chemical reduction processes. Atomized iron powder occupies the largest volume share due to its spherical morphology suiting metal injection molding, while reduced iron powder retains cost advantages in high-volume automotive press-and-sinter applications where purity requirements are moderately specified. Additive manufacturing represents the fastest-expanding application segment, though from a smaller base, as spherical iron powder variants gain qualification for binder jet and laser powder bed fusion systems.
EPA hazardous air pollutant standards under the National Emission Standards for Hazardous Air Pollutants constrain US-based reduction furnace operations, elevating capital requirements for domestic producers. REACH registration and the EU Green Deal carbon border adjustments are reshaping European import sourcing, favoring producers with verified low-carbon reduction pathways. Stakeholders must monitor evolving OEM powder specifications for electric vehicle motor cores and hydrogen economy valve components, as these applications impose stricter chemistry and compressibility thresholds than conventional internal combustion engine parts.
Market Dynamics
Automotive electrification is compressing traditional powder metallurgy demand while simultaneously opening high-purity specifications for electric motor cores and hydrogen infrastructure valves.
Growth Catalysts
- EPA Emissions Standards:Tightening hazardous air pollutant rules under NESHAP are pushing US foundries toward cleaner reduced iron feedstock alternatives for sintered components.
- Electric Vehicle Motor Cores:OEMs specify higher-purity iron powders above 99.5% iron content for laminated stator and rotor stacks requiring superior magnetic properties.
- Hydrogen Economy Valves:Hydrogen fuel cell and storage systems demand specialized powder metallurgy grades with stricter chemistry thresholds for high-pressure containment.
Market Restraints
- Iron Ore Price Volatility:Input cost swings in direct reduced iron feedstock compress margin predictability for powder producers without captive ore supply.
- Production Concentration:Advanced atomization capacity clusters in Germany and Japan, creating geographic supply risk for North American automotive customers.
- Atomized Powder Substitution:Spherical iron powders produced via water and gas atomization are capturing metal injection molding applications from traditional reduced iron grades.
Strategic Opportunities
- India Manufacturing Expansion:BIS certification alignment and automotive PLI scheme incentives create entry pathways for powder metallurgy feedstock suppliers.
- Additive Manufacturing Qualification:Binder jet and laser powder bed fusion systems are opening qualification pathways for spherical iron powder variants in tooling and repair.
- EU Green Deal Carbon Border Adjustments:Verified low-carbon reduction pathways will confer sourcing preference for European OEM qualification programs.
Industry Challenges
- REACH Registration Timelines:ECHA compliance documentation for new powder grades extends product qualification cycles by 18-24 months.
- Legacy Furnace Retrofit Requirements:NESHAP-compliant reduction furnace upgrades demand capital deployment exceeding $15 million per production line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reduced Iron Powder Market |
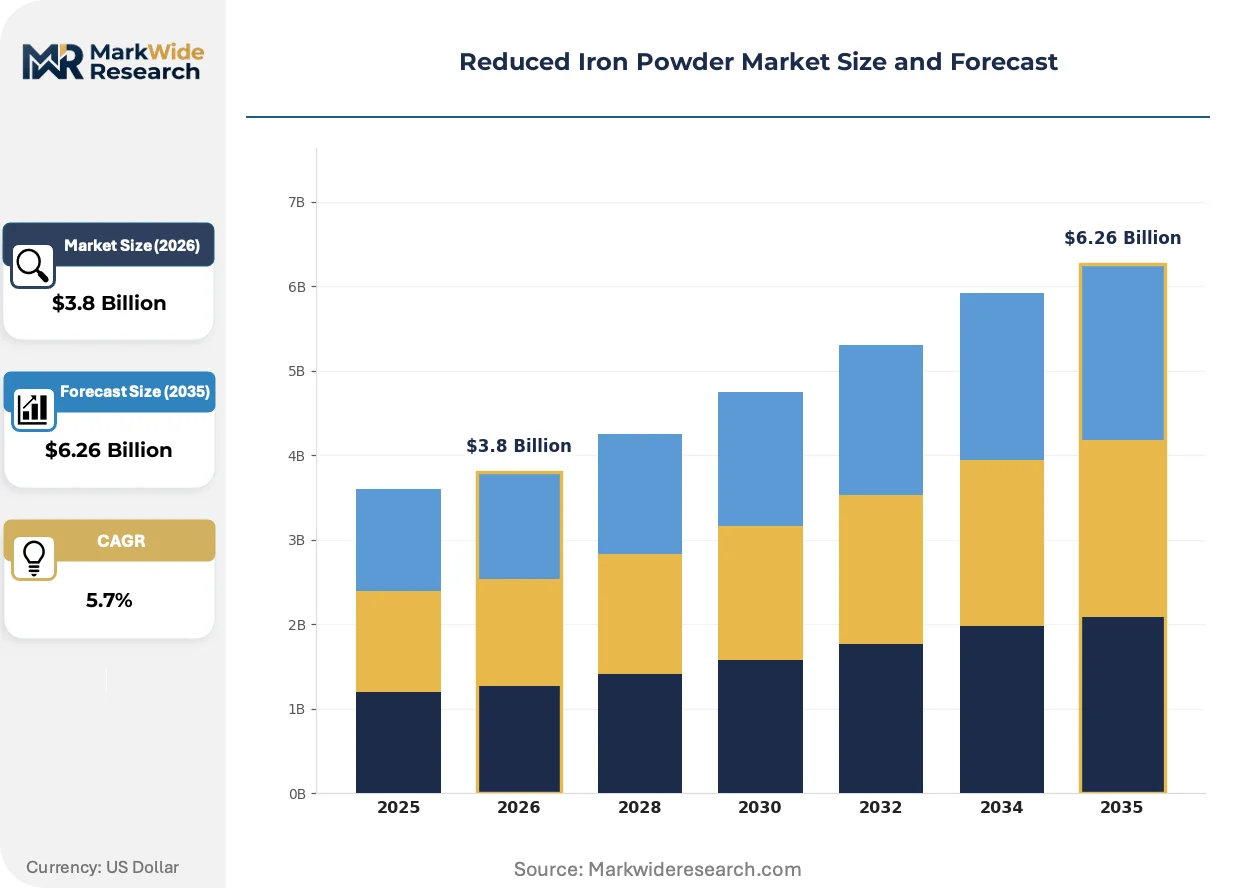
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomized Iron Powder, Electrode Iron Powder, Reduced Iron Powder, Spherical Iron Powder Application: Metal Injection Molding, Additive Manufacturing, Coatings, Magnetic Materials End User: Automotive, Aerospace, Electronics, Pharmaceutical Distribution Channel: Direct Sales, Distributors, Online Retail, Manufacturers |
| Companies Covered | JFE Steel Corporation, Yuean Metal, Höganäs AB, Industrial Metal Powders, American Elements, Rio Tinto Metal Powders, Cathay Industries, Sundram Group, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reduced Iron Powder Market Evolving Landscape
Process innovation and regulatory pressure are converging to reshape powder specifications, production methods, and procurement patterns across the value chain.
Hydrogen-based direct reduction is displacing coal-fired shaft furnace processes in European powder production. Höganäs AB and JFE Steel Corporation are piloting hydrogen plasma reduction for automotive-grade iron powder with sub-1% carbon content. This pathway is displacing legacy coke-based reduction in markets where EU Green Deal carbon accounting shapes supplier selection.
REACH registration and the EU Green Deal carbon border adjustments are tightening feedstock traceability requirements. ECHA substance data documentation now extends to reduction pathway verification for iron powder imports. European automotive OEMs are responding by consolidating supplier lists around producers with verified Scope 3 emissions data.
Automotive procurement departments are compressing supplier qualification cycles while demanding simultaneous chemistry and compressibility guarantees. Tier-1 powder metallurgy component manufacturers are consolidating purchase orders with dual-qualified suppliers holding both atomization and reduction capabilities. This concentration is most visible in Germany, where drivetrain component suppliers serve multiple OEM platforms from single-source feedstock agreements.
Reduced Iron Powder Market Segmentation
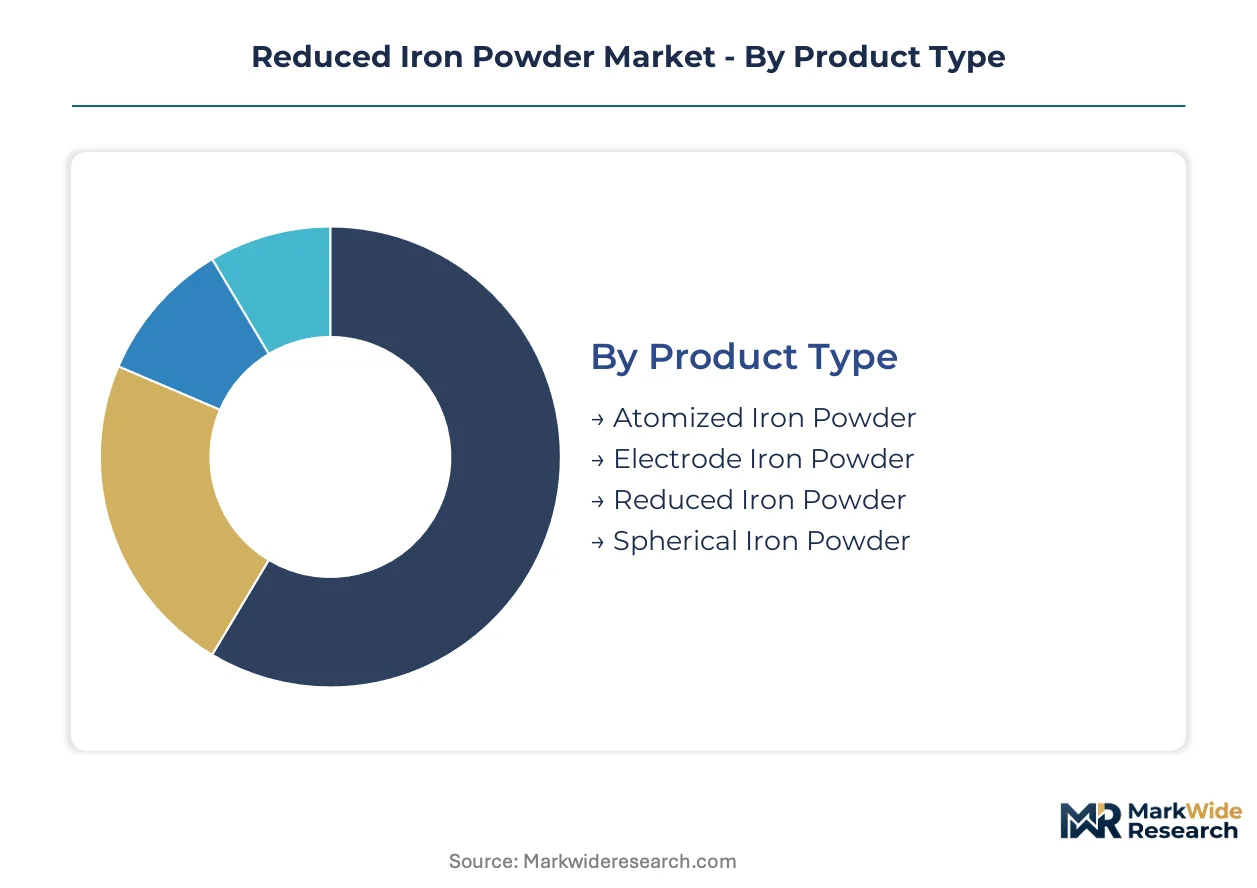
Reduced iron powder specifications fragment across purity grades, particle morphologies, and compressibility thresholds that determine channel economics. Each segment carries distinct qualification requirements and margin structures that reshape supplier-procurement relationships.
Product Type:
Channel-mix varies sharply by production method: atomized grades flow through distributors to metal injection molding houses, while reduced iron powder moves direct to automotive press-and-sinter operations.
- Atomized Iron Powder:Spherical morphology produced via water or gas atomization delivers superior flowability for metal injection molding. Demand concentrates in Japan and Germany where automotive Tier-1 suppliers specify tight particle size distributions for complex geometries.
- Reduced Iron Powder:Irregular sponge morphology from solid-state iron oxide reduction offers cost advantages in high-volume automotive applications. German drivetrain manufacturers dominate procurement, sourcing direct from integrated steel-to-powder producers with verified low-carbon reduction pathways.
- Electrode Iron Powder:High-purity grades for welding electrode coatings flow through specialized distributors serving fabrication shops.
- Spherical Iron Powder:Premium atomized variants for additive manufacturing binder jet systems command direct sales channels with extended qualification protocols.
By volume, Reduced Iron Powder leads. By growth pace, Spherical Iron Powder is ahead.
Application:
Cost tier stratification separates commodity press-and-sinter from premium additive manufacturing applications with 3-5x feedstock cost multiples.
- Metal Injection Molding:Complex near-net-shape components for automotive and firearms rely on atomized powder feedstock with carbon content below 0.1%. Japanese medical device manufacturers are expanding qualification programs for 17-4 PH stainless steel injection molded parts.
- Additive Manufacturing:Binder jet and laser powder bed fusion systems demand spherical iron powder with sub-45 micron cuts and oxygen content below 800 ppm. Aerospace tooling repair applications in Germany are climbing the fastest as OEMs qualify iron-based alternatives to nickel superalloys.
- Coatings:Thermal spray and surface engineering applications utilize blended iron powders through distributor networks serving maintenance operations.
- Magnetic Materials:Soft magnetic composites for electric motor cores require high-purity reduced iron powder with insulation coatings, sourced direct from producers with automotive IATF certification.
Metal Injection Molding captures the largest volume share. Additive Manufacturing shows the steepest expansion trajectory.
End User:
Customer type determines specification stringency: automotive procurement imposes simultaneous chemistry and compressibility guarantees, while pharmaceutical applications demand batch-level traceability.
- Automotive:Powder metallurgy structural components and soft magnetic motor cores represent the dominant demand sink. German OEMs are consolidating supplier lists around dual-qualified producers holding both atomization and reduction capabilities.
- Aerospace:Additive manufacturing tooling and repair applications specify spherical iron powder with full material pedigree documentation. Maintenance repair organizations in France are expanding binder jet capacity for legacy tooling reproduction.
- Electronics:Inductor cores and electromagnetic shielding utilize specialized iron powder grades through electronics distributors.
- Pharmaceutical:High-purity reduced iron powder for nutritional supplements and API synthesis requires GMP-compliant production with batch documentation.
Automotive commands the largest volume position. Aerospace is expanding most quickly.
Distribution Channel:
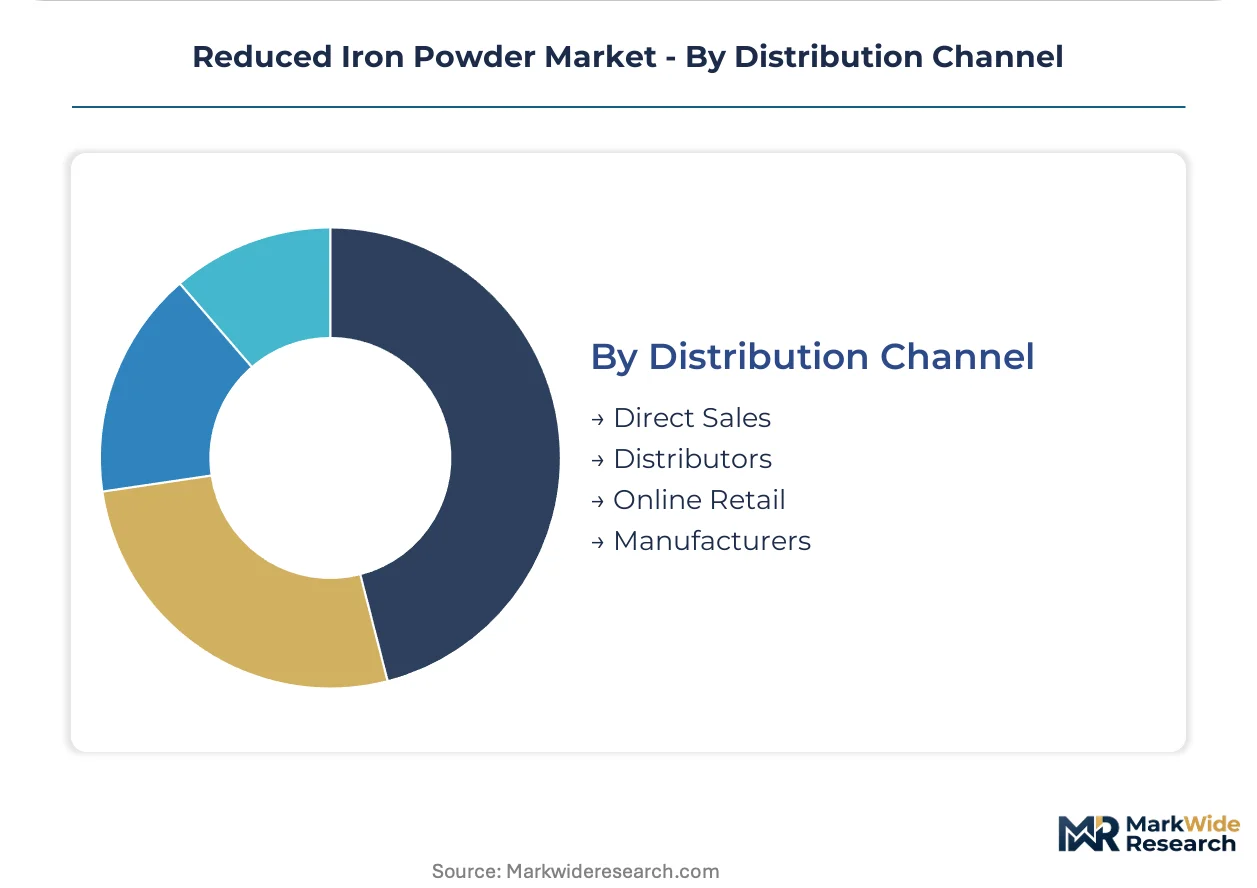
Supply concentration in Germany and Japan shapes channel configuration: direct sales dominate where producers hold captive automotive relationships, while distributors fill geographic and specification gaps.
- Direct Sales:Long-term supply agreements between powder producers and Tier-1 automotive component manufacturers lock in volume commitments with price adjustment clauses tied to iron ore indices. Höganäs AB and JFE Steel Corporation anchor this channel with integrated production-to-customer logistics.
- Distributors:Regional stocking distributors serve job shops and smaller metal injection molding houses with blended inventories and technical support. Indian distributors are expanding warehousing capacity near Pune and Chennai automotive clusters under PLI scheme incentives.
- Online Retail:Small-lot specialty grades for research and prototyping flow through e-commerce platforms with limited technical service.
- Manufacturers:Captive powder production by integrated automotive suppliers remains minimal due to atomization capital intensity exceeding $50 million per line.
Direct Sales handles the largest volume flows. Distributors are gaining share fastest in emerging manufacturing regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced atomization and reduction capacity clusters in Germany and Japan, creating geographic supply risk for automotive customers in North America and emerging Asian manufacturing regions. Regulatory divergence between EPA emissions standards in the United States and EU Green Deal carbon border adjustments is reshaping procurement patterns across continental markets.
Germany
Automotive powder metallurgy for drivetrain components and electric motor cores drives demand concentration in Baden-Württemberg and Bavaria. REACH registration and ECHA substance data documentation requirements extend qualification cycles for imported feedstock. Höganäs AB operates advanced production facilities serving continental European OEM qualification programs with verified low-carbon reduction pathways.
Japan
Integrated steelmaking-to-powder operations anchor supply security for domestic automotive and electronics manufacturers. METI industrial policy supports hydrogen-based direct reduction pilot programs for sub-1% carbon content grades. JFE Steel Corporation maintains captive production in Nagoya and Chiba prefectures, supplying Tier-1 component manufacturers with dual atomization and reduction capabilities.
United States
EPA National Emission Standards for Hazardous Air Pollutants constrain domestic reduction furnace operations, elevating capital requirements for NESHAP-compliant upgrades. Automotive OEMs in Michigan and Ohio specify higher-purity iron powders above 99.5% iron content for laminated motor stacks. Foundries are consolidating supplier relationships around dual-qualified producers with integrated logistics.
India
BIS certification alignment and automotive PLI scheme incentives create entry pathways for powder metallurgy feedstock suppliers. CDSCO and the central bank's industrial credit policies support capital deployment in Pune and Chennai automotive clusters. Regional distributors are expanding warehousing capacity to serve expanding press-and-sinter operations under government manufacturing incentives.
China
GB standards and MIIT industrial guidelines shape domestic powder specifications for metal injection molding and additive manufacturing applications. Dual carbon goals and MEE emissions enforcement are pressuring legacy coal-fired reduction capacity in Shandong and Jiangsu provinces. Domestic producers are retrofitting shaft furnaces to meet tightening environmental compliance thresholds.
Reduced Iron Powder Market Competitive Landscape
Concentration sits with integrated steel-to-powder producers and specialized atomization houses that command automotive qualification relationships. The vendor base spans three tiers: multinational integrated producers with captive ore supply, regional specialists with single-process capabilities, and emerging Asian fabricators serving cost-sensitive metal injection molding applications. Dominant competitive moves include backward integration into direct reduced iron feedstock and technology licensing for hydrogen-based reduction pathways.
Among integrated producers, Höganäs AB and JFE Steel Corporation exemplify the dual-capability archetype spanning atomization and reduction. Rio Tinto Metal Powders represents feedstock-traceable positioning for European OEM carbon accounting requirements. These three companies anchor the premium tier where automotive procurement departments consolidate purchase orders around verified Scope 3 emissions documentation and simultaneous chemistry and compressibility guarantees.
| Leading Market Players |
|---|
| JFE Steel Corporation |
| Yuean Metal |
| Höganäs AB |
| Industrial Metal Powders |
| American Elements |
| Rio Tinto Metal Powders |
| Cathay Industries |
| Sundram Group |
| BASF |
| Others |
Value Network & Pricing Analysis
REACH registration and ECHA substance data documentation gates both supplier qualification and price differentiation simultaneously, forcing automotive procurement departments to consolidate purchase orders around dual-qualified producers with verified Scope 3 emissions data and simultaneous chemistry guarantees.
Pricing Analysis
REACH dictates the pricing tier structure across the reduced iron powder sector, separating automotive-grade specifications above 99.5% iron content from commodity press-and-sinter grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification investment, with IATF-automotive-qualified producers commanding 15-25% premiums over distributor-sourced alternatives. Pricing pressure stems from iron ore feedstock volatility compressing margin predictability for non-integrated producers. Job shops and smaller metal injection molding houses exhibit highest price sensitivity, while German OEM procurement departments prioritize compressibility guarantees over unit cost.
Supply Chain Analysis
Advanced atomization capacity concentration in Germany and Japan underwrites supply security risks for North American automotive customers. Production draws from direct reduced iron feedstock, hydrogen reduction pathways, and legacy coke-based shaft furnace output. Single-source vulnerability intensifies as Tier-1 component manufacturers consolidate around Höganäs AB and JFE Steel Corporation for dual atomization-reduction capabilities. Distribution runs through direct sales agreements with price adjustment clauses tied to iron ore indices, supplemented by regional distributors serving geographic gaps in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reduced iron powder sits in early-cycle expansion as automotive electrification and hydrogen infrastructure deployment accelerate qualification demand for high-purity grades above legacy internal combustion engine specifications.
For Market Incumbents: Consolidate supplier relationships by locking in long-term offtake agreements with German and Japanese automotive OEMs before atomized powder substitution captures additional metal injection molding share. Backward integration into direct reduced iron feedstock secures margin predictability against iron ore volatility. NESHAP-compliant furnace retrofit requirements exceeding $15 million per line will strain regional specialists without captive capital access. For New Entrants and Emerging Players: Additive manufacturing qualification services represent a service-layer gap where incumbents under-serve, particularly for aerospace tooling repair applications requiring sub-45 micron spherical powder with full material pedigree documentation. Target Indian automotive clusters near Pune and Chennai where BIS certification alignment and PLI scheme incentives reduce entry barriers against established European suppliers. Partner with regional distributors to bypass direct sales channel concentration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrogen-based direct reduction pilot programs as EU Green Deal carbon accounting reshapes supplier selection criteria. Five-to-ten year viability favors integrated steel-to-powder producers with verified low-carbon reduction pathways and dual atomization capabilities. Watch for consolidation signals as NESHAP compliance costs force exit of single-process regional operators in the United States.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Based Direct Reduction Scale-Up | EU Green Deal carbon border adjustments will privilege producers with sub-1% carbon content pathways. |
| Dual Atomization-Reduction Capacity Addition | German automotive OEMs are consolidating supplier lists around producers holding both capabilities. |
| REACH Registration Acceleration | ECHA compliance documentation extends product qualification cycles by 18-24 months for new entrants. |
| India Manufacturing Footprint Expansion | BIS certification alignment and automotive PLI scheme incentives create entry pathways near Pune clusters. |
| Additive Manufacturing Qualification Investment | Binder jet and laser powder bed fusion systems open premium pricing for spherical iron powder variants. |
Research Methodology
A standing panel of powder metallurgy procurement directors, automotive Tier-1 supplier engineers, foundry operations managers, and ECHA regulatory consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA NESHAP filings, ECHA substance registration databases, EU Green Deal carbon accounting guidelines, and automotive OEM supplier qualification documentation. Bottom-up segment sizing triangulated against top-down iron ore consumption models and powder metallurgy component production estimates.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions spanning production method purity grades, particle morphology specifications, automotive versus aerospace end-use applications, and regional regulatory cluster variations. CAGRs were derived from fitted growth curves incorporating electric vehicle motor core adoption rates and hydrogen infrastructure deployment timelines as industry-specific forecast inputs.
Underlying assumptions cover REACH registration timeline stability and NESHAP enforcement continuity, with deviation risk concentrated in iron ore price volatility and atomized powder substitution acceleration. Practitioners should keep alternative scenarios live as EU carbon border adjustment implementation schedules and EPA emissions standard tightening evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
Magnetic Materials Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Magnetic Filter Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
North America Samarium Cobalt Magnets Market
Magnetic Materials
Nanocrystalline Soft Magnetic Material Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Global Electrical Steel Sheet Market