
 Magnet Buffer Market | 2026-2036
Magnet Buffer Market Size, Share, and Industry Trends Forecast 2026-2036
Magnet Buffer Market Insights
REACH compliance is consolidating the cost-of-entry calculus for magnet buffer suppliers seeking European market access. SMC leverages its pneumatic automation heritage to anchor premium positioning in material handling segments. Festo competes through deep R&D intensity in polyurethane formulation for robotics integration buffers. Parker Hannifin sustains manufacturing scale advantages across North American automotive assembly corridors.
A magnet buffer is an elastomeric or metallic damping device employing permanent magnetic attachment to absorb kinetic energy and prevent mechanical collision damage in automated systems, typically specified by Shore hardness ratings between 40A and 90A and operating temperature ranges from -20°C to 80°C. Its primary industrial purpose is protecting precision equipment and reducing noise in high-cycle automation environments. Steel-based buffers dominate aerospace manufacturing applications where impact resistance thresholds exceed 500 J, while polyurethane formulations represent the fastest-expanding category in robotics integration due to superior rebound resilience. Composite magnet buffers command the strongest margin pools in semiconductor-adjacent cleanroom installations where outgassing specifications restrict conventional elastomer options.
The EPA oversees volatile organic compound emissions from rubber curing processes affecting domestic magnet buffer production, while ECHA enforces SVHC restrictions under REACH that limit phthalate plasticizer content in European-bound products. OSHA machine guarding standards in the United States and Japan's METI industrial safety directives both mandate energy-absorbing stops on automated material handling equipment, directly expanding replacement demand. Stakeholders must monitor evolving PFAS restrictions across multiple jurisdictions, as fluorinated polymer coatings currently used in high-temperature magnet buffer variants face prospective phase-out timelines that could force rapid material reformulation investments.
Market Dynamics
REACH compliance and the EU F-Gas Regulation are consolidating supplier bases by elevating material certification thresholds, forcing magnet buffer manufacturers to absorb reformulation costs or exit European automotive corridors entirely.
Growth Catalysts
- Robotics precision demands:German, Japanese, and American automotive manufacturers are scaling magnet buffer procurement for end-effector collision protection in high-cycle assembly environments.
- OSHA machine guarding mandates:United States federal safety standards require energy-absorbing stops on automated material handling equipment, expanding replacement demand across warehouse and distribution facilities.
- Polyurethane formulation advances:Superior rebound resilience in next-generation elastomer compounds is displacing conventional rubber buffers in cleanroom-adjacent semiconductor manufacturing.
Market Restraints
- Phthalate plasticizer restrictions:ECHA SVHC limitations under REACH constrain formulation flexibility for European-bound products, forcing costly alternative plasticizer sourcing.
- Steel supply concentration:Aerospace-grade magnet buffer production depends on specialized alloy suppliers concentrated in North American and East Asian metallurgical corridors.
- PFAS coating phase-out timelines:Prospective restrictions on fluorinated polymer coatings threaten high-temperature buffer variants with forced material transitions.
Strategic Opportunities
- Cleanroom semiconductor installations:Composite magnet buffers with ultra-low outgassing specifications command premium positioning in wafer fabrication facilities.
- EU Green Deal alignment:Bio-based polyurethane feedstocks qualify for preferential procurement scoring in European public-sector automation tenders.
- Digital twin integration:Sensor-embedded smart buffers enabling predictive maintenance are converging with industrial IoT platforms in Japanese automotive plants.
Industry Challenges
- Rebound resilience calibration:Robotics integrators demand precise Shore hardness matching across temperature ranges, requiring specialized compound engineering talent.
- Multi-jurisdiction certification timelines:Simultaneous EPA VOC compliance, REACH SVHC documentation, and METI safety filings extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnet Buffer Market |
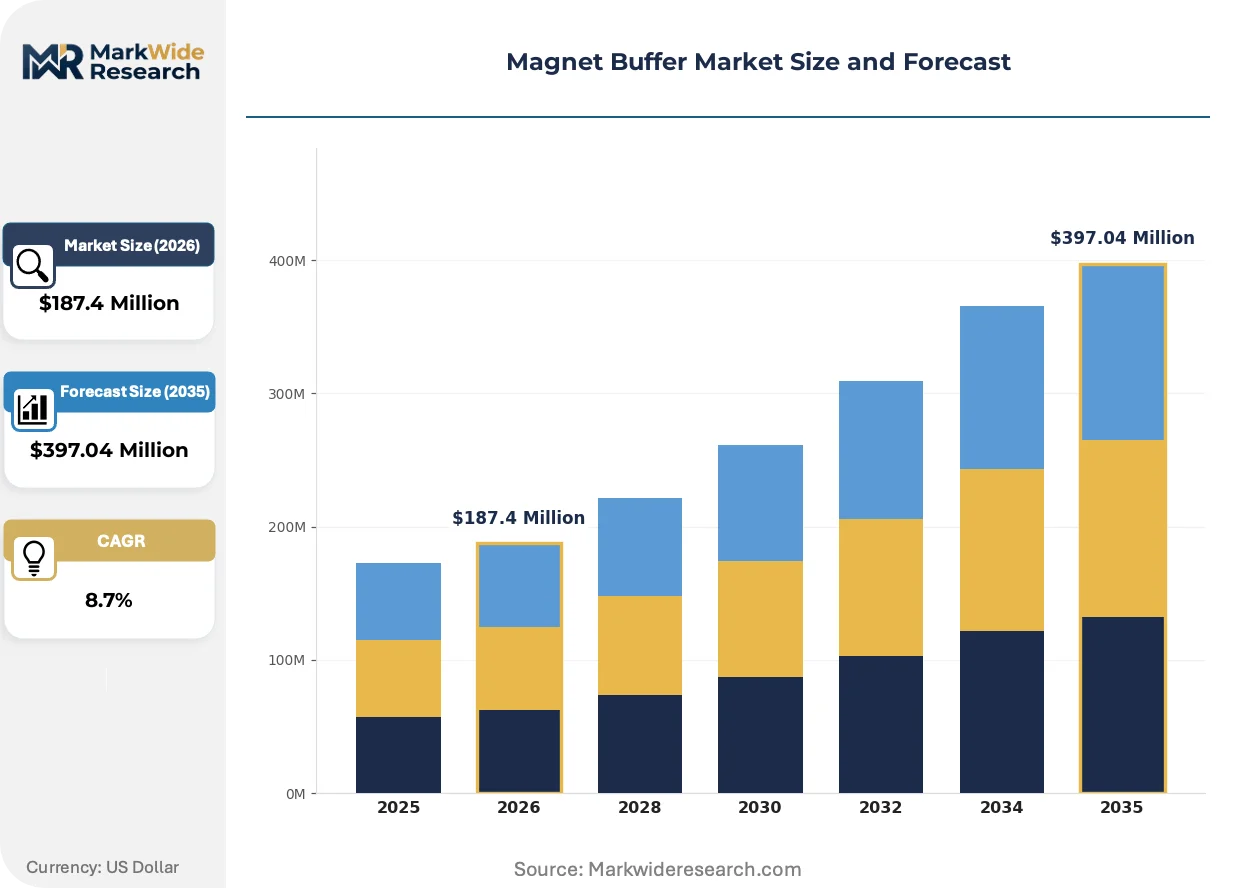
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber-based, Steel-based, Polyurethane, Neoprene, Composite Application: Material Handling, Automotive Assembly, Robotics Integration, Packaging Machinery, Aerospace Manufacturing End User Industry: Manufacturing Plants, Logistics Providers, Robotics Manufacturers, Heavy Equipment Fabricators, Aerospace Assemblers Installation Type: Surface Mount, Recessed Mount, Magnetic Mount, Adhesive Mount, Bolted Mount |
| Companies Covered | SMC, CKD Corporation, Miculek, Festo, IMI Precision Engineering, Parker Hannifin, Emerson, Airtac International Group, Bosch Rexroth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnet Buffer Market Trends and Innovations
Magnet buffer technology is pivoting toward intelligent damping systems and sustainable material platforms, with regulatory chemistry constraints and precision automation requirements driving concurrent innovation threads.
Magneto-rheological fluid integration is unifying adaptive damping control with permanent magnetic attachment mechanisms. German automotive tier-1 suppliers are piloting these systems in battery assembly lines where impact profiles vary by cell format. This convergence is compressing the performance gap between fixed elastomer buffers and active electromechanical alternatives.
ECHA enforcement of SVHC candidate list expansions is restricting phthalate plasticizer content in European-bound elastomer formulations. Compounders are accelerating bio-based polyol substitution programs to preempt compliance disruptions. Polyurethane buffer suppliers serving Bavarian automotive clusters face the most acute formulation timeline pressure.
Buyer consolidation among robotics OEMs is compressing supplier qualification cycles and unbundling after-sales service contracts. Japanese and American integrators now specify buffer performance warranties tied to cumulative cycle counts rather than calendar periods. This shift is most visible in Michigan and Guangdong Province assembly corridor procurement frameworks.
Magnet Buffer Market Segmentation
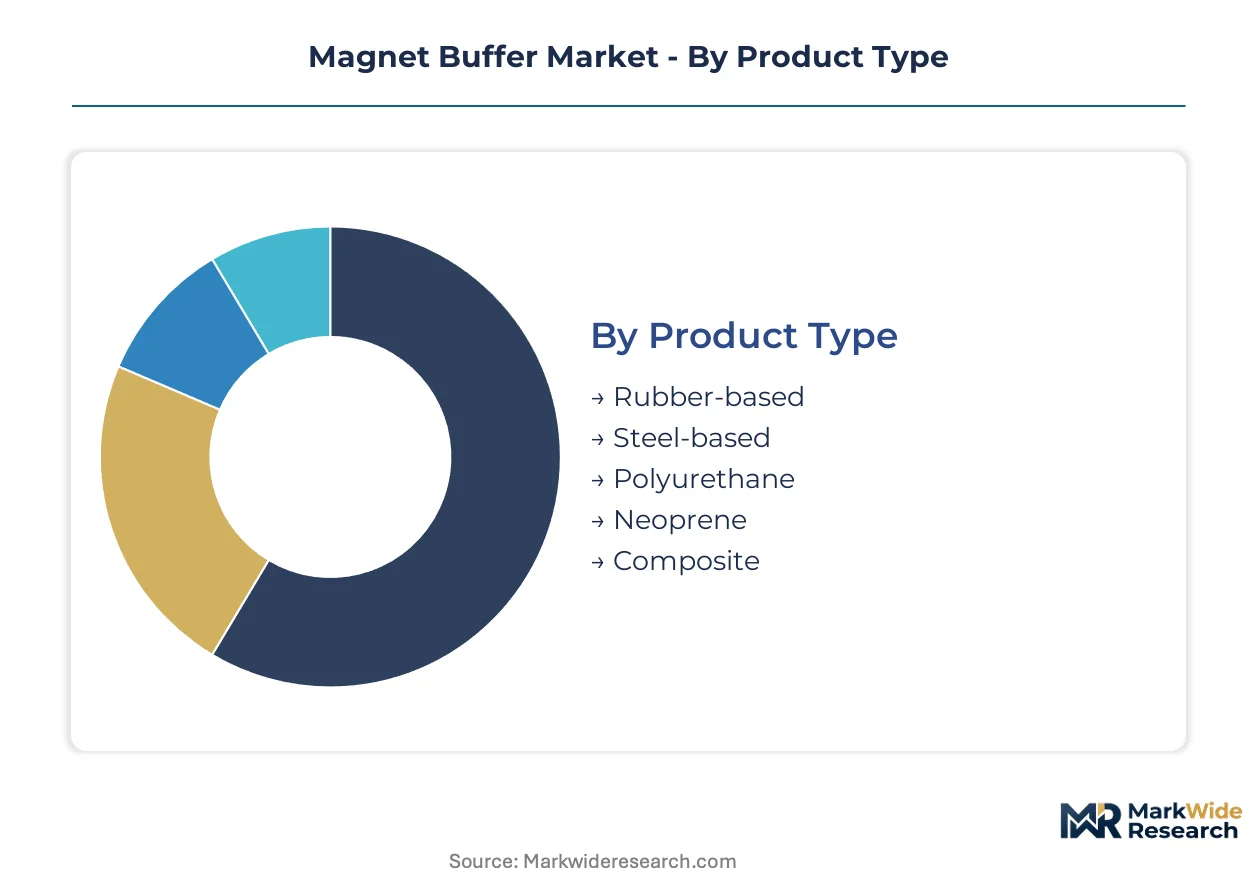
Magnet buffer procurement decisions hinge on impact energy absorption requirements, chemical compatibility constraints, and mounting geometry limitations. Buyers across automotive, robotics, and aerospace verticals specify buffers against Shore hardness ranges, temperature ratings, and outgassing thresholds rather than brand preference alone.
Product Type:
Cost tier differentiation separates commodity elastomer formulations from certified aerospace-grade compounds.
- Polyurethane:Engineered with superior rebound resilience between 40A and 90A Shore hardness, this elastomer dominates robotics integration in German and Japanese automotive plants where cycle counts exceed 10 million operations. Bavarian battery assembly lines specify polyurethane buffers for adaptive damping in cell-format handling systems.
- Steel-based: Aerospace-grade alloy construction absorbs impact energies exceeding 500 J without permanent deformation. Demand concentrates in North American and East Asian metallurgical corridors where specialized heat-treatment capabilities reside.
- Rubber-based: Conventional nitrile and SBR compounds serve cost-sensitive material handling in warehouse distribution facilities across Michigan and Guangdong Province.
- Neoprene: Chloroprene polymer buffers resist ozone degradation in outdoor port machinery and marine logistics applications.
- Composite: Multi-layer elastomer-metal laminates command premium positioning in semiconductor cleanrooms where outgassing specifications restrict conventional options.
Volume sits with rubber-based formulations; growth tilts toward polyurethane.
Application:
Application selection tracks automation intensity and precision tolerance thresholds.
- Robotics Integration:End-effector collision protection in high-cycle environments demands precise Shore hardness matching across -20°C to 80°C operating windows. Japanese automotive OEMs now specify cumulative cycle-count warranties rather than calendar periods.
- Automotive Assembly: Paint-shop-compatible buffers must survive phosphate bath exposure and E-coat oven cycles. EPA VOC compliance and ECHA SVHC documentation extend qualification timelines for European-bound supply.
- Material Handling: OSHA machine guarding mandates drive replacement demand across warehouse and distribution corridors in the United States.
- Packaging Machinery: High-speed carton handling requires noise reduction below 75 dB in food-grade environments.
- Aerospace Manufacturing: Impact resistance certification to MIL-STD-810 governs fastener installation and composite layup protection.
Procurement concentrates in automotive assembly; steepest expansion trajectory appears in robotics integration.
End User Industry:
Customer type determines specification authority and contract structure.
- Robotics Manufacturers:German, Japanese, and American integrators consolidate supplier bases and compress qualification cycles. They specify buffer performance against ISO 9283 repeatability standards.
- Manufacturing Plants: Tier-1 automotive suppliers in Bavaria and Michigan operate captive maintenance inventories with scheduled replacement protocols.
- Logistics Providers: E-commerce fulfillment centers prioritize rapid-swap magnetic mounting to minimize conveyor downtime.
- Heavy Equipment Fabricators: Construction and mining OEMs specify steel-reinforced buffers for extreme impact environments.
- Aerospace Assemblers: Cleanroom-adjacent operations demand lot-traceable compounds with full material certification chains.
Revenue gravity centers on robotics manufacturers; margin pools concentrate with aerospace assemblers.
Installation Type:
Mounting geometry selection reflects maintenance access constraints and substrate compatibility.
- Magnetic Mount:Permanent rare-earth attachment enables tool-free repositioning on ferrous surfaces. This configuration dominates robotics cell reconfiguration in Japanese automotive plants.
- Surface Mount: Flat-base adhesion suits conveyor systems and fixed automation lines where vibration damping is secondary to impact protection.
- Recessed Mount: Flush installation protects buffer faces from lateral shear in high-traffic material handling corridors.
- Adhesive Mount: Structural bonding agents secure buffers to non-ferrous composites in aerospace fixture applications.
- Bolted Mount: Through-hole mechanical fastening survives washdown cycles in food and pharmaceutical processing equipment.
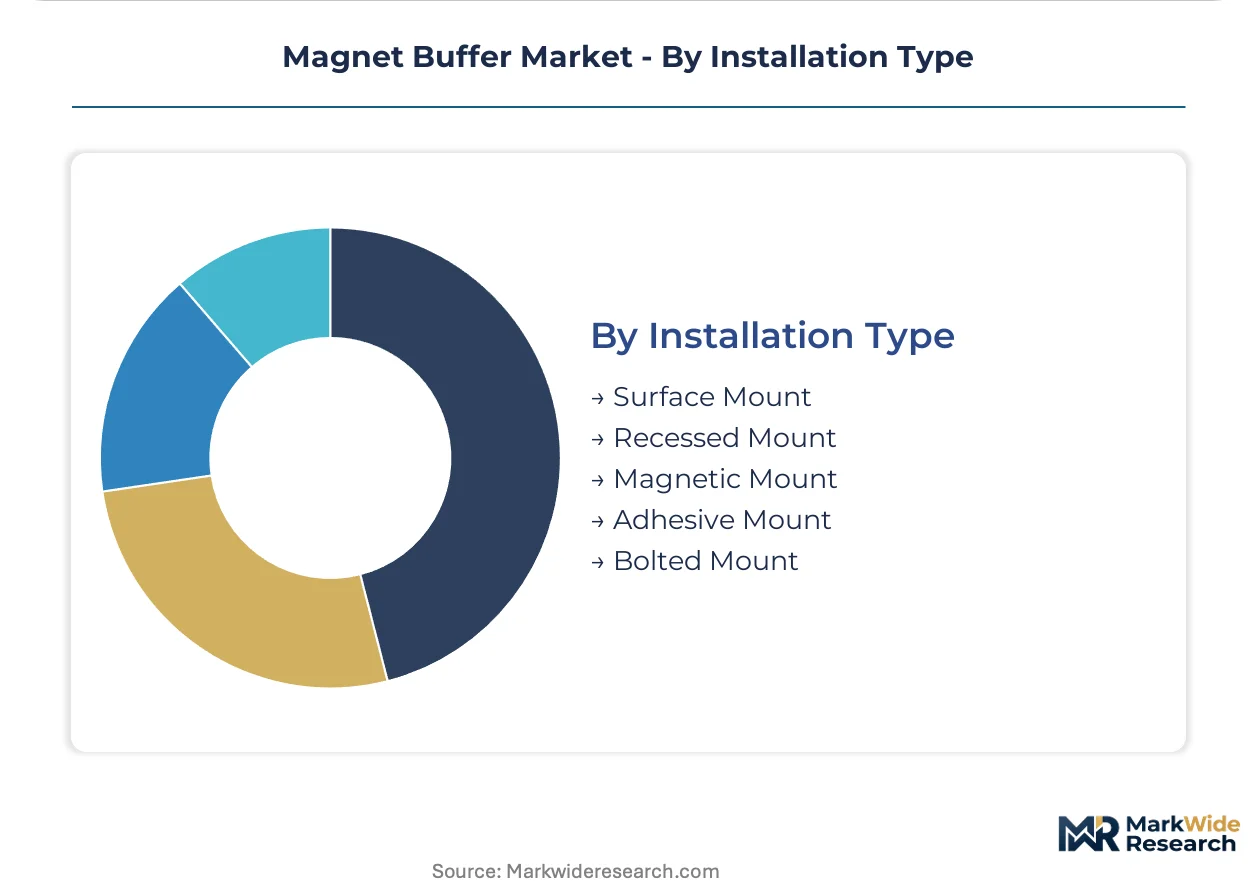
Deployment favors magnetic mounting in robotics; bolted configurations retain share in heavy equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province's bonded logistics zones and Japan's Kansai Special Area are concentrating magnet buffer procurement for robotics manufacturing. Bavaria's automotive clusters and Michigan's assembly corridors anchor demand in precision automation. These geographic concentrations reflect tax-advantaged production incentives and tier-1 supplier density.
United States
OSHA machine guarding mandates drive replacement cycles across warehouse distribution networks. EPA volatile organic compound regulations constrain rubber curing operations in domestic manufacturing. Michigan's automotive assembly corridor absorbs premium polyurethane buffers for battery pack handling systems.
Germany
EU F-Gas Regulation and REACH SVHC documentation extend supplier qualification timelines for European-bound products. ECHA enforcement of phthalate restrictions forces compound reformulation in elastomer production. Bavarian battery assembly lines specify adaptive damping buffers for cell-format handling equipment.
Japan
METI industrial safety directives mandate energy-absorbing stops on automated material handling equipment. JIS standards govern buffer performance specifications for robotics integration. Kansai region automotive plants pilot sensor-embedded smart buffers for predictive maintenance platforms.
China
MIIT industrial automation targets accelerate robotics deployment in manufacturing provinces. GB standards regulate elastomer compound safety for domestic production. Guangdong Province electronics clusters concentrate demand for cleanroom-compatible composite buffers in semiconductor-adjacent facilities.
South Korea
Seoul Capital Area robotics manufacturers consolidate supplier bases and compress qualification cycles. MFDS and KOSHA safety protocols govern automated equipment installations. Busan-Ulsan industrial corridor specializes in steel-reinforced buffers for heavy equipment fabrication.
Magnet Buffer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: diversified industrial automation conglomerates with pneumatic heritage, focused motion control specialists with deep elastomer formulation expertise, and regional fabrication houses serving cost-sensitive procurement. Dominant competitive moves include backward integration into specialized alloy supply and geographic expansion through distributor network consolidation.
Within the diversified automation tier, SMC and Festo exemplify heritage-driven positioning anchored in pneumatic system integration. Parker Hannifin occupies a scale-driven position across North American automotive corridors. These three companies represent contrasting geographic anchors—Japanese, German, and American industrial automation traditions—while serving overlapping robotics and automotive end-use specifications.
| Leading Market Players |
|---|
| SMC |
| CKD Corporation |
| Miculek |
| Festo |
| IMI Precision Engineering |
| Parker Hannifin |
| Emerson |
| Airtac International Group |
| Bosch Rexroth |
| Others |
Pricing and Supply Chain Analysis
Polyurethane formulation advances toward bio-based polyol feedstocks are simultaneously elevating compound engineering costs and consolidating supplier bases among REACH-certified European compounders. This dual squeeze compresses margin pools for uncertified regional fabricators while rewarding backward-integrated players with captive formulation capabilities.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement premiums from spot-inventory discounts across automotive assembly corridors. Three-tier pricing structure across REACH-certified premium, EPA-compliant standard, and uncertified economy levels reflects documentation burden differentials. Pricing pressure stems from robotics OEMs consolidating supplier bases and demanding cumulative cycle-count warranties. Tier-1 automotive integrators exhibit lowest price sensitivity; warehouse distribution operators show highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with specialized alloy suppliers concentrated in North American and East Asian metallurgical corridors for aerospace-grade steel buffers. Raw material flows draw from rare-earth magnet processors in China, polyol compounders in Germany, and chloroprene polymer producers in Japan. Tariff exposure on rare-earth imports threatens magnetic mounting component costs. Distribution runs through pneumatic automation distributors with deep ties to robotics OEM procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
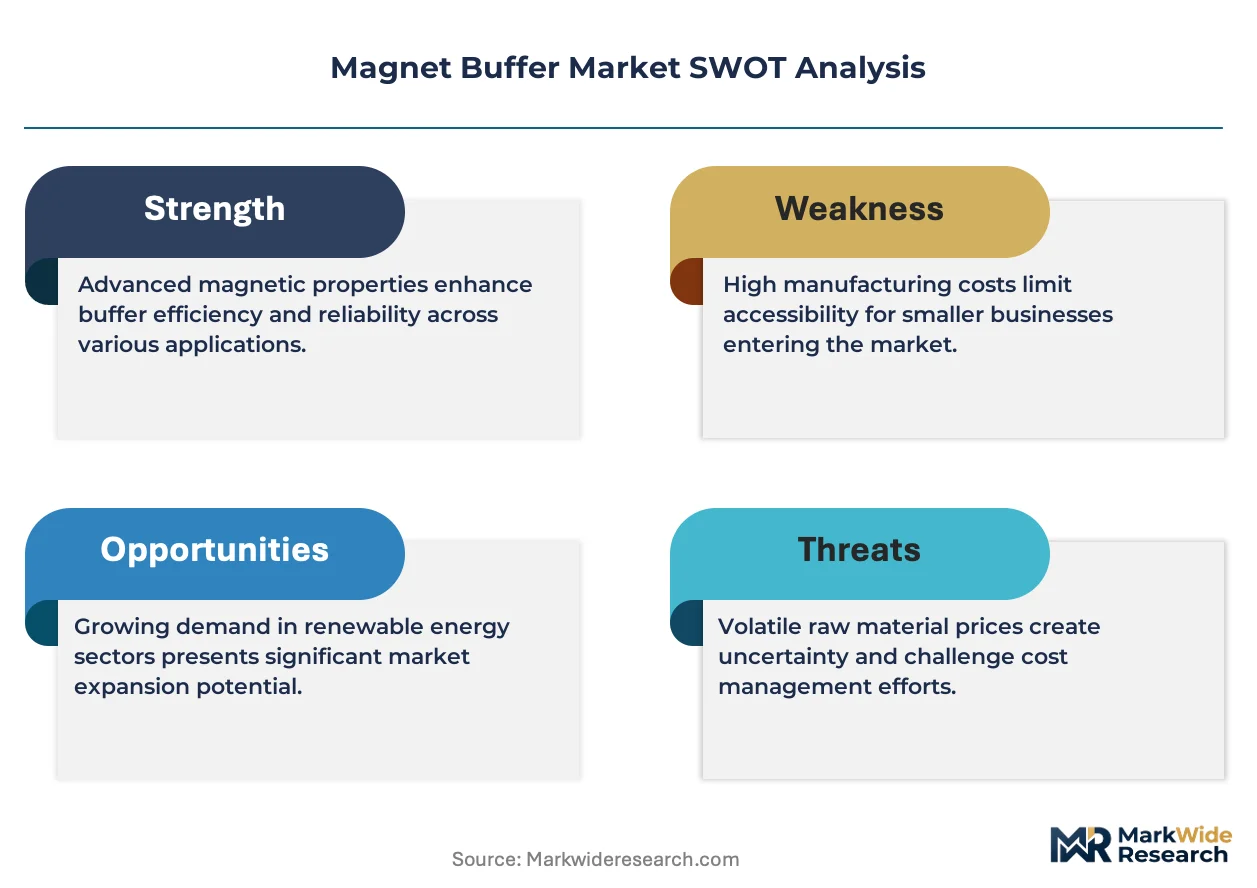
This market reads as a cost-of-compliance story where REACH SVHC documentation and ECHA enforcement create barrier-to-entry moats for compounders with established European certification chains.
For Market Incumbents: Deepen backward integration into specialized polyurethane formulation to defend margin position against bio-based feedstock cost volatility. Fortify Bavarian and Michigan service infrastructure to capture replacement demand from OSHA machine guarding mandates. Prioritize sensor-embedded smart buffer R&D to meet Japanese automotive predictive maintenance specifications.
For New Entrants and Emerging Players: Capture white-space in cleanroom-compatible composite buffers for Guangdong Province semiconductor clusters where outgassing specifications restrict incumbent options. Exploit underpenetrated logistics provider segments with rapid-swap magnetic mounting configurations. Lead with EU Green Deal alignment and bio-based polyurethane credentials to qualify for European public-sector automation tenders.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade-sale acquisitions by diversified pneumatic automation conglomerates seeking REACH-compliant formulation capabilities. Five-to-ten year viability favors compounders with dual EPA and ECHA certification infrastructure. Watch PFAS restriction timeline acceleration as inflection indicator forcing material reformulation investments across high-temperature buffer portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Formulation | Captures margin pools from REACH-certified compound supply in Bavarian automotive corridors. |
| Sensor-Embedded Smart Buffer Development | Aligns with METI predictive maintenance pilots in Kansai region automotive plants. |
| Bio-Based Polyol Feedstock Transition | Qualifies for EU Green Deal preferential procurement scoring in European public tenders. |
| Cleanroom Composite Buffer Certification | Penetrates semiconductor-adjacent installations in Guangdong Province electronics clusters. |
| Distributor Network Consolidation | Compresses qualification cycles for robotics OEM procurement teams in Michigan and Japan. |
Research Methodology
Independent corroboration across robotics OEM procurement directors, polyurethane compound R&D leads, and pneumatic automation distributor principals underwrites the qualitative findings. Primary fieldwork incorporated maintenance directors at Tier-1 automotive plants, aftermarket service heads at material handling operators, and regulatory affairs specialists at elastomer manufacturers. Secondary validation drew from EPA VOC emission databases, ECHA SVHC candidate list updates, METI industrial safety directive filings, and customs trade flow records. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Rate-of-change decomposition across the analysis window separated volume growth from price-mix effects by product type, application, and end-user industry. Segmentation dimensions modeled include elastomer formulation chemistry, mounting geometry configuration, and regional regulatory compliance tier. CAGRs derived from trend extrapolation of robotics deployment intensity and automotive assembly line automation rates. Industry-specific forecast inputs incorporated OSHA machine guarding mandate implementation timelines and MIIT industrial automation target trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PFAS coating phase-out acceleration and rare-earth supply chain restructuring. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Asia-Pacific Magnet Wire Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Magnetic Carbon Nanofoam Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
Ferrofluid Market
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Europe Ferrite Magnet Market
Magnetic Materials
North America Samarium Cobalt Magnets Market
Magnetic Materials
Global Electrical Steel Sheet Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
North America Magnet Wire Market