
 Global Electrical Steel Sheet Market | 2026-2036
Global Electrical Steel Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrical Steel Sheet Market Foresight
IEC 60404-8-7 certification for grain-oriented electrical steel is unwinding the competitive field, disqualifying second-tier mills from transformer core supply contracts. China Baowu Steel Group leverages its captive iron ore and hot-rolling capacity to dominate domestic procurement cycles. ArcelorMittal S.A. anchors European transformer demand through its Belgian and French finishing lines. Nippon Steel Corporation differentiates via ultra-low core-loss grades for high-efficiency distribution transformers.
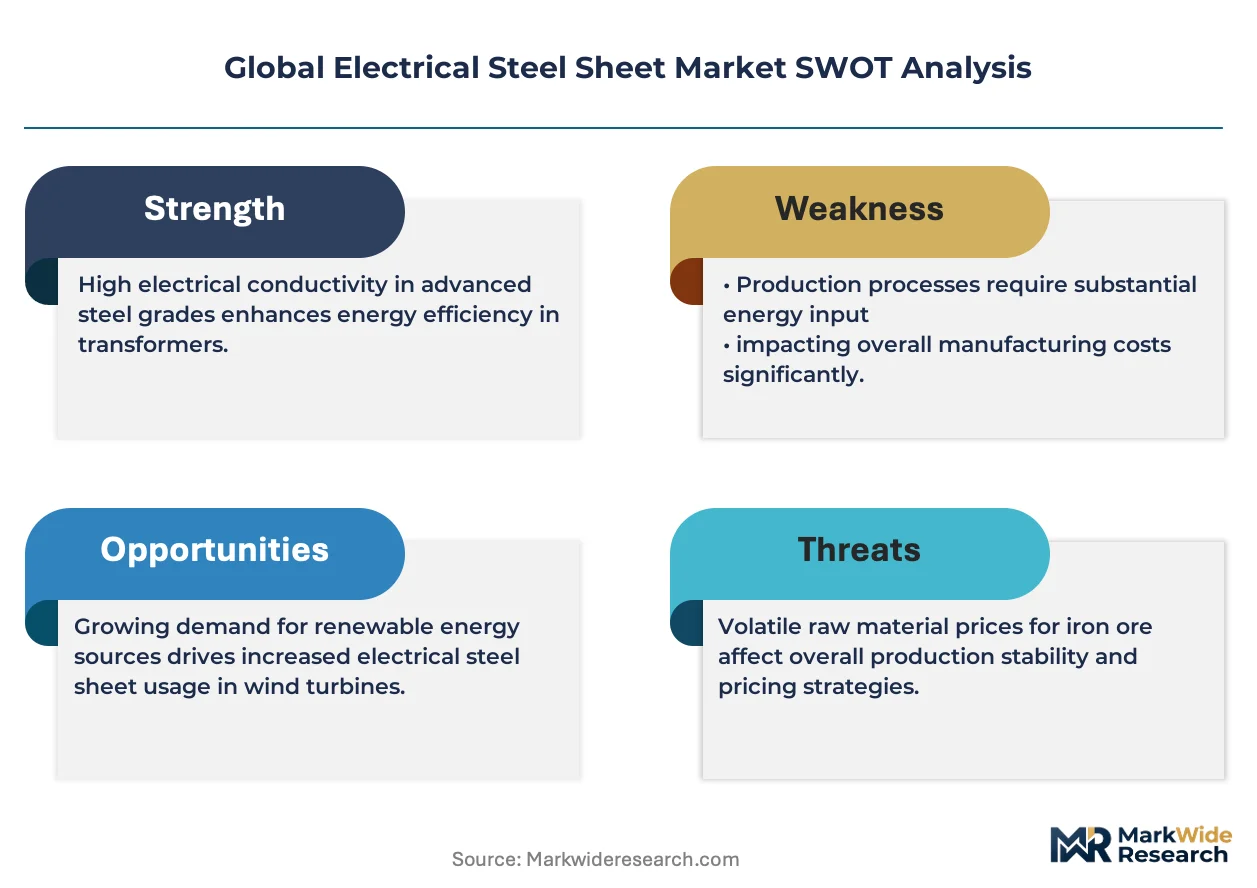
Electrical steel sheet is a silicon-alloyed flat-rolled product, typically containing 1.0–4.5% silicon by weight, manufactured through cold rolling and annealing to control grain orientation and magnetic permeability; its primary purpose is to minimize hysteresis and eddy-current losses in electromagnetic cores. Grain-oriented material commands premium positioning in power transformers due to directional magnetic properties, while non-grain oriented grades compete on volume in electric motors where isotropic flux paths suffice. Renewable energy end-user demand is accelerating fastest, driven by wind turbine generators and solar inverter step-up transformers requiring high-permeability formulations.
REACH compliance in Europe, GB standards enforcement by SAMR in China, and EPA air-quality oversight at US annealing facilities collectively tighten coating and emission specifications, raising capital thresholds for new entrants. The EU AI Act and CSRD disclosure rules will soon require supply-chain carbon accounting that favors mills with hydrogen-reduction pilot lines. Stakeholders must monitor which producers secure qualification for next-generation amorphous-competitive grades before grid procurement cycles lock in multi-year supplier agreements.
Market Dynamics
Transformer procurement cycles in China and India are compressing as power utilities accelerate grid modernization, forcing mills to requalify core-loss specifications ahead of IEC 60404-8-7 enforcement deadlines.
Growth Catalysts
- EU F-Gas Regulation:Tightening fluorinated-gas phase-down mandates are accelerating replacement of aging distribution transformers with high-efficiency units requiring premium grain-oriented grades.
- Wind turbine generators:Direct-drive permanent magnet designs are consuming non-grain oriented electrical steel at volumes that outpace traditional motor applications.
- Shanghai-Busan manufacturing clusters:Integrated steel-electronics supply chains are shortening lead times from mill annealing to transformer core stamping.
Market Restraints
- Iron ore price volatility:Captive mining capacity concentrates among top-tier integrated producers, exposing second-tier mills to input cost squeezes.
- Supply concentration risk:Grain-oriented finishing capacity clusters in Belgium, France, and Japan, creating single-source vulnerability for European transformer OEMs.
- Amorphous metal substitution:Metglas and Hitachi Metals are pushing nanocrystalline ribbon for distribution transformer cores with lower core-loss profiles.
Strategic Opportunities
- India CEA efficiency mandates:Central Electricity Authority regulations are forcing state utilities to specify CRGO-grade cores in new procurement tenders.
- Hydrogen-direct-reduction pilot lines:EU CSRD carbon-accounting rules will favor mills with near-zero-emission annealing capacity in next qualification cycles.
- Solar inverter step-up transformers:Utility-scale photovoltaic installations are creating demand for high-permeability grades in compact substation designs.
Industry Challenges
- IEC 60404-8-7 certification timelines:Second-tier mills face 18-24 month qualification delays that lock them out of transformer core contracts.
- Coating chemistry reformulation:REACH compliance and GB standards enforcement are forcing simultaneous retooling of insulation and anti-corrosion layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrical Steel Sheet Market |
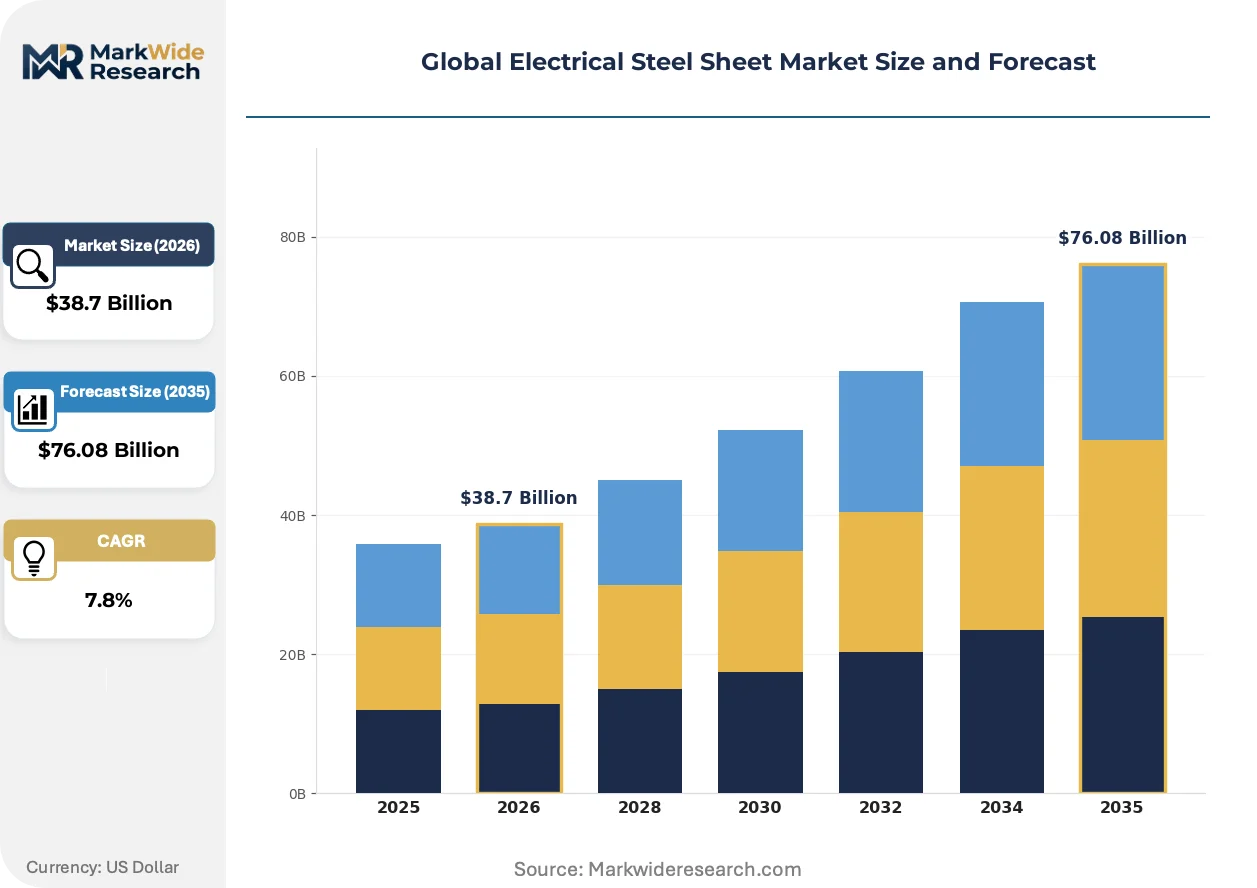
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $76.08 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grain-Oriented, Non-Grain Oriented, High Permeability, Semi-Processed Application: Transformers, Electric Motors, Generators, Inductors Manufacturing Stage: Cold Rolled, Annealed, Coated, Insulated End User Industry: Power Generation, Household Appliances, Heavy Equipment, Renewable Energy |
| Companies Covered | China Baowu Steel Group, ArcelorMittal S.A., Nippon Steel Corporation, POSCO, JFE Steel Corporation, thyssenkrupp Electrical Steel, Cleveland-Cliffs Inc., Tata Steel Limited, Nucor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrical Steel Sheet Market Shifts & Advancements
Coating chemistries and core-loss specifications are converging under tightening efficiency mandates, compressing the competitive field to mills with integrated qualification and low-carbon production capacity.
Ultra-thin gauge grain-oriented electrical steel is miniaturizing transformer core designs while maintaining magnetic permeability. Wind turbine OEMs in Denmark and Germany are specifying 0.18mm thickness grades for direct-drive generators. This thickness reduction is miniaturizing generator footprints without sacrificing flux density, enabling nacelle weight reductions that compound through tower and foundation specifications.
The EU AI Act and CSRD disclosure rules are mandating supply-chain carbon accounting that penetrates to tier-three suppliers. Mills without hydrogen-reduction pilot lines face disqualification from European transformer procurement cycles. Belgian and French finishing lines are responding with blockchain-tracked emissions certificates tied to each coil batch.
Utility procurement departments are consolidating supplier panels around pre-qualified mills with dual certification for IEC and GB standards. State Grid Corporation of China and Power Grid Corporation of India are both reducing approved vendor lists from twelve to four core suppliers. This concentration is most visible in East Asian tender processes, where integrated steel-electronics clusters now dominate qualification timelines.
Global Electrical Steel Sheet Market Segmentation
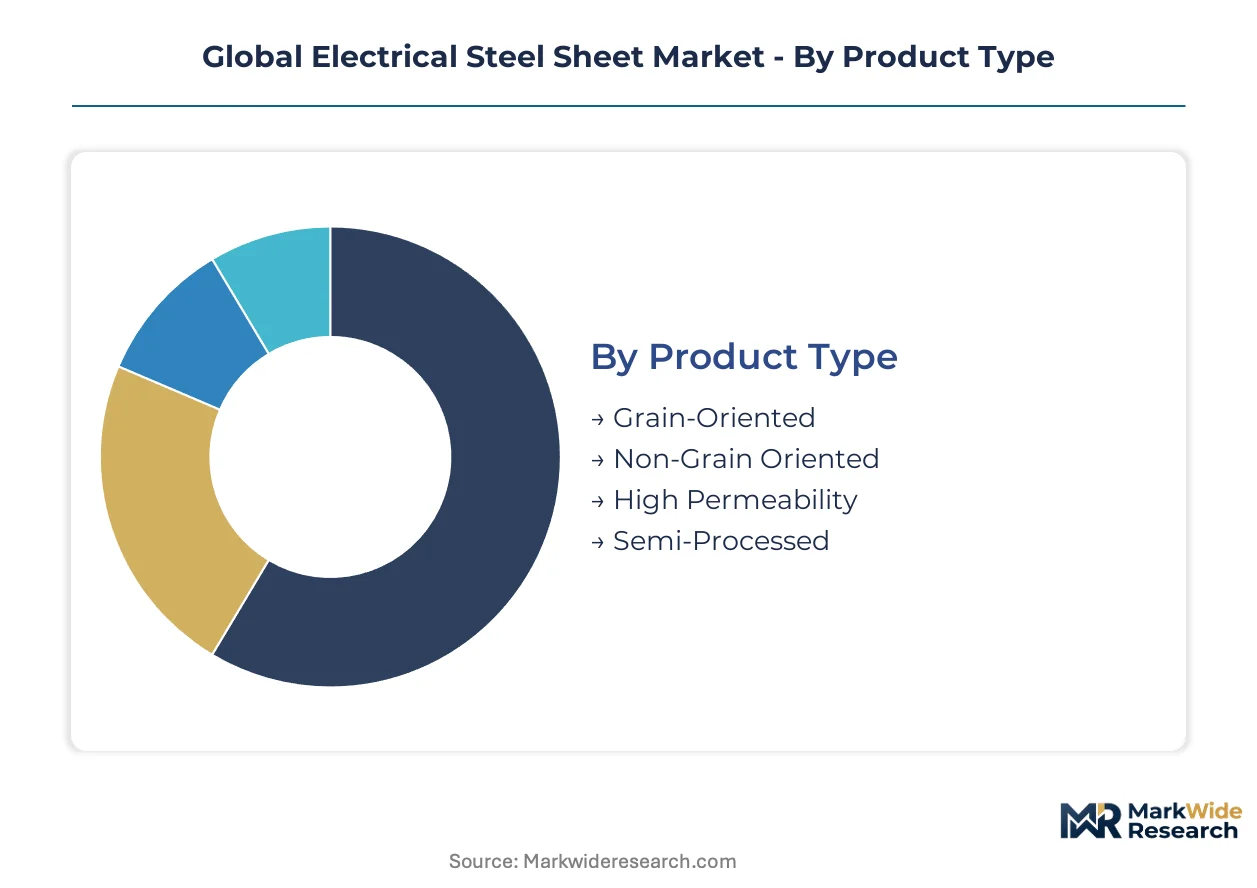
Electrical steel sheet segmentation maps directly to transformer and motor OEM procurement specifications. Grain orientation and manufacturing stage determine qualification timelines and geographic sourcing patterns across utility and industrial accounts.
Product Type:
Grain-oriented grades dominate domestic procurement in transformer-heavy markets, while non-grain oriented flows through export channels to motor manufacturers.
- Grain-Oriented:Silicon-alloyed steel with controlled crystallographic alignment delivers directional magnetic properties for power transformer cores. Demand concentrates in China and India where State Grid and Power Grid Corporation of India are modernizing distribution networks under tightening IEC efficiency mandates.
- Non-Grain Oriented:Isotropic magnetic properties suit rotating machinery where flux direction varies; wind turbine generators in Denmark and Germany are specifying high-silicon grades for direct-drive permanent magnet designs. Export volumes from Shanghai-Busan clusters supply European and North American motor OEMs.
- High Permeability:Ultra-low core-loss formulations for compact substation transformers in utility-scale solar installations.
- Semi-Processed:Intermediate annealed product for downstream stampers performing final heat treatment.
Grain-Oriented commands the established base. The steepest expansion runs through Non-Grain Oriented.
Application:
Application segmentation tracks the divergence between stationary electromagnetic equipment and rotating machinery, each with distinct qualification protocols and margin structures.
- Transformers:Distribution and power transformers consume grain-oriented grades with core-loss specifications tightening under EU F-Gas Regulation and India CEA mandates. Procurement cycles compress as utilities in China and India accelerate grid modernization.
- Electric Motors:Industrial and appliance motors drive volume demand for non-grain oriented grades; efficiency regulations in Europe and China push toward higher silicon content.
- Generators:Wind turbine OEMs specify thin-gauge non-grain oriented for nacelle weight reduction.
- Inductors:Power electronics and EV charging infrastructure create niche demand for high-frequency capable grades.
Transformers anchor revenue concentration. Generators are climbing the fastest as renewable deployment accelerates.
Manufacturing Stage:
Stage segmentation reveals where capital intensity and technical barriers concentrate competitive advantage among integrated producers.
- Cold Rolled:Thickness reduction to 0.18-0.35mm sets the mechanical foundation for magnetic properties; Belgian and French finishing lines specialize in ultra-thin gauge for premium transformer cores.
- Annealed:Controlled atmosphere heat treatment establishes grain orientation and core-loss performance; hydrogen-reduction pilot lines in Europe gain preference under CSRD carbon accounting rules.
- Coated:Insulation and anti-corrosion layers face simultaneous retooling for REACH compliance and China GB standards enforcement.
- Insulated:Final dielectric treatment for high-voltage transformer applications.
Annealed capacity locks in supplier relationships. Coated stages face the most intensive reformulation pressure.
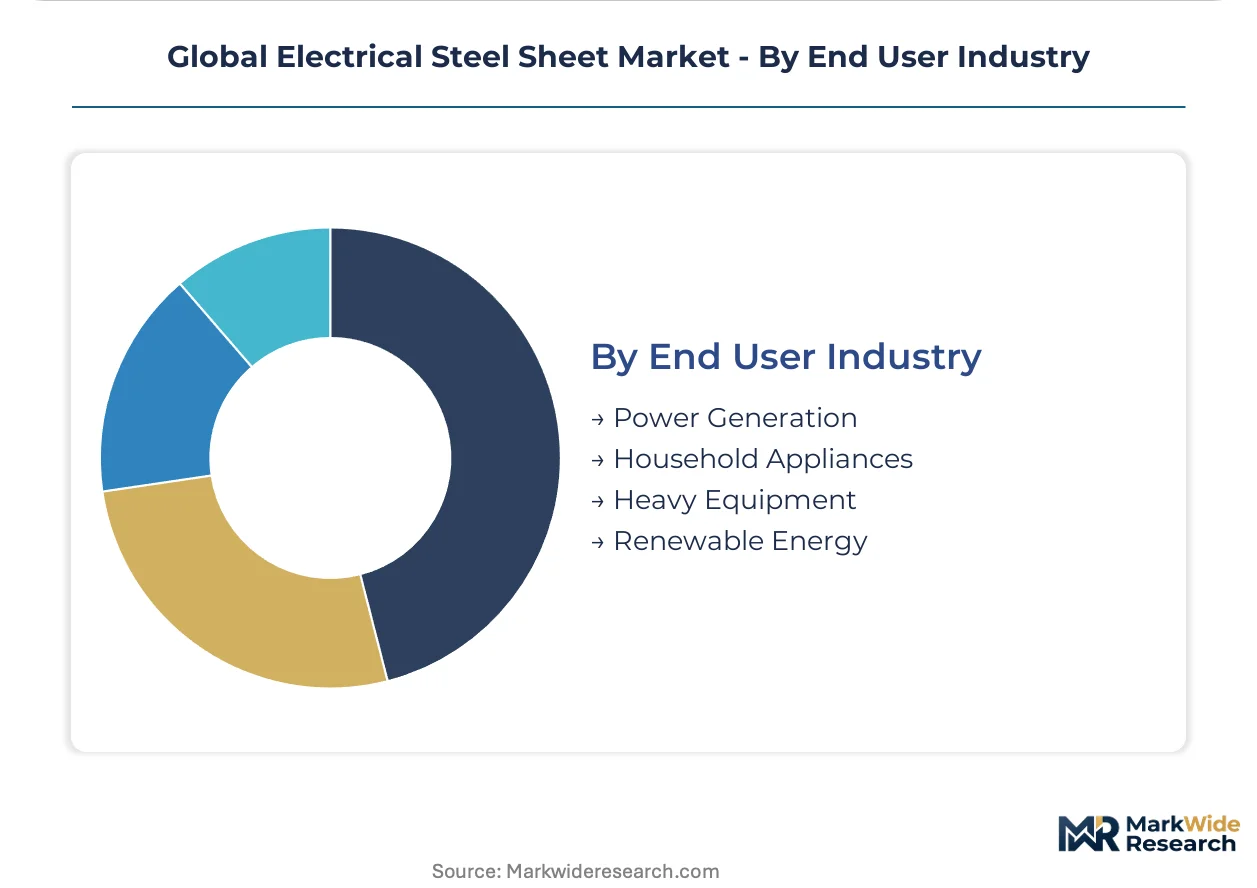
End User Industry:
End-use segmentation exposes the split between regulated utility procurement and discretionary industrial demand.
- Power Generation:Centralized and distributed generation infrastructure specifies premium grades with extended qualification timelines; state-owned utilities in China and India consolidate vendor panels around pre-qualified mills.
- Household Appliances:Compressor and washing machine motors consume standard non-grain oriented grades with price-sensitive procurement.
- Heavy Equipment:Industrial motors and drives for manufacturing and mining applications.
- Renewable Energy:Wind and solar installations demand high-permeability formulations for compact designs; solar inverter step-up transformers in utility-scale photovoltaic projects specify grades that minimize footprint in substation layouts.
Power Generation maintains volume dominance. Renewable Energy is gaining share fastest as capacity additions accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Busan maritime corridor anchors East Asian supply chains, with dedicated bulk terminals handling silicon-alloyed coil shipments to transformer stampers. This infrastructure underwrites the fastest procurement cycles from mill annealing to core assembly.
China
State Grid Corporation procurement tenders specify CRGO-grade cores under tightening GB standards enforcement by SAMR. The Yangtze River Delta cluster around Shanghai integrates Baowu Steel hot-rolling with downstream electronics manufacturing. Hydrogen-reduction pilot lines at select mills gain preference as dual carbon goals harden emission accounting.
India
Power Grid Corporation of India compresses vendor panels from twelve to four approved suppliers under CEA efficiency mandates. Central Electricity Authority regulations now require grain-oriented cores in all new distribution transformer tenders. Manufacturing concentrates in Gujarat and Maharashtra where integrated steel-electronics corridors shorten lead times.
Japan
METI efficiency standards drive specification of ultra-low core-loss grades for high-efficiency distribution transformers. JIS certification protocols create 18-24 month qualification barriers for foreign mills seeking utility access. The Chubu region around Nagoya hosts specialized finishing lines serving domestic transformer OEMs.
Germany
Wind turbine OEMs in northern Germany specify thin-gauge non-grain oriented grades for direct-drive permanent magnet generators. REACH compliance and EU F-Gas Regulation force simultaneous coating chemistry reformulation across annealing facilities. The Ruhr industrial corridor maintains finishing capacity for premium transformer core supply.
United States
EPA air-quality oversight at annealing facilities tightens emission thresholds for coating and heat-treatment stages. FERC grid interconnection standards accelerate transformer procurement for renewable energy integration. The Great Lakes region retains cold-rolling capacity serving domestic motor and transformer manufacturers.
Global Electrical Steel Sheet Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and qualification timelines. The field compresses around three tiers: integrated ore-to-coil producers with captive mining, regional finishing specialists with IEC-certified annealing lines, and emerging hydrogen-reduction pilots seeking CSRD-compliant positioning. Dominant competitive moves include backward integration into iron ore supply and strategic partnerships for coating chemistry development.
Within the integrated producer tier, China Baowu Steel Group and ArcelorMittal S.A. occupy positions that exemplify scale-driven supply security. Nippon Steel Corporation sits within the specialization vector, representing premium-grade differentiation for high-efficiency applications. These three anchors demonstrate how geographic concentration of finishing capacity—Belgian and French lines for ArcelorMittal, Japanese facilities for Nippon Steel—shapes procurement access for regional transformer OEMs.
| Leading Market Players |
|---|
| China Baowu Steel Group |
| ArcelorMittal S.A. |
| Nippon Steel Corporation |
| POSCO |
| JFE Steel Corporation |
| thyssenkrupp Electrical Steel |
| Cleveland-Cliffs Inc. |
| Tata Steel Limited |
| Nucor Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between State Grid Corporation of China and Baowu Steel lock in both supply access and price visibility across multi-year procurement cycles, insulating integrated mills from iron ore volatility while exposing second-tier producers to spot market squeezes under SAMR's tightening GB standards enforcement.
Pricing Analysis
Certification level creates the primary spread across the market, with IEC 60404-8-7-qualified grades commanding substantial premiums over uncertified alternatives. Contract-based long-term offtake dominates transformer procurement, while spot transactions persist for non-grain oriented motor grades. Price differentiation hinges on core-loss performance tiers and captive iron ore supply. Cost compression in standard grades is intensifying because Indian and Chinese utilities are consolidating vendor panels. Appliance motor manufacturers exhibit highest price sensitivity; utility procurement departments show lowest sensitivity due to efficiency-mandate compliance requirements.
Supply Chain Analysis
Strategic stockpiling of silicon-alloyed coil prevails among transformer OEMs facing 18-24 month IEC qualification timelines, while motor manufacturers maintain just-in-time inventory given shorter non-grain oriented lead times. Supply concentrates in China, Japan, and Belgium, with finishing capacity clustering around Shanghai, Nagoya, and the French-Belgian border. The chain rests on iron ore, silicon metal, and specialized annealing furnace inputs. Single-source vulnerability plagues European transformer OEMs dependent on ArcelorMittal's Belgian and French lines. Distribution runs through dedicated bulk terminals along the Shanghai-Busan maritime corridor to integrated steel-electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as State Grid Corporation of China and Power Grid Corporation of India compress approved vendor lists from twelve to four core suppliers, shifting negotiation leverage toward procurement departments and away from fragmented mill bases.
For Market Incumbents: Compound qualification advantages by accelerating hydrogen-reduction pilot line investments ahead of EU CSRD carbon-accounting enforcement. Deepen backward integration into captive silicon metal supply to insulate margins from raw material squeezes. Lock in multi-year offtake agreements with Indian utilities before CEA efficiency mandates fully reshape vendor panels. Prioritize coating chemistry R&D partnerships to satisfy simultaneous REACH and GB standards retooling requirements. For New Entrants and Emerging Players: Differentiate on hydrogen-reduction positioning for European transformer procurement cycles seeking CSRD-compliant suppliers. Target solar inverter step-up transformer segments where qualification timelines remain shorter than utility-scale power transformer barriers. Enter through semi-processed product supply to downstream stampers performing final annealing, avoiding 18-24 month IEC certification delays that lock out greenfield coil producers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated ore-to-coil producers with dual IEC-GB certification and established utility relationships. Long-term viability over the coming decade rests on securing annealing capacity in jurisdictions with carbon-accounting headroom. Monitor hydrogen-reduction pilot line commissioning announcements as the inflection indicator for next qualification cycle positioning. Prioritize targets with Shanghai-Busan cluster access and existing State Grid or Power Grid Corporation of India supply relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Direct-Reduction Pilot Line Investment | Secures CSRD-compliant positioning for European transformer procurement cycles under tightening carbon-accounting rules. |
| Backward Integration into Silicon Metal Supply | Insulates core-loss grade producers from input cost volatility concentrated among top-tier integrated mills. |
| Dual IEC-GB Certification Achievement | Unlocks access to consolidated vendor panels at State Grid and Power Grid Corporation of India. |
| Coating Chemistry Reformulation Partnership | Addresses simultaneous REACH compliance and SAMR GB standards enforcement across insulation layers. |
| Ultra-Thin Gauge Cold Rolling Capacity Expansion | Captures wind turbine generator demand from Danish and German OEMs specifying 0.18mm thickness grades. |
Research Methodology
Desk research of customs trade data, SEC filings from listed steel producers, and IEC certification registries preceded structured interviews with transformer procurement officers at Chinese and Indian utilities, annealing line technical directors, coating chemistry R&D leads, and wind turbine generator supply chain managers. Primary fieldwork combined with secondary validation from SAMR enforcement notices and EU F-Gas Regulation implementation documents. Bottom-up coil shipment data triangulated against top-down transformer installation forecasts.
Variance decomposition across product type, manufacturing stage, and end-user industry dimensions shaped volume and value outputs over the projection horizon. CAGRs derived from segmented growth rate modeling incorporating renewable energy capacity addition pipelines and utility grid modernization procurement schedules. Core-loss specification tightening trajectories under IEC 60404-8-7 and hydrogen-reduction pilot line commissioning timelines served as key forecast inputs.
Forecasts assume regulatory continuity in EU F-Gas phase-down mandates, India CEA efficiency regulations, and China dual carbon goals; material policy shifts would require re-modeling. Supply concentration risk at Belgian and French finishing lines, amorphous metal substitution acceleration, and iron ore price volatility represent primary revision triggers. Revision becomes warranted when hydrogen-reduction capacity crosses thresholds that disqualify conventional annealing lines from European procurement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Europe Copper Magnetic Wire Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Samarium Cobalt Magnets Market
Magnetic Materials
Copper Magnet Wire Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Magnetic Filter Market
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Global Permanent Magnet Market
Magnetic Materials
Ferrite Magnet Market
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
Ferromanganese Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
Japan Neodymium Iron Boron Magnet Market
Magnetic Materials
Magnet Market
Magnetic Materials
Global Soft Magnetic Alloys Market