
 Magnetic Alloys Market | 2026-2036
Magnetic Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Alloys Market Analytics
Modular magnet assembly kits is expanding buyer flexibility across distributed manufacturing networks. Hitachi Metals Ltd. leverages integrated rare-earth sourcing from mine to finished magnet to control supply security. Arnold Magnetic Technologies specializes in thin-gauge laminations for aerospace sensor applications. Vacuumschmelze GmbH & Co. KG anchors European supply through its rapid-solidification ribbon production in Hanau.
Magnetic alloys are metallic compositions engineered to exhibit ferromagnetic properties, typically incorporating iron, nickel, cobalt, or rare-earth elements such as neodymium and samarium with specified coercivity and remanence values, produced through sintering, rapid solidification, or melt-spinning for energy conversion and field-generation roles. Neodymium Iron Boron dominates value pools due to its unmatched maximum energy product for traction motor applications. Soft magnet alloys in transformer cores represent a mature, volume-heavy segment where grain-oriented electrical steel maintains cost advantage. Hybrid magnet configurations combining ferrite with rare-earth phases are gaining traction in cost-sensitive automotive auxiliary systems.
China's MIIT enforces GB standards on rare-earth magnet performance and traceability, while the EU REACH regulation restricts hazardous substances in magnet coatings and surface treatments. The US Department of Commerce maintains export control lists affecting magnet alloy processing equipment. Stakeholders must monitor raw material passport requirements and alternative magnet chemistry investments to secure supply continuity.
Market Dynamics
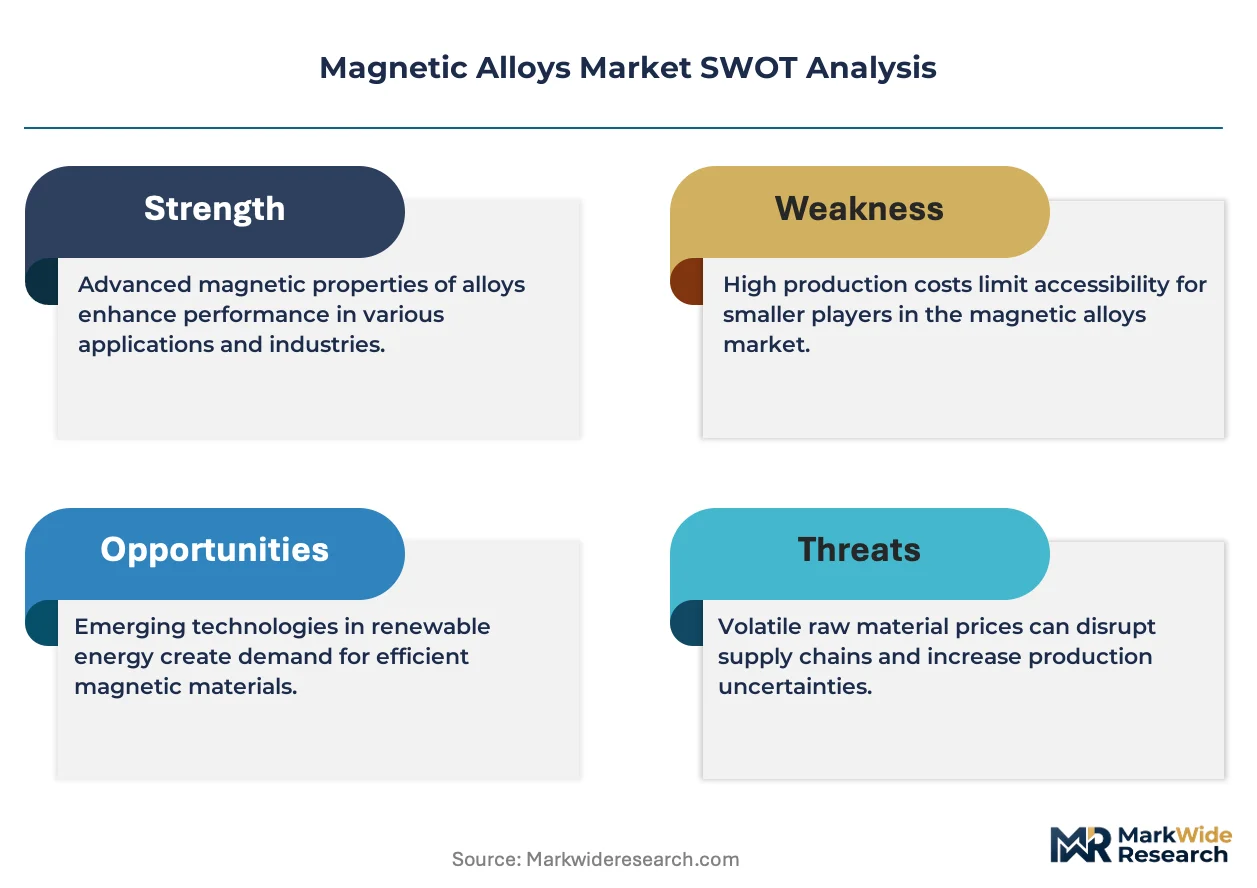
Rare-earth supply concentration in China's processing corridors is forcing magnet buyers to reconfigure procurement strategies around dual-sourcing mandates and alternative chemistry investments. This structural chokepoint is accelerating the search for non-dysprosium magnet formulations and regional magnet manufacturing capacity.
Growth Catalysts
- EV Traction Motor Demand:Automakers in Germany, Japan, and the United States are locking in multi-year magnet supply contracts for permanent magnet synchronous motors, with procurement volumes scaling proportionally to battery electric vehicle production targets.
- Wind Turbine Generator Scaling:Direct-drive permanent magnet generators for offshore wind installations are consuming neodymium iron boron alloys at rates that outpace historical onshore turbine specifications.
- China's Dual Carbon Framework:Beijing's carbon neutrality mandates are tightening energy efficiency standards for industrial motors, compelling retrofits with high-performance rare-earth magnets in factory automation systems.
Market Restraints
- Raw Material Concentration Risk:Over eighty percent of separated rare-earth oxide refining occurs in Chinese facilities, creating single-point-of-failure exposure for magnet alloy feedstock security.
- Dysprosium and Terbium Cost Volatility:Heavy rare-earth prices swing with Chinese export licensing cycles, compressing magnet manufacturer margins and destabilizing long-term contract pricing.
- Grain-Oriented Electrical Steel Substitution:Transformer core applications face persistent cost pressure from silicon steel laminations that satisfy efficiency thresholds without rare-earth content.
Strategic Opportunities
- Cerium-Substituted Magnet Formulations:Research programs at national laboratories in the United States and Australia are validating cerium-rich magnet alloys that reduce heavy rare-earth dependence for automotive auxiliary motors.
- India's PLI Scheme for Advanced Chemistry Cell Manufacturing:Domestic battery and motor production incentives are creating localized magnet demand that could support regional alloy processing investments.
- Modular Magnet Assembly Platforms:Distributed manufacturing networks are adopting kit-based magnet sourcing that reduces finished goods inventory and enables just-in-time motor assembly.
Industry Challenges
- Rare-Earth Metallurgy Talent Scarcity:Universities in Europe and North America produce insufficient graduates with expertise in magnet alloy sintering, rapid solidification, and corrosion-resistant coating processes.
- REACH Compliance for Surface Treatments:European magnet coaters face extended certification timelines for hexavalent chromium alternatives that satisfy salt-spray corrosion resistance standards.
- Magnet Recycling Yield Gaps:Hydrogen decrepitation and subsequent reprocessing of end-of-life magnets achieves recovery rates below commercial viability thresholds for many alloy grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Alloys Market |
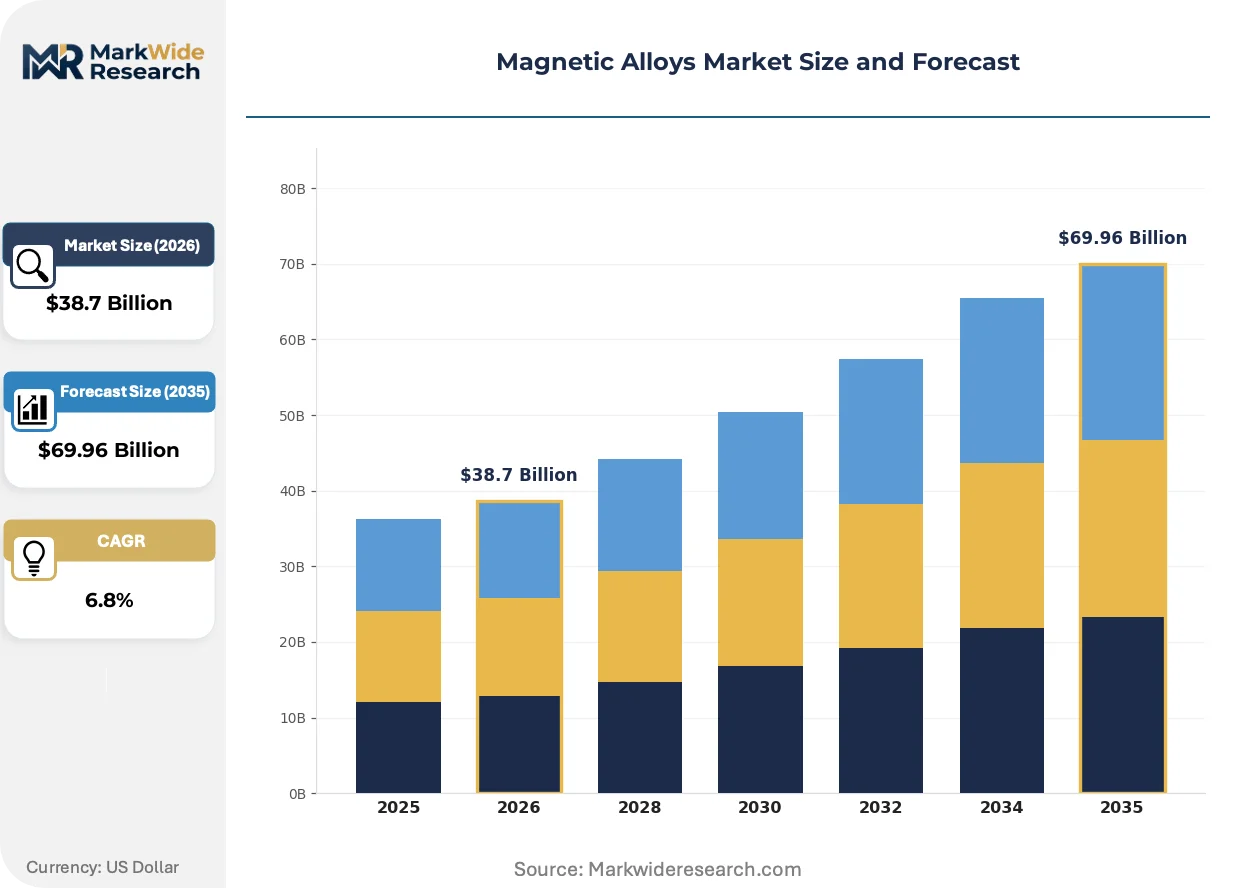
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Samarium Cobalt, Neodymium Iron Boron, Alnico, Ferrite Application: Motors, Sensors, Transformers, Magnetic Couplings End User: Aerospace, Electronics, Automotive, Healthcare Technology: Permanent Magnets, Soft Magnets, Hybrid Magnets, Composite Magnets |
| Companies Covered | Hitachi Metals Ltd., Arnold Magnetic Technologies, Vacuumschmelze GmbH & Co. KG, Shin-Etsu Chemical Co., Ltd., TDK Corporation, Molycorp Magnequench, DMEGC Magnetics Ltd., Ningbo Keningda Industry Co., Ltd., JL MAG Rare-Earth Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Alloys Market Evolving Landscape
Magnet alloy development is pivoting toward chemistry diversification and manufacturing flexibility as supply security concerns override pure performance optimization. Technical progress is concentrating in three interconnected domains.
Hot-deformed nanocrystalline magnet technology is converging with aerospace sensor miniaturization requirements. Defense contractors in the United States and satellite component suppliers in Japan are adopting these alloys for gyroscope and actuator applications where thermal stability exceeds sintered magnet limits. The convergence is compressing development cycles for next-generation guidance systems.
China's MIIT is enforcing updated GB standards on rare-earth magnet traceability and performance certification. The regulation requires mine-to-magnet documentation for export-bound products, increasing administrative burden on Ningbo and Ganzhou manufacturers. European automotive Tier-1 suppliers are responding by qualifying secondary magnet sources in Southeast Asia to diversify compliance risk.
Long-term magnet supply agreements are displacing spot-market purchasing for electric vehicle powertrain procurement. Automakers in Germany, South Korea, and the United States are locking in five-to-seven-year contracts directly with magnet alloy processors, bypassing traditional distributor channels. This pattern is most visible in traction motor programs where qualification timelines exceed eighteen months.
Magnetic Alloys Market Segmentation
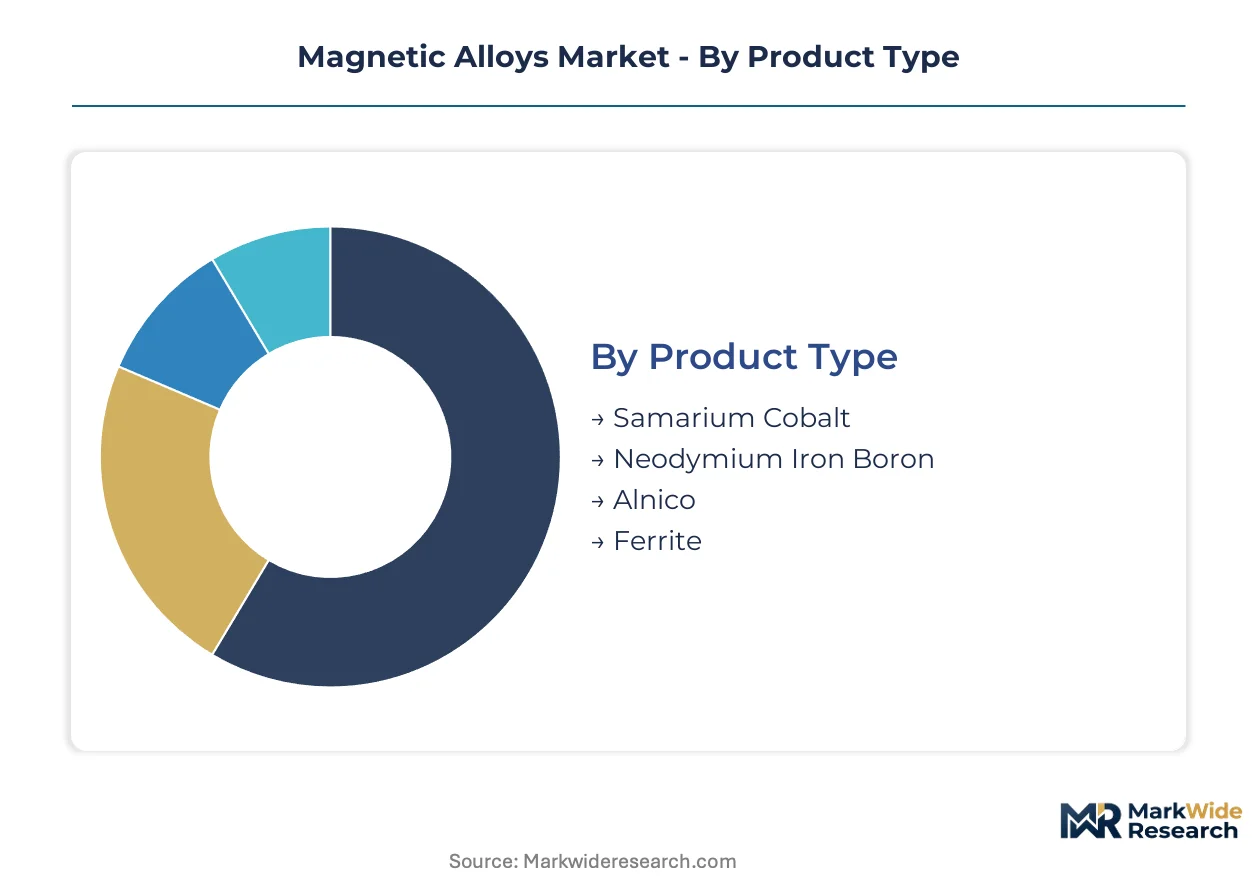
Segmentation in magnetic alloys determines procurement pathways, certification burdens, and margin structures. Buyers select alloy categories based on thermal tolerance, coercivity requirements, and supply security rather than price alone.
Product Type:
GB standards from China's MIIT govern rare-earth magnet exports, while REACH restricts coating chemistries for European-bound shipments. Aerospace buyers demand ITAR-compliant supply chains for samarium cobalt.
- Neodymium Iron Boron:Sintered NdFeB alloys deliver maximum energy product values exceeding 50 MGOe, enabling compact traction motor designs. Procurement concentrates in Germany's automaker supply chains, where qualification timelines exceed eighteen months and dual-sourcing mandates are now standard.
- Samarium Cobalt:These alloys retain magnetic performance above 300°C, making them irreplaceable for satellite actuators and defense gyroscopes. US defense contractors prioritize ITAR-certified processors in Pennsylvania and California over Asian sources despite cost premiums.
- Alnico:Cast or sintered aluminum-nickel-cobalt compositions serve temperature-stable sensor applications in industrial automation.
- Ferrite:Ceramic ferrite magnets dominate cost-sensitive automotive auxiliary motors where energy product requirements remain modest.
Neodymium Iron Boron sits at the top of the volume ranking, with Samarium Cobalt climbing the fastest.
Application:
Cost tiers separate commodity transformer cores from qualified aerospace sensor materials. Motors command premium pricing due to EV traction motor qualification complexity.
- Motors:Permanent magnet synchronous motors for battery electric vehicles consume neodymium iron boron at rates scaling with production targets. South Korean and German automakers have locked in five-to-seven-year direct contracts with alloy processors.
- Sensors:Thin-gauge laminations and nanocrystalline ribbons enable miniaturized position and current sensing. Japanese satellite component suppliers drive specification tightening for thermal stability beyond sintered magnet limits.
- Transformers:Grain-oriented electrical steel maintains cost advantage in utility-scale power distribution despite rare-earth efficiency gains.
- Magnetic Couplings:Hermetic seals for chemical processing and medical equipment utilize corrosion-resistant magnet assemblies.
Motors dominates volume, with Sensors gaining share fastest.
End User:
Customer type determines specification stringency and contract structure. Automotive and aerospace buyers impose traceability requirements that commodity electronics purchasers waive.
- Automotive:Powertrain electrification is scaling procurement of rare-earth permanent magnets proportionally to battery electric vehicle targets. Tier-1 motor suppliers in Germany, Japan, and the United States bypass traditional distributors for direct alloy processor relationships.
- Aerospace:Defense contractors and satellite manufacturers specify hot-deformed nanocrystalline alloys for gyroscope and actuator applications. Thermal stability requirements exceed what sintered magnets can deliver.
- Electronics:Consumer device manufacturers prioritize magnet cost minimization for speakers and vibration motors.
- Healthcare:MRI scanner manufacturers require homogeneous magnetic field generation with minimal temperature drift.
Automotive leads volume, with Aerospace expanding most quickly.
Technology:
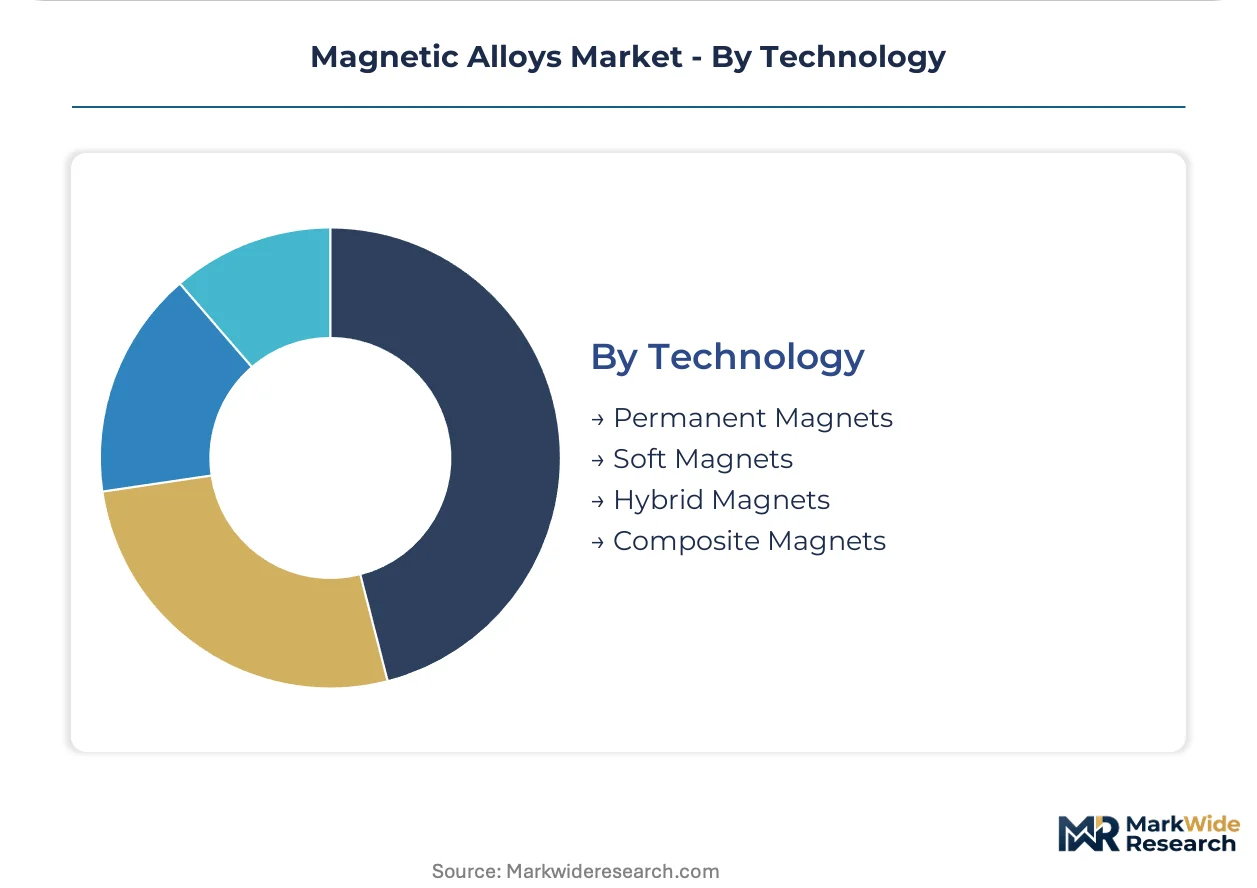
Maturity gradients separate established soft magnet transformer cores from emerging composite formulations. Hybrid configurations are gaining traction in cost-sensitive automotive auxiliary systems.
- Permanent Magnets:Sintered and bonded rare-earth magnets enable high-efficiency energy conversion in traction motors and wind turbine generators. Direct-drive offshore wind installations consume neodymium iron boron at rates outpacing historical onshore specifications.
- Soft Magnets:Rapid-solidification ribbon and grain-oriented electrical steel serve transformer and inductor applications. Vacuumschmelze's Hanau facility anchors European supply security for amorphous metal distribution.
- Hybrid Magnets:Ferrite-rare-earth combinations balance cost and performance for automotive auxiliary motors.
- Composite Magnets:Polymer-bonded magnet powders enable complex geometries for sensor housings and miniature actuators.
Soft Magnets dominates volume, with Hybrid Magnets climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The magnetic alloys industry traces its modern scaling to Japanese metallurgical breakthroughs in the 1980s, when neodymium iron boron formulations emerged from Sumitomo Special Metals research. Today, production corridors span East Asian processing clusters, European specialty foundries, and North American defense-certified facilities.
China
Electric vehicle powertrain manufacturers in Shanghai and Shenzhen are scaling procurement of rare-earth permanent magnets. MIIT enforces updated GB standards on magnet traceability and performance certification for export-bound products. Ningbo and Ganzhou manufacturing clusters concentrate sintering capacity and rapid-solidification ribbon production for global automotive supply chains.
Japan
Automakers in Toyota City and Yokohama have locked in multi-year magnet supply contracts for permanent magnet synchronous motors. METI coordinates national stockpiling programs for dysprosium and terbium to buffer against Chinese export licensing volatility. Chubu and Kansai industrial corridors host precision magnet processors serving satellite component suppliers and defense gyroscope manufacturers.
Germany
BMW and Volkswagen procurement teams in Munich and Wolfsburg are bypassing traditional distributors for direct alloy processor relationships. REACH regulation restricts hazardous substances in magnet coatings and surface treatments. Bavaria and Baden-Württemberg anchor European demand for qualified traction motor magnets with eighteen-month qualification timelines.
United States
Defense contractors in Pennsylvania and California prioritize ITAR-certified processors for samarium cobalt alloys in guidance systems. The Department of Commerce maintains export control lists affecting magnet alloy processing equipment. Mountain Pass and Texas-based rare-earth separation facilities are expanding to reduce feedstock dependence on Chinese refining corridors.
South Korea
Hyundai and Kia motor programs in Ulsan and Hwaseong are consuming neodymium iron boron at rates scaling with battery electric vehicle production targets. MFDS oversees material safety standards for magnet applications in medical devices. Seoul Capital Area procurement teams are qualifying secondary magnet sources in Southeast Asia to diversify compliance risk from Chinese GB standards.
Magnetic Alloys Market Competitive Landscape
The competitive structure tilts toward integrated rare-earth processors with captive mine-to-magnet supply chains. Tier-1 automotive suppliers and wind turbine OEMs now demand dual-sourcing mandates that favor processors with documented traceability systems. Three archetypes dominate: vertically integrated Asian conglomerates controlling oxide separation through finished magnet production; European specialty metallurgists focused on aerospace-certified alloys; and regional fabricators serving cost-sensitive automotive auxiliary markets. Capacity expansion and strategic partnerships represent the dominant competitive moves as buyers seek supply security over pure price optimization.
Among integrated Japanese processors, Hitachi Metals Ltd. and Shin-Etsu Chemical Co., Ltd. exemplify the conglomerate archetype with upstream control over rare-earth sourcing corridors. Vacuumschmelze GmbH & Co. KG anchors European supply security through its Hanau-based rapid-solidification ribbon production, representing the specialty metallurgist tier focused on thermal stability specifications. These three occupy positions that reflect the market's segmentation between volume-driven automotive procurement and precision aerospace requirements.
| Leading Market Players |
|---|
| Hitachi Metals Ltd. |
| Arnold Magnetic Technologies |
| Vacuumschmelze GmbH & Co. KG |
| Shin-Etsu Chemical Co., Ltd. |
| TDK Corporation |
| Molycorp Magnequench |
| DMEGC Magnetics Ltd. |
| Ningbo Keningda Industry Co., Ltd. |
| JL MAG Rare-Earth Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Dysprosium oxide spot quotations cascade through magnet alloy supply chains into three distinct procurement tiers. Heavy rare-earth price volatility compresses margins for processors locked into eighteen-month automotive qualification cycles, while spot-market buyers absorb immediate cost shocks.
Pricing Analysis
Contract-based long-term offtake dominates procurement for EV traction motor programs, with pricing stratifying across ITAR-certified aerospace grades, automotive-qualified sintered alloys, and commodity ferrite cores. Price differentiation centers on traceability certification and thermal stability specifications. Cost compression in standard-grade NdFeB is intensifying because Chinese export licensing cycles destabilize feedstock costs. Automotive Tier-1 suppliers exhibit lowest price sensitivity due to dual-sourcing mandates, while consumer electronics manufacturers maximize spot-market leverage.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore buffer European and Southeast Asian manufacturers against Chinese export timing risks. Feedstock security draws from Chinese rare-earth separation corridors, Australian heavy mineral concentrates, and Mountain Pass bastnaesite. Dysprosium and terbium supply hinges on Myanmar ionic clay deposits and Chinese ion-adsorption clay processing. Single-source vulnerability concentrates in Ganzhou and Ningbo sintering clusters. Distribution runs through direct processor-automaker relationships that displace traditional distributor channels for qualified traction motor alloys.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magnetic alloys market compounds steadily as electrification infrastructure locks in structural demand for permanent magnet synchronous motors across automotive and wind power applications.
For Market Incumbents: Deepen backward integration into rare-earth oxide separation to offset Chinese export licensing volatility. Secure ITAR certification for Pennsylvania and California facilities to defend aerospace samarium cobalt positioning against emerging domestic processors. Add rapid-solidification ribbon capacity in Hanau or comparable European hubs to anchor regional supply security for transformer core applications. For New Entrants and Emerging Players: The gap between aerospace-certified samarium cobalt premiums and commodity ferrite pricing opens white-space in automotive auxiliary motors requiring corrosion resistance without full rare-earth content. Target India's PLI-supported battery and motor manufacturing clusters where localized alloy demand outpaces domestic processing capacity. Pursue modular magnet assembly partnerships with Southeast Asian distributors to bypass eighteen-month automotive qualification barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty metallurgists possessing hot-deformed nanocrystalline production expertise for satellite actuator applications. Long-term viability favors processors with documented mine-to-magnet traceability systems aligned with EU REACH and China's MIIT GB standards. Watch for cerium-substituted magnet formulation breakthroughs at Australian and US national laboratories as inflection signals for heavy rare-earth demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Separation | Mountain Pass and Texas facilities reduce Chinese oxide refining dependence for magnet feedstock security. |
| ITAR Certification Investment | US defense contractors prioritize Pennsylvania and California processors for samarium cobalt guidance systems. |
| Cerium-Substituted R&D Partnership | National laboratory programs in Australia and the United States validate reduced heavy rare-earth automotive formulations. |
| Modular Magnet Assembly Platform | Kit-based sourcing enables just-in-time motor assembly across distributed Southeast Asian manufacturing networks. |
| REACH-Compliant Coating Development | European automotive Tier-1 suppliers require hexavalent chromium alternatives meeting salt-spray corrosion standards. |
Research Methodology
Coverage spans China, Japan, Germany, the United States, and South Korea, with primary inputs from each jurisdiction triangulated against secondary validation. Magnet alloy procurement directors, rare-earth separation plant managers, automotive Tier-1 supplier quality engineers, and wind turbine OEM material strategists provided structured interviews. Secondary sources include Chinese customs export data, MIIT GB standard filings, EU REACH substance restriction updates, SEC 10-K disclosures from listed processors, and production databases from vehicle registration systems. Bottom-up alloy demand modeling and top-down rare-earth oxide supply constraints were cross-validated.
Rate-of-change decomposition separates volume growth from price trajectory across the analysis window. Segmentation dimensions include magnet chemistry class, thermal stability tier, end-use application, and regional regulatory cluster. CAGRs were derived from alloy-specific demand elasticity coefficients applied to EV production targets and wind turbine installation schedules. Forecast inputs incorporate Chinese dual carbon policy implementation timelines and EU carbon border adjustment mechanism progression.
Caveats apply where Chinese export licensing volatility, Myanmar supply disruptions, or breakthroughs in cerium-substituted formulations could materially shift the outlook. Forecasts reflect documented assumptions on rare-earth separation capacity expansion and automotive qualification timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
High Performance Permanent Magnet Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
Global Electrical Steel Sheet Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Sintered Soft Magnetic Material Market
Magnetic Materials
Japan Neodymium Iron Boron Magnet Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Ferrofluid Market
Magnetic Materials
Ferromanganese Market
Magnetic Materials
Magnetic Carbon Nanofoam Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
Global Soft Magnetic Materials Market