
 Global Iron Powder Market | 2026-2036
Global Iron Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Iron Powder Market Foresight
The EU Green Deal is recalibrating procurement priorities across European automotive supply chains, pushing OEMs toward low-carbon iron powder grades for sintered components. Höganäs AB leverages its integrated sponge iron route in Sweden to deliver certified low-emission powders to tier-one suppliers. JFE Steel Corporation anchors Asian supply through its atomized powder complex in eastern Japan, while GKN Powder Metallurgy competes via dense regional press-and-sinter networks across Germany and North America.
Iron powder consists of discrete metallic iron particles typically manufactured through reduction of iron oxide, atomization of molten metal, electrolytic deposition, or thermal decomposition of iron pentacarbonyl, with particle sizes ranging from sub-10 micrometer fine grades to coarse fractions above 150 micrometers for filtration and structural applications. Its primary purpose centers on enabling near-net-shape fabrication via powder metallurgy, magnetic core production, and chemical reduction processes. Reduced iron powder dominates volume flows in automotive press-and-sinter operations where cost efficiency matters most, while atomized iron powder captures expanding share in additive manufacturing feedstock as laser powder bed fusion tolerances tighten. Carbonyl iron powder occupies the premium tier for high-frequency electromagnetic applications in radar and telecommunications hardware.
The EPA enforces particulate matter thresholds at US powder production facilities, while REACH governs chemical registration and occupational exposure limits across European manufacturing sites. Japan's METI coordinates domestic powder standards through JIS H 2111, aligning with automotive quality mandates from NHTSA and ECHA compliance requirements. Buyers must track evolving carbon border adjustments and alloy substitution patterns as electrification redesigns magnetic material specifications.
Market Dynamics
The EU Green Deal's embodied carbon mandates are compressing supplier margins and forcing tier-one automotive buyers to requalify their entire ferrous feedstock base against Scope 3 thresholds. This regulatory pressure is concentrating procurement power among powder producers with verifiable low-emission reduction routes.
Growth Catalysts
- Automotive lightweighting mandates:NHTSA fuel economy standards are pushing Detroit OEMs toward hollow sintered drivetrain components that reduce vehicle mass without sacrificing torque capacity.
- REACH chemical registration:European powder metallurgy suppliers are capturing premium positioning by certifying cobalt-free iron grades ahead of 2025 substance restriction deadlines.
- Additive manufacturing qualification:Laser powder bed fusion tolerances are tightening in Germany's medical implant sector, pulling atomized spherical powder into orthopedic supply chains previously served by wrought bar stock.
Market Restraints
- Scrap price volatility:Atomized powder producers in Japan face margin compression when shredded automotive scrap spikes above historical baselines, forcing quarterly surcharge negotiations with press-and-sinter customers.
- Sponge iron supply concentration:Swedish reduction capacity dominates certified low-carbon powder feedstock, creating single-source risk for European automotive suppliers seeking Green Deal compliance.
- Carbonyl iron process limitations:Thermal decomposition of iron pentacarbonyl yields sub-10 micrometer particles unsuitable for structural powder metallurgy, restricting this premium grade to electromagnetic applications.
Strategic Opportunities
- India's PLI scheme for specialty steel:Domestic atomized powder production under the production-linked incentive framework is attracting joint venture investment for electric motor lamination feedstock.
- Hydrogen-based direct reduction:Pilot plants in northern Sweden are integrating green hydrogen into sponge iron routes, positioning early movers for EU carbon border adjustment exemptions.
- Water atomization for AM feedstock:Indian powder producers are retrofitting gas atomization lines with high-pressure water systems to capture price-sensitive additive manufacturing demand in domestic tooling markets.
Industry Challenges
- Metallurgical technician scarcity:Germany's press-and-sinter operations report acute shortages of sintering furnace operators capable of maintaining atmosphere control within hydrogen-nitrogen specifications.
- ISO 22068 certification timelines:Automotive suppliers in Japan face 18-month qualification periods for new powder grades, compressing product development cycles against model-year deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Iron Powder Market |
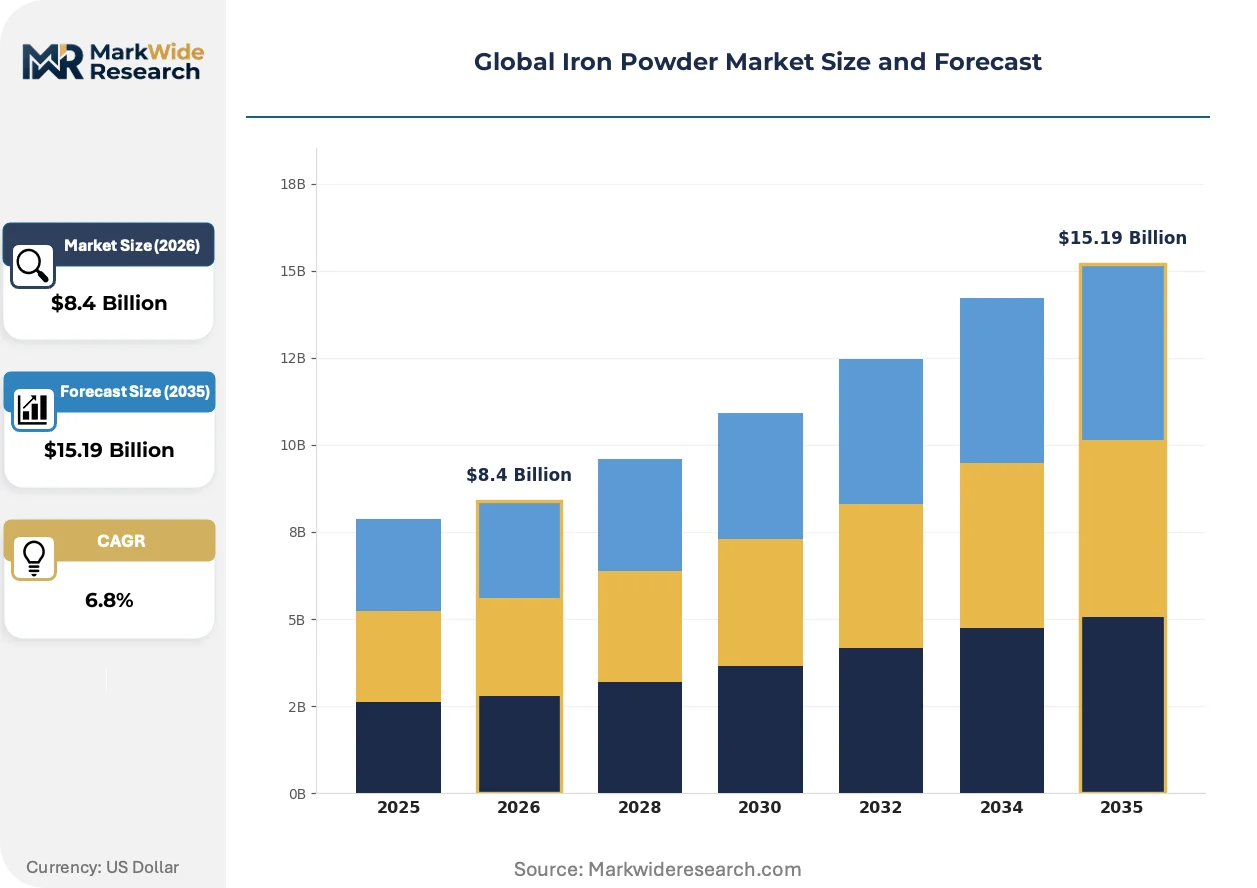
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reduced Iron Powder, Atomized Iron Powder, Electrolytic Iron Powder, Carbonyl Iron Powder Application: Powder Metallurgy, Magnetic Materials, Welding, Chemical Industry, Electronics End User Industry: Automotive Suppliers, Electrical Manufacturers, Construction Firms, Chemical Producers, Electronics Fabricators Form: Fine Powder, Coarse Powder, Granular Powder, Flake Powder |
| Companies Covered | Höganäs AB, Rio Tinto Metal Powders, JFE Steel Corporation, Kobe Steel, Industrial Metal Powders (India) Pvt. Ltd., BASF SE, GKN Powder Metallurgy, Reade International Corporation, American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Iron Powder Market Shifts & Advancements
Near-net-shape fabrication is displacing conventional machining across multiple end-use verticals, compressing material waste coefficients and tightening powder specification windows. This shift is forcing upstream producers to invest in particle morphology control and in-line sizing systems.
Water atomization is integrating high-pressure cooling systems with inert gas post-treatment to produce spherical iron powder at cost points competitive with gas atomization. Tier-one automotive suppliers in Germany are qualifying these grades for differential gear applications where fatigue resistance requirements previously demanded premium atomized feedstock. The structural consequence is a compression in the historical price gap between reduced and atomized powder categories.
REACH substance restrictions are forcing European powder metallurgy suppliers to eliminate cobalt and nickel from sintered steel formulations ahead of 2025 sunset dates. The regulation is accelerating R&D spending on manganese sulfide and calcium-treated alternatives for machinability enhancement. Magnetic core producers in France and Italy are most affected, with several facilities completing alloy reformulations six months ahead of enforcement to secure automotive qualification continuity.
Buyer consolidation among German automotive tier-ones is compressing supplier lists and extending master service agreement durations from annual to multi-year frameworks. Procurement teams at drivetrain specialists are bundling iron powder, copper premix, and lubricant purchases under single-source contracts with volume-tiered pricing. This concentration is most visible in Stuttgart and Munich supply clusters, where three buyers now account for the majority of domestic press-and-sinter powder offtake.
Global Iron Powder Market Segmentation
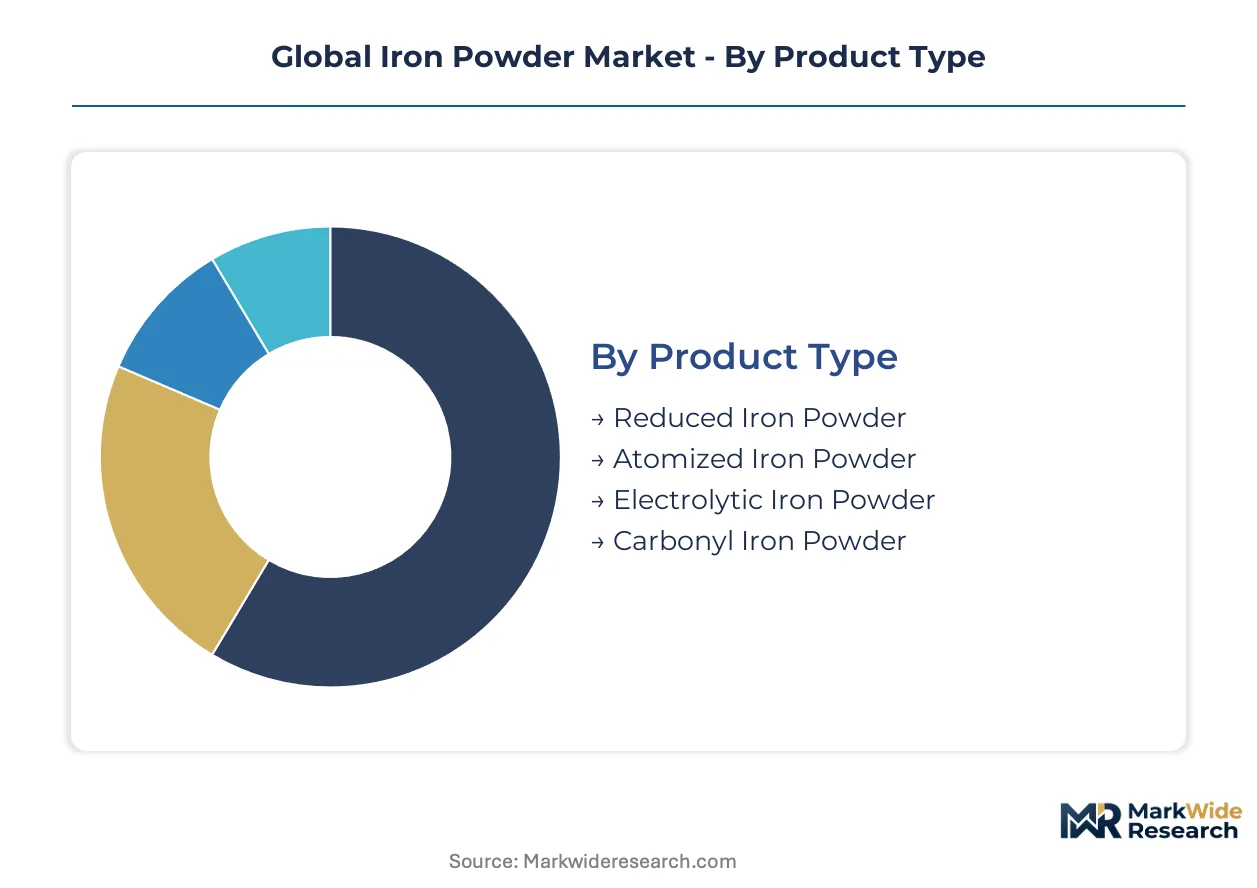
Iron powder grades diverge sharply in production economics and qualification requirements. Procurement teams must match particle morphology to specific forming processes while tracking embodied carbon credentials across supplier bases.
Product Type:
Capital intensity separates these routes by an order of magnitude, with thermal decomposition and electrolytic deposition requiring specialized reactor infrastructure versus conventional reduction furnaces.
- Reduced Iron Powder:Sponge iron reduction dominates automotive press-and-sinter volumes through Höganäs AB's integrated Swedish operations. German drivetrain suppliers rely on this grade for hollow gear components under EU Green Deal Scope 3 thresholds.
- Atomized Iron Powder:Molten metal atomization commands premium positioning in additive manufacturing feedstock where laser powder bed fusion tolerances tighten. India's PLI scheme for specialty steel is accelerating domestic water-atomization capacity for electric motor lamination supply chains.
- Electrolytic Iron Powder:Electrodeposition yields ultra-purity grades for high-frequency magnetic cores in French and Italian electronics fabrication.
- Carbonyl Iron Powder:Thermal decomposition of iron pentacarbonyl restricts output to sub-10 micrometer electromagnetic applications in radar and telecommunications hardware.
Most installed capacity flows through reduced iron powder. Expansion is steepest in atomized iron powder.
Application:
Customer technical requirements determine specification windows, with automotive fatigue standards imposing the tightest particle size distributions.
- Powder Metallurgy:Near-net-shape sintering displaces machined bar stock in Detroit OEM drivetrain lightweighting programs under NHTSA fuel economy mandates. German press-and-sinter networks report acute shortages of hydrogen-nitrogen atmosphere technicians.
- Magnetic Materials:Motor lamination stacks and high-frequency cores drive specification differentiation between carbonyl and electrolytic grades. REACH cobalt restrictions are forcing alloy reformulations across French and Italian core producers ahead of enforcement deadlines.
- Welding:Flux-cored wire formulations consume coarse atomized fractions for arc stability in structural steel fabrication.
- Chemical Industry:Reduction chemistry and catalyst substrates utilize reactive iron surfaces in hydrogenation processes.
- Electronics:Miniaturized inductors and EMI shielding demand sub-20 micrometer spherical morphology.
Volume concentration sits with powder metallurgy. Magnetic materials are climbing the fastest as electrification redesigns motor specifications.
End User Industry:
Procurement scale and qualification duration vary dramatically across these verticals, with automotive master service agreements extending to multi-year frameworks.
- Automotive Suppliers:Tier-one drivetrain specialists in Stuttgart and Munich bundle iron powder, copper premix, and lubricant purchases under volume-tiered single-source contracts. Three buyers now account for the majority of domestic press-and-sinter offtake.
- Electrical Manufacturers:Motor lamination and transformer core producers specify low-loss grades with strict oxide content limits for efficiency certification.
- Construction Firms:Structural welding and soil remediation applications consume coarse reduced grades with lower purity tolerances.
- Chemical Producers:Batch hydrogenation processes require consistent reactivity profiles from sponge iron feedstock.
- Electronics Fabricators:Miniaturized component producers in Japan face 18-month ISO 22068 qualification timelines that compress product development cycles.
Automotive suppliers anchor procurement volume. Electrical manufacturers show the steepest specification tightening.
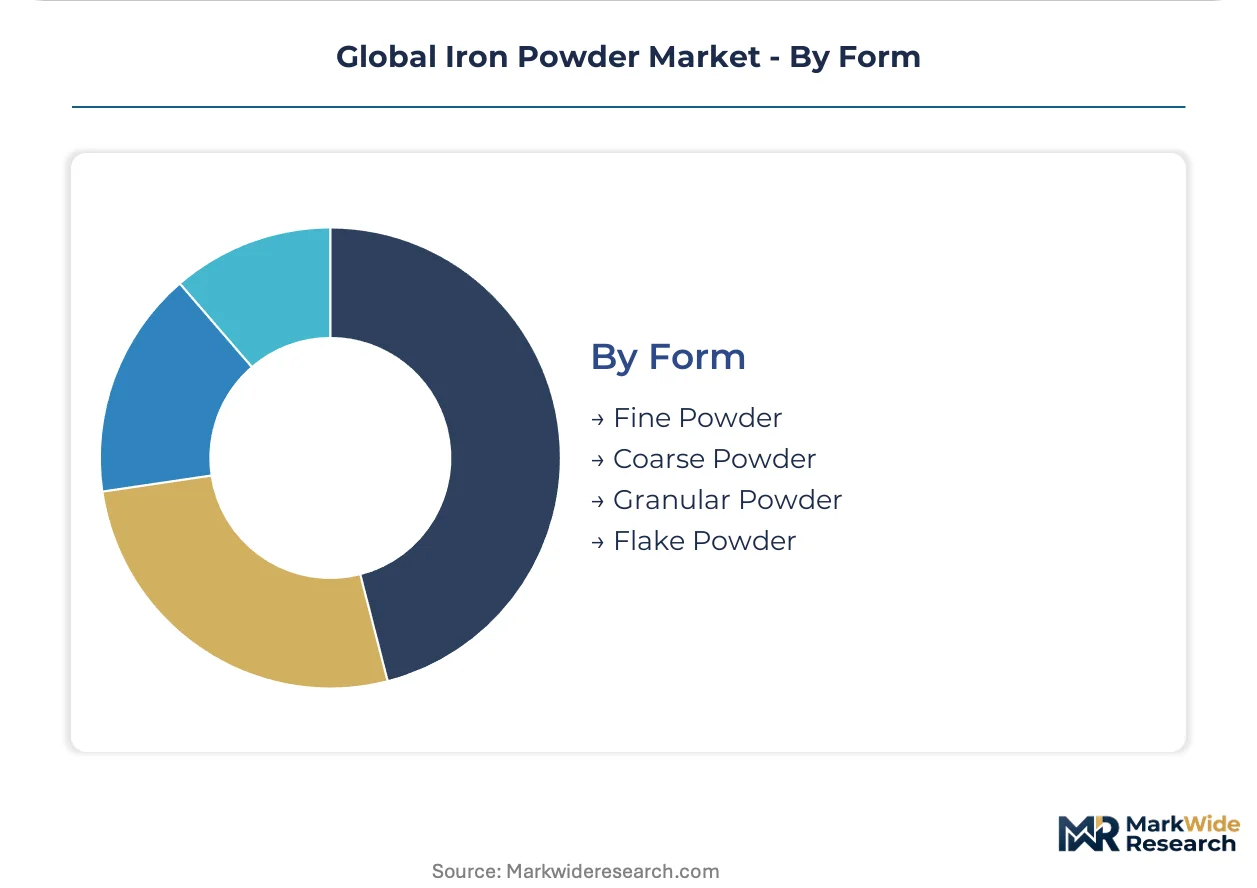
Form:
Particle geometry directly determines flow characteristics in automated pressing operations and packing density in thermal processing.
- Fine Powder:Sub-45 micrometer fractions enable thin-wall sintering and high-surface-area catalytic applications. Laser powder bed fusion in Germany's medical implant sector is pulling spherical fine grades into orthopedic supply chains.
- Coarse Powder:150-plus micrometer fractions serve filtration media and heavy-section structural components where permeability matters.
- Granular Powder:Controlled agglomeration improves flowability in high-speed pressing operations without lubricant overload.
- Flake Powder:Aspect ratio engineering delivers directional electromagnetic properties in shielding and absorber applications.
Granular powder carries the most installed pressing capacity. Fine powder is expanding most quickly as additive manufacturing tolerances tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron powder manufacturing originated in Sweden's Höganäs district during the early twentieth century, establishing the sponge iron reduction route that still supplies European automotive chains. Production networks now span three continents with distinct regulatory and demand profiles.
Germany
Stuttgart and Munich host concentrated press-and-sinter operations serving tier-one drivetrain suppliers. EU Green Deal embodied carbon mandates are forcing requalification of ferrous feedstock bases against Scope 3 thresholds. Three buyers now account for the majority of domestic powder offtake through multi-year master service agreements.
Japan
Electric motor lamination stacks and high-frequency magnetic cores drive specification differentiation between carbonyl and electrolytic grades. METI coordinates domestic powder standards through JIS H 2111, aligning with automotive quality mandates from NHTSA and ECHA compliance requirements. Electronics fabricators in the Kanto region face 18-month ISO 22068 qualification timelines.
India
Domestic additive manufacturing and electric motor supply chains are expanding rapidly. The PLI scheme for specialty steel is attracting joint venture investment for atomized powder production. Water atomization lines are being retrofitted with high-pressure cooling systems to capture price-sensitive tooling demand.
United States
Detroit OEMs are adopting hollow sintered drivetrain components under NHTSA fuel economy standards. The EPA enforces particulate matter thresholds at powder production facilities. Press-and-sinter networks in the Midwest report capacity constraints as lightweighting mandates accelerate.
Sweden
Sponge iron reduction capacity dominates certified low-carbon powder feedstock for European automotive suppliers seeking Green Deal compliance. Pilot plants in northern Sweden are integrating green hydrogen into reduction routes. This concentration creates single-source risk for buyers dependent on verified low-emission grades.
Global Iron Powder Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct technology vectors in iron powder supply. Integrated reduction facilities command cost advantages in automotive press-and-sinter volumes, while specialized atomization houses capture premium positioning in additive manufacturing feedstock. Three archetypes dominate: vertically integrated sponge iron operators, regional press-and-sinter networks, and specialty electromagnetic powder specialists. Competitive moves concentrate on hydrogen-based process conversion and multi-year procurement contract consolidation.
Among Nordic integrated producers, Höganäs AB exemplifies the low-carbon reduction archetype through its Swedish sponge iron operations. JFE Steel Corporation anchors Asian supply positioning from its eastern Japan atomization complex. GKN Powder Metallurgy sits within the regional network tier, competing via dense press-and-sister infrastructure across Germany and North America.
| Leading Market Players |
|---|
| Höganäs AB |
| Rio Tinto Metal Powders |
| JFE Steel Corporation |
| Kobe Steel |
| Industrial Metal Powders (India) Pvt. Ltd. |
| BASF SE |
| GKN Powder Metallurgy |
| Reade International Corporation |
| American Elements |
| Others |
Supply & Pricing Matrix
Sintering furnace operators capable of hydrogen-nitrogen atmosphere control command wage premiums in Stuttgart and Munich that widen the spread between certified low-carbon powder grades and standard reduced iron tiers. Labor scarcity in these German press-and-sinter clusters forces buyers to absorb higher logistics costs for qualified technical staff, compressing margins on economy-grade feedstock while premium atomized powder carries through cost-plus structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates carbonyl iron powder for electromagnetic applications from atomized grades for additive manufacturing and reduced powder for automotive press-and-sinter. Price differentiation hinges on embodied carbon certification under EU Green Deal Scope 3 thresholds and particle sphericity tolerances for laser powder bed fusion. Cost compression in standard reduced powder is intensifying because Swedish sponge iron capacity dominates certified low-carbon feedstock. Tier-one automotive suppliers in Germany show least price sensitivity due to multi-year master service agreements, while domestic tooling markets in India exhibit highest elasticity to atomized powder surcharges.
Supply Chain Analysis
Workforce availability for metallurgical technicians in Germany, Japan, and Sweden constrains capacity expansion across sponge iron reduction and atomization routes. Supply concentrates in Sweden for certified low-carbon feedstock, Japan for carbonyl and electrolytic grades, and India for emerging water-atomization capacity. Raw material dependencies draw from iron ore pellets, shredded automotive scrap, and iron pentacarbonyl precursor chemicals. Single-source vulnerability runs through Höganäs AB's integrated Swedish operations for Green Deal-compliant powder. Distribution runs through regional press-and-sinter networks in Germany and North America, with direct mill relationships for large automotive tier-ones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's carbon border adjustment mechanism in Europe against India's PLI scheme for specialty steel creates a geographic-arbitrage window for powder producers to site reduction capacity where regulatory compliance costs diverge most sharply.
For Market Incumbents: Deepen captive supply of sponge iron feedstock through backward integration into Swedish or Indian reduction assets to defend against hydrogen-based direct reduction entrants. Secure multi-year offtake contracts with Stuttgart and Munich automotive clusters before qualification timelines compress further. The priority lever sits with locking in sintering furnace operator training pipelines to preempt German metallurgical technician scarcity. For New Entrants and Emerging Players: REACH substance restrictions in Europe open a window for cobalt-free iron grade specialists to capture French and Italian magnetic core reformulation demand ahead of enforcement deadlines. Target India's electric motor lamination supply chain through water-atomization joint ventures under the PLI scheme. The most penetrable segment is price-sensitive additive manufacturing feedstock in domestic tooling markets where gas atomization incumbents carry cost disadvantages. For Investors and Strategic Acquirers: Tier-one automotive suppliers are the most active acquirer in this space, seeking to secure ferrous feedstock for electrification-driven motor lamination stacks. Long-term viability centers on hydrogen-based direct reduction routes positioned for EU carbon border adjustment exemptions. The acquisition target archetype is mid-cap atomization houses with spherical powder capabilities for laser powder bed fusion. Watch for scrap price volatility spikes as the inflection signal for margin compression across Japanese atomized powder producers.| Strategic Initiative | Industry Significance |
|---|---|
| Green Hydrogen Integration | Pilot plants in northern Sweden position early movers for EU carbon border adjustment exemptions. |
| Water Atomization Retrofit | Indian producers capture price-sensitive additive manufacturing demand in domestic tooling markets. |
| Cobalt-Free Alloy Reformulation | French and Italian magnetic core producers secure automotive qualification continuity ahead of REACH deadlines. |
| Multi-Year Master Service Agreements | Three Stuttgart and Munich buyers now account for majority of domestic press-and-sinter powder offtake. |
| Sintering Technician Training Pipeline | German press-and-sinter networks address acute hydrogen-nitrogen atmosphere operator shortages. |
Research Methodology
Multiple input streams — trade data reconciliation, primary interviews with powder metallurgy procurement leads and sintering furnace operators, and secondary validation through JIS H 2111 standards documentation and EU Green Deal regulatory filings — were reconciled to construct market size estimates. Stakeholder roles included tier-one automotive supplier procurement directors, METI coordination officials, atomization plant managers in India, and REACH compliance officers at French magnetic core producers. Secondary sources encompassed customs records for iron powder trade flows, SEC filings from integrated steel producers, EPA particulate matter enforcement data, and automotive production databases from IHS Markit. Bottom-up capacity modeling and top-down demand triangulation from end-use verticals were cross-checked for consistency.
Data-stream reconciliation across the projection horizon applied segment-specific growth drivers to derive volume and value trajectories. Segmentation dimensions modeled include production route (reduced, atomized, electrolytic, carbonyl), end-use application (powder metallurgy, magnetic materials, welding, chemical, electronics), particle size form, and regional production hub. CAGRs were computed from annualized growth rates across the modeling period. Industry-specific forecast inputs incorporated NHTSA fuel economy mandate compliance timelines, EU carbon border adjustment phase-in schedules, and India's PLI scheme disbursement triggers for specialty steel.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt scrap price spikes or accelerated REACH substance restriction enforcement. Projections reflect assumptions regarding hydrogen-based direct reduction scale-up rates and automotive lightweighting program continuity. Material deviation in EU Green Deal Scope 3 threshold calibration or German metallurgical technician training pipeline completion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Asia-Pacific Magnet Wire Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Samarium Cobalt Magnets Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
Magnet Market
Magnetic Materials
Magnetic Materials Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Carbonyl Iron Powder Market
Magnetic Materials
Global Non-Oriented Electrical Steel Market
Magnetic Materials
Ferroboron Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Global Electrical Steel Sheet Market