
 Magnetic Materials Market | 2026-2036
Magnetic Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Materials Market Intelligence
Buyer concentration among large automotive and electronics original equipment manufacturers is pivoting procurement strategies towards long-term supply agreements for critical rare earth magnets. Shin-Etsu Chemical Co., Ltd. dominates the high-performance neodymium magnet space through its patented production processes. TDK Corporation leverages its expertise in ferrites and electronic components to serve the consumer electronics sector. Arnold Magnetic Technologies specializes in custom-engineered magnetic assemblies for aerospace and defense applications.
Magnetic materials are substances that exhibit magnetic properties, classified by their response to an applied magnetic field. This includes ferrites, which are ceramic iron oxide compounds, and rare earth magnets, offering high magnetic flux density. Permanent magnets, especially rare earth types, command high value due to their use in electric motors within the automotive industry. Soft magnets are vital for transformers and data storage devices, representing a mature and high-volume market segment.
The European Union's RoHS directive restricts hazardous substances in electronic equipment, affecting the composition of magnetic components. In the United States, initiatives to secure domestic supply chains for critical minerals, including those for magnets, are guided by government policy and impact sourcing decisions. Navigating the divergent material regulations and geopolitical supply risks will be the central challenge for downstream manufacturers.
Market Dynamics
The central structural force shaping the magnetic materials market is the geopolitical contest over rare earth element supply chains. This dynamic pits the automotive industry's urgent demand for high-performance magnets against the profound supply concentration within China.
Growth Catalysts
- Electric Vehicle Powertrains:Demand for high-performance neodymium-iron-boron (NdFeB) magnets is accelerating due to their critical role in compact, high-efficiency electric motors for battery electric vehicles and hybrids.
- Government Supply Chain Initiatives:Policies in the United States, such as those guided by the Inflation Reduction Act (IRA), incentivize the development of domestic rare earth mining, processing, and magnet manufacturing capabilities.
- Renewable Energy Expansion:The construction of direct-drive wind turbines requires large permanent magnets, creating a significant, high-volume demand stream for materials capable of operating under high mechanical stress.
Market Restraints
- Rare Earth Price Volatility:The market is subject to significant price fluctuations for key rare earth inputs like neodymium and dysprosium, which are largely controlled by Chinese production quotas and export policies.
- Substitution Threats:The high cost and supply risk of rare earth magnets drive research into alternative motor technologies, including switched reluctance motors and induction motors that do not require permanent magnets.
- Regulatory Compliance Burdens:European Union directives like RoHS and REACH restrict the use of certain substances in magnetic materials, increasing testing and reformulation costs for manufacturers selling into the EU.
Strategic Opportunities
- Magnet Recycling Infrastructure:Establishing closed-loop recycling systems in Europe and North America to recover rare earth elements from end-of-life products presents a major opportunity to create a secure, secondary source of supply.
- Rare-Earth-Free Magnet Development:Commercializing new permanent magnet compositions that reduce or eliminate the need for critical rare earths offers a path to mitigate supply chain risks and appeal to cost-sensitive applications.
- Medical Device Applications:There is an expanding need for custom-engineered magnetic assemblies in advanced medical equipment, including magnetic resonance imaging (MRI) systems, sensors, and targeted drug delivery devices.
Industry Challenges
- Intellectual Property Navigation:The production of high-performance sintered NdFeB magnets is protected by a complex web of patents, creating high barriers to entry for new manufacturers outside of established licensing agreements.
- High Capital Investment:Building new, vertically integrated magnet production facilities, from rare earth separation to final magnet finishing, requires substantial upfront capital expenditure and long lead times.
- Specialized Talent Scarcity:A global shortage of metallurgists, materials scientists, and process engineers with expertise in rare earth processing and magnet manufacturing hinders capacity expansion outside of Asia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Materials Market |
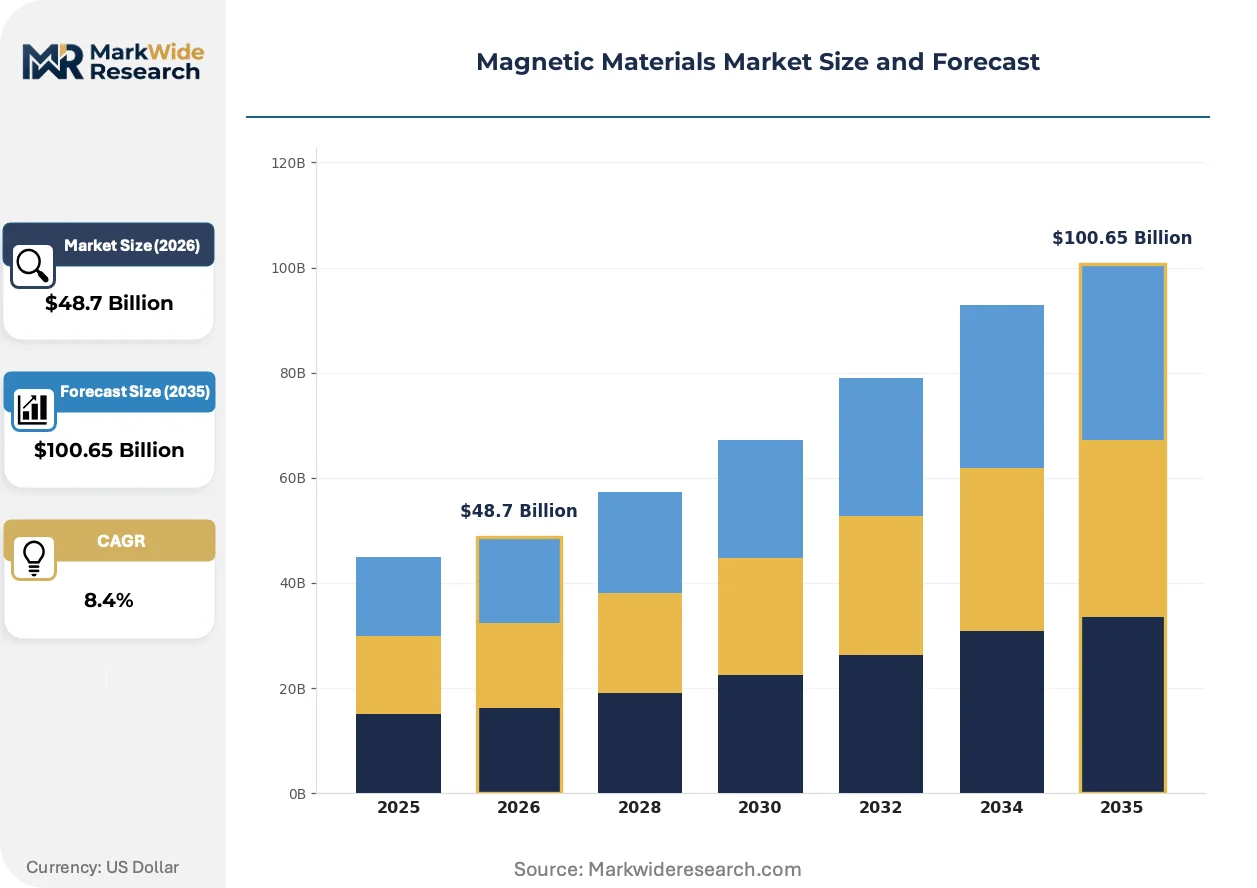
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Magnets, Soft Magnets, Soft Magnetic Composites, Rare Earth Magnets Application: Electric Motors, Transformers, Magnetic Sensors, Data Storage Devices End User: Automotive Industry, Consumer Electronics, Aerospace Sector, Industrial Machinery Component: Alloy Materials, Ferrites, Nanomaterials, Magnetic Ceramics |
| Companies Covered | Arnold Magnetic Technologies, Ningbo Keningda Industry Co., Ltd., Shin-Etsu Chemical Co., Ltd., Electron Energy Corporation, Lingyi iTECH (Guangdong) Company, Hitachi Metals Ltd., DMEGC Magnetic Ltd., Vacuumschmelze GmbH & Co. KG, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Materials Market Strategic Shifts & Innovations
Innovation in the magnetic materials sector focuses on mitigating supply chain vulnerabilities while simultaneously pushing the performance envelope for next-generation electronics and electric motors. Material science advancements and novel manufacturing processes are central to addressing these dual market pressures.
Advanced Manufacturing Processes
Grain boundary diffusion (GBD) technology enables the precise application of heavy rare earth elements like dysprosium onto neodymium magnets, enhancing their thermal stability. Automotive and industrial motor manufacturers are adopting components made with this process to improve performance and efficiency. This manufacturing advancement is consolidating the competitive landscape around process-level intellectual property, shifting focus from raw material control to production expertise.
Strategic Onshoring Policies
The US Inflation Reduction Act (IRA) includes provisions that directly incentivize domestic production of critical materials for electric vehicles. This policy has a direct industrial consequence, spurring investment in North American rare earth processing and magnet manufacturing facilities. The automotive supply chain is the most affected segment, with vehicle OEMs actively seeking to qualify new regional suppliers to comply with the IRA's stringent sourcing rules.
Evolving Procurement Models
A clear shift is underway from transactional, spot-market purchasing to the establishment of long-term supply agreements for critical magnets. This change directly impacts magnet producers, favoring those with the scale and financial stability to commit to multi-year offtake contracts. The electric vehicle industry is where this trend is most visible, as automakers lock in future supply to de-risk their ambitious production roadmaps.
Magnetic Materials Market Segmentation
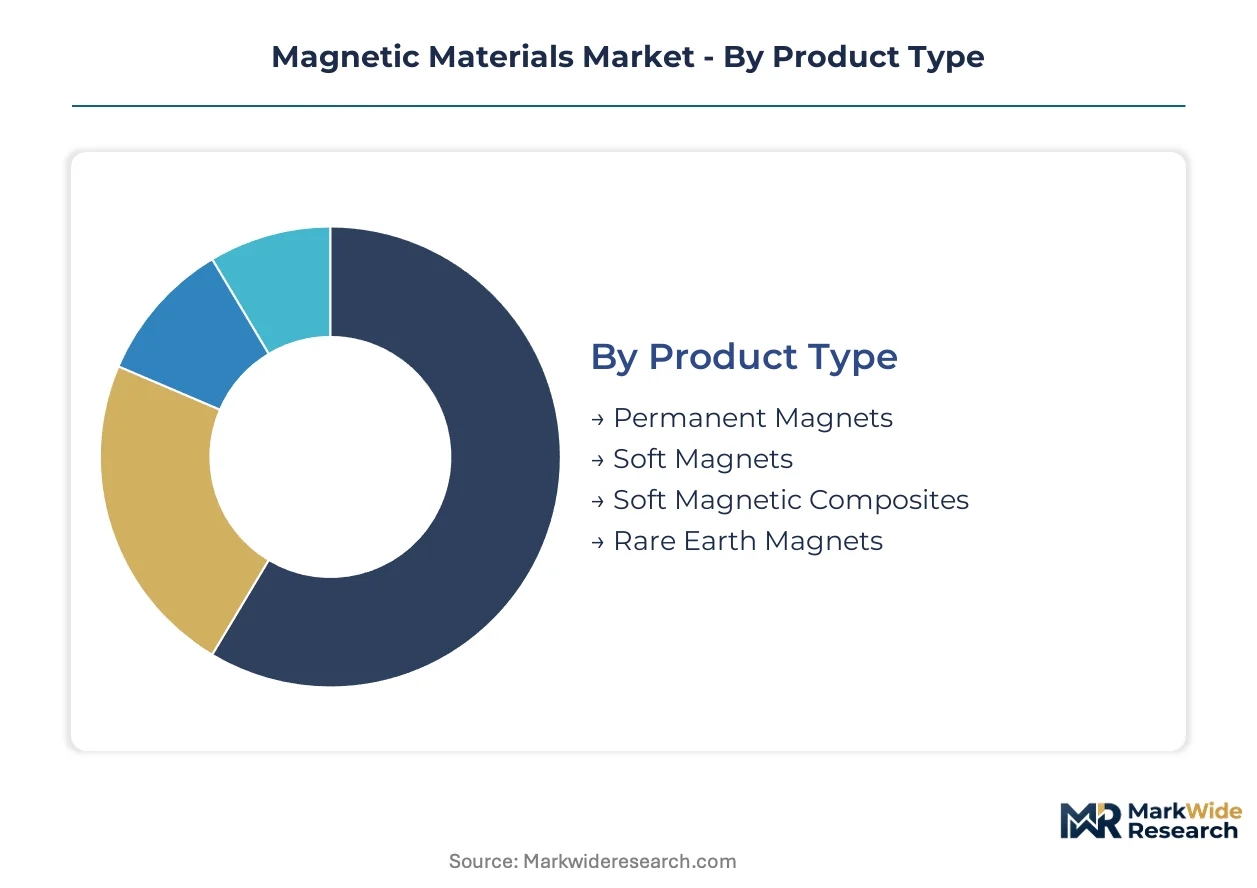
Understanding the distinct segments within the magnetic materials market is crucial for navigating its complex value chains and diverse performance requirements. This segmentation highlights the varying demands across different product types, applications, end-users, and core components, influencing strategic investments and material development.
Product Type:
The magnetic materials market stratifies across high-volume commodity products and premium, performance-driven segments.
- Rare Earth Magnets:These permanent magnets, primarily neodymium-iron-boron (NdFeB), offer exceptional magnetic strength and thermal stability. Demand concentrates within the automotive industry, where they are critical for efficient electric vehicle powertrains.
- Permanent Magnets:These materials retain their magnetic properties after magnetization, including rare earth and ferrite types. The industrial machinery sector drives significant demand for these magnets in motors and generators, requiring consistent performance.
- Soft Magnets:Soft magnets are easily magnetized and demagnetized, primarily used in transformers and inductors. The data storage industry relies on these materials for efficient operation.
- Soft Magnetic Composites:These materials combine magnetic particles with a binder, offering design flexibility for complex shapes. Their use in power electronics is expanding due to improved high-frequency performance.
Today's leader: Permanent Magnets. Tomorrow's challenger: Rare Earth Magnets.
Application:
Magnetic material applications range from high-power industrial uses to precision consumer electronics.
- Electric Motors:Electric motors convert electrical energy into mechanical energy, heavily utilizing permanent magnets for efficiency. The automotive sector's shift to electric vehicles represents the fastest-growing trajectory for this application.
- Transformers:Transformers efficiently transfer electrical power between circuits using soft magnetic cores to minimize energy loss. Global energy infrastructure projects maintain consistent demand for these components, ensuring grid stability.
- Data Storage Devices:Magnetic materials are fundamental to hard disk drives and magnetic tapes for reliable data storage. The enterprise data center market sustains demand for these traditional storage solutions.
- Magnetic Sensors:These sensors detect magnetic fields, enabling precise measurements in various control systems. Industrial automation systems frequently integrate magnetic sensors for positional feedback.
Demand is highest in Transformers, but Electric Motors are expanding most quickly.
End User:
End-user industries dictate both the performance specifications and procurement volumes for magnetic materials.
- Automotive Industry:The automotive industry requires high-performance magnets for electric powertrains, sensors, and comfort systems. Government supply chain initiatives, such as the US Inflation Reduction Act, significantly influence sourcing decisions for this sector.
- Consumer Electronics:This sector uses magnetic materials in speakers, motors, and data storage for devices like smartphones and laptops. Miniaturization trends and energy efficiency regulations, like EU RoHS, drive material innovation.
- Industrial Machinery:Industrial machinery employs magnetic components in motors, generators, and lifting equipment. The global manufacturing base provides a steady demand for robust magnetic solutions.
- Aerospace Sector:The aerospace sector utilizes custom-engineered magnetic assemblies for avionics, sensors, and control systems. High reliability and extreme operating conditions define material requirements for these applications.
The market's future hinges on the Automotive Industry, with Industrial Machinery providing stability.
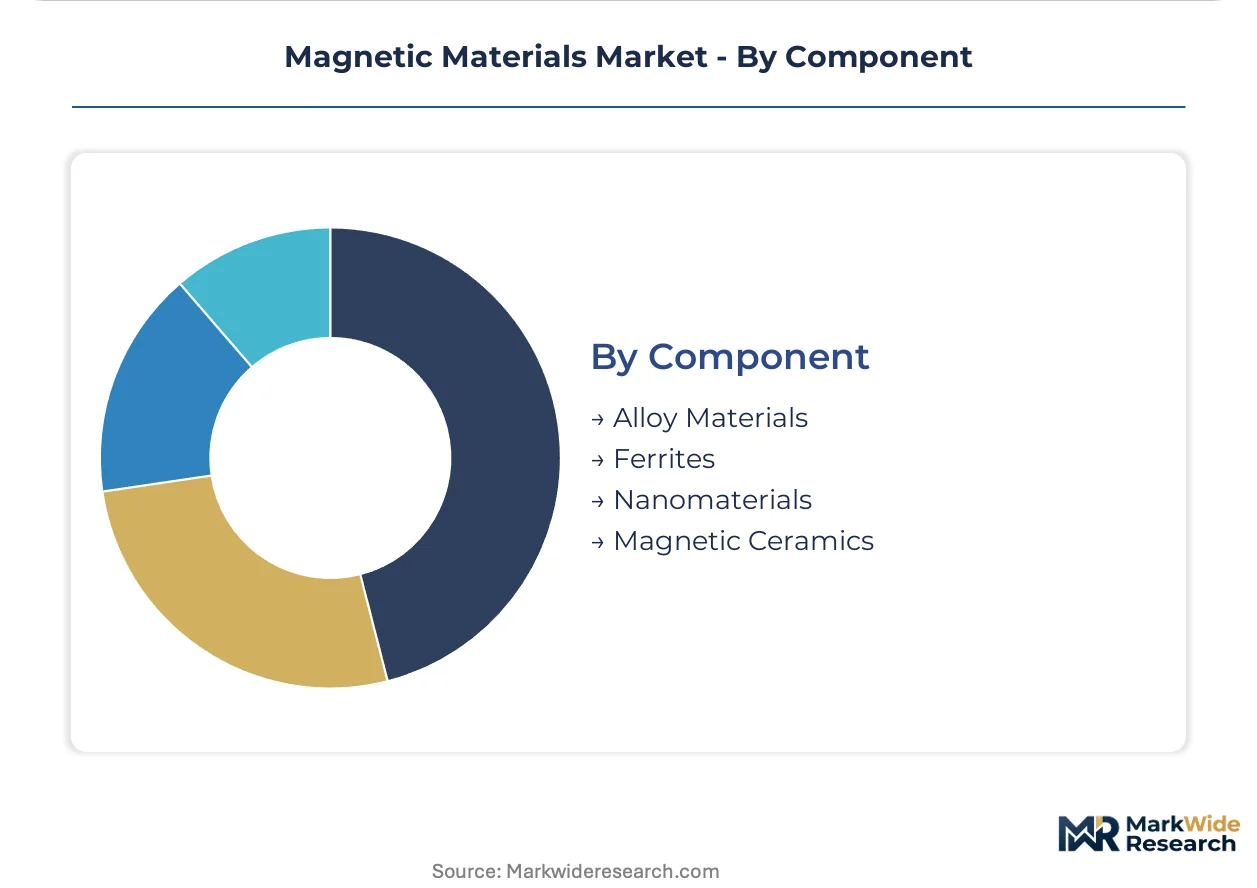
Component:
The availability and cost of raw material components directly influence the magnetic materials supply chain.
- Ferrites:Ferrites are ceramic compounds of iron oxide with other metals, offering cost-effective magnetic properties. Their widespread use in consumer electronics and power applications ensures consistent, high-volume demand.
- Alloy Materials:These materials, including Alnico and SmCo, are metal mixtures designed for specific magnetic performance characteristics. Aerospace and defense applications rely on their specialized properties for critical systems.
- Nanomaterials:Nanomaterials offer enhanced magnetic properties at a nanoscale, enabling miniaturization and improved performance. Research into advanced medical devices explores their potential for targeted therapies.
- Magnetic Ceramics:Magnetic ceramics, often ferrites, provide insulation and magnetic properties for high-frequency applications. The telecommunications infrastructure sector uses these components in filters and inductors.
Innovation is driving Nanomaterials, while Ferrites remain foundational.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized talent concentration in materials science and rare earth processing anchors magnetic materials production in key Asian economies. These regions foster the engineering expertise necessary for advanced magnet manufacturing. Geopolitical factors and strategic industrial policies increasingly influence the global distribution of this critical supply chain.
China
China's extensive rare earth reserves and processing capabilities drive its significant demand for magnetic materials in electric vehicles and consumer electronics. The nation's dual carbon goals promote the use of high-efficiency motors for energy conservation. Industrial clusters in Ganxian, Jiangxi Province, concentrate rare earth mining and separation, supporting the global magnet supply chain.
United States
The United States prioritizes domestic production of high-performance magnets for electric vehicle powertrains and defense applications. The Inflation Reduction Act (IRA) provides significant incentives for North American rare earth processing and magnet manufacturing. Texas is emerging as a hub for EV production, attracting investment in localized magnet facilities to meet sourcing requirements.
Germany
Germany's robust automotive industry, particularly its pivot to electric mobility, fuels strong demand for permanent magnets in motors and sensors. Compliance with the EU RoHS directive influences material selection and recycling practices for electronic components. Bavaria hosts significant automotive R&D and industrial machinery manufacturers, requiring advanced magnetic solutions.
Japan
Japan maintains a leadership position in high-performance magnet technology, particularly for consumer electronics and industrial automation. The Ministry of Economy, Trade and Industry (METI) supports strategic material research and development to secure future supply. Tokyo's dense electronics innovation ecosystem drives demand for miniaturized and efficient magnetic components.
South Korea
South Korea's advanced electronics manufacturing and growing electric vehicle sector create substantial demand for magnetic materials. The K-Battery Strategy supports the development of critical components, including magnets, for the EV supply chain. Gyeonggi Province, a major industrial region, houses numerous semiconductor, display, and EV component manufacturers utilizing magnetic materials.
Magnetic Materials Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the magnetic materials market. The competitive landscape includes established chemical manufacturers and specialized magnetic assembly providers. Archetypes span high-performance rare earth magnet producers, broad-portfolio ferrite suppliers, and custom-engineered solution providers. Companies are engaging in strategic partnerships and capacity expansions to secure long-term supply agreements.
Shin-Etsu Chemical Co., Ltd. represents a leader in high-performance neodymium magnet production, leveraging patented processes for advanced materials. TDK Corporation exemplifies a diversified player, with expertise in ferrites and electronic components serving the consumer electronics sector. Arnold Magnetic Technologies occupies a niche in custom-engineered magnetic assemblies, providing specialized solutions for aerospace and defense applications.
| Leading Market Players |
|---|
| Arnold Magnetic Technologies |
| Ningbo Keningda Industry Co., Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| Electron Energy Corporation |
| Lingyi iTECH (Guangdong) Company |
| Hitachi Metals Ltd. |
| DMEGC Magnetic Ltd. |
| Vacuumschmelze GmbH & Co. KG |
| TDK Corporation |
| Others |
Cost & Logistics Intelligence
Automotive OEMs' procurement strategies are pivoting towards contract-based long-term offtake agreements for critical rare earth magnets. This shift directly influences pricing stability and supply chain configuration for high-performance materials.
Pricing Analysis
Contract-based long-term offtake agreements dominate for high-performance rare earth magnets, while commodity spot pricing persists for standard ferrites. Price differentiation stems from the quality grade, particularly for neodymium-iron-boron (NdFeB) magnets, and the customization level required for specialized aerospace applications. Pricing softness stems from rare earth price volatility, largely controlled by Chinese production quotas and export policies. Consumer electronics manufacturers are highly price-sensitive for standard components, while aerospace and defense sectors prioritize performance over cost.
Supply Chain Analysis
Certification and qualification gating heavily influence supply chain entry for high-performance magnets used in automotive and aerospace applications. China dominates rare earth mining and processing, with Japan and Germany leading in advanced magnet manufacturing. Neodymium, dysprosium, and iron are critical inputs for high-performance magnets. Single-source vulnerability from China creates geopolitical risk for downstream manufacturers. Direct sales and long-term supply agreements characterize distribution for high-value magnets, while distributors serve broader industrial and electronics markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magnetic materials market presents a margin-expansion story, driven by the premium pricing of high-performance rare earth magnets for electric vehicles.
For Market Incumbents:Deepen intellectual property protection around advanced manufacturing processes like grain boundary diffusion to counter substitution threats. Secure long-term rare earth supply through multi-year contracts with diversified mining partners to mitigate Chinese supply risk. Invest in capacity additions in North America and Europe, driven by government incentives like the US Inflation Reduction Act (IRA).
For New Entrants and Emerging Players:Capture niche opportunities in specialized magnetic assemblies for medical devices, where custom engineering commands premium pricing. Target the rapidly expanding electric vehicle accessory market with cost-effective ferrite solutions. Focus on innovation in rare-earth-free magnet development to appeal to cost-sensitive applications and mitigate supply chain risks.
For Investors and Strategic Acquirers:Specialized materials firms are the most active acquirers in this space, seeking assets with strong intellectual property portfolios and vertical integration capabilities. The market offers long-term viability over the next decade, propelled by electrification and renewable energy. Integrated magnet recycling infrastructure providers represent attractive acquisition targets for securing secondary supply. Investment in domestic rare earth processing outside China signals a shift in supply chain resilience.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases production scale for high-demand electric vehicle magnets. |
| Long-term Supply Agreement | Secures critical rare earth inputs, mitigating price volatility. |
| Joint Venture | Facilitates technology transfer and market access in new geographies. |
| Product Launch | Introduces innovative rare-earth-free magnets for cost-sensitive applications. |
| Geographic Expansion | Establishes manufacturing presence in regions with strong government incentives. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's automotive OEM procurement managers and magnet material scientists. This approach combines insights from electronics R&D directors and government policy advisors with secondary validation. Data sources include EU RoHS directives, US Inflation Reduction Act (IRA) documents, company annual reports, and academic research papers on magnetic materials. Bottom-up data from company disclosures and top-down market sizing ensure robust triangulation.
Rate-of-change decomposition analyzes market dynamics by volume and value across the modeling period. The analytical framework segments by product type, application, end-user, component, and magnet performance tier. Compound annual growth rates were derived from historical data trends and projected adoption rates of electric vehicles. Electric vehicle production forecasts and renewable energy installation targets serve as key industry-specific forecast inputs.
Underlying measurement precision varies by segment; rare earth magnet forecasts carry tighter precision than general ferrite projections. Forecasts reflect assumptions regarding geopolitical stability and technological advancements. Rare earth price volatility and the pace of rare-earth-free magnet development could revise projections. A model refresh is warranted upon material change in critical mineral supply policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Samarium Cobalt Magnets Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
Ferroboron Market
Magnetic Materials
Ferrite Magnet Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Superconducting Magnets Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Global Electrical Steel Sheet Market