
 Global Ceramic Inks Market | 2026-2036
Global Ceramic Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ceramic Inks Market Foresight
Digital inkjet service contracts is recalibrating how ceramic ink suppliers capture recurring revenue alongside hardware placements. Ferro Corporation leverages its pigment synthesis capabilities to anchor long-term supply agreements with tile manufacturers across North America. Torrecid Group sustains competitive positioning through integrated frit production and localized technical service networks in Spain and Italy. Zschimmer & Schwarz differentiates via specialized ink formulations for high-definition digital printing systems.
Ceramic inks comprise finely ground mineral pigments, frits, and functional additives suspended in liquid carriers, engineered to fuse with glazed ceramic surfaces during firing cycles at temperatures typically exceeding 1000°C. Water-based formulations are gaining share amid VOC restrictions, while UV curable variants serve lower-temperature substrates in decorative ceramics. Digital printing technology commands the fastest expansion trajectory, displacing screen printing in premium tile segments where short-run customization and reduced inventory risk concentrate margin pools. Solvent-based products retain volume dominance in emerging markets where equipment retrofit costs delay technology transitions.
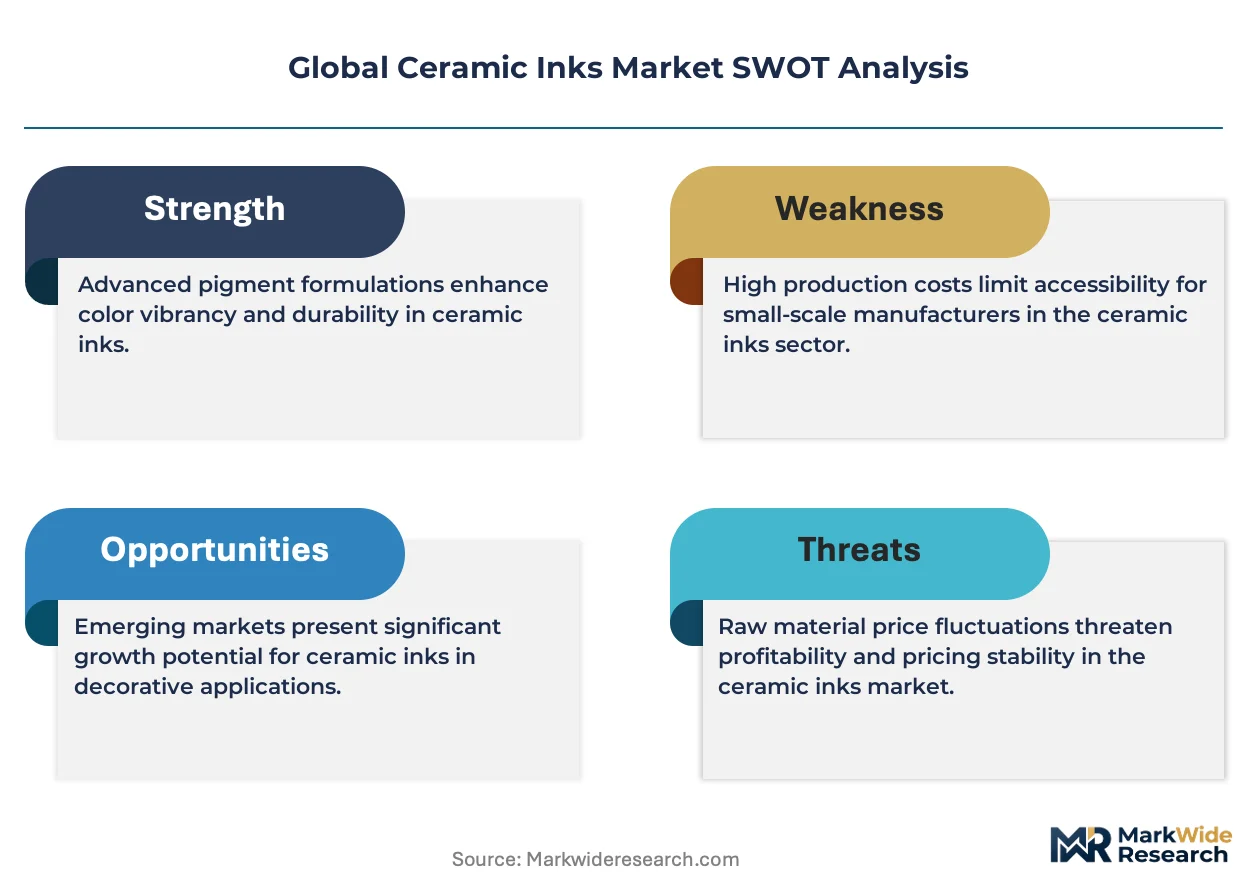
REACH in Europe and EPA regulations in the United States restrict heavy metal content in ceramic pigments, compelling reformulation investments across suppliers. China's GB standards and MEE oversight enforce comparable limits on cadmium and lead leachates from finished ceramic goods. India's BIS certification requirements for imported decorative tiles create additional compliance thresholds for ink exporters. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and maintain formulation flexibility across regional production footprints.
Market Dynamics
Digital inkjet printing systems are compressing production cycles for tile manufacturers, forcing ink suppliers to restructure service models around hardware-ink bundling rather than standalone pigment sales.
Growth Catalysts
- REACH compliance deadlines:European ceramic producers are accelerating reformulation timelines ahead of ECHA substance restriction reviews, pulling forward technical service contracts with qualified ink suppliers.
- Water-based carrier technologies:VOC emission ceilings in manufacturing clusters are redirecting capital toward aqueous ink systems that eliminate solvent recovery infrastructure.
- Sanitaryware segment expansion:Premium bathroom fixture producers in China are adopting high-definition digital decoration, expanding addressable ink volumes beyond traditional wall and floor tile applications.
Market Restraints
- Zirconium silicate supply concentration:Pigment-grade zircon feedstock originates from a narrow supplier base in South Africa and Australia, exposing ink producers to raw material availability shocks.
- Frit synthesis energy intensity:Glass frit production requires sustained furnace temperatures exceeding 1400°C, locking suppliers into natural gas cost exposure without near-term electrification pathways.
- Screen printing residual demand:Emerging market tile producers in Southeast Asia retain depreciated rotary screen equipment, delaying digital conversion and constraining premium ink penetration.
Strategic Opportunities
- India BIS certification pathways:Import compliance requirements for decorative tiles create captive demand for pre-certified ink formulations among exporters targeting Indian distribution channels.
- UV-curable ceramic systems:Low-temperature substrate decoration for glass and metal-ceramic hybrids opens adjacent applications outside traditional high-fire tile production.
- EU Green Deal industrial decarbonization incentives:Carbon border adjustment mechanisms favor domestic European ink production with verified low-emission frit synthesis processes.
Industry Challenges
- Digital press technician scarcity:Tile manufacturers face recruitment gaps for operators capable of calibrating piezoelectric printhead arrays and color management software.
- Reformulation inventory stranding:Cadmium and lead pigment phase-outs under China's GB standards and EPA heavy metal rules force write-downs of legacy stockpiles.
- Printhead-ink compatibility certification:Proprietary fluid specifications from press OEMs extend qualification timelines for third-party ink suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ceramic Inks Market |
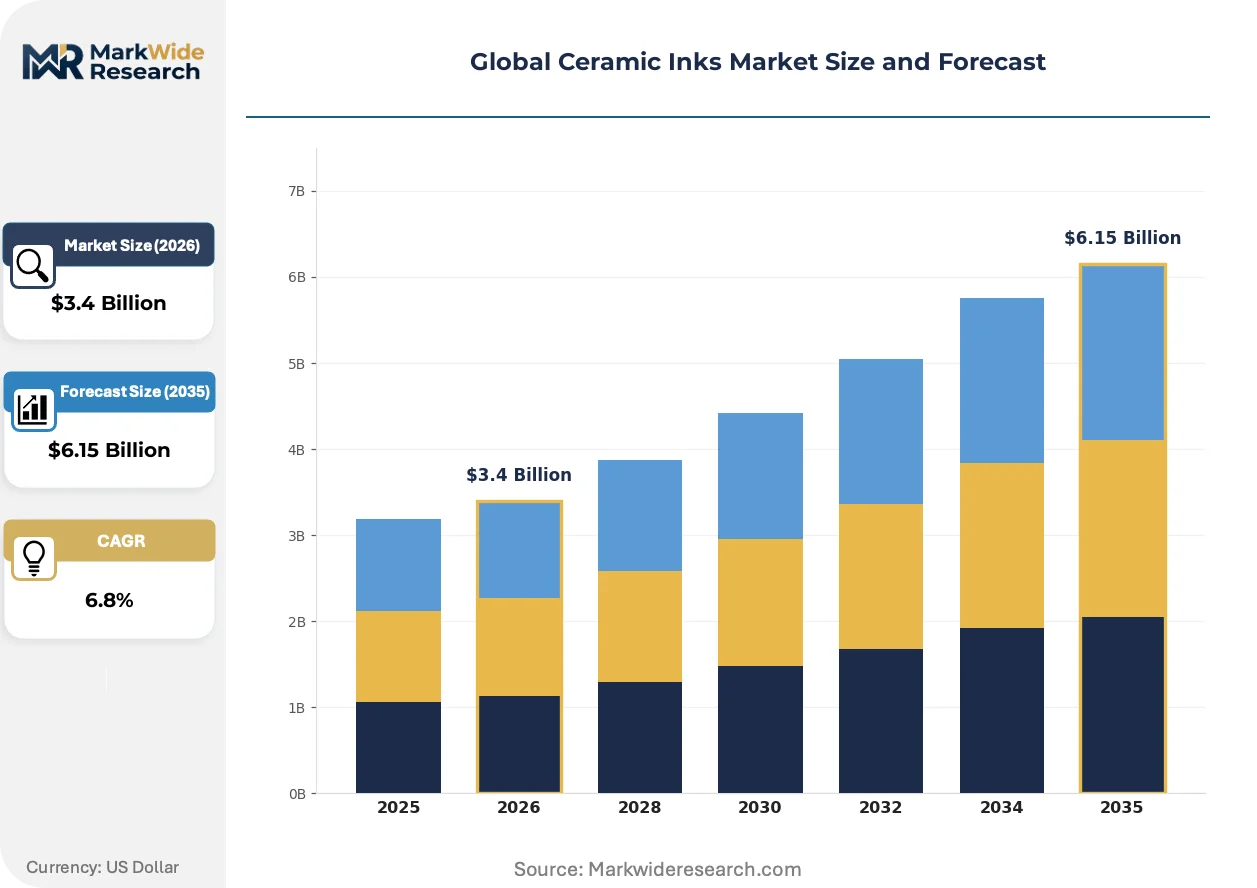
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, UV Curable, Heat-Sensitive, Epoxy, Acrylic Application: Wall Tiles, Floor Tiles, Decorative Ceramics, Tableware, Sanitaryware, Electrical Components Technology: Screen Printing, Digital Printing, Inkjet Printing, Flexography, Gravure Printing, Pad Printing End User Industry: Tile Manufacturers, Tableware Producers, Sanitaryware Fabricators, Electronics Manufacturers, Interior Decorators, Construction Firms |
| Companies Covered | Ferro Corporation, Torrecid Group, Zschimmer & Schwarz, Esmalglass-Itaca Grupo, Fritta, Colorobbia Holdings, Sun Chemical, Kao Chimigraf, Sicer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ceramic Inks Market Shifts & Advancements
Formulation chemistry and hardware architecture are fusing into unified production systems, eroding historical boundaries between ink supply and equipment vendor relationships.
Nano-pigment dispersion technology enables single-pass digital printing at production speeds matching conventional rotary screen lines. Large-format tile producers in Italy and Spain are retrofitting existing roller kilns with inkjet modules rather than building greenfield digital plants. This convergence with legacy manufacturing assets is compressing capital requirements for technology transition.
REACH authorization requirements for chromium-based pigments are forcing substitution toward rare earth and cobalt alternatives across European ceramic decoration. The industrial consequence is elevated raw material cost structures and reformulation R&D cycles extending 18-24 months. Spanish frit producers are responding by vertically integrating into rare earth oxide sourcing through Moroccan mining partnerships.
Tile distributors are unbundling ink supply from equipment procurement, negotiating direct multi-year pigment contracts independent of press manufacturer financing packages. Italian buying cooperatives are consolidating regional demand to secure volume pricing on water-based formulations. This disintermediation is most visible in Emilia-Romagna, where ceramic cluster density enables collective procurement leverage against multinational ink suppliers.
Global Ceramic Inks Market Segmentation
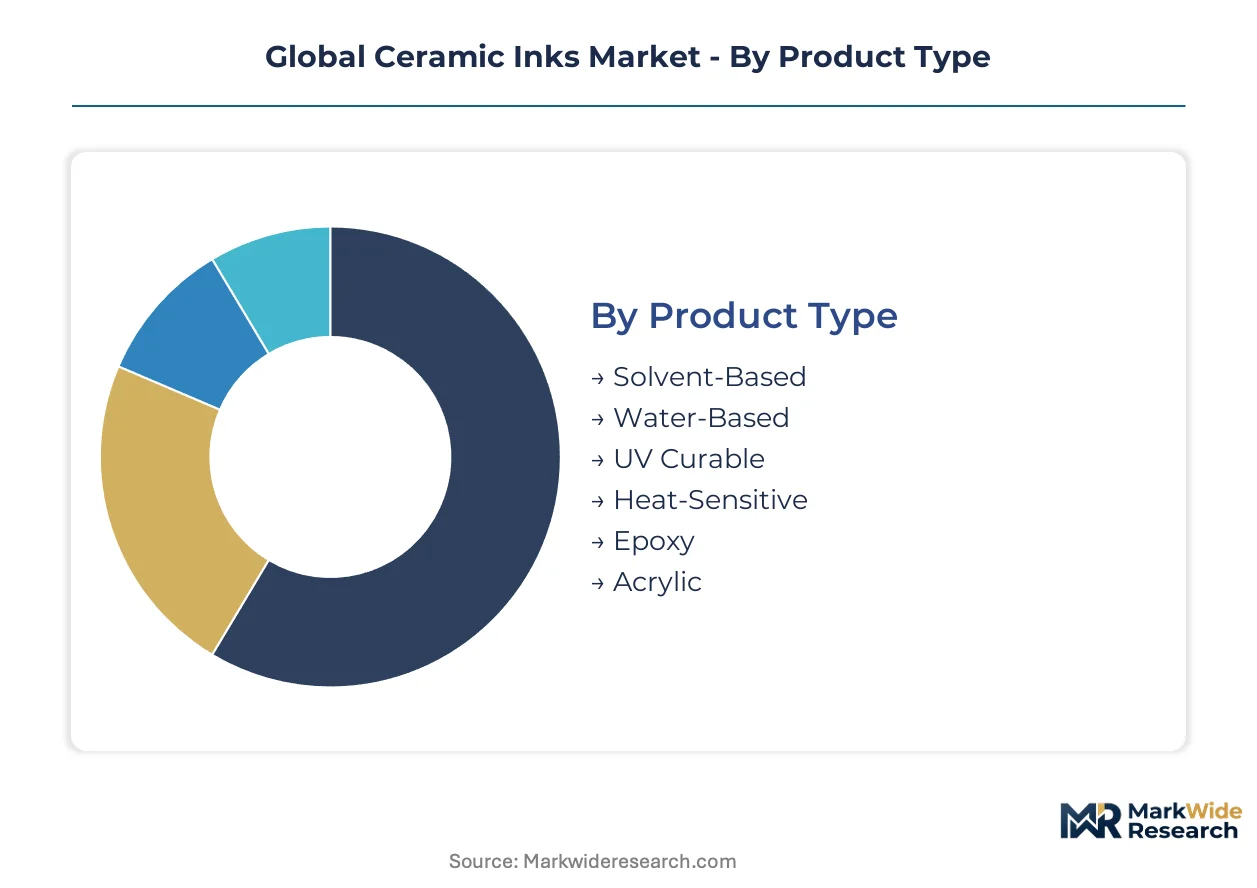
Segmentation in ceramic inks reveals how formulation chemistry, application requirements, and printing technology intersect with regulatory compliance burdens. Each dimension carries distinct certification obligations that reshape supplier-customer contracting and regional market access.
Product Type:
REACH authorization requirements and VOC emission ceilings create divergent compliance pathways across carrier chemistries, with some formulations requiring full ECHA substance registration while others qualify for simplified notification.
- Solvent-Based:Mineral spirits and glycol ether carriers suspend high-concentration pigments for rotary screen and conventional inkjet systems. Tile producers in Southeast Asia retain these formulations where solvent recovery infrastructure remains capitalized, though EPA and MEE emission rules are compressing their addressable market.
- Water-Based:Aqueous acrylic and polyurethane dispersions eliminate volatile organic compound exposure, aligning with EU Industrial Emissions Directive thresholds and China's MEE air quality enforcement in manufacturing clusters. Italian and Spanish tile clusters are retrofitting drying lines to accommodate slower evaporation profiles.
- UV Curable:Photoinitiator-acrylate systems enable instant polymerization under LED arrays, serving glass-ceramic hybrids and low-temperature substrates outside traditional kiln firing.
- Heat-Sensitive:Thermochromic pigment formulations shift color states across defined temperature bands, deployed in authentication markings and interactive tableware.
- Epoxy:Two-part systems deliver chemical resistance for electrical component encapsulation and industrial ceramic coatings.
- Acrylic:Alkali-resistant binders suit exterior facade tiles facing freeze-thaw cycling and salt spray exposure.
Water-based formulations sit at the top of the volume ranking, with UV curable variants climbing the fastest as substrate diversification accelerates.
Application:
End-use segments stratify by firing temperature requirements, surface area coverage, and decoration complexity, with premium sanitaryware commanding formulation premiums over commodity wall tile.
- Wall Tiles:High-volume square and rectangular formats dominate ink consumption, with digital printing penetration reaching saturation in Italian and Spanish production clusters while Chinese manufacturers accelerate retrofit cycles.
- Floor Tiles:Abrasion-resistant formulations with enhanced frit hardness withstand mechanical wear testing under ISO 10545-6 protocols, concentrating demand among porcelain producers.
- Decorative Ceramics:Artisan pottery and limited-edition vessels require small-batch color matching and rapid formulation turnaround, favoring regional ink blending facilities over centralized mass production.
- Tableware:Food-contact compliance under FDA 21 CFR 175.300 and EFSA migration limits restricts pigment selection to certified cobalt blues and zirconium-based encapsulates.
- Sanitaryware:Vitreous china and fireclay fixtures adopt high-definition inkjet for basin rims and toilet tank lids, expanding addressable ink volumes beyond traditional tile applications.
- Electrical Components:Ceramic substrate printing for circuit boards and insulators demands dielectric stability and precise resistivity control.
Wall tiles command the highest absolute ink volumes, with sanitaryware gaining share fastest as bathroom fixture premiumization extends digital decoration adoption.
Technology:
Print method selection determines pigment particle size distribution, viscosity ranges, and drying kinetics, with digital systems imposing tighter fluid specifications than analog alternatives.
- Screen Printing:Rotary and flatbed systems push high-viscosity pastes through mesh apertures, retaining cost advantage in long-run commodity tile production across Indonesian and Vietnamese manufacturing bases.
- Digital Printing:Piezoelectric drop-on-demand architectures enable single-pass decoration at production speeds matching conventional screen lines, compressing inventory risk for Italian large-format tile specialists.
- Inkjet Printing:Continuous and drop-on-demand variants subdivide by printhead architecture, with Kyocera and FujiFilm Dimatix specifications dictating ink fluid properties.
- Flexography:Anilox roller metering suits continuous patterns on cylindrical ceramic vessels and tableware rims.
- Gravure Printing:Engraved cylinder transfer delivers uniform ink film thickness for high-speed wall tile decoration in legacy production lines.
- Pad Printing:Silicone pad transfer enables decoration on concave sanitaryware surfaces and irregular ceramic geometries.
Screen printing retains volume leadership in absolute terms, with inkjet printing expanding most quickly as hardware costs decline and technician training programs mature.
End User Industry:
Customer concentration varies dramatically, with consolidated tile manufacturers negotiating multi-year supply agreements while fragmented tableware artisans purchase through distributor channels.
- Tile Manufacturers:Integrated producers in China's Foshan and Zibo clusters, Italy's Sassuolo district, and Spain's Castellón province consume bulk ink volumes, often qualifying for direct technical service embedding.
- Tableware Producers:Stoke-on-Trent ceramics heritage brands and Portuguese porcelain specialists prioritize lead-free formulations meeting California Proposition 65 and EU food-contact frameworks.
- Sanitaryware Fabricators:Kohler, Lixil, and Roca manufacturing networks specify color consistency across global production footprints, requiring ink suppliers to maintain batch uniformity across multiple synthesis facilities.
- Electronics Manufacturers:Murata, TDK, and AVX demand thick-film conductor and resistor pastes with precise temperature coefficient specifications.
- Interior Decorators:Custom ceramic art installations and architectural surface projects purchase through specialty distributor channels with extended color matching services.
- Construction Firms:Large-scale facade and flooring contractors source through building material wholesalers, with project-specific tinting requirements.
Tile manufacturers anchor procurement volumes, with sanitaryware fabricators driving the steepest formulation premium expansion as high-definition digital adoption penetrates bathroom fixture production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are fragmenting ceramic ink production geography, with reformulation costs and emission compliance thresholds driving capacity relocation toward jurisdictions with lower environmental enforcement intensity or subsidized greenfield development.
China
Domestic wall tile and sanitaryware manufacturers in Foshan and Zibo clusters consume substantial ink volumes as digital printing retrofit cycles accelerate. MEE enforcement of GB standards on cadmium and lead leachates is forcing pigment reformulation across Guangdong and Shandong production bases. The Yangtze River Delta ceramic belt is consolidating water-based ink adoption ahead of dual carbon goals.
Italy
Sassuolo district tile specialists drive premium ink formulation demand for large-format porcelain and high-definition decoration. REACH authorization requirements for chromium-based pigments are compelling rare earth substitution investments among Emilia-Romagna frit producers. Buying cooperatives in Modena and Reggio Emilia are consolidating regional procurement leverage against multinational suppliers.
Spain
Castellón province ceramic clusters sustain integrated frit-to-ink production chains serving Mediterranean export markets. ECHA substance restriction reviews are pulling forward technical service contracts with qualified reformulation partners. Localized technical service networks anchor supplier relationships across Valencia and Tarragona manufacturing concentrations.
United States
EPA heavy metal rules and California Proposition 65 liability exposure restrict pigment selection for tableware and food-contact applications. Southeastern tile manufacturing corridors in Georgia and Tennessee are expanding digital press installations. Ferro Corporation leverages pigment synthesis capabilities to anchor long-term supply agreements across North American distribution channels.
India
BIS certification requirements for imported decorative tiles create captive demand for pre-certified ink formulations among exporters targeting Indian distribution channels. Gujarat and Rajasthan ceramic belts are expanding wall tile capacity with hybrid screen-digital production lines. Domestic sanitaryware producers in Morbi and Thangadh are piloting high-definition inkjet decoration for premium bathroom fixtures.
Global Ceramic Inks Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise commanding premium positioning in regulated European markets while scale-driven commodity supply dominates emerging economy procurement. The vendor base concentrates around pigment synthesis capabilities, frit production integration, and digital press technical service embedding. Three archetypes dominate: backward-integrated frit-to-ink houses, pigment-specialist independents, and hardware-bundled service providers. Consolidation is accelerating through Moroccan rare earth mining partnerships and multi-year pigment contracting independent of press manufacturer financing.
Among European-headquartered specialists, Ferro Corporation, Torrecid Group, and Zschimmer & Schwarz occupy positions reflecting distinct capability anchors. Ferro exemplifies the pigment-synthesis archetype with North American manufacturing footprint. Torrecid represents integrated frit production with localized technical service density in Mediterranean markets. Zschimmer & Schwarz sits within the formulation-specialist tier serving high-definition digital printing system requirements. These three collectively illustrate how supplier positioning diverges across raw material control, production integration, and application-specific technical service depth.
| Leading Market Players |
|---|
| Ferro Corporation |
| Torrecid Group |
| Zschimmer & Schwarz |
| Esmalglass-Itaca Grupo |
| Fritta |
| Colorobbia Holdings |
| Sun Chemical |
| Kao Chimigraf |
| Sicer |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap frit producers in Spain and Italy anchor supply discipline through generational ownership structures that resist short-term margin compression, while their concentrated regional clustering enables collective procurement leverage against multinational pigment suppliers. This ownership pattern reinforces pricing power in premium water-based formulations even as Chinese state-backed producers expand capacity in commodity solvent-based tiers.
Pricing Analysis
Capacity additions in China are reshaping price floors for solvent-based ceramic inks as state-subsidized producers in Guangdong and Shandong expand output. Three-tier pricing structure across premium REACH-certified, standard ISO-grade, and economy non-certified levels stratifies the market, with certification tier and volume scale as the primary differentiation drivers. Cost compression in economy tiers is intensifying because depreciated screen-printing equipment in Southeast Asia delays digital conversion and sustains legacy ink demand. Commodity tile manufacturers in Indonesia and Vietnam exhibit highest price sensitivity, while premium sanitaryware fabricators in Italy and Germany accept formulation premiums for batch consistency guarantees.
Supply Chain Analysis
Domestic-content mandates under India's BIS certification requirements are reshaping sourcing patterns for exporters targeting Indian distribution channels, compelling ink suppliers to establish localized blending facilities or pre-certify formulations. Geographic supply concentration centers on China, Italy, and Spain, with pigment-grade zircon feedstock drawing from South African and Australian mining operations. Raw material dependencies rest on rare earth oxides, zirconium silicate, and glass frit as critical inputs. Single-source vulnerability from concentrated zircon suppliers in South Africa exposes ink producers to availability shocks. Distribution runs through direct technical service embedding with large tile manufacturers and regional distributor networks serving fragmented tableware artisans.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Ceramic Inks Market functions as a stable compounder anchored by irreplaceable formulation chemistry in high-temperature ceramic decoration, where regulatory compliance burdens create durable competitive moats around qualified suppliers.
For Market Incumbents: Anticipate cadmium and lead pigment phase-outs under China's GB standards and EPA heavy metal rules by accelerating rare earth substitution R&D and securing Moroccan mining partnerships for oxide feedstock. Prioritize technical service embedding with Italian and Spanish buying cooperatives to defend against distributor-led disintermediation. Backward integration into frit synthesis insulates margin pressure from natural gas cost volatility in European production bases. For New Entrants and Emerging Players: REACH authorization requirements in Europe open a window for specialized reformulation service providers capable of navigating ECHA substance restriction timelines for chromium-based pigment substitutions. Target India's BIS certification gap as the most penetrable geography, where pre-certified ink demand among tile exporters exceeds qualified local supply. Pursue white-label manufacturing partnerships with established frit houses rather than greenfield synthesis investments. For Investors and Strategic Acquirers: Valuations sit cheapest among pigment-synthesis independents lacking digital press technical service capabilities, as hardware-ink bundling trends concentrate margin capture with integrated service providers. Five-to-ten-year viability favors suppliers with verified low-emission frit processes eligible for EU Green Deal industrial decarbonization incentives. Monitor printhead-ink compatibility certification timelines as the inflection signal for third-party ink market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Oxide Sourcing Partnership | Moroccan mining alliances secure cobalt and rare earth feedstock for REACH-compliant pigment substitution. |
| Water-Based Formulation Capacity Expansion | Italian and Spanish retrofit investments align with EU Industrial Emissions Directive VOC thresholds. |
| BIS Pre-Certification Program | Indian compliance pathways create captive demand among exporters targeting Gujarat and Rajasthan ceramic belts. |
| Digital Press Technical Service Embedding | Kyocera and FujiFilm Dimatix compatibility certification accelerates third-party ink qualification timelines. |
| Localized Blending Facility Network | Regional tinting capabilities serve fragmented tableware artisans in Stoke-on-Trent and Portuguese porcelain clusters. |
Research Methodology
Multiple input streams — technical interviews with frit synthesis directors and ceramic ink R&D leads, procurement discussions with tile manufacturer buying cooperatives, and validation with distribution channel partners — were reconciled against trade data from Italian ceramic machinery associations, Spanish frit producer disclosures, and Chinese customs records for zirconium silicate imports. Secondary sources included ECHA substance restriction databases, EPA heavy metal rule filings, and BIS certification registries. Bottom-up volume modeling across carrier chemistry, application, and technology segments was cross-checked against top-down market sizing from regional production cluster analysis.
Historical capacity utilization patterns from Italian and Spanish ceramic belt surveys were cross-referenced against panel input from technical service directors regarding digital press retrofit cycles. Segmentation dimensions modeled encompass formulation chemistry tier, end-use application, printing technology architecture, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for technology substitution elasticities, with specific inputs including zircon feedstock price volatility indices and REACH authorization timeline probabilities for chromium-based pigments.
Revisions become necessary when ECHA substance restriction reviews accelerate beyond current timelines, when Chinese MEE enforcement intensity shifts dramatically, or when printhead OEMs alter proprietary fluid specification protocols. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory compliance cost pass-through rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
North America Printing Inks Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Food Marking Inks Market
Printing Inks
Radiation Curable Inks Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
UV Cured Inks Market
Printing Inks
Flexographic Printing Inks Market
Printing Inks
Molecular Ink Market
Printing Inks
Anti-Counterfeit Printing Ink Market
Printing Inks
Global Decorative Print Market
Printing Inks
Flexo-Ink Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
Global Conductive Inks Market
Printing Inks
Screen Printing Inks Market
Printing Inks
Functional Printing Market
Printing Inks
Ink Resins Market