
 Ferrite Market | 2026-2036
Ferrite Market Size, Share, and Industry Trends Forecast 2026-2036
Ferrite Market Analysis
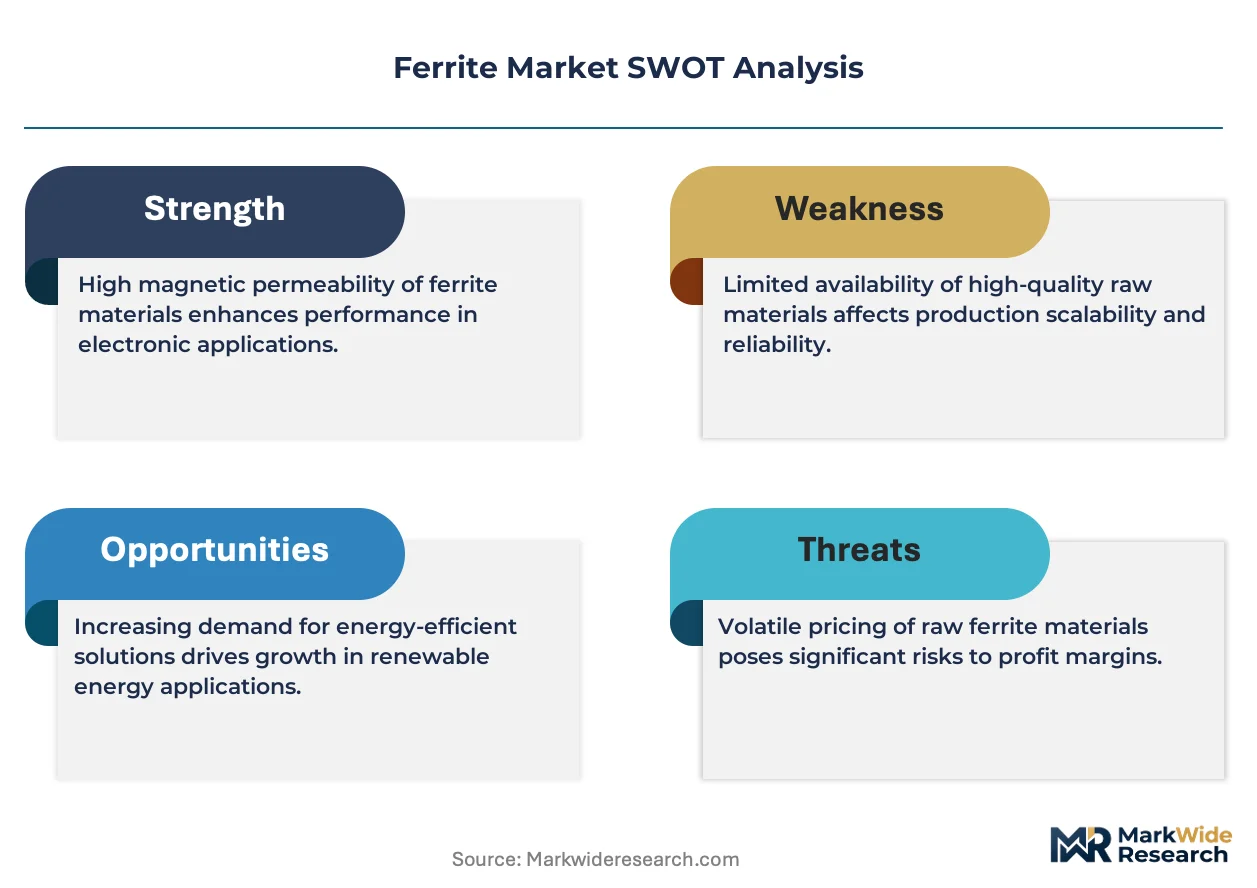
The capital-intensity divergence between integrated oxide producers and outsourced assemblers is bifurcating competitive dynamics across the ferrite supply base. TDK Corporation leverages captive powder synthesis and kiln operations to sustain margin capture from raw material through finished core. Murata Manufacturing Co., Ltd. anchors its position through extreme miniaturization expertise in multilayer chip inductors. Samsung Electro-Mechanics competes by dominating ferrite supply into captive consumer electronics and automotive module divisions.
Ferrites are ceramic compounds of iron oxide combined with metallic elements such as manganese, zinc, or nickel, sintered at temperatures exceeding 1,200°C to achieve controlled magnetic permeability and low core loss for high-frequency electromagnetic applications. Soft ferrite occupies the dominant volume position due to pervasive deployment in switch-mode power supplies and electromagnetic interference suppression cores. Hard ferrite generates lower absolute revenue but secures durable margin pools in automotive sensor and motor applications where temperature stability and corrosion resistance command specification premiums. Hexaferrite variants are gaining traction in telecommunications infrastructure as 5G base station deployments intensify demand for millimeter-wave absorbing materials.
China's MIIT enforces GB standards governing magnetic material energy efficiency classifications, while the European Union's RoHS and REACH frameworks restrict hazardous substance content in ferrite-bound electronic assemblies sold across member states. Japan's METI coordinates JIS standards that define performance benchmarks for ferrite cores deployed in automotive and industrial power electronics. Stakeholders must monitor divergence between Asian efficiency mandates and European chemical compliance thresholds when configuring regional product portfolios and qualification timelines.
Market Dynamics
China's dual carbon goals and the EU's stricter energy efficiency mandates are compressing material specifications across the ferrite supply base, forcing manufacturers to requalify powder formulations and kiln parameters against divergent regional thresholds.
Growth Catalysts
- Automotive electrification:Electric vehicle powertrain manufacturers are expanding procurement of soft ferrite cores for onboard chargers and DC-DC converters, with East Asian manufacturing clusters capturing the bulk of qualification programs.
- Telecommunications infrastructure buildout:5G base station deployments are accelerating demand for hexaferrite variants capable of millimeter-wave absorption, particularly across China, Japan, and South Korea.
- RoHS and REACH frameworks:The European Union's chemical compliance thresholds are filtering non-compliant suppliers from Western supply chains, tightening effective capacity for qualified producers.
Market Restraints
- Raw material concentration:Manganese and zinc oxide supply concentrates in Chinese mining and refining operations, exposing downstream ferrite producers to export control volatility and input cost spikes.
- Energy intensity barriers:Sintering temperatures exceeding 1,200°C require natural gas or electricity inputs that face carbon pricing exposure under the EU Green Deal and China's dual carbon enforcement.
- Technical performance ceilings:Soft ferrite permeability and core loss characteristics hit physical limits above 3 MHz, constraining deployment in next-generation gallium nitride power converters.
Strategic Opportunities
- Underpenetrated industrial motor retrofits:Hard ferrite permanent magnets remain below 15% penetration in legacy industrial motor fleets across India, where BIS efficiency standards are tightening replacement cycles.
- Convergence of ferrite and additive manufacturing:Binder jet printing of complex core geometries is enabling topology-optimized inductor designs that conventional pressing cannot achieve.
- Japan's METI automotive incentives:JIS standard harmonization with international EV platform requirements is creating qualification fast-tracks for ferrite cores meeting combined thermal and vibration benchmarks.
Industry Challenges
- Specialized kiln engineering talent:Atmospheric control expertise for precise oxygen partial pressure during sintering resides with a shrinking cohort of Japanese and German process engineers nearing retirement.
- Dual certification timeline compression:Simultaneous GB standard testing for China and REACH dossier preparation for Europe extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferrite Market |
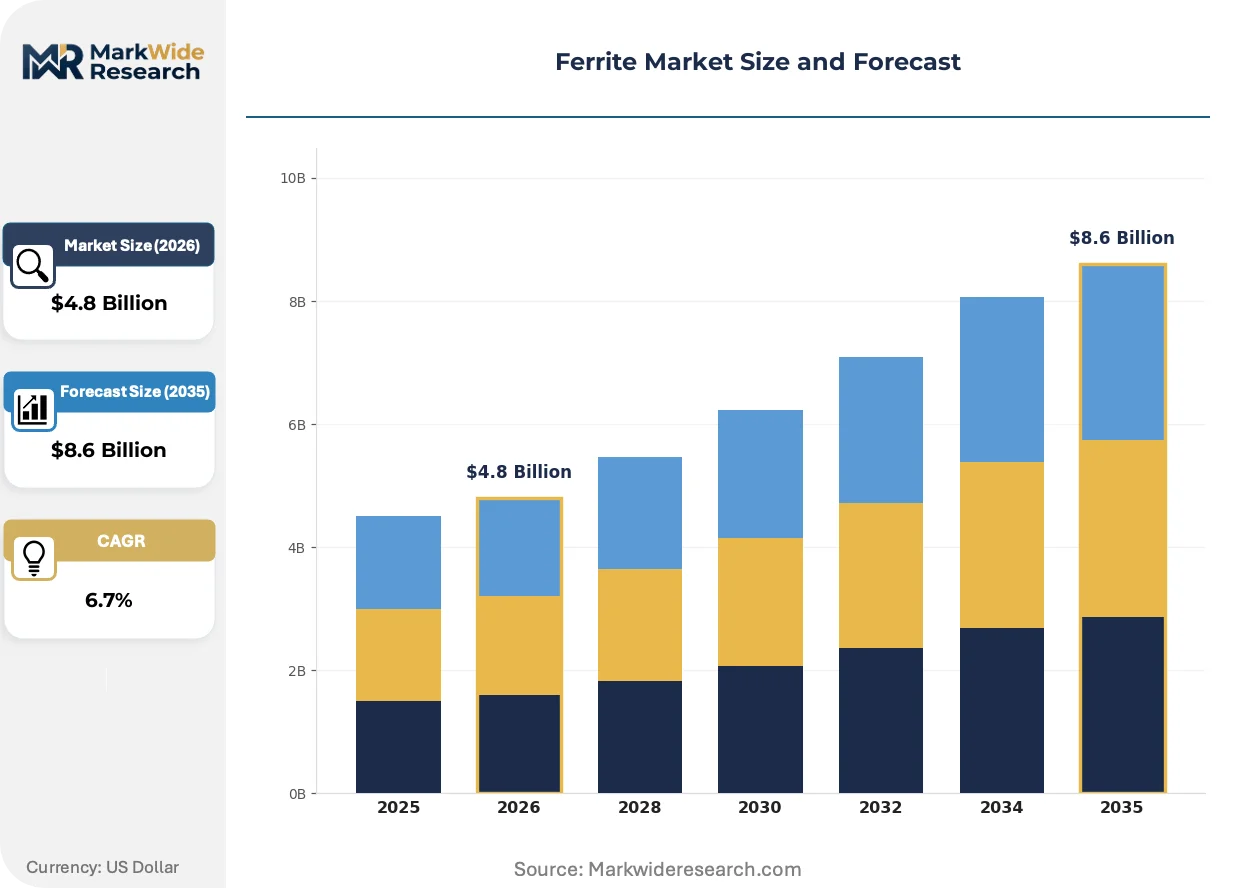
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Ferrite, Hard Ferrite, Spinel Ferrite, Hexaferrite Application: Electronics, Magnetic Devices, Energy Storage, Transformers End User: Automotive, Telecommunications, Aerospace, Consumer Electronics Technology: 3D Printing, Magnetic Imaging, Inductive Heating, Power Electronics |
| Companies Covered | Samsung Electro-Mechanics, Murata Manufacturing Co., Ltd., TDK Corporation, VACUUMSCHMELZE GmbH & Co. KG, Magnetics, Ferroxcube, Fair-Rite Products Corp., Sumida Corporation, Hitachi Metals, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferrite Market Emerging Trajectories
Material science advances and regulatory divergence are fragmenting competitive strategies across the ferrite value chain, with powder synthesis capabilities becoming the decisive differentiator between margin capture and commodity positioning.
Nickel-zinc ferrite formulations optimized for frequencies above 10 MHz are supplanting manganese-zinc variants in 5G infrastructure power amplifiers. Base station original equipment manufacturers in South Korea and Japan are accelerating qualification timelines for these high-resistivity cores. The shift is compressing addressable volume for legacy Mn-Zn producers while expanding margin pools for specialized Ni-Zn synthesis operations.
China's MIIT enforcement of GB standard energy efficiency classifications is tightening magnetic material specifications for switch-mode power supplies sold domestically. Domestic ferrite producers must now submit third-party test reports documenting core loss at elevated temperatures. The policy is accelerating consolidation among smaller Chinese powder manufacturers lacking in-house metrology laboratories.
Automotive tier-one suppliers are unbundling ferrite core procurement from finished inductor module contracts, reversing decade-old captive sourcing arrangements. Powertrain divisions at major vehicle manufacturers now direct-qualify ferrite suppliers separately from their EMS partners. The pattern is most visible in Germany and Japan, where platform-standardized EV architectures enable component-level specification authority.
Ferrite Market Segmentation
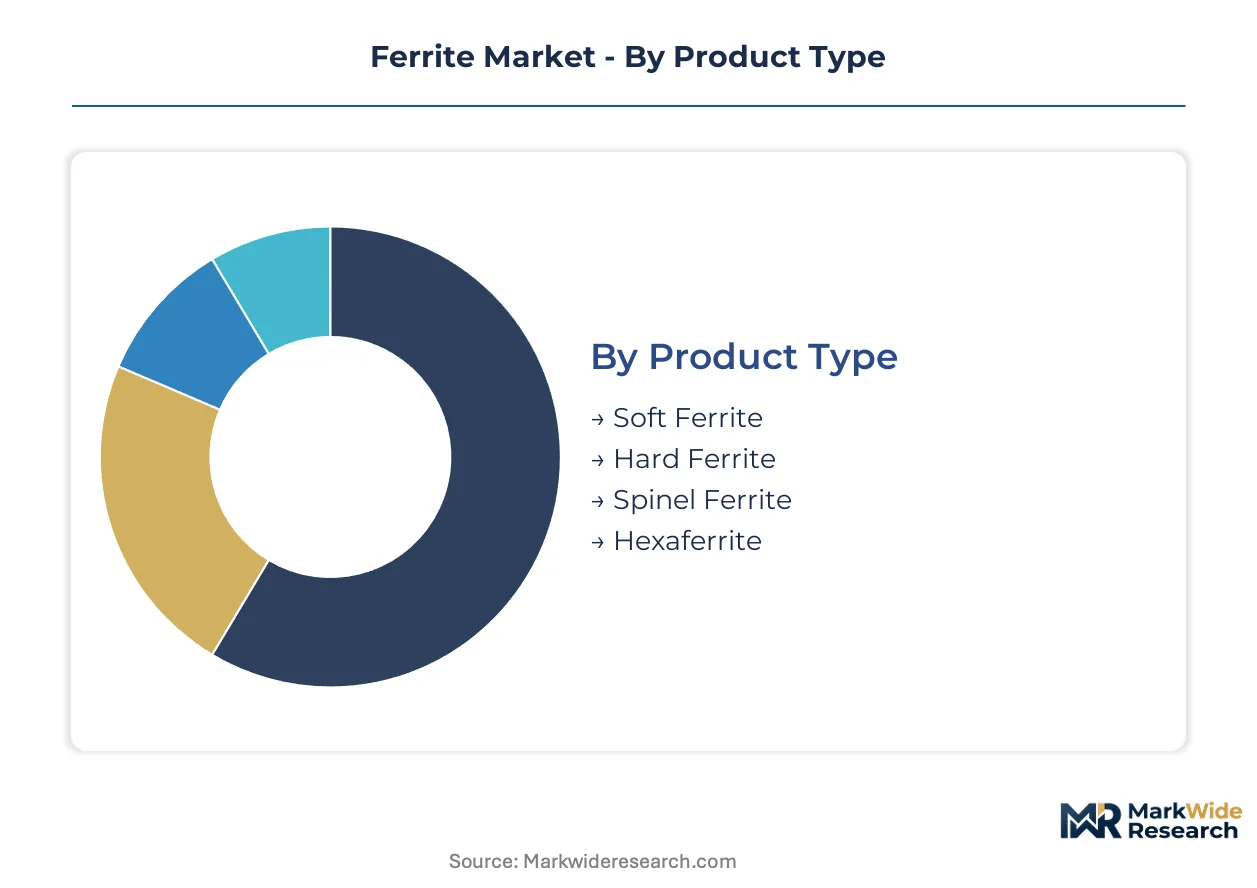
Ferrite market segmentation reveals how substitution pressures from amorphous metals and silicon steel reshape competitive positioning across material classes. Understanding these fault lines enables suppliers to defend margin pools against encroaching alternative technologies.
Product Type:
Soft ferrite faces the most acute substitution threat from nanocrystalline cores in high-frequency power applications, while hard ferrite permanent magnets confront rare-earth magnet displacement in traction motors.
- Soft Ferrite:Ceramic iron oxide compounds sintered with manganese or zinc achieve controlled permeability below 3 MHz. Switch-mode power supply manufacturers in China and Japan dominate procurement volumes as GB standard efficiency classifications tighten core loss specifications at elevated temperatures.
- Hard Ferrite:Strontium or barium hexaferrite variants deliver temperature-stable magnetic remanence for automotive sensors and fractional horsepower motors. German and Japanese automotive tier-one suppliers specify these corrosion-resistant magnets for underhood applications where thermal cycling exceeds 150°C.
- Spinel Ferrite:Cubic crystal structure ferrites with nickel or magnesium substitution enable microwave absorption in radar-absorbent military applications.
- Hexaferrite:Platelet-shaped particles align in polymer matrices for millimeter-wave absorption in South Korean 5G base station deployments.
Soft ferrite retains volume leadership; hexaferrite holds the steepest expansion curve.
Application:
Cost tier differentiation separates specification-grade applications commanding qualification premiums from commodity replacement markets competing on unit economics.
- Electronics:Multilayer chip inductors and EMI suppression cores for smartphones and laptops require sub-millimeter dimensional tolerances. Japanese producers dominate this premium tier through extreme miniaturization expertise in nickel-zinc formulations.
- Magnetic Devices:Permanent magnet motors, magnetic separators, and loudspeaker drivers utilize hard ferrite where energy product requirements fall below rare-earth thresholds. Indian industrial motor retrofits represent an underpenetrated volume opportunity as BIS efficiency standards tighten replacement cycles.
- Energy Storage:Ferrite cores in flywheel systems and magnetic energy storage devices face competition from advanced battery chemistries.
- Transformers:Distribution and power transformer cores above 50 kVA increasingly substitute silicon steel for ferrite due to saturation flux density limitations.
Electronics commands the highest margin tier; magnetic devices deliver the largest absolute volume.
End User:
Customer type concentration creates divergent procurement patterns between platform-standardized automotive buyers and fragmented consumer electronics assemblers.
- Automotive:Powertrain electrification is accelerating qualification of soft ferrite cores for onboard chargers and DC-DC converters. European vehicle manufacturers now direct-qualify ferrite suppliers separately from EMS partners, reversing decade-old captive sourcing arrangements.
- Telecommunications:5G infrastructure buildouts in China, Japan, and South Korea are intensifying demand for hexaferrite millimeter-wave absorbers and nickel-zinc power amplifier cores optimized above 10 MHz.
- Aerospace:Satellite and avionics applications specify radiation-hardened ferrite components with traceable thermal cycling documentation.
- Consumer Electronics:Smartphone and tablet manufacturers in East Asian manufacturing clusters drive high-volume procurement of multilayer chip inductors with aggressive cost-down targets.
Automotive delivers the steepest specification tightening; telecommunications provides the most rapid demand expansion.
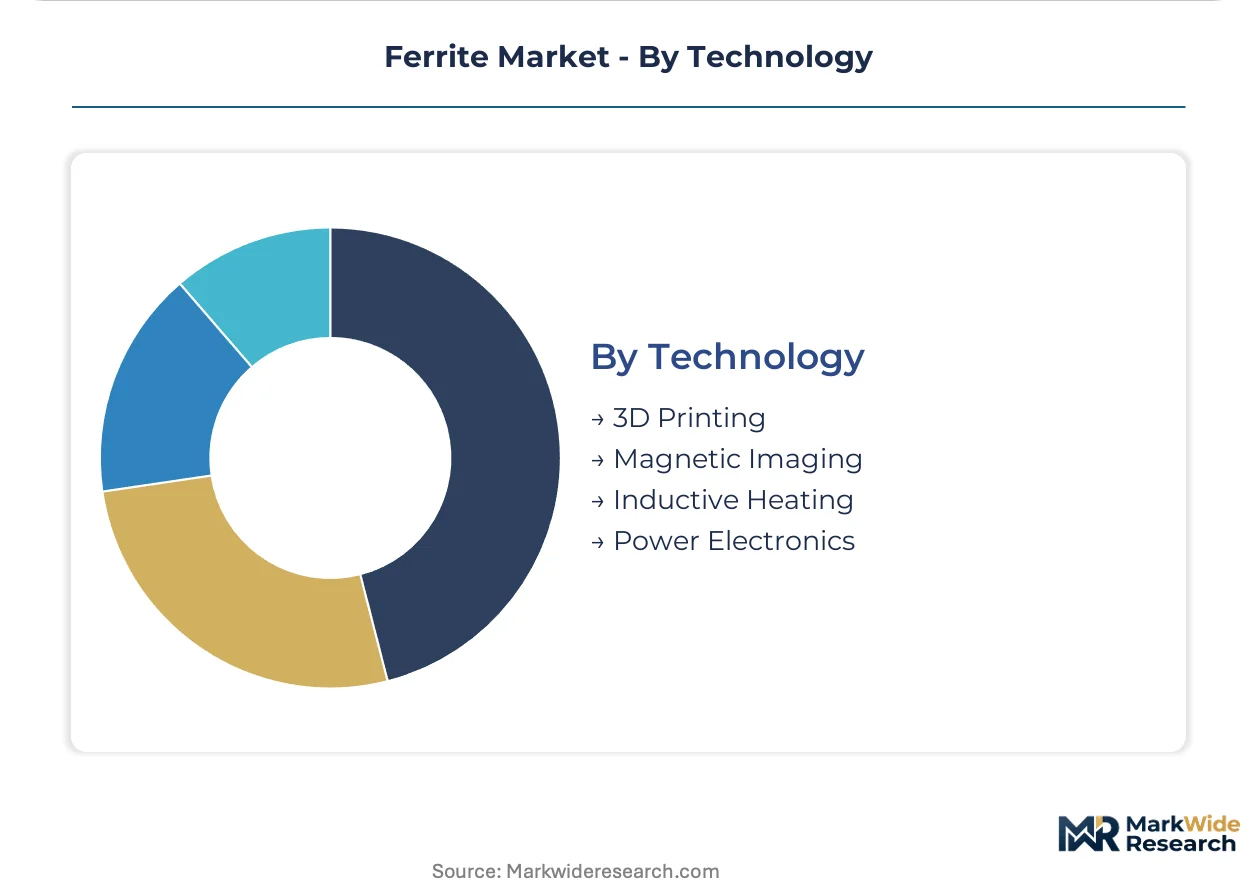
Technology:
Manufacturing process maturity separates established powder metallurgy methods from emerging additive approaches reshaping core geometry possibilities.
- 3D Printing:Binder jet printing of complex ferrite core geometries enables topology-optimized inductor designs impossible through conventional pressing. German and Japanese equipment suppliers are qualifying these processes for small-batch automotive prototype cores.
- Magnetic Imaging:MRI systems utilize ferrite shielding and gradient coil components where patient proximity demands biocompatible ceramic formulations.
- Inductive Heating:Industrial cooking and metallurgical applications require ferrite flux concentrators with specific Curie temperature characteristics.
- Power Electronics:Gallium nitride and silicon carbide converter architectures above 3 MHz are displacing soft ferrite with alternative magnetic materials, constraining addressable frequency range.
Power electronics represents the most mature technology base; 3D printing offers the most disruptive geometry capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in ferrite materials tilt heavily toward East Asian surplus positions, with China, Japan, and South Korea collectively supplying over seventy percent of global core and powder shipments. European and North American manufacturers remain net importers of high-specification ferrite components for automotive and telecommunications applications.
China
Domestic EV powertrain production consumes expanding volumes of soft ferrite cores for onboard chargers and DC-DC converters. MIIT enforcement of GB standard energy efficiency classifications tightens magnetic material specifications for switch-mode power supplies. Manufacturing clusters in the Yangtze River Delta around Shanghai and Suzhou concentrate powder synthesis and sintering operations serving both domestic demand and export markets.
Japan
METI coordinates JIS standards that define performance benchmarks for ferrite cores deployed in automotive and industrial power electronics. Japanese producers dominate premium multilayer chip inductor segments through extreme miniaturization expertise. The Kanto region around Tokyo and the Kansai corridor through Osaka anchor specialized kiln engineering capabilities and precision powder formulation operations.
South Korea
5G base station deployments accelerate demand for hexaferrite millimeter-wave absorbers and nickel-zinc power amplifier cores optimized above 10 MHz. Domestic telecommunications infrastructure buildouts create captive demand for high-resistivity ferrite formulations. The Seoul Capital Area and Busan-Ulsan corridor concentrate base station original equipment manufacturing and supporting magnetic component supply chains.
Germany
Automotive tier-one suppliers unbundle ferrite core procurement from finished inductor module contracts, reversing decade-old captive sourcing arrangements. REACH and RoHS frameworks restrict hazardous substance content in ferrite-bound electronic assemblies sold across EU member states. Bavaria and Baden-Württemberg host powertrain divisions at major vehicle manufacturers exercising direct qualification authority over ferrite suppliers.
United States
Fair-Rite Products Corp. and Magnetics anchor domestic ferrite core production for EMI suppression and power applications. FCC emissions regulations drive specification requirements for ferrite components in telecommunications and computing equipment. The Northeast Corridor and Midwest manufacturing belts concentrate assembly operations importing powder and cores from East Asian suppliers.
Ferrite Market Vendor Landscape
Concentration sits with integrated oxide producers controlling captive powder synthesis and kiln operations, while outsourced assemblers compete on scale and cost efficiency. The vendor base separates into three strategic archetypes: vertically integrated material-to-core specialists, component-scale fabricators serving captive electronics divisions, and regional powder merchants supplying qualification-dependent niche applications. Dominant competitive moves include backward integration into raw material refining and technology licensing partnerships spanning powder formulation patents.
Within the integrated specialist tier, TDK Corporation and Murata Manufacturing Co., Ltd. exemplify archetypes combining captive powder synthesis with finished core production. Samsung Electro-Mechanics occupies a position bridging component fabrication and captive supply into consumer electronics and automotive module divisions. These three Japanese and Korean entities represent distinct competitive positioning strategies: TDK through material science depth, Murata through miniaturization expertise, and Samsung Electro-Mechanics through vertical integration into parent-company demand channels.
| Leading Market Players |
|---|
| Samsung Electro-Mechanics |
| Murata Manufacturing Co., Ltd. |
| TDK Corporation |
| VACUUMSCHMELZE GmbH & Co. KG |
| Magnetics |
| Ferroxcube |
| Fair-Rite Products Corp. |
| Sumida Corporation |
| Hitachi Metals, Ltd. |
| Others |
Supply Flow & Price Mechanics
Ninety-day powder inventory cycles at Japanese kiln operators translate directly into pricing power premiums for qualified ferrite core suppliers, as sintering capacity constraints and divergent regional certification timelines compress effective supply elasticity. Buyers face configured-to-order premiums of 15-25% above standard catalog pricing when demanding GB standard compliance documentation alongside REACH dossier preparation.
Pricing Analysis
The customization-premium spread widens most acutely between automotive-grade ferrite cores and commodity EMI suppression components. Three-tier pricing structure across automotive qualification, industrial specification, and consumer electronics economy levels reflects divergent certification investment recovery horizons. Pricing pressure stems from rare-earth magnet substitution threats in traction motor applications, compressing hard ferrite margin pools. Consumer electronics assemblers exhibit highest price sensitivity, while automotive tier-one suppliers prioritize thermal cycling documentation over unit cost.
Supply Chain Analysis
China and Japan anchor global ferrite powder synthesis and sintering operations, with South Korean producers specializing in nickel-zinc formulations for telecommunications infrastructure. Manganese oxide, zinc oxide, and strontium carbonate feedstocks draw from Chinese mining and refining concentration. Single-source vulnerability concentrates in atmospheric kiln engineering expertise residing with retiring Japanese and German process specialists. Distribution runs through direct long-term offtake agreements with automotive powertrain divisions and spot procurement channels serving consumer electronics EMS partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ferrite suppliers operate behind a defensive moat of regulatory entrenchment, where GB standard testing and REACH dossier preparation create 8-14 month qualification barriers that lock out uncommitted entrants.
For Market Incumbents: Fortify atmospheric control capabilities through apprenticeship programs targeting kiln engineering succession gaps before specialist retirement waves peak. Deepen backward integration into manganese oxide refining to offset Chinese export control volatility. Nanocrystalline core substitution in GaN converters above 3 MHz represents the most acute technology threat requiring R&D counter-positioning in high-frequency nickel-zinc formulations. For New Entrants and Emerging Players: Anchor in India's underpenetrated industrial motor retrofit segment, where BIS efficiency standards tightening below 15% current hard ferrite penetration creates white-space demand. Target binder jet printing qualification partnerships with German automotive prototype divisions seeking topology-optimized core geometries. A certification-fast-track go-to-market angle leveraging single-standard focus—either GB or REACH rather than dual compliance—compresses initial launch timelines. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because powder synthesis capability scarcity and diverging regional standards favor scaled specialists with captive metrology laboratories. Acquisition targets should display integrated oxide-to-core operations with established automotive qualification pipelines. The signal to watch is JIS-GB standard harmonization progress, which would collapse dual-certification cost advantages and trigger accelerated M&A among regional specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxide Refining | Captive manganese and zinc oxide supply insulates margin capture from Chinese export control volatility. |
| Dual Certification Fast-Track Investment | Simultaneous GB standard and REACH dossier capability compresses product launch cycles for automotive clients. |
| Kiln Engineering Apprenticeship Programs | Atmospheric control expertise succession addresses specialist retirement risk concentrated in Japan and Germany. |
| Binder Jet Printing Qualification | Topology-optimized core geometries enable differentiation against conventional pressing limitations in automotive prototypes. |
| Nickel-Zinc Formulation R&D Expansion | High-resistivity cores above 10 MHz counter nanocrystalline substitution in 5G power amplifier applications. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade customs data, MIIT GB standard filings, and SEC 10-K disclosures from listed magnetic material producers. Primary interviews engaged powder synthesis plant managers, automotive tier-one procurement directors, and kiln engineering specialists across Japanese and German operations. Secondary validation drew from ECHA REACH registration databases, JIS standard revision notices, and ferrite core import-export manifests. Bottom-up volume modeling triangulated against top-down value estimates from regional production cluster analysis.
Segmentation dimensions modeled include ferrite material class, end-use application tier, customer procurement archetype, and regional regulatory compliance cluster across the projection horizon. CAGRs derive from production capacity expansion announcements, EV platform content-per-vehicle trajectories, and telecommunications infrastructure deployment schedules. Industry-specific forecast inputs incorporate sintering energy cost exposure under EU carbon pricing and Chinese dual carbon enforcement mechanisms.
Material uncertainties — rare-earth magnet cost trajectories, gallium nitride converter frequency adoption curves, and kiln engineering talent availability — sit outside the modeled envelope. Forecasts reflect assumptions about sustained automotive electrification procurement and 5G base station buildout continuity. Recalibration cycles align with material shifts in MIIT enforcement intensity and JIS-GB standard harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminium Collars Market
Metals
Copper and Copper Alloy Powder Market
Metals
Iron Casting Market
Metals
Stainless Steel Foil Market
Metals
Aluminum Scrap Recycling Market
Metals
Monel Alloy Market
Metals
Metal Forging Market
Metals
North America Aluminum Market
Metals
Aluminum Casting Market
Metals
Carbon Steel Market
Metals
Metal Coil Lamination Market
Metals
Tungsten Metal Powder Market
Metals
Metallurgical Coal Market
Metals
Qatar Metalworking Market
Metals
US Ferrochrome Market
Metals
High Purity Boron Market