
 Flux Field Directional Material Market | 2026-2036
Flux Field Directional Material Market Size, Share, and Industry Trends Forecast 2026-2036
Flux Field Directional Material Market Analytics
Modular kit configurations for magnetic shielding assemblies is pivoting how procurement teams evaluate total cost of ownership. Hitachi Metals Ltd. leverages captive rare-earth processing to secure feedstock consistency across its high-permeability alloy lines. TDK Corporation anchors its position through deep specialization in ferrite core geometries for signal processing applications. Vacuumschmelze GmbH & Co. KG differentiates via precision strip casting capabilities that command premium positioning in aerospace qualification programs.
Flux field directional materials are engineered substances that guide, concentrate, or suppress magnetic flux paths through controlled permeability profiles, typically manufactured via melt-spinning, powder metallurgy, or thin-film deposition to achieve coercivity values below 2 A/m and saturation flux densities exceeding 1.5 T for shielding and energy conversion tasks. Magnetic Materials occupies the dominant revenue position due to entrenched demand from transformer and motor manufacturers seeking grain-oriented silicon steel alternatives. Nano-Coatings represents the fastest-expanding product category as semiconductor fabs adopt atomic-layer-deposited magnetic layers for next-generation data storage architectures. Signal Processing applications concentrate margin pools where phase-noise specifications for 5G infrastructure filters justify material premiums.
The FCC governs electromagnetic interference limits for consumer electronics and telecommunications equipment in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substance content in magnetic material formulations, compelling reformulation investments across export-oriented suppliers. Japan's METI coordinates domestic rare-earth stockpiling policies that directly influence alloy pricing and allocation priorities for precision electronics manufacturers. Stakeholders must monitor evolving dual-use export control classifications for high-permeability alloys as geopolitical friction reshapes cross-border material flows.
Market Dynamics
Magnetic shielding procurement for next-generation avionics is tightening supply partnerships with specialty alloy foundries, creating chokepoints that favor vertically integrated producers with captive rare-earth processing capabilities.
Growth Catalysts
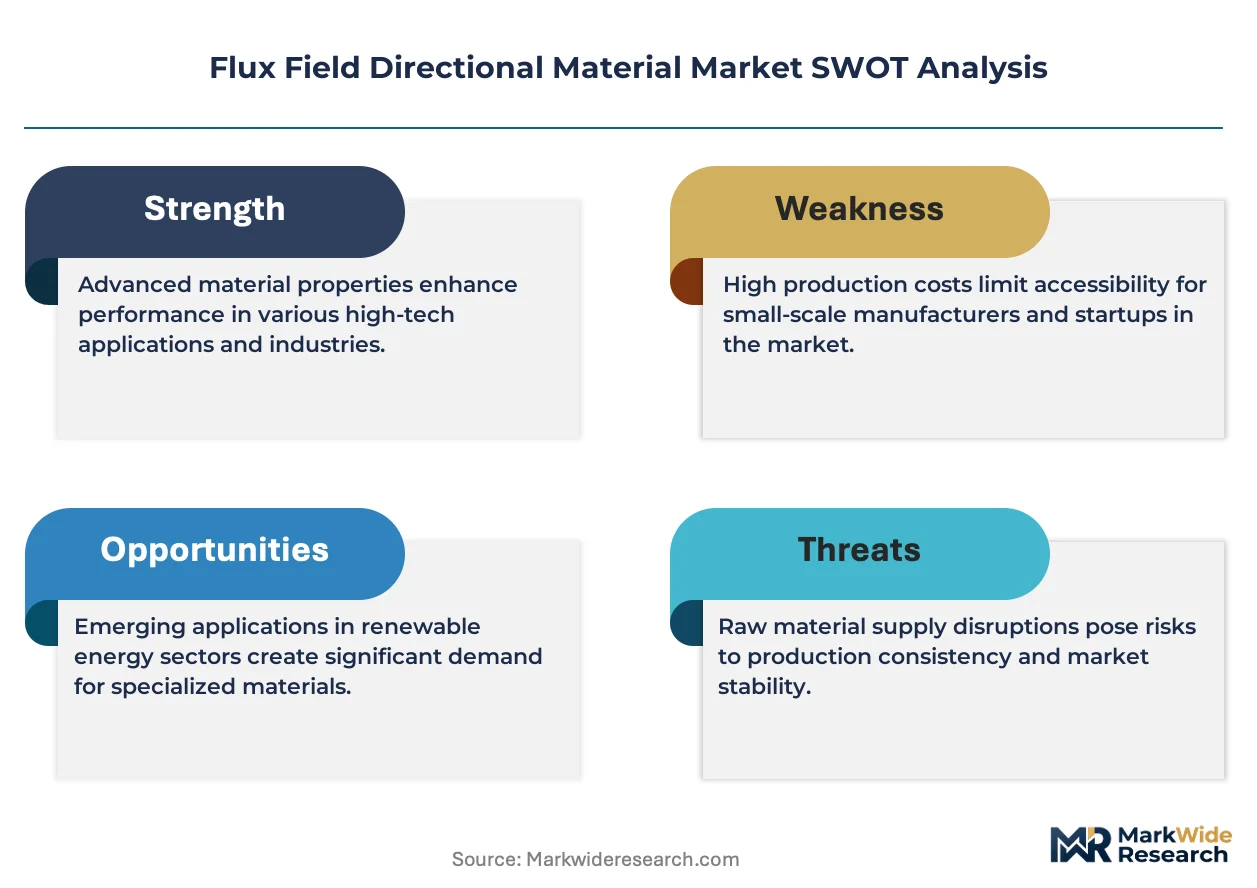
- FCC electromagnetic compatibility mandates:Certification acceleration for consumer electronics and telecommunications equipment in the United States drives material qualification investments across shielding alloy suppliers.
- Atomic-layer-deposited magnetic layers:Semiconductor fabs adopt nano-coating architectures for data storage, expanding addressable demand beyond traditional transformer and motor applications.
- Japan's precision electronics clusters:Concentrated demand from high-frequency component manufacturers pulls premium-grade high-permeability alloys into allocation priority.
Market Restraints
- Rare-earth feedstock volatility:Dependence on dysprosium and terbium supplies subject to METI stockpiling policies creates alloy pricing instability for non-integrated producers.
- REACH and RoHS reformulation costs:European hazardous substance restrictions compel export-oriented suppliers to redesign magnetic material compositions, extending development cycles.
- Grain-oriented silicon steel substitution:Established transformer manufacturers retain incumbent supply contracts, slowing displacement rates for advanced directional materials.
Strategic Opportunities
- 5G infrastructure phase-noise specifications:Signal processing filters for telecommunications base stations justify material premiums in a margin-rich application vertical.
- Dual-use export control reclassification:Geopolitical friction around high-permeability alloys creates openings for domestic suppliers in Germany and Japan to capture redirected demand.
- Modular kit configurations:Procurement teams evaluate total cost of ownership through pre-assembled magnetic shielding assemblies, shifting value capture toward system integrators.
Industry Challenges
- Aerospace qualification timelines:Precision strip casting capabilities require multi-year certification programs with OEMs, locking working capital in inventory before revenue recognition.
- Electromagnetic simulation talent scarcity:Finite element modeling expertise for flux path optimization concentrates among specialized engineering consultancies, inflating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flux Field Directional Material Market |
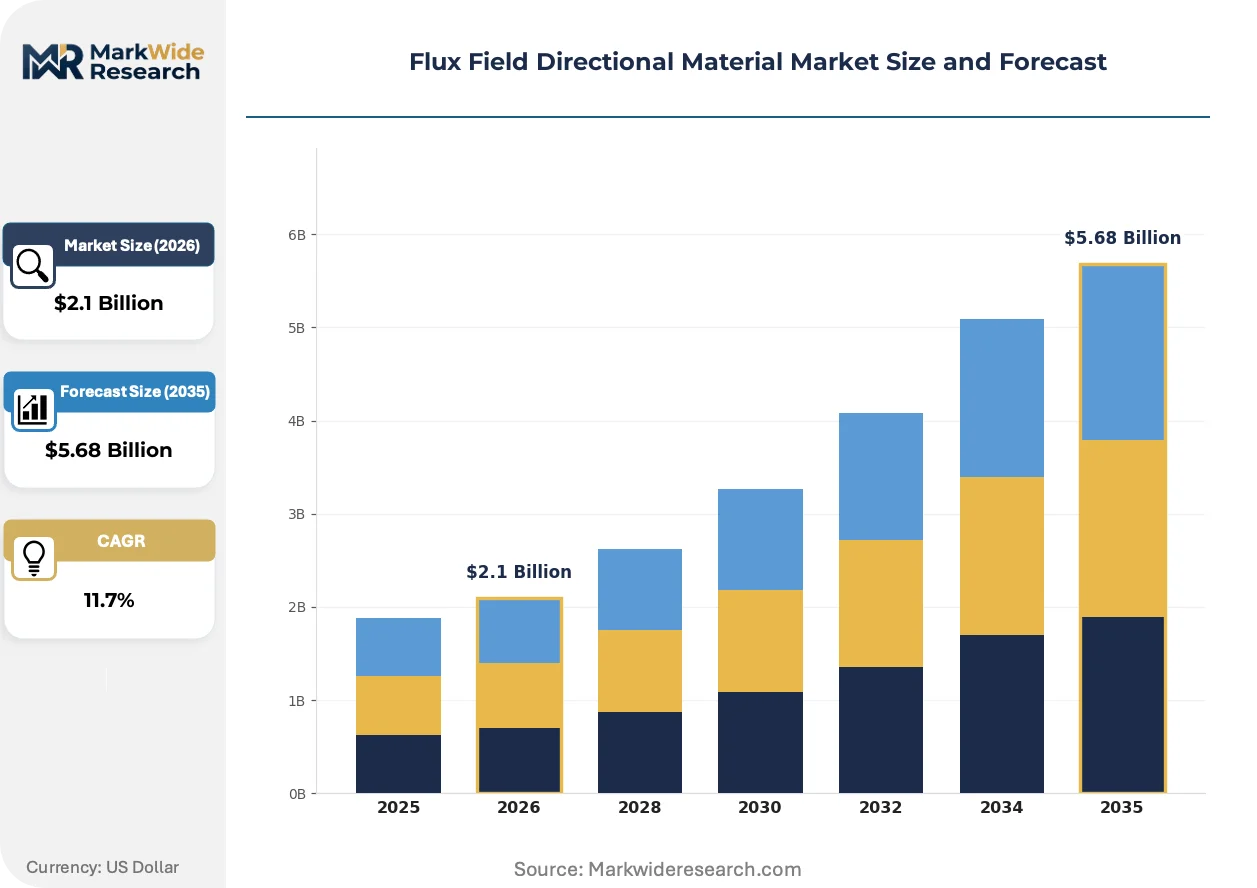
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.68 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Materials, Ferrite Components, Composite Materials, Nano-Coatings End User: Aerospace, Automotive Industry, Consumer Electronics, Energy Sector Application: Magnetic Shielding, Signal Processing, Power Generation, Data Storage Technology: Electromagnetic Theory, Material Science, Nanotechnology, Composite Fabrication |
| Companies Covered | Hitachi Metals Ltd., TDK Corporation, Shin-Etsu Chemical Co. Ltd., Daido Steel Ltd., Arnold Magnetic Technologies, Proterial, Ltd., Ningbo Yunsheng Co. Ltd., Vacuumschmelze GmbH & Co. KG, DMEGC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flux Field Directional Material Market Evolving Landscape
Material architectures and procurement protocols are converging around precision requirements from semiconductor and aerospace end-uses, compressing development cycles while elevating performance thresholds.
Melt-spun amorphous metal ribbons with sub-2 A/m coercivity are decentralizing transformer core manufacturing by enabling distributed, low-loss energy conversion equipment. Regional utilities in East Asia adopt these materials for grid-edge power electronics, bypassing traditional centralized core lamination supply chains. The shift compresses logistics costs while fragmenting procurement authority away from national transformer OEMs.
REACH substance restriction amendments are forcing magnetic material formulators to eliminate hexavalent chromium passivation layers from high-permeability alloy surface treatments. European suppliers invest in plasma electrolytic oxidation alternatives, extending qualification timelines for aerospace export contracts. Germany's industrial corridor bears the highest compliance burden as specialty foundries serve dual domestic and export markets.
Buyer concentration among aerospace OEMs is compressing supplier negotiation leverage through multi-year blanket purchase agreements with price-adjustment clauses. Tier-2 shielding assemblers in Japan's precision electronics clusters respond by unbundling after-sales technical support into separate service contracts. The model shift is most visible in North American avionics procurement, where total cost of ownership evaluations now span fifteen-year operational lifecycles.
Flux Field Directional Material Market Segmentation
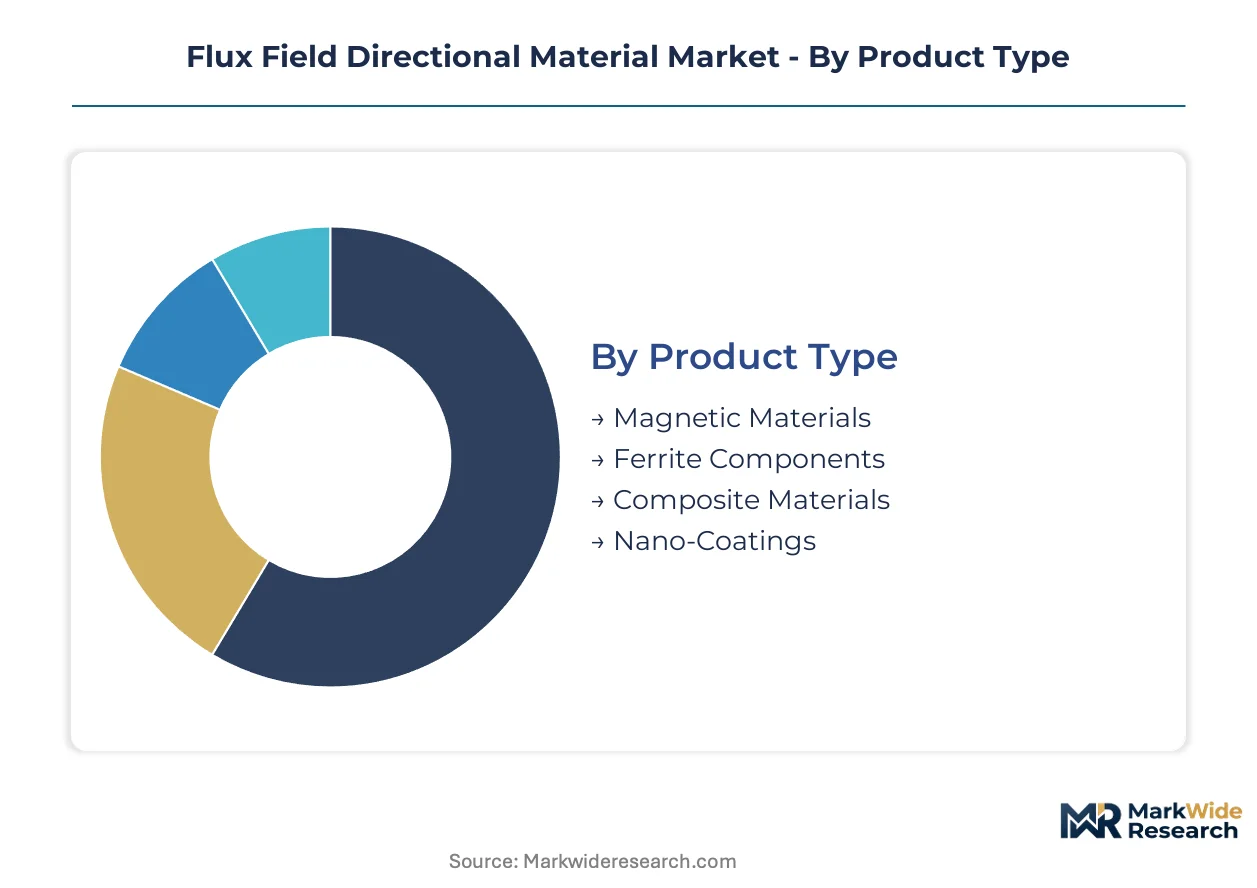
Flux field directional materials serve distinct performance requirements across magnetic shielding, signal processing, and energy conversion applications. Segmentation reveals where capital deployment concentrates and which technical specifications command premium positioning in procurement cycles.
Product Type:
Capital intensity varies sharply across manufacturing processes, with melt-spinning and thin-film deposition requiring substantially higher upfront equipment investment than conventional powder metallurgy.
- Magnetic Materials:Grain-oriented silicon steels and high-permeability alloys manufactured via precision strip casting dominate transformer core and motor lamination supply chains. Aerospace OEMs in Germany and Japan lock in multi-year procurement agreements for these materials, prioritizing batch consistency over unit cost in qualification programs.
- Nano-Coatings:Atomic-layer-deposited magnetic layers achieve sub-nanometer thickness control for semiconductor data storage architectures. Foundries in Japan's precision electronics clusters pull these materials into allocation priority as bit-density requirements intensify.
- Ferrite Components:Sintered ceramic magnets serve cost-sensitive signal filtering applications in telecommunications infrastructure.
- Composite Materials:Polymer-bonded magnetic powders enable complex geometries for automotive sensors and actuators.
Magnetic Materials absorbs the bulk of installed capacity; Nano-Coatings is expanding most quickly.
End User:
Customer concentration patterns determine pricing power, with aerospace procurement teams wielding fifteen-year total cost of ownership frameworks against fragmented component suppliers.
- Aerospace:Avionics manufacturers specify magnetic shielding assemblies for flight-critical navigation and communication systems. FCC electromagnetic compatibility mandates for civilian aircraft equipment drive material qualification investments across North American supply chains.
- Automotive Industry:Electric powertrain and autonomous sensor architectures consume ferrite cores and shielding alloys for motor control units. Germany's industrial corridor hosts concentrated demand from premium vehicle OEMs integrating 800V inverter platforms.
- Consumer Electronics:Smartphone and wearable manufacturers prioritize miniaturized shielding solutions for RF interference management.
- Energy Sector:Grid-scale transformers and renewable inverter installations specify grain-oriented steel alternatives for loss reduction.
Aerospace commands the steepest material premiums; Automotive Industry is climbing the fastest as electrification accelerates.
Application:
Performance thresholds separate commodity supply from premium positioning, with phase-noise specifications in telecommunications justifying substantial material markups.
- Magnetic Shielding:High-permeability alloy enclosures suppress electromagnetic interference in sensitive instrumentation. Modular kit configurations for shielding assemblies are pivoting how procurement teams evaluate supplier total cost of ownership across North American avionics programs.
- Signal Processing:Ferrite core geometries for 5G infrastructure filters face stringent phase-noise specifications. Japan's precision electronics clusters concentrate margin pools where material premiums reflect impedance stability across temperature extremes.
- Power Generation:Transformer and generator cores demand low-coercivity alloys for eddy current loss minimization.
- Data Storage:Perpendicular magnetic recording layers require atomic-scale deposition control for bit-patterned media.
Magnetic Shielding captures the majority of alloy volume; Signal Processing is gaining share fastest on telecommunications infrastructure buildouts.
Technology:
Intellectual property concentration determines competitive moats, with nanotechnology patent portfolios commanding substantial valuation premiums in specialty materials.
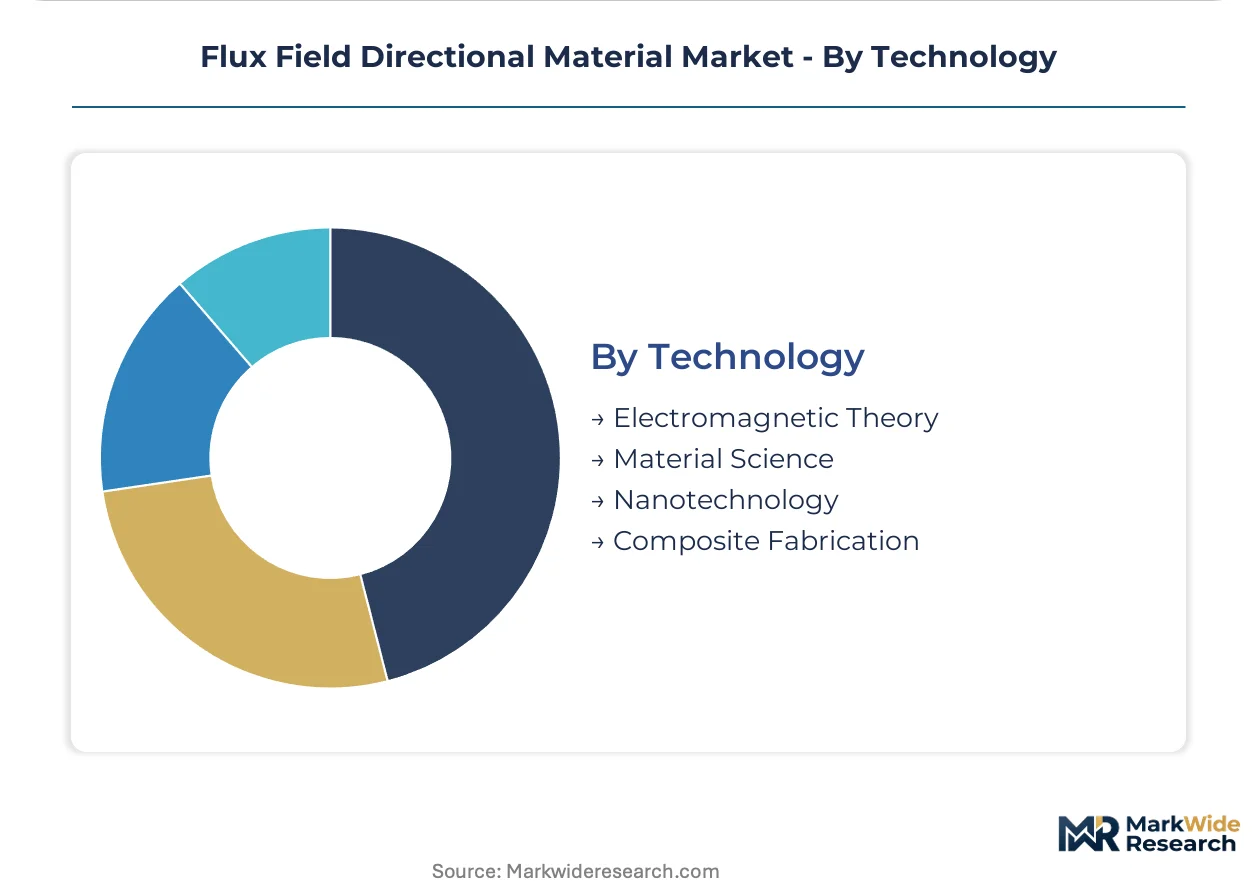
- Material Science:Alloy formulation and heat treatment protocols govern permeability and coercivity tradeoffs. Specialty foundries in Germany's industrial corridor differentiate via precision strip casting capabilities that command premium positioning in aerospace qualification programs.
- Nanotechnology:Atomic-layer deposition and self-assembled monolayer techniques enable sub-10nm magnetic feature control. Semiconductor fabs adopt these architectures for next-generation data storage, expanding addressable demand beyond traditional transformer applications.
- Electromagnetic Theory:Finite element modeling expertise for flux path optimization concentrates among specialized engineering consultancies.
- Composite Fabrication:Polymer matrix processing bonds magnetic fillers for complex three-dimensional component geometries.
Material Science underpins established revenue streams; Nanotechnology is expanding most quickly as deposition equipment costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Japan where precision strip casting capabilities serve aerospace qualification programs, while consumption spreads across avionics clusters in the United States and semiconductor fabs in East Asia.
United States
Aerospace OEMs in Seattle and Wichita drive magnetic shielding procurement for next-generation avionics systems. FCC electromagnetic compatibility mandates accelerate material certification cycles for civilian aircraft equipment. California's Bay Area semiconductor fabs pull nano-coating materials into allocation priority for data storage architectures.
Germany
Premium vehicle OEMs integrating 800V inverter platforms consume ferrite cores and shielding alloys for motor control units. REACH substance restriction amendments compel reformulation investments across export-oriented specialty foundries. The industrial corridor spanning North Rhine-Westphalia and Bavaria hosts concentrated rare-earth alloy processing capacity.
Japan
Precision electronics manufacturers in Tokyo and Osaka specify high-permeability alloys for 5G infrastructure phase-noise filters. METI coordinates domestic rare-earth stockpiling policies that directly influence alloy pricing and allocation priorities. Nagoya's automotive component clusters anchor demand for miniaturized shielding solutions.
China
Grid-scale transformer installations specify grain-oriented steel alternatives for loss reduction in renewable energy integration. The country's national industrial standards regulator enforces electromagnetic compatibility testing protocols for telecommunications equipment. Yangtze River Delta foundries expand melt-spun amorphous metal ribbon capacity for distributed power electronics.
South Korea
Memory semiconductor manufacturers adopt atomic-layer-deposited magnetic layers for next-generation bit-patterned media. The national standards body aligns domestic testing protocols with IEC electromagnetic compatibility frameworks. Seoul Capital Area fabs concentrate demand for sub-10nm deposition control equipment.
Flux Field Directional Material Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across magnetic material supply chains. The vendor base spans vertically integrated rare-earth processors, precision strip casting foundries, and atomic-layer deposition equipment operators. Three archetypes dominate: captive feedstock controllers, qualification-locked aerospace suppliers, and nano-coating technology licensors. Capacity expansion and strategic partnerships represent the dominant competitive moves as procurement teams evaluate fifteen-year total cost of ownership frameworks.
Within the captive feedstock tier, Hitachi Metals Ltd. and Shin-Etsu Chemical Co. Ltd. exemplify backward integration into rare-earth processing. TDK Corporation occupies a position among precision electronics specialists with deep ferrite core geometry expertise. Vacuumschmelze GmbH & Co. KG anchors the aerospace qualification tier through precision strip casting capabilities that command premium positioning in multi-year OEM programs.
| Leading Market Players |
|---|
| Hitachi Metals Ltd. |
| TDK Corporation |
| Shin-Etsu Chemical Co. Ltd. |
| Daido Steel Ltd. |
| Arnold Magnetic Technologies |
| Proterial, Ltd. |
| Ningbo Yunsheng Co. Ltd. |
| Vacuumschmelze GmbH & Co. KG |
| DMEGC |
| Others |
Value Network & Pricing Analysis
Fifteen-year total cost of ownership frameworks from aerospace OEMs compress supplier negotiation leverage and force specialty alloy foundries into multi-year blanket purchase agreements with price-adjustment clauses. This procurement consolidation elevates pricing power toward buyers with qualification-locked supply chains while fragmenting margin pools for non-integrated assemblers.
Pricing Analysis
Margin tightening in aerospace-grade alloys reflects buyer concentration among avionics OEMs and their insistence on batch consistency premiums. Three-tier pricing structure across aerospace-qualified, industrial-standard, and commodity-grade materials separates qualification-locked supply from spot-market transactions. Cost compression in ferrite cores accelerates because automotive electrification programs demand volume scale without material specification relaxation. Consumer electronics manufacturers exhibit highest price sensitivity, while semiconductor fabs accept substantial premiums for atomic-layer deposition control.
Supply Chain Analysis
Single-source vulnerability sits with rare-earth processing capacity concentrated in China, Japan, and Australia's extraction corridors. High-permeability alloy production draws from dysprosium and terbium feedstocks tethered to METI stockpiling policies and export control classifications. Tariff exposure around dual-use material classifications threatens cross-border flows of precision strip castings. Distribution runs through specialty foundry direct contracts to aerospace OEMs, bypassing traditional component distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flux field directional materials constitute a vertical-integration race where captive rare-earth processing and precision casting capabilities determine who captures margin pools. Players are pursuing upstream feedstock control as the decisive competitive lever.
For Market Incumbents: Hedge against rare-earth price volatility through backward integration into extraction partnerships or long-term offtake agreements with Australian and Canadian rare-earth developers. Lock in aerospace qualification timelines through dedicated engineering liaison teams embedded at OEM facilities in Wichita and Nagoya. Defend against nano-coating specialists by accelerating atomic-layer deposition equipment partnerships with semiconductor fabs. For New Entrants and Emerging Players: Capture white-space in modular shielding kit assembly for North American avionics aftermarket, where procurement teams unbundle technical support into separate service contracts. Target automotive sensor applications in Germany's 800V inverter supply chain as the most penetrable vertical for non-qualified material suppliers. Lead with electromagnetic simulation capabilities as a differentiated go-to-market angle, addressing talent scarcity among incumbent foundries. For Investors and Strategic Acquirers: The window for entry favors nano-coating technology licensors with atomic-layer deposition patent portfolios and established foundry relationships. Long-term viability hinges on positioning for semiconductor data storage architecture transitions rather than traditional transformer core displacement. Watch Japan's METI rare-earth stockpile release schedules as the critical inflection signal for alloy pricing and allocation priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Rare-Earth Processing | Secures feedstock consistency against METI stockpiling volatility for high-permeability alloy lines. |
| Precision Strip Casting Capacity Expansion | Commands aerospace qualification premiums through batch consistency exceeding melt-spun ribbon alternatives. |
| Atomic-Layer Deposition Equipment Partnership | Captures semiconductor fab allocation priority for data storage nano-coating architectures. |
| Modular Shielding Kit Configuration | Shifts value capture toward system integrators as procurement teams evaluate fifteen-year operational lifecycles. |
| Electromagnetic Simulation Capability Buildout | Addresses finite element modeling talent scarcity inflating R&D overhead across specialty foundries. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with specialty alloy foundry managers, aerospace OEM procurement directors, semiconductor fab materials engineers, and rare-earth trading specialists. FCC electromagnetic compatibility dockets, METI stockpile policy announcements, REACH substance restriction amendments, and ECHA registration databases provided regulatory trajectory inputs. Bottom-up capacity assessments triangulated against top-down demand modeling from transformer OEM production schedules and avionics platform development timelines.
Data-stream reconciliation across shipment volumes, alloy pricing indices, and qualification program announcements generated consistent trajectory outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, application performance threshold, and technology maturity tier. CAGRs derived from elasticity-adjusted demand curves incorporating rare-earth price volatility scenarios and aerospace procurement cycle timing. Industry-specific forecast inputs encompassed semiconductor bit-density roadmaps and grid-edge power electronics adoption patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to dual-use export control reclassifications and REACH substance restriction amendments. Forecasts reflect documented assumptions around rare-earth supply continuity and aerospace qualification timeline stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Ferroboron Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Ferrofluid Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Global Electrical Steel Sheet Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Global Soft Magnetic Materials Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
Sintered Magnet Market
Magnetic Materials
Magnetorheological Fluid Market
Magnetic Materials
Ferromanganese Market
Magnetic Materials
Magnetic Materials Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market