
 Calcined Shale Market | 2026-2036
Calcined Shale Market Size, Share, and Industry Trends Forecast 2026-2036
Calcined Shale Market Intelligence
The unbundling of calcined shale from pre-mixed cement formulations is broadening its availability as a standalone supplementary cementitious material. Global cement producers like Holcim leverage their extensive distribution networks to supply calcined shale for large-scale infrastructure projects. HeidelbergCement differentiates through its research into optimizing calcined clay and shale blends for specific performance characteristics. Technology providers such as FLSmidth supply the specialized kiln and grinding systems required for efficient calcination.
Calcined shale is an artificial pozzolan produced by heating raw shale to temperatures between 600°C and 800°C. This thermal activation process transforms the clay minerals within the shale into a reactive aluminosilicate material, making it a valuable supplementary cementitious material (SCM) for enhancing concrete durability. The powder form dominates the market, primarily for its use as a partial replacement for clinker in cement production, which falls under the cement product type. Granular and pelletized forms are gaining traction in lightweight aggregate applications for concrete and road engineering.
Performance standards like ASTM C618 in the United States and EN 197-1 in Europe govern the use of calcined shale as a pozzolan in cement and concrete. Policy initiatives, including the EU Green Deal and China's dual carbon goals, create strong incentives for its adoption to lower the carbon footprint of construction materials. Stakeholder success will depend on navigating these varied regional standards while optimizing calcination processes to ensure consistent product quality and performance.
Market Dynamics
The central force shaping the calcined shale market is the global cement industry's decarbonization mandate. Regulatory pressures, such as the EU Green Deal and China's dual carbon goals, are compelling cement producers to reduce clinker content, creating structural demand for alternative supplementary cementitious materials.
Growth Catalysts
- Decarbonization Policies:The EU Green Deal and similar frameworks create a strong regulatory pull for low-carbon cement. This directly benefits calcined shale as a proven supplementary cementitious material (SCM) for clinker substitution, reducing the CO2 footprint of concrete.
- Infrastructure Expansion:High-growth construction markets, particularly in India, are undertaking massive road and infrastructure projects. The use of calcined shale in lightweight aggregates for road engineering supports this expansion while offering material performance benefits.
- SCM Unbundling:The strategic separation of calcined shale from pre-blended cements is increasing its availability as a standalone product. This allows for greater formulation flexibility in large-scale civil engineering projects, tailored to specific performance requirements.
Market Restraints
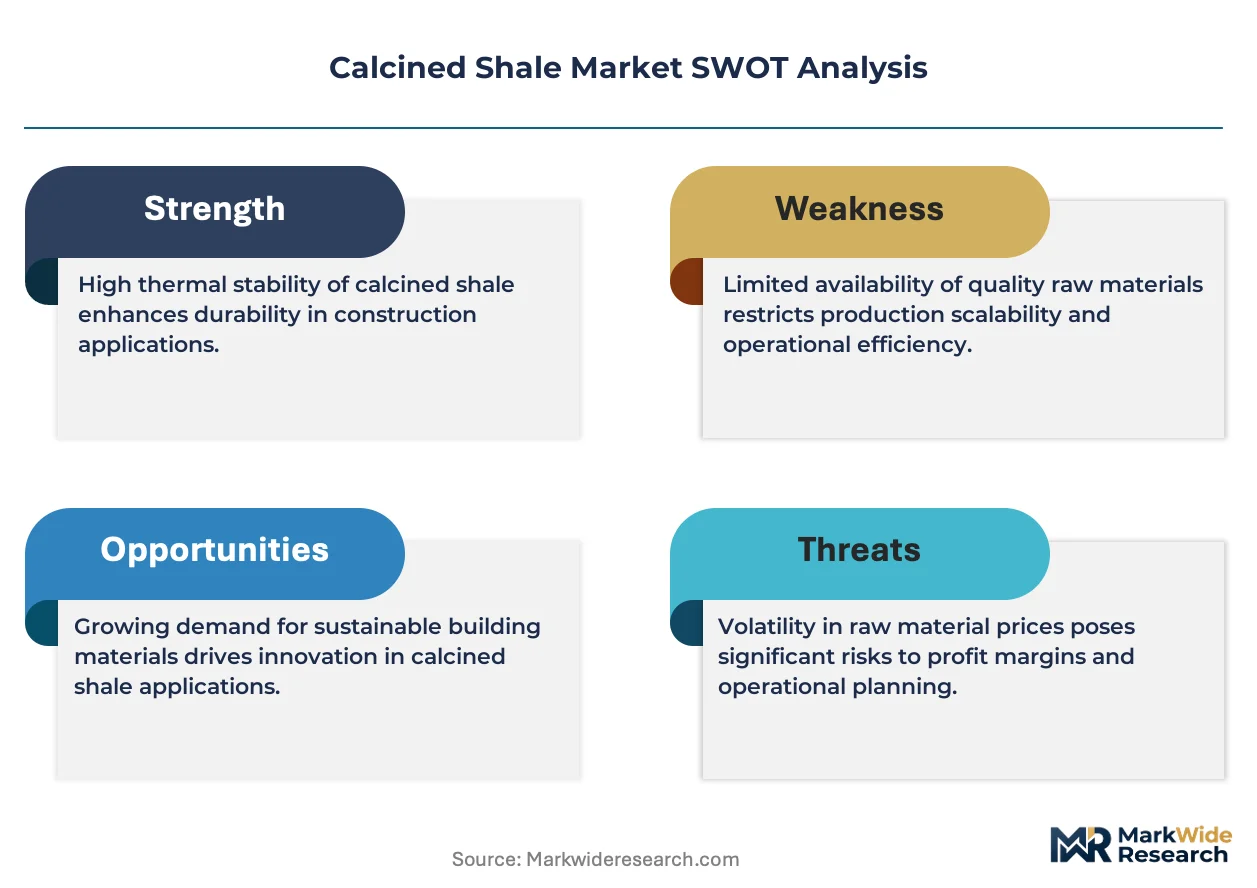
- Energy-Intensive Production:The calcination process requires heating shale to high temperatures, resulting in significant energy consumption. This makes production costs highly sensitive to fluctuations in natural gas and electricity prices, impacting final product affordability.
- Raw Material Variability:The pozzolanic reactivity of calcined shale is directly dependent on the specific clay mineralogy of the raw shale source. This inherent geological variability can lead to inconsistent product performance if not managed by sophisticated process controls.
- Substitution from Incumbents:Calcined shale competes with established SCMs like fly ash and ground granulated blast-furnace slag (GGBFS). The existing supply chains and widespread acceptance of these materials present a significant barrier to substitution in conservative construction markets.
Strategic Opportunities
- Specialized Aggregate Development:There is an opportunity to develop and market granular and pelletized forms of calcined shale specifically for high-value applications, such as geotechnical fills, green roofing media, and horticultural substrates, moving beyond traditional concrete.
- Emerging Market Penetration:Targeting large-scale infrastructure development in regions like Southeast Asia and Sub-Saharan Africa offers significant growth potential. These markets require vast quantities of construction materials and often lack sufficient local sources of traditional pozzolans.
- Carbon Credit Monetization:Producers can leverage the quantifiable CO2 reductions achieved by substituting clinker with calcined shale. Creating frameworks to monetize these reductions through carbon credit markets or green building certifications provides a new revenue stream.
Industry Challenges
- Harmonization of Standards:The lack of a single, globally recognized performance standard for calcined clays creates compliance complexities. Navigating the differences between regional specifications like ASTM C618 and EN 197-1 complicates international trade and product specification.
- Capital Investment Hurdles:The significant capital expenditure needed for specialized rotary kiln and grinding systems for efficient calcination acts as a barrier to entry. This limits the ability of smaller players to enter the market and compete on production cost.
- Quality Control Complexity:Maintaining consistent product quality from geologically variable shale deposits demands advanced process monitoring and quality assurance protocols. Implementing and operating these systems adds operational complexity and cost for producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcined Shale Market |
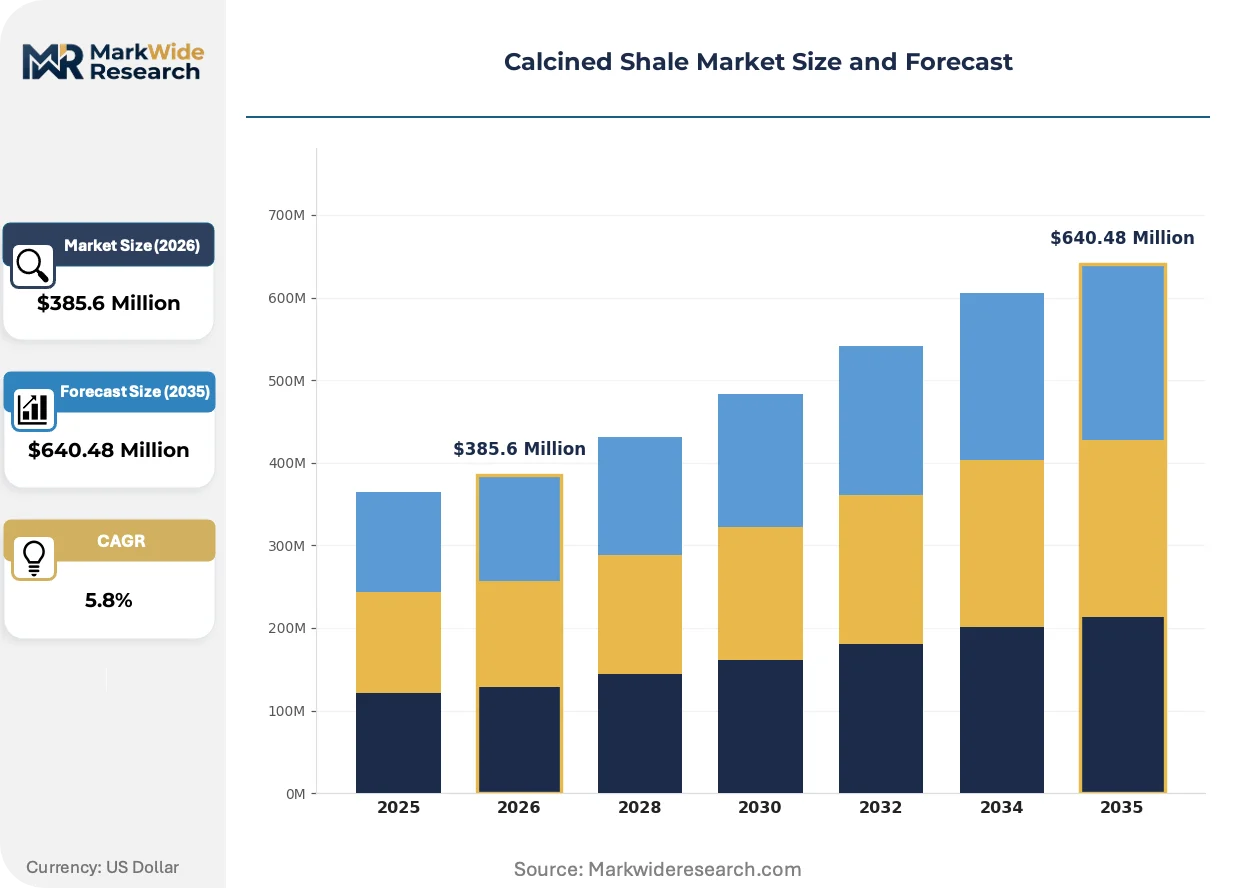
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement, Concrete, Aggregate, Insulating Material End Use Industry: Construction, Road Engineering, Agriculture, Landscaping Form: Granular, Powder, Pelletized, Coated Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Thiele Kaolin Company, EICL Limited, HeidelbergCement, Kirkland Mining Company, CemGreen, Holcim, Hoffmann Mineral GmbH, RK Minerals, FLSmidth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcined Shale Market Strategic Shifts & Innovations
Performance-driven decarbonization is the core theme driving innovation in the calcined shale market. Advances focus on optimizing the material's properties as a supplementary cementitious material, while regulatory frameworks create a non-negotiable demand for its CO2-reducing capabilities in cement and concrete.
Advanced analytical techniques are being used to map the precise mineralogy of raw shale deposits before processing. Cement manufacturers and research bodies adopt methods like quantitative X-ray diffraction to calibrate calcination parameters for specific geological sources. This data-driven optimization is unifying the previously separate domains of geology and material science, enabling the production of calcined shale with highly predictable pozzolanic activity.
China's dual carbon goals are creating powerful incentives to reduce the clinker-to-cement ratio in its domestic industry. This national policy directly stimulates demand for locally sourced pozzolans, including calcined shale, as a primary substitute for carbon-intensive clinker. The country's vast cement sector is the most affected, responding by building new calcination capacity and modifying production lines to handle larger volumes of SCMs.
A shift toward performance-based specifications for concrete is changing procurement for major infrastructure. This model allows engineers to select materials like calcined shale to meet specific targets for durability, chloride resistance, or carbon footprint, rather than following a rigid, prescriptive recipe. This trend is most prominent in large public infrastructure projects in Europe and North America, where lifecycle cost analysis and sustainability metrics are becoming key decision criteria.
Calcined Shale Market Segmentation
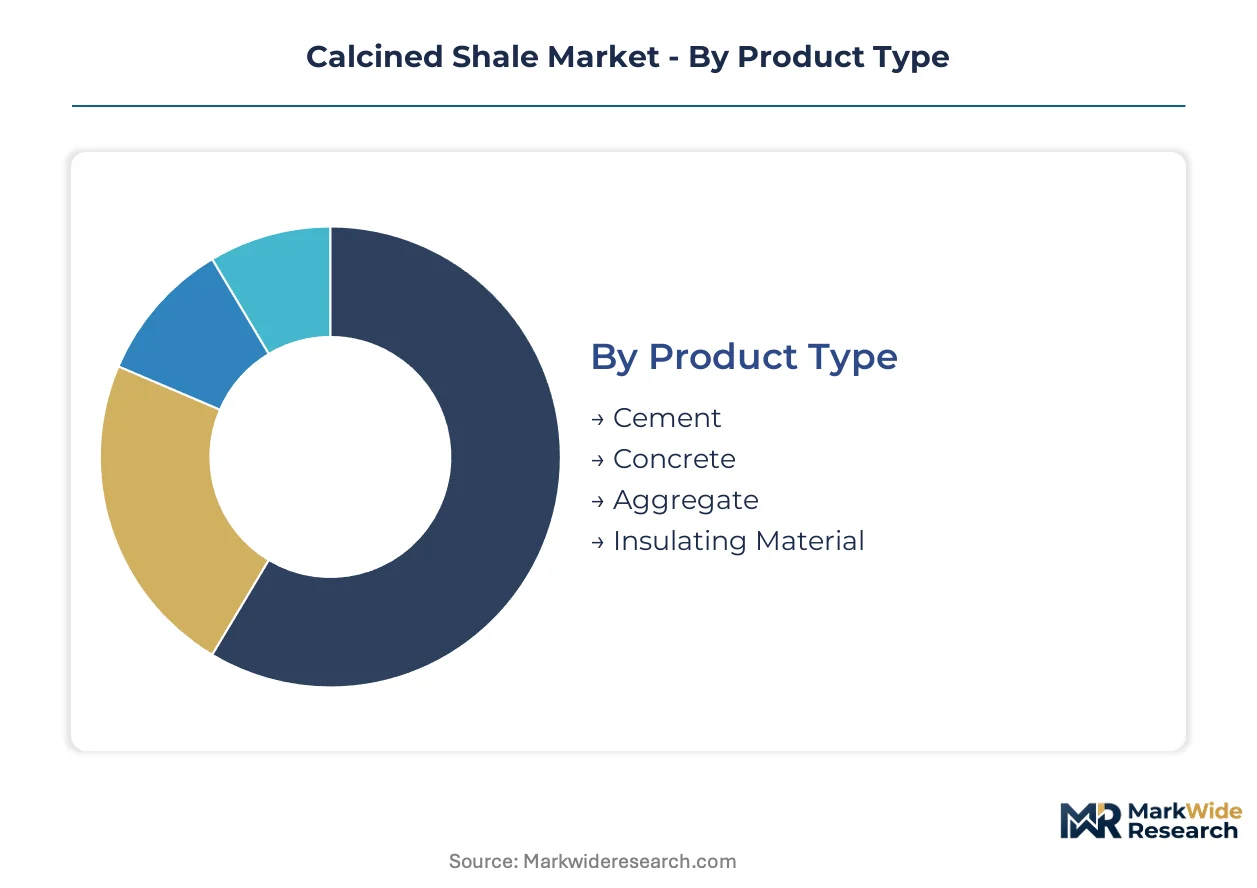
The calcined shale market demonstrates diverse applications and operational models, necessitating a clear segmentation to understand demand drivers. Analyzing these segments helps stakeholders identify specific material requirements, target emerging end-use sectors, and optimize distribution strategies for varying customer scales.
Product Type:
Buyers in the calcined shale market differentiate their product needs based on the specific material properties required for their final application.
- Cement:Calcined shale acts as an artificial pozzolan, produced by heating raw shale to temperatures between 600°C and 800°C, transforming clay minerals into reactive aluminosilicate. Demand concentrates in global cement production, driven by decarbonization mandates like the EU Green Deal to reduce clinker content.
- Aggregate:Granular and pelletized calcined shale forms serve as lightweight aggregates, offering reduced density and improved thermal properties for construction. High-growth construction markets such as India utilize these aggregates for road engineering and infrastructure, supporting expansion.
- Concrete:Calcined shale enhances concrete durability and strength when used as a supplementary cementitious material.
- Insulating Material:The material's porous structure provides thermal insulation properties for various building applications.
Volume sits with Cement; growth tilts toward Aggregate.
End Use Industry:
End-use industries dictate the performance characteristics and scale of calcined shale required for specific applications.
- Construction:Calcined shale integrates into various construction materials, including concrete, mortar, and specialized binders, improving their long-term durability. Global infrastructure projects, particularly in emerging economies, drive demand for sustainable and high-performance building components.
- Road Engineering:The material serves as a lightweight aggregate or sub-base stabilizer, contributing to reduced roadbed weight and improved structural integrity. Large-scale road networks in countries like India utilize calcined shale to enhance performance and manage material costs.
- Agriculture:Calcined shale can improve soil structure and water retention in agricultural applications.
- Landscaping:It functions as a lightweight filler or drainage material in various landscaping and horticultural projects.
The Construction sector largely dominates consumption, while Road Engineering exhibits significant expanding demand.
Form:
The physical characteristics of calcined shale determine its suitability for specific processing and application methods.
- Powder:This finely ground form of calcined shale maximizes surface area for pozzolanic reactions, crucial for clinker replacement in cement production. Global cement manufacturers leverage powder calcined shale to meet decarbonization targets, especially in China's vast cement sector.
- Granular:Granular calcined shale consists of irregularly shaped particles, providing bulk and structural stability for lightweight aggregate applications. Infrastructure projects in North America and Europe increasingly specify granular forms for geotechnical fills and road bases.
- Pelletized:Pelletized calcined shale offers uniform size and reduced dust, beneficial for specialized aggregate or horticultural uses.
- Coated:Coated calcined shale enhances specific properties like water repellency or dust suppression for niche applications.
Powder form constitutes the majority of the market, with granular and pelletized forms experiencing strong uptake.
Distribution Channel:
Distribution channels reflect the varying scales and logistical requirements for delivering calcined shale to diverse end-users.
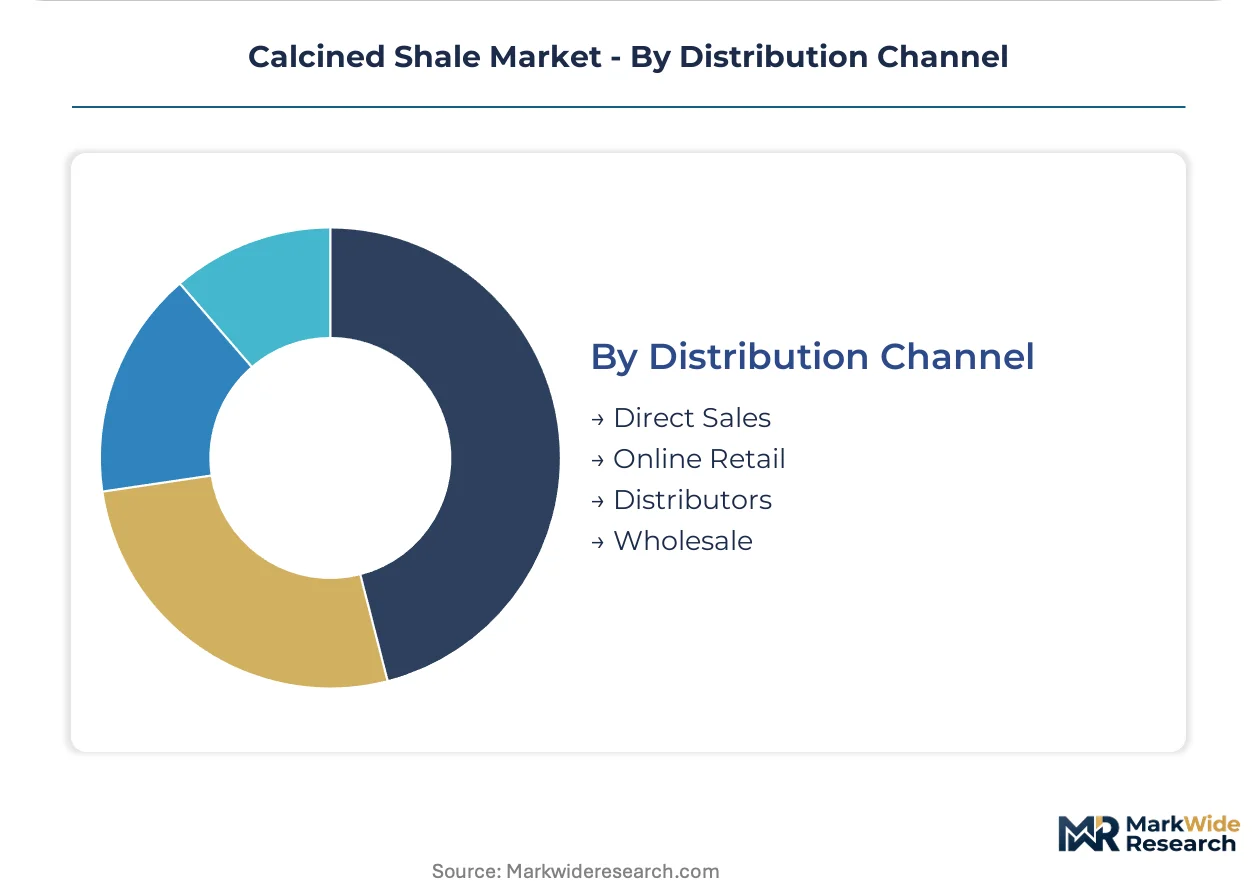
- Direct Sales:Large-volume transactions occur directly between calcined shale producers and major construction companies or cement manufacturers. Global cement producers leverage direct sales for large-scale infrastructure projects, ensuring consistent supply and quality control.
- Distributors:Regional distributors manage inventory and logistics, providing calcined shale to smaller construction firms and specialized material suppliers. This channel facilitates market penetration in fragmented construction markets, offering localized availability and technical support.
- Online Retail:Online platforms serve niche markets for specialized aggregates or smaller volume purchases, offering convenience.
- Wholesale:Wholesale operations supply bulk quantities to regional material yards and large-scale project contractors.
Direct Sales accounts for a substantial portion of volume, while the distributor network shows expanding reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The calcined shale market exhibits distinct regional dynamics, characterized by significant production capacities in some areas and robust consumption in others. Regulatory frameworks across various nations are increasingly influencing both the supply and demand for this sustainable construction material. This global landscape shapes investment decisions and technological advancements in calcined shale production.
China
China's vast cement sector drives substantial demand for calcined shale as a supplementary cementitious material. The country's dual carbon goals actively compel cement producers to integrate low-carbon alternatives to reduce clinker content. Major industrial hubs like the Yangtze River Delta are seeing increased adoption of calcined shale in large-scale infrastructure projects.
India
Infrastructure expansion projects in India create a significant need for lightweight aggregates and sustainable construction materials. The Indian government's focus on sustainable infrastructure development encourages the use of materials like calcined shale in road engineering. Cities such as Mumbai and Delhi are experiencing high demand for calcined shale in urban development and road network upgrades.
United States
Demand for calcined shale in the United States stems from its use in concrete durability enhancements and as an SCM. Performance standards like ASTM C618 guide the specification of calcined shale in construction projects across the nation. The Gulf Coast region, with its extensive industrial and construction activities, utilizes calcined shale for various infrastructure applications.
Germany
Germany's commitment to the EU Green Deal mandates lower carbon footprints in its construction industry, boosting calcined shale adoption. European standards such as EN 197-1 govern the application of pozzolans in cement and concrete mixtures. The Rhine-Ruhr metropolitan region, a dense industrial and urban area, integrates calcined shale into modern building practices.
Indonesia
Emerging market penetration strategies target Indonesia due to its substantial infrastructure development needs. The Indonesian government's push for sustainable building materials supports the integration of calcined shale in new projects. Jakarta, as a rapidly expanding capital city, represents a key consumption center for sustainable aggregates in its urban development.
Calcined Shale Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists for market share in the calcined shale industry. The market structure features a mix of established cement producers and specialized material suppliers. Strategic archetypes include large-scale SCM providers, regional aggregate suppliers, and technology providers for calcination processes. Dominant competitive moves involve strategic partnerships for raw material sourcing and significant capital investments in new production capacities.
At the scale-driven end of the market, global cement producers like Holcim and HeidelbergCement exemplify companies leveraging extensive distribution networks to supply calcined shale for large-scale infrastructure projects. These entities often integrate calcined shale into their broader supplementary cementitious material portfolios, responding to decarbonization mandates. Meanwhile, FLSmidth, a technology provider, occupies a distinct position by supplying the specialized kiln and grinding systems essential for efficient calcination processes. This demonstrates the market's reliance on both material supply and critical processing technology for operational efficiency.
| Leading Market Players |
|---|
| Thiele Kaolin Company |
| EICL Limited |
| HeidelbergCement |
| Kirkland Mining Company |
| CemGreen |
| Holcim |
| Hoffmann Mineral GmbH |
| RK Minerals |
| FLSmidth |
| Others |
Cost & Logistics Intelligence
Global decarbonization mandates, such as the EU Green Deal, are compelling cement producers to reduce clinker content. This structural demand for calcined shale shapes its supply response and influences pricing dynamics across the construction material value chain.
Pricing Analysis
Cost-down pressure on supplementary cementitious materials accelerates due to large-scale infrastructure projects seeking material cost efficiencies. The dominant pricing model for calcined shale involves contract-based long-term offtake agreements with major cement producers. Price differentiation stems from pozzolanic activity, geographic delivery costs, and volume scale. Smaller construction firms purchasing granular forms exhibit higher price sensitivity compared to global cement manufacturers securing powder form via long-term contracts.
Supply Chain Analysis
Single-source vulnerability sits with the highly localized raw shale deposits, making consistent quality crucial. Geographic supply concentrates in regions with abundant shale resources and demand, including China, India, and parts of the United States. The supply chain relies heavily on raw shale extraction and energy-intensive calcination, leading to significant exposure to commodity price volatility for natural gas and electricity. Distribution runs primarily through direct sales to major cement manufacturers, complemented by regional distributors serving smaller construction firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcined shale market is entering a technology-transition phase, as advanced kiln and grinding systems replace older, less efficient calcination methods. This shift enables greater consistency and reactivity for supplementary cementitious material applications.
For Market Incumbents: Cement producers must invest in advanced calcination capacity to ensure consistent product quality, defending against competition from established SCMs. Strategic partnerships for raw shale sourcing in high-demand regions like India will secure long-term supply. R&D into optimizing calcined shale blends for specific performance characteristics, alongside robust certification investments, strengthens market position. This mitigates margin pressure from fluctuating energy costs in production.
For New Entrants and Emerging Players: Regional distributors provide a critical entry point for new players targeting specialized aggregate development, such as geotechnical fills. The most penetrable segment lies in granular and pelletized forms for niche construction and horticultural uses. Penetrating emerging markets like Indonesia and other parts of Southeast Asia offers significant growth potential due to infrastructure needs. A go-to-market angle emphasizing performance-based specifications for concrete can differentiate offerings.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking long-term exposure to decarbonization trends over the next 5-10 years. Acquisition targets should focus on mid-sized, vertically integrated calcined shale producers possessing proprietary process technology for quality control. Investors should watch for the rapid expansion of new calcination capacity in emerging markets like India as an inflection indicator. This signals accelerating demand and regulatory support for SCMs.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in advanced calcination technology | Optimizes energy efficiency and ensures consistent pozzolanic activity for cement producers. |
| Form raw shale sourcing partnerships | Secures consistent supply of quality raw material, mitigating geological variability for manufacturers. |
| Develop specialized aggregate applications | Expands market reach beyond traditional concrete, targeting high-value niche construction sectors. |
| Pursue carbon credit monetization | Creates new revenue streams by leveraging CO2 reductions from clinker substitution for producers. |
| Expand into emerging infrastructure markets | Captures demand in regions like Southeast Asia and India with significant construction growth. |
Research Approach
Document review covered industry association reports, government environmental policies, and relevant patent databases, complemented by interviews with industry stakeholders. Primary research engaged cement production executives, SCM R&D directors, construction project managers, and kiln technology providers. This approach ensured bottom-up validation of market dynamics and top-down triangulation of macro trends. Secondary data from academic research papers further supported the analysis.
A robust quantitative model generated volume and value projections across the analysis window, segmented by product type, end-use industry, form, and distribution channel. CAGRs were derived from historical growth patterns and projected adoption rates, integrating regional regulatory frameworks. Key forecast inputs included anticipated clinker substitution rates and global infrastructure spending forecasts. This framework provides a comprehensive market outlook.
Caveats apply where sudden shifts in energy prices or new SCM technologies could materially shift the outlook. Forecasts reflect current regulatory trajectories and anticipated infrastructure spending. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Abrasive Cloth Market
Abrasives
Surface Conditioning Wheels Market
Abrasives
Asia-Pacific Abrasives Market
Abrasives
Global Rubber Bonded Abrasive Market
Abrasives
Polishing Chemicals Market
Abrasives
Superabrasive Electroplated Grinding Wheel Market
Abrasives
Global Abrasives Market
Abrasives
Boron Carbide Market
Abrasives
North America Abrasives Market
Abrasives
Liquid Sandpaper Market
Abrasives
Non-Woven Abrasives Market
Abrasives
Carbide Grinding Wheel Market
Abrasives
Abrasive Tools Market
Abrasives
Middle East and Africa Abrasives Market
Abrasives
Lapping and Polishing Films Market
Abrasives
Sandblaster Market