
 Ductile Iron Pipe Market | 2026-2036
Ductile Iron Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Ductile Iron Pipe Market Intelligence
EPA Lead and Copper Rule revisions is broadening the cost-of-entry calculus for water infrastructure suppliers across the United States. Saint-Gobain PAM leverages its European foundry expertise to anchor premium coated pipe supply for North American municipal bids. Kubota Corporation sustains dominant positioning in Japan's seismic-resistant pipeline specifications while extending distribution partnerships across Southeast Asia.
Ductile iron pipe consists of spheroidal graphite cast iron with minimum tensile strength of 60,000 psi, manufactured through centrifugal casting or static casting processes for pressurized fluid conveyance and gravity flow systems. Pressure pipe dominates capital allocation from water utilities due to burst resistance requirements in potable water networks, while coated pipe variants command margin premiums from corrosion protection specifications in aggressive soil environments. Non-pressure pipe segments face slower replacement cycles in sewer applications where PVC and concrete alternatives compete on installed cost.
AWWA C151 standards in the United States, EN 545/598 in Europe, and ISO 2531 govern wall thickness, joint design, and hydrostatic testing protocols that determine product qualification for municipal procurement. India's BIS certification and China's GB/T 13295 standards create parallel compliance pathways that shape export competitiveness for foundries serving multiple geographies. Stakeholders must monitor evolving lead-content thresholds and embodied carbon disclosure requirements that will increasingly filter supplier eligibility in public tenders.
Market Dynamics
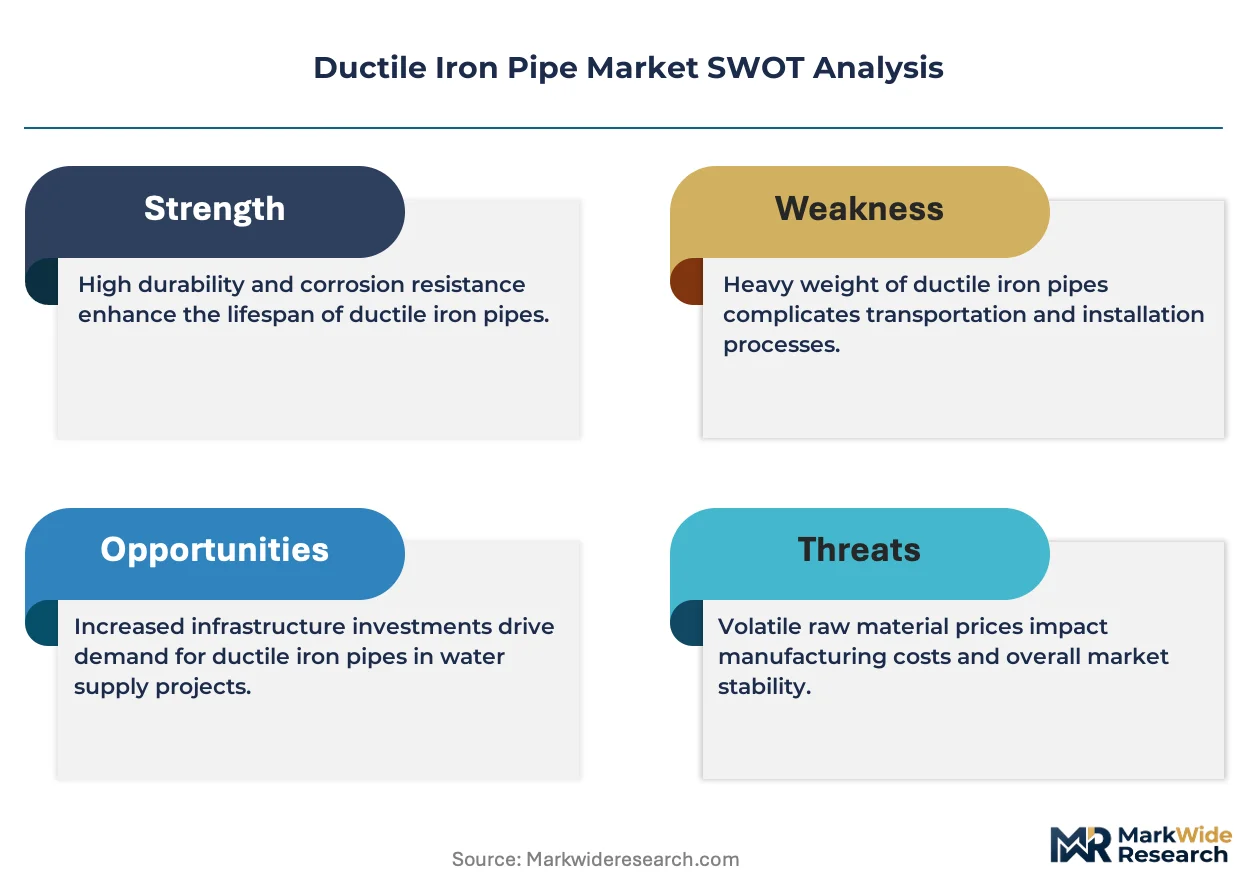
Municipal water utilities face simultaneous pressure from EPA Lead and Copper Rule enforcement and seismic resilience mandates, forcing capital reallocation toward corrosion-resistant ductile iron infrastructure with higher upfront costs but extended service life.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:The U.S. EPA's tightened lead-action thresholds compel wholesale replacement of aging cast iron distribution networks, accelerating procurement cycles for certified ductile iron suppliers.
- Seismic-Resistant Specifications:Japan's METI-driven pipeline standards now mandate ductile iron for high-risk fault zones, extending specification influence across Pacific Ring of Fire municipalities.
- Smart Cities Mission:India's urban infrastructure corridors prioritize pressurized water systems with 100-year design life, concentrating demand in Delhi-Mumbai Industrial Corridor zones.
Market Restraints
- Scrap Iron Price Volatility:Foundry input costs fluctuate with global ferrous scrap markets, compressing margin visibility for fixed-price municipal contracts spanning multi-year installation timelines.
- Chinese Foundry Dominance:Overcapacity in Hebei and Shandong provinces creates price-floor pressure on export markets, limiting pricing power for European and North American producers.
- PVC Substitution in Gravity Sewers:Thermoplastic alternatives capture non-pressure applications through lower installed cost, constraining ductile iron volume in wastewater infrastructure segments.
Strategic Opportunities
- Carbon Disclosure Requirements:The EU's CSRD and emerging embodied-carbon procurement filters favor domestic European foundries with verified low-carbon production methods in public tenders.
- Coating Technology Convergence:Fusion-bonded epoxy and polyurethane lining systems extend service life in aggressive soils, opening premium pricing in coastal and industrial contamination zones.
- Direct Utility Contracting:Bypassing traditional distributor channels through digital procurement platforms reduces friction for midsize water authorities seeking certified product traceability.
Industry Challenges
- Centrifugal Casting Technician Shortage:Specialized mold operation and quality-control expertise faces generational attrition, constraining foundry expansion despite order backlogs.
- Multi-Jurisdictional Certification Timelines:Simultaneous pursuit of AWWA C151, EN 545, and BIS approvals extends product qualification cycles by 18-24 months for export-focused manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ductile Iron Pipe Market |
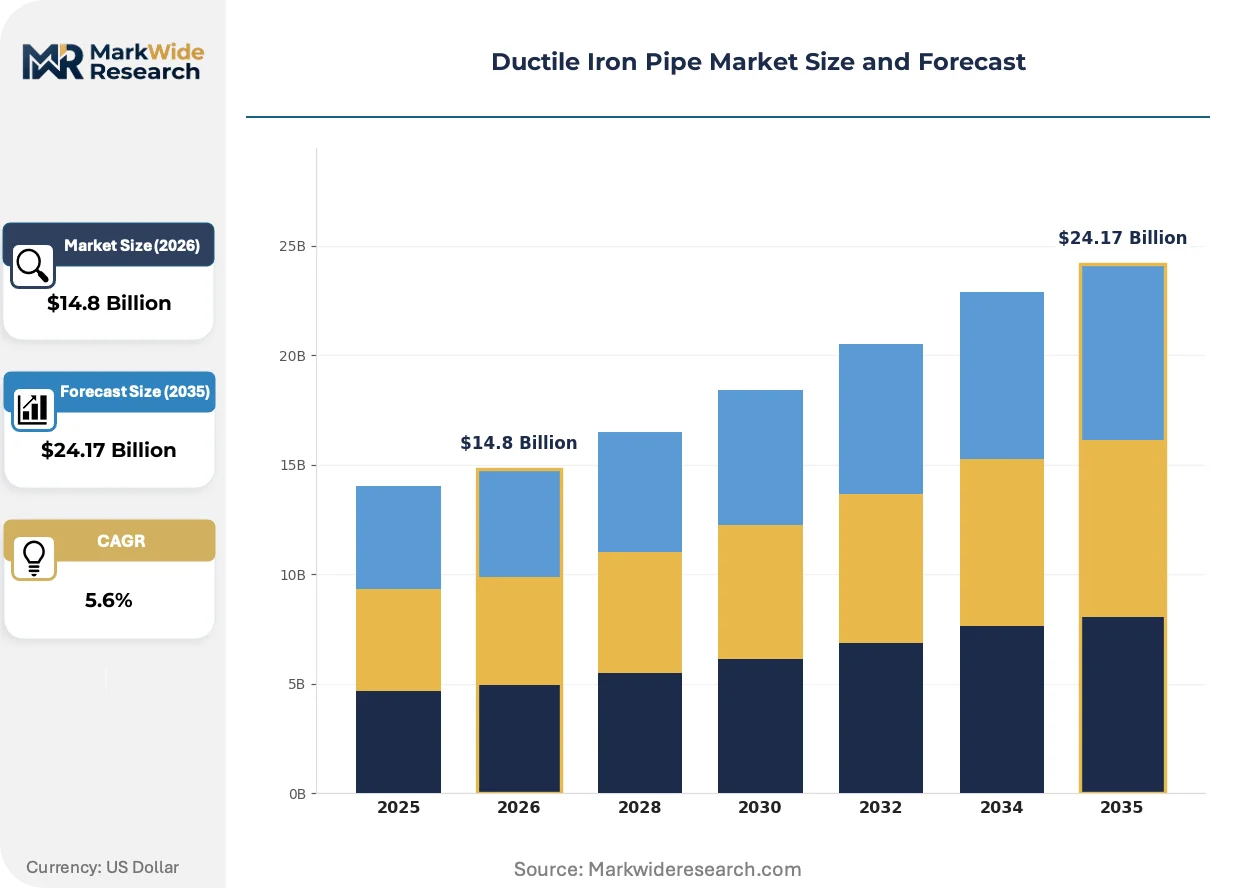
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Pipe, Non-Pressure Pipe, Coated Pipe, Fittings End User: Water Utilities, Wastewater Management, Construction, Industrial Sector Installation Type: Above Ground, Below Ground, Buried, Floating Application: Potable Water Supply, Irrigation, Fire Protection, Sewer Systems |
| Companies Covered | U.S. Pipe, Jindal SAW Ltd., American Cast Iron Pipe Company, Electrosteel Steels Ltd., Xinxing Ductile Iron Pipes Co., Ltd., Saint-Gobain PAM, Kubota Corporation, CNBM International Corporation, McWane, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ductile Iron Pipe Market Strategic Shifts & Innovations
Material science advances and procurement digitization are compressing traditional specification cycles while embedding sustainability metrics into municipal vendor selection criteria.
High-strength ductile iron grades with enhanced nodularity are absorbing structural load requirements previously reserved for steel-reinforced concrete pressure vessels. Water utilities in earthquake-prone Japanese prefectures specify these grades for trunk mains exceeding 1,200mm diameter. The technology is absorbing market share from welded steel in high-pressure transmission applications where joint flexibility reduces seismic failure risk.
REACH compliance deadlines for chemical substances in protective coatings are forcing reformulation of solvent-based linings across European foundry operations. Industrial consequences include accelerated R&D spending on waterborne epoxy alternatives and qualification testing delays. Pressure pipe segments serving aggressive soil environments in Northern Europe face the tightest compliance timelines, with Dutch and German utilities already embedding substance restrictions into technical specifications.
Buyers now unbundle installation from material supply, contracting directly with certified contractors while sourcing pipe through competitive digital platforms. Traditional distributor networks in North American municipal markets face margin compression as state-level procurement cooperatives aggregate demand and negotiate master agreements. This pattern concentrates most visibly in California and Texas water authority purchasing, where volume aggregation platforms now handle 40% of ductile iron procurement by value.
Ductile Iron Pipe Market Segmentation
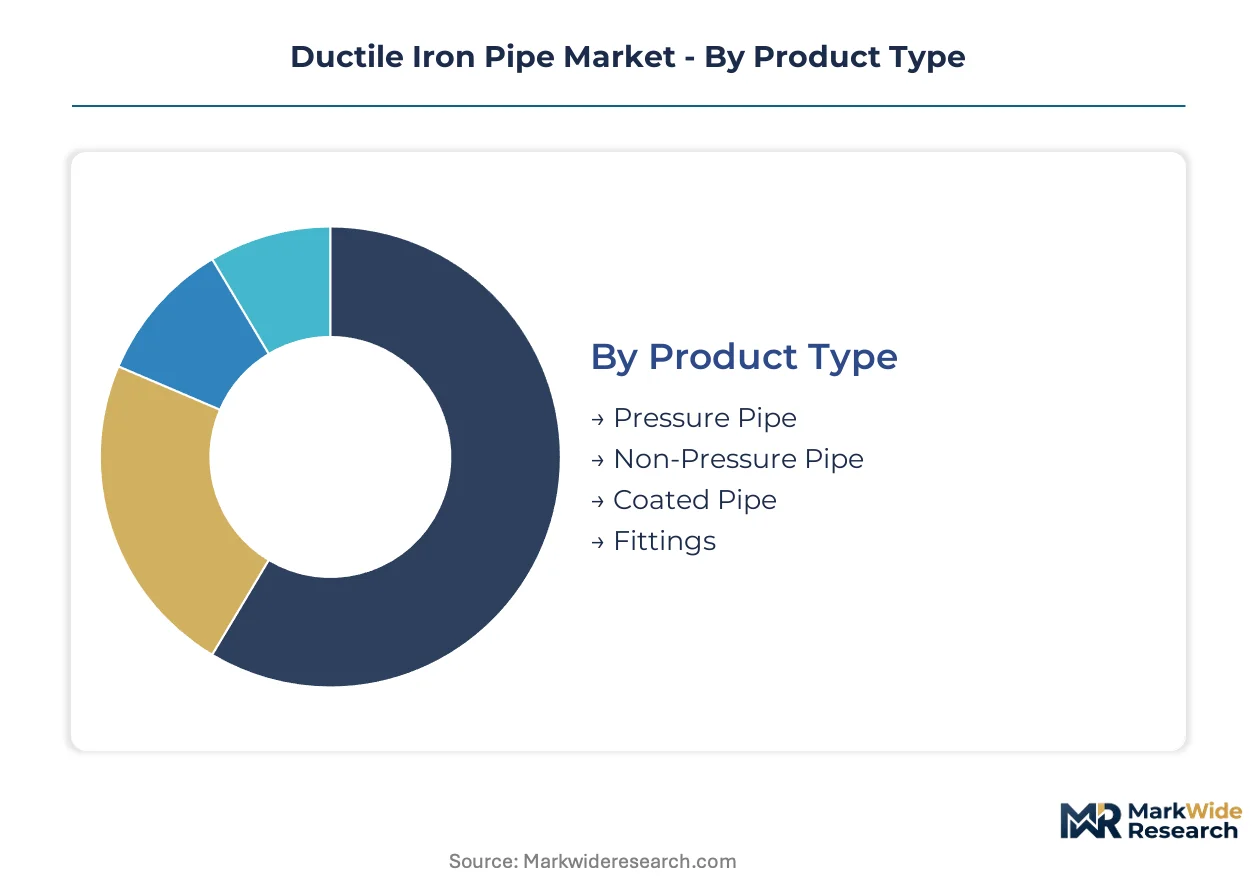
Ductile iron pipe procurement varies sharply across pressure ratings, soil conditions, and regulatory environments. Specification complexity forces foundries to maintain parallel certification portfolios while utilities prioritize corrosion resistance and seismic performance in their capital planning.
Product Type:
Standardization dominates pressure-rated systems while coating specifications introduce customization layers for aggressive environments.
- Pressure Pipe:Centrifugally cast pipe with wall thickness calibrated to AWWA C151 pressure classes (150-350 psi). Water utilities in California and Texas specify these for trunk mains where burst resistance outweighs installed cost premiums.
- Coated Pipe:Fusion-bonded epoxy or polyurethane linings extend service life in acidic soils and coastal zones. Dutch and German utilities now mandate REACH-compliant coating formulations in public tenders.
- Non-Pressure Pipe:Gravity sewer applications where PVC and concrete alternatives compete on unit economics.
- Fittings:Joint configurations and branch connections for network topology adaptation.
Leading the category by volume: Pressure Pipe. Growing fastest: Coated Pipe.
End User:
Capital allocation cycles diverge between regulated utilities with rate-base recovery and private developers with compressed project timelines.
- Water Utilities:Municipal and regional authorities with 50-100 year asset planning horizons. India's Smart Cities Mission corridors concentrate procurement in Delhi-Mumbai Industrial Corridor zones.
- Wastewater Management:Sewer district operators facing EPA consent decrees and parallel enforcement in China's Yangtze River Delta urban clusters.
- Construction:Private developers integrating distribution networks into master-planned communities.
- Industrial Sector:Process water and cooling systems for power generation and manufacturing facilities.
Water Utilities command the largest share of ductile iron procurement. Wastewater Management is expanding most quickly as consent decree deadlines accelerate replacement cycles.
Installation Type:
Below-ground burial dominates unit economics while seismic zones and floodplains force specialized engineering.
- Buried:Standard trench installation with compacted backfill for 100-year design life. Accounts for the overwhelming majority of municipal water distribution networks.
- Below Ground:Encased or tunnel-installed systems for river crossings and utility corridors.
- Above Ground:Bridge-mounted or exposed installations for temporary bypass or industrial process lines.
- Floating:Marine intake and outfall systems for coastal desalination and power plants.
Buried installation leads by installed length. Below Ground configurations are gaining share fastest in dense urban utility corridors.
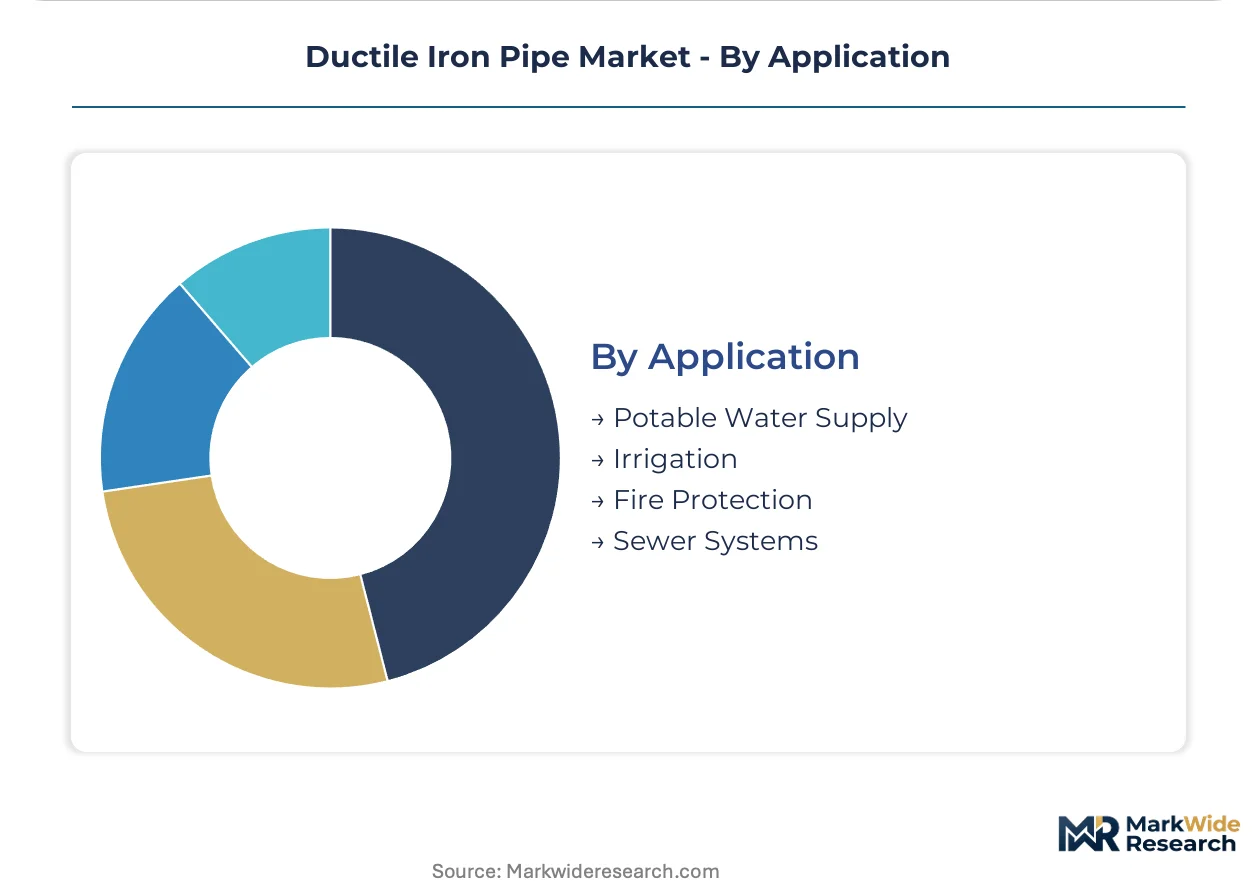
Application:
Drinking water quality mandates create specification rigidity while fire protection and irrigation tolerate broader material substitution.
- Potable Water Supply:Pressurized distribution networks governed by EPA Lead and Copper Rule revisions and India's BIS certification requirements. Corrosion-resistant linings are non-negotiable in this segment.
- Sewer Systems:Gravity and force-main applications where joint integrity prevents infiltration and exfiltration. Japan's METI-driven seismic standards now specify ductile iron for high-risk fault zones.
- Fire Protection:Standpipe and sprinkler system feeds where pressure retention is critical.
- Irrigation:Agricultural and golf course distribution with lower pressure requirements and shorter asset life expectations.
Potable Water Supply dominates capital deployment. Sewer Systems show the steepest expansion trajectory as combined sewer overflow mandates force infrastructure upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Smart Cities Mission corridors concentrate procurement in designated special economic zones, while China's Yangtze River Delta urban clusters drive foundry capacity expansion for corrosion-resistant infrastructure.
United States
California and Texas water authorities aggregate demand through volume procurement cooperatives covering 40% of ductile iron procurement by value. EPA Lead and Copper Rule revisions compel wholesale replacement of aging cast iron distribution networks across municipal systems. The Los Angeles-San Diego corridor and Houston-Gulf Coast zone anchor trunk main installations for seismic-resistant specifications.
China
Hebei and Shandong provinces maintain foundry overcapacity that creates price-floor pressure on export markets for ductile iron pipe. GB/T 13295 standards create parallel compliance pathways shaping export competitiveness for manufacturers serving multiple geographies. The Yangtze River Delta urban clusters strain legacy distribution networks as rapid urbanization accelerates infrastructure upgrades.
India
Delhi-Mumbai Industrial Corridor zones prioritize pressurized water systems with 100-year design life under Smart Cities Mission infrastructure mandates. BIS certification requirements govern product qualification for municipal procurement across urban infrastructure corridors. Maharashtra and Gujarat industrial belts concentrate demand for corrosion-resistant ductile iron systems replacing aging cast iron networks.
Japan
METI-driven pipeline standards now mandate ductile iron for high-risk fault zones across Pacific Ring of Fire municipalities. Seismic-resistant specifications extend specification influence through prefectural procurement guidelines. The Kanto and Kansai regions specify high-strength ductile iron grades for trunk mains exceeding 1,200mm diameter in earthquake-prone zones.
Germany
REACH compliance deadlines for chemical substances in protective coatings force reformulation of solvent-based linings across foundry operations. EN 545/598 standards govern wall thickness, joint design, and hydrostatic testing protocols for municipal procurement. The Ruhr industrial region and Bavarian utility networks embed substance restrictions into technical specifications for aggressive soil environments.
Ductile Iron Pipe Market Key Industry Players
North American producers anchor one tier for municipal water utility contracts; Asian specialists hold manufacturing scale advantages for export markets. The vendor base organizes around three strategic archetypes: integrated foundry-to-installation operators, coating technology specialists, and regional distribution-focused fabricators. Capacity expansion and strategic partnerships represent the dominant competitive moves as players position for carbon disclosure requirements in public tenders.
Within the integrated foundry tier, Saint-Gobain PAM and Kubota Corporation exemplify geographic specialization strategies—European foundry expertise anchoring premium coated pipe supply against Japanese seismic-resistant specification dominance. Xinxing Ductile Iron Pipes Co., Ltd. occupies a position representing Chinese manufacturing scale, with Zhengzhou-based operations reflecting the concentration of foundry capacity in Hebei and Shandong provinces. These three entities represent distinct competitive positioning vectors: premium specification leadership, seismic engineering specialization, and cost-optimized volume production.
| Leading Market Players |
|---|
| U.S. Pipe |
| Jindal SAW Ltd. |
| American Cast Iron Pipe Company |
| Electrosteel Steels Ltd. |
| Xinxing Ductile Iron Pipes Co., Ltd. |
| Saint-Gobain PAM |
| Kubota Corporation |
| CNBM International Corporation |
| McWane, Inc. |
| Others |
Cost & Logistics Intelligence
Municipal procurement cooperatives in California and Texas concentrate demand aggregation for ductile iron pipe, anchoring contract-based long-term offtake pricing that favors volume-scaled tier differentiation over spot market volatility. This buyer concentration forces foundries to absorb scrap iron cost fluctuations within fixed municipal contract structures.
Pricing Analysis
Short lead-time premiums command substantial markups over standard delivery schedules as water utilities facing EPA consent decree deadlines prioritize burst-resistant inventory availability. Pricing stratifies across premium coated pipe for aggressive soil environments, standard pressure-rated systems for trunk mains, and economy non-pressure grades where PVC alternatives constrain ceilings. Price differentiation hinges on AWWA C151 certification tier and fusion-bonded epoxy lining specifications. Cost compression in standard pressure pipe is intensifying because Hebei and Shandong foundry overcapacity feeds export price-floor pressure. Private construction developers exhibit highest price sensitivity due to compressed project timelines, while municipal water utilities prioritize 100-year design life over unit cost.
Supply Chain Analysis
Reverse logistics for ductile iron pipe center on end-of-life network recovery and scrap remelting flows, with municipal utilities increasingly mandating take-back provisions in master procurement agreements. Primary manufacturing concentrates in China, India, and the United States, with Hebei province anchoring global centrifugal casting capacity. Foundry operations draw from ferrous scrap, nodularizing agents, and REACH-compliant coating formulations as critical inputs. Single-source vulnerability pervades specialized centrifugal casting technician labor pools, constraining capacity expansion despite order backlogs. Distribution runs through state-level procurement cooperatives and traditional distributor networks, with digital platforms capturing share in direct utility contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ductile iron pipe markets are transitioning from legacy cast iron replacement cycles toward seismic-resistant and corrosion-protected specifications, with fusion-bonded epoxy coating technology displacing solvent-based linings under REACH and emerging carbon disclosure mandates.
For Market Incumbents: Anchor defensive positioning through backward integration into ferrous scrap supply and captive coating formulation capabilities, insulating margin structures from Hebei province price-floor pressure. Accelerate EN 545/598 and BIS certification parallel-track investments to compress 18-24 month qualification timelines for export markets. Prioritize direct digital procurement platform partnerships with California and Texas water authorities to bypass distributor margin compression. For New Entrants and Emerging Players: Capture white-space opportunity in REACH-compliant waterborne epoxy coating formulations for Northern European aggressive soil specifications, where incumbent reformulation delays create qualification gaps. Target India's Smart Cities Mission corridor demand in Maharashtra and Gujarat industrial belts, where BIS certification barriers filter competition. Pursue joint venture structures with established foundries to access centrifugal casting technician expertise without generational labor pool exposure. For Investors and Strategic Acquirers: The window for entry favors coating technology specialists with verified low-carbon production methods ahead of EU CSRD procurement filter implementation. Long-term viability hinges on positioning for carbon disclosure requirements that will increasingly determine supplier eligibility in public tenders. Monitor EPA Lead and Copper Rule enforcement acceleration and METI seismic specification expansion as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Supply | Captive ferrous scrap sourcing insulates margin structures from global price volatility. |
| Coating Technology Certification | REACH-compliant waterborne epoxy qualification opens premium Northern European municipal tenders. |
| Direct Digital Procurement Platform | Bypassing distributor networks captures California and Texas cooperative contract flows. |
| Seismic-Resistant Grade Development | High-nodularity ductile iron specifications penetrate Japan's METI-mandated fault zone replacements. |
| Multi-Jurisdictional Certification Parallel-Track | Simultaneous AWWA C151, EN 545, and BIS pursuit compresses 18-24 month export qualification cycles. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with primary interviews conducted among foundry operations managers, municipal water utility procurement directors, coating formulation chemists, and centrifugal casting technicians. AWWA C151 certification databases, EPA enforcement action records, and India's BIS registration directories provided secondary validation. Foundry capacity utilization data from Hebei and Shandong provinces, alongside EN 545/598 compliance registries, supplied production-side triangulation. Bottom-up unit economics and top-down sectoral expenditure patterns were reconciled to calibrate market size estimates.
Data-stream reconciliation across shipment volumes, installed base depreciation schedules, and municipal capital improvement plans informed the analytical framework across the projection horizon. Segmentation modeling incorporated pressure class tier, coating specification, installation type, and regional regulatory cluster dimensions. CAGRs were derived from trend extrapolation of replacement cycle acceleration and urban infrastructure investment patterns. Scrap iron price volatility indices and seismic specification adoption curves served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese foundry capacity rationalization, REACH coating compliance deadline shifts, and generational technician labor pool attrition. Forecasts reflect documented assumptions regarding EPA enforcement continuity and Smart Cities Mission funding flows. Practitioners should monitor scrap iron futures curves, METI specification expansion announcements, and EU CSRD procurement filter implementation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Steel Products Market
Building Materials
LAMEA Engineered Stone Market
Building Materials
Europe Building and Construction Sheets Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
Cement Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
Granite Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
Spain Cement Market