
 Roof Cover Boards Market | 2026-2036
Roof Cover Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Roof Cover Boards Market Analytics
Polyisocyanurate is shifting from premium niche to default specification in low-slope commercial roofing, displacing fiberboard in projects where thermal resistance and compressive strength carry equal weight. Owens Corning leverages its vertically integrated glass-mat supply to control gypsum cover board input costs across North American plants. Johns Manville sustains technical leadership through in-house polymer chemistry capabilities that differentiate its polyiso product line from commodity competitors.
Roof cover boards are rigid substrate layers installed between structural roof decks and waterproofing membranes, typically manufactured from gypsum, polyisocyanurate foam, fiberboard, or plywood with nominal thicknesses ranging from 0.25 to 1.0 inch and compressive strengths from 30 to 1,000 psi depending on application load requirements. Their primary industrial purpose is to protect insulation and membrane systems from foot traffic, hail impact, and thermal cycling stress while providing a uniform fastening surface. Polyisocyanurate cover boards command the dominant share of new commercial specifications due to superior R-value per inch, though gypsum variants retain strong positions in fire-rated assemblies where ASTM E119 compliance is mandatory. Mechanically attached installation leads volume in high-wind zones across the Gulf Coast and Atlantic seaboard, while adhered systems gain ground in urban infill projects where fastening penetration conflicts with structural constraints.
The National Roofing Contractors Association publishes installation standards that directly influence contractor specification behavior, while ASTM International maintains material performance benchmarks for flexural strength, dimensional stability, and moisture absorption that govern product qualification for commercial warranties. Municipal building codes in Miami-Dade County and similar wind-borne debris regions enforce uplift resistance requirements that effectively mandate cover board use in qualifying roof assemblies. Stakeholders must monitor evolving state-level energy stretch codes and their interaction with federal tax incentive programs for building envelope improvements, as these policy layers increasingly determine whether cover boards are treated as optional upgrades or baseline requirements in new construction and reroofing decisions.
Market Dynamics
Energy stretch codes in California, New York, and Massachusetts are compressing thermal performance baselines for commercial roofing assemblies, converting cover boards from optional upgrades to mandatory substrate layers in new construction and reroofing projects.
Growth Catalysts
- Cool roof mandates:EPA energy efficiency standards tighten thermal resistance requirements across southern US states, accelerating specification of high-R-value polyisocyanurate cover boards in single-ply membrane systems.
- Hail belt expansion:Insurance underwriters in Texas, Colorado, and Oklahoma increasingly require impact-resistant roof assemblies, driving adoption of dense gypsum and cementitious cover boards for membrane protection.
- Mechanical attachment:Miami-Dade County wind uplift codes and similar ordinances in coastal Florida jurisdictions effectively mandate cover board use to qualify for reduced insurance premiums.
Market Restraints
- Petrochemical input volatility:Polyisocyanurate production depends on methylene diphenyl diisocyanate and polyol feedstocks, exposing margins to crude oil and natural gas price swings.
- Gypsum supply concentration:High-purity synthetic gypsum from flue-gas desulfurization concentrates among power utilities in the Ohio River Valley, creating regional supply vulnerability for gypsum cover board manufacturers.
- Fire-rated assembly complexity:ASTM E119 compliance testing timelines extend 12-18 months for new product formulations, slowing innovation cycles in gypsum and mineral wool cover board categories.
Strategic Opportunities
- Inland Southeast penetration:Tennessee, Georgia, and Alabama commercial construction lags national cover board adoption rates by 15-20 percentage points, presenting white-space expansion for regional distributors.
- Photovoltaic integration:Rooftop solar mounting systems require compressive-resistant substrates, creating specification pull for high-density cover boards in California and Arizona utility-scale installations.
- Inflation Reduction Act incentives:Federal tax deductions for building envelope improvements expand cover board eligibility in cost segregation analyses, shifting contractor specification behavior in 2024-2025 project pipelines.
Industry Challenges
- Installer certification gaps:NRCA ProCertification for cover board installation remains underpenetrated outside major metropolitan markets, creating quality variance and warranty dispute exposure.
- Adhesive compatibility testing:Single-ply membrane manufacturers require project-specific bond testing with cover board substrates, adding 2-4 weeks to procurement cycles in adhered system specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roof Cover Boards Market |
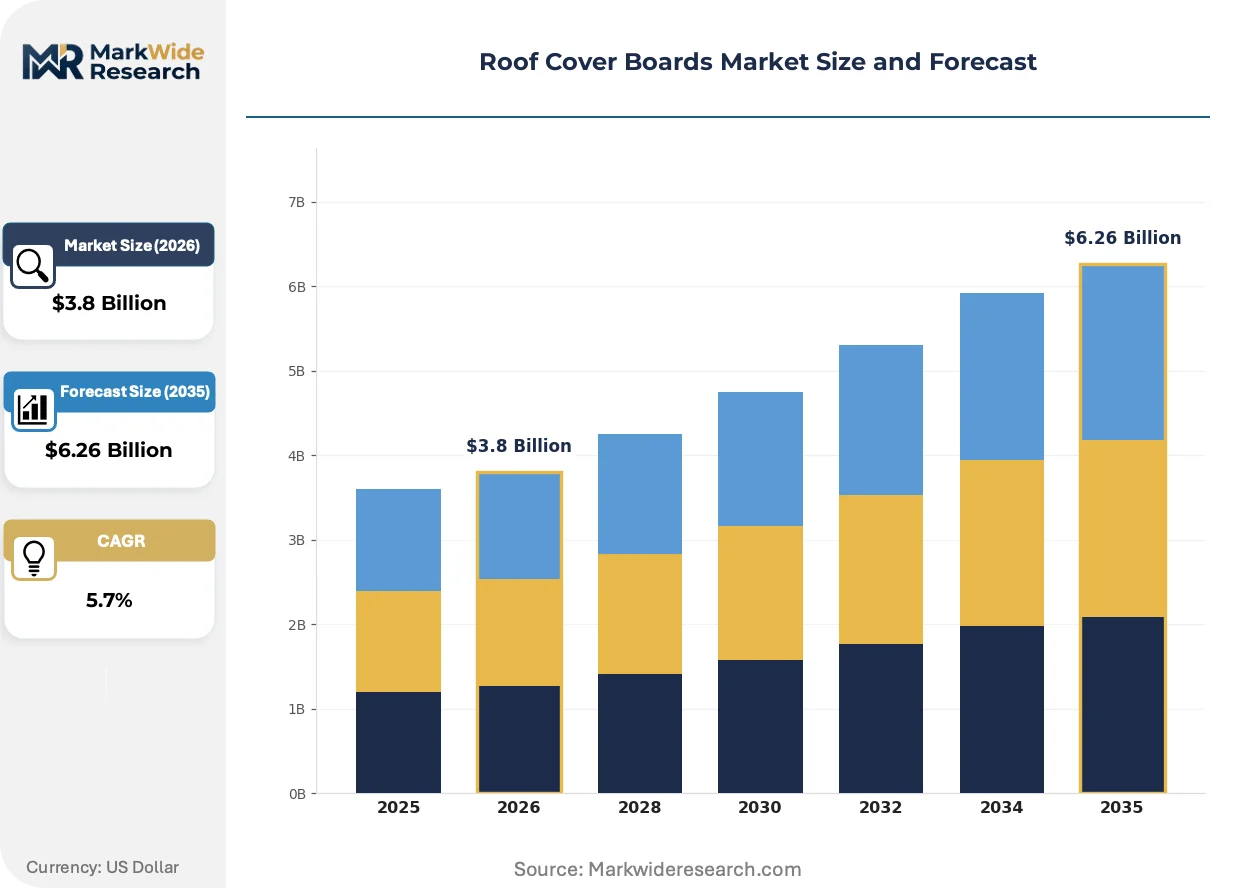
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, Polyisocyanurate, Gypsum, Fiberboard Installation Type: Mechanically Attached, Adhered, Ballasted, Hybrid End User: Commercial Buildings, Industrial Facilities, Residential Homes, Agricultural Structures Distribution Channel: Direct Sales, Wholesalers, Retailers, Online Platforms |
| Companies Covered | CertainTeed, GAF Materials, Atlas Roofing, Owens Corning, IKO Industries, TAMKO Building Products, Johns Manville, Carlisle Companies, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roof Cover Boards Market Evolving Landscape
Material science advances and code harmonization efforts are compressing the performance gap between commodity and premium cover board categories, while procurement digitization accelerates specification transparency across fragmented contractor networks.
Factory-applied facer technologies are decentralizing supply chain control in polyisocyanurate cover board manufacturing. Glass-mat and foil facers previously sourced through third-party converters are now produced through captive coating lines at major insulation plants. This backward integration into facer production compresses lead times from 6-8 weeks to 10-14 days for custom thickness orders. Regional distributors in Texas and Arizona report faster project turnaround as a result.
California Title 24 energy code updates and parallel stretch code adoptions in New York State are mandating R-value targets that effectively require cover board layers in most commercial low-slope assemblies. The industrial consequence is specification lock-in for thermal-resistant substrates in new construction permits. Building departments in Los Angeles County and New York City now reject permit applications lacking documented cover board specifications for roofs exceeding 10,000 square feet.
Specification authority is migrating from general contractors to roofing consultants and envelope commissioning agents. Third-party specifiers now control substrate selection in 60% of large commercial projects, displacing traditional distributor influence. This shift concentrates purchasing power among national engineering firms with master specifications favoring certified products. The pattern is most visible in healthcare and data center verticals where envelope performance guarantees carry liquidated damages clauses.
Roof Cover Boards Market Segmentation
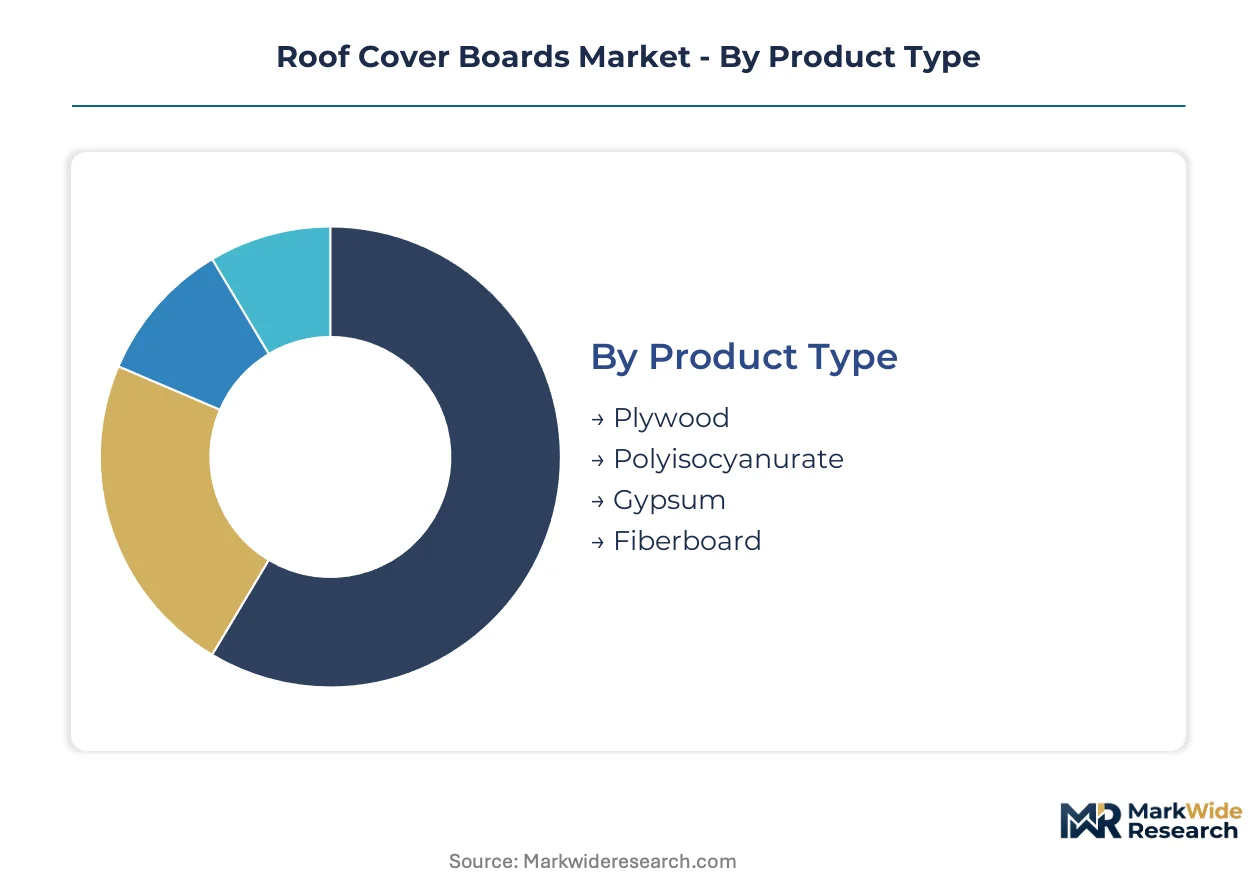
Roof cover board specification patterns diverge sharply across material chemistry, attachment methodology, and building typology. Procurement channels and end-use requirements create distinct demand profiles that manufacturers must navigate through differentiated product positioning and distribution investment.
Product Type:
Supply concentration among integrated insulation manufacturers favors polyisocyanurate and gypsum variants with captive raw material access, while fiberboard and plywood depend on fragmented commodity feedstock markets.
- Polyisocyanurate:Closed-cell foam core laminated with glass-mat or foil facers delivers R-values exceeding 6.0 per inch. Demand concentrates in California and Texas commercial low-slope roofing where Title 24 and utility rebate programs mandate high thermal resistance assemblies. Owens Corning and Johns Manville control dominant manufacturing positions through backward integration into MDI and glass-mat supply.
- Gypsum:Calcium sulfate dihydrate core with reinforced facers provides fire-rated substrate performance for ASTM E119 assemblies. Specifications cluster in healthcare and high-rise construction across Miami-Dade County and Chicago where code-mandated fire resistance trumps thermal efficiency priorities. Synthetic gypsum from Ohio River Valley flue-gas desulfurization operations feeds regional production concentration.
- Fiberboard:Cellulose-based rigid substrate manufactured from wood fibers and asphalt binders serves budget-conscious reroofing applications.
- Plywood:Structural wood panel substrate retains niche specification in steep-slope residential and agricultural applications requiring nail-base fastening surfaces.
Polyisocyanurate absorbs the bulk of installed capacity; gypsum is expanding most quickly in fire-rated verticals.
Installation Type:
Attachment methodology selection tracks wind zone exposure, structural deck condition, and membrane manufacturer warranty requirements rather than cost optimization alone.
- Mechanically Attached:Fastener plates and screws secure cover boards directly to steel or concrete decks at engineered spacing patterns. Gulf Coast and Atlantic seaboard jurisdictions specify this method exclusively for high-velocity hurricane zones under Florida Building Code and Miami-Dade County protocols. Fastener pull-through resistance testing governs product qualification.
- Adhered:Low-rise polyurethane or asphalt-based adhesives bond cover boards to insulation and membranes without deck penetration. Urban infill projects in New York City and Boston specify adhered systems to avoid penetrating post-tensioned concrete slabs. Adhesive compatibility testing with single-ply membranes extends procurement cycles.
- Ballasted:Loose-laid cover boards weighted with stone ballast or pavers suit low-wind applications with structural load capacity.
- Hybrid:Combined mechanical and adhesive attachment addresses complex roof geometries and perimeter uplift zones.
Mechanically attached systems dominate coastal specifications; adhered methods are climbing the fastest in dense urban construction.
End User:
Building typology determines load requirements, warranty expectations, and specification authority concentration among architects, consultants, or contractors.
- Commercial Buildings:Office, retail, and institutional low-slope roofing drives premium polyisocyanurate and gypsum specification. Third-party envelope commissioning agents control substrate selection in data center and healthcare verticals where performance guarantees carry liquidated damages exposure.
- Industrial Facilities:Manufacturing plants and warehouses prioritize compressive strength for maintenance traffic and equipment loads. Specifications favor high-density cover boards with 100+ psi ratings.
- Residential Homes:Steep-slope and low-slope residential applications specify thinner, lower-density substrates.
- Agricultural Structures:Barns, storage facilities, and processing plants use cost-optimized fiberboard or plywood where fire ratings are not mandated.
Commercial buildings command the largest volume share; industrial facilities are gaining share fastest through reshoring-driven construction.
Distribution Channel:
Channel selection reflects project scale, specification complexity, and contractor purchasing behavior across national, regional, and local market tiers.
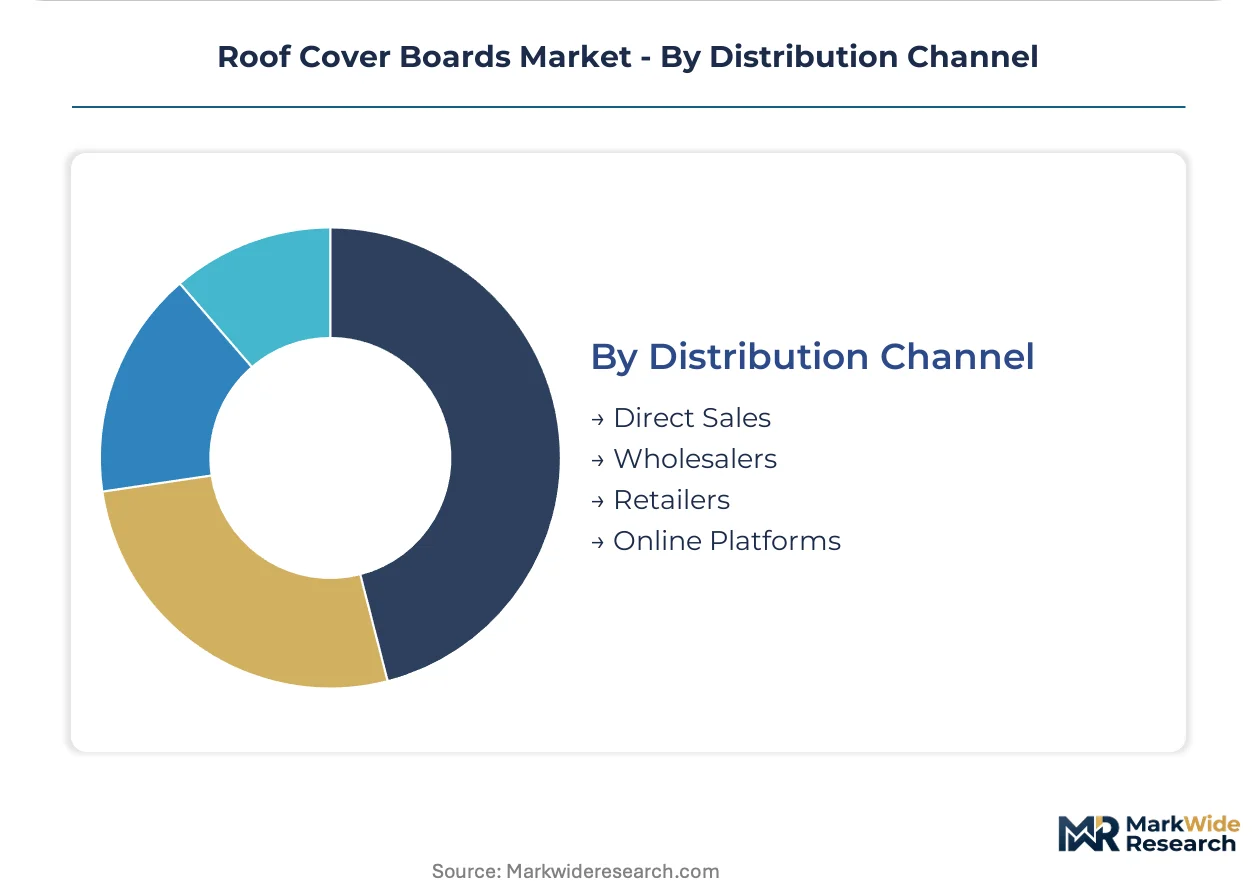
- Direct Sales:Manufacturers serve national roofing contractors and design-build firms with project-specific pricing and technical support. Large commercial projects exceeding 50,000 square feet negotiate direct procurement terms.
- Wholesalers:Regional distributors stock standard thicknesses and maintain contractor credit relationships. Beacon Roofing Supply and ABC Supply control extensive branch networks.
- Retailers:Big-box and specialty building material retailers serve residential and small commercial repair markets.
- Online Platforms:Digital procurement channels facilitate specification comparison and price transparency for standardized products.
Wholesalers handle the majority of transaction volume; direct sales are expanding most quickly in large commercial and industrial project segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial building owners in the southern and western United States drive the majority of cover board specification, with extreme heat exposure accelerating membrane degradation and converting thermal-resistant substrates from optional upgrades to baseline requirements in low-slope roofing assemblies.
United States
EPA cool roof mandates and evolving energy efficiency standards tighten thermal performance requirements across southern states, accelerating polyisocyanurate cover board adoption in single-ply membrane systems. The Inflation Reduction Act expands federal tax deductions for building envelope improvements, shifting contractor specification behavior in 2024-2025 project pipelines. Los Angeles County building departments now reject permit applications lacking documented cover board specifications for commercial roofs exceeding 10,000 square feet.
Canada
Energy stretch code adoptions in Ontario and British Columbia compress thermal performance baselines for commercial roofing, converting cover boards from optional upgrades to mandatory substrate layers in new construction and reroofing projects. The country's national building code references ASTM International material performance benchmarks for flexural strength and dimensional stability that govern product qualification for commercial warranties. Toronto and Vancouver commercial construction markets concentrate specification authority among envelope commissioning agents in healthcare and data center verticals.
Mexico
Industrial reshoring-driven construction in Nuevo León and the Bajío Region expands demand for compressive-resistant substrates in manufacturing facilities and warehouses. Mexico's national construction standards increasingly reference international thermal performance benchmarks as multinational tenants require building envelope specifications matching US and Canadian operations. Monterrey industrial clusters specify high-density cover boards with 100+ psi ratings for maintenance traffic and equipment loads.
Germany
EU Green Deal implementation and national energy efficiency regulations tighten building envelope requirements for commercial structures, creating specification pull for thermal-resistant roofing substrates. REACH chemical regulations and CE marking requirements govern material composition and fire-rated performance in gypsum and mineral wool cover board categories. Industrial construction in North Rhine-Westphalia and Bavaria concentrates demand for substrates meeting combined thermal and compressive performance standards.
China
Dual carbon goals and GB standards for building energy efficiency accelerate specification of high-R-value roofing assemblies in commercial construction across Yangtze River Delta and Pearl River Delta clusters. The Ministry of Ecology and Environment enforces evolving standards for construction material emissions and thermal performance that influence substrate selection in new building permits. Shanghai and Shenzhen building departments increasingly require documented thermal resistance calculations for low-slope commercial roofing exceeding specified square footage thresholds.
Roof Cover Boards Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated insulation manufacturers commanding dominant positions in polyisocyanurate and gypsum variants through captive raw material access while fiberboard and plywood suppliers depend on fragmented commodity feedstock markets. Market structure reflects supply concentration among backward-integrated producers with in-house polymer chemistry and glass-mat production capabilities. Three archetypes define competitive positioning: vertically integrated material science leaders controlling MDI and facer supply, regional gypsum processors leveraging synthetic feedstock proximity, and specialty distributors consolidating contractor relationships through technical service investment. Capacity expansion and specification authority migration toward third-party envelope consultants represent the dominant competitive vectors reshaping procurement channels.
Within the integrated-manufacturer tier, Owens Corning and Johns Manville exemplify archetypes of supply chain control and technical differentiation respectively. Owens Corning occupies a position anchored by captive glass-mat production feeding gypsum cover board operations across North American plants. Johns Manville represents the polymer chemistry-led model, with in-house capabilities distinguishing product lines from commodity competitors. Carlisle Companies sits within the diversified building materials constellation, leveraging cross-product specification relationships in commercial roofing systems. These three anchors illustrate how raw material integration and technical service investment separate premium positioning from price-driven alternatives.
| Leading Market Players |
|---|
| CertainTeed |
| GAF Materials |
| Atlas Roofing |
| Owens Corning |
| IKO Industries |
| TAMKO Building Products |
| Johns Manville |
| Carlisle Companies |
| Sika AG |
| Others |
Value Network & Pricing Analysis
Large commercial roofing contractors and national design-build firms concentrate purchasing power through direct procurement negotiations, anchoring the market in project-based transactional pricing where volume commitments unlock preferential terms. This buyer concentration compresses margins for commodity cover board tiers while insulating premium polyisocyanurate and fire-rated gypsum variants from price erosion.
Pricing Analysis
High-volume mechanically attached specifications in Gulf Coast wind zones trade at thinner margins than low-volume adhered systems for urban infill projects. Price differentiation separates ASTM E119-certified fire-rated assemblies from standard thermal-performance grades, with certification investment creating sustainable premium capture. Pricing pressure stems from petrochemical feedstock volatility in MDI and polyol inputs, squeezing polyisocyanurate producer margins. Budget-conscious reroofing contractors in the Inland Southeast exhibit highest price sensitivity, while envelope commissioning agents in healthcare and data center verticals prioritize performance guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from national roofing contractors and major distributors mandate multi-supplier qualification for MDI, glass-mat facers, and synthetic gypsum feedstocks. Supply concentrates in the United States, Canada, and Germany, with captive production of glass-mat and polymer chemistry capabilities anchoring integrated manufacturer positions. Raw material dependencies rest on methylene diphenyl diisocyanate from Gulf Coast petrochemical complexes, high-purity synthetic gypsum from Ohio River Valley flue-gas desulfurization operations, and specialized glass fibers from southeastern US melting furnaces. Single-source vulnerability in synthetic gypsum concentrates regional supply risk for gypsum cover board manufacturers. Distribution runs through Beacon Roofing Supply and ABC Supply branch networks, with direct sales expanding in large commercial projects exceeding 50,000 square feet.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The roof cover board market sits in a material-transition phase as polyisocyanurate displaces fiberboard from premium commercial specifications, driven by Title 24 and energy stretch code mandates that encode thermal performance requirements into permit approvals.
For Market Incumbents: Deploy captive glass-mat and polymer chemistry capabilities to defend specification authority against commodity competitors. Owens Corning and Johns Manville demonstrate how backward integration into facer production and in-house MDI formulation insulates margin structures from petrochemical volatility. Incumbents should accelerate certification investment for ASTM E119 fire-rated assemblies, as building departments in Los Angeles County and Miami-Dade County increasingly reject permits lacking documented substrate specifications. For New Entrants and Emerging Players: The premium-to-economy price gap in adhered system specifications presents white-space opportunity for regional specialists with adhesive compatibility testing capabilities. Tennessee, Georgia, and Alabama commercial construction lags national cover board adoption by 15-20 percentage points, offering penetrable expansion terrain. New entrants should target photovoltaic integration projects in California and Arizona, where rooftop solar mounting systems require compressive-resistant substrates and specification pull concentrates among EPC contractors rather than incumbent distributor relationships. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with captive raw material access and established envelope commissioning agent relationships. Long-term viability hinges on positioning for continued code harmonization that converts cover boards from optional upgrades to mandatory substrate layers. Acquisition targets should demonstrate certified product portfolios and technical service infrastructure serving healthcare and data center verticals. The signal to watch is state-level energy stretch code adoption velocity, as California, New York, and Massachusetts precede broader national pattern.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Facer Production | Captive glass-mat supply compresses lead times from 6-8 weeks to 10-14 days for custom orders. |
| ASTM E119 Certification Investment | Fire-rated assembly qualification opens specification pathways in Miami-Dade County and Chicago high-rise construction. |
| Photovoltaic Substrate Development | High-density cover boards address compressive loads from utility-scale rooftop solar mounting systems in California installations. |
| Regional Distribution Expansion | Tennessee, Georgia, and Alabama branch networks capture underpenetrated Inland Southeast commercial construction demand. |
| Envelope Commissioning Agent Partnership | Third-party specifiers now control substrate selection in 60% of large commercial projects with liquidated damages exposure. |
Research Methodology
Independent corroboration across primary interviews with roofing contractors, envelope commissioning agents, and distribution channel managers, combined with secondary validation of ASTM International standards documentation and National Roofing Contractors Association technical bulletins, underwrites the qualitative findings. The analysis draws from bottom-up project pipeline tracking and top-down construction permit data triangulation. Primary fieldwork engaged plant managers at integrated insulation manufacturers, procurement leads at national roofing contractors, and specification directors at engineering firms controlling master specifications. Secondary sources include building department permit databases, EPA energy efficiency standard filings, and SEC 10-K disclosures from publicly traded building materials companies.
Comparable-period anchoring to historical specification patterns across the 2019-2024 window informs the projection framework. The analytical model segments demand by material chemistry, attachment methodology, building typology, and distribution channel, with additional dimensioning by wind zone exposure and regulatory jurisdiction. CAGRs derive from regression analysis of permit-approval trends and contractor purchasing behavior shifts. Industry-specific forecast inputs include Title 24 adoption velocity, Inflation Reduction Act tax incentive utilization rates, and single-ply membrane manufacturer warranty requirement evolution.
Underlying measurement precision varies by segment; polyisocyanurate and gypsum cover board volumes carry tighter precision than fiberboard and plywood categories due to concentrated manufacturer reporting. Forecasts reflect assumptions regarding continued energy code tightening and petrochemical input cost stability. Deviation in MDI pricing volatility or federal tax incentive program extension would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Lightweight Precast Wall Panel Market
Building Materials
China Aluminum Door and Window Market
Building Materials
GRC Cladding Market
Building Materials
Global White Cement Market
Building Materials
Canada Architectural Coatings Market
Building Materials
Concrete Admixtures Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Long Steel Market
Building Materials
Africa Aluminum Door and Window Market
Building Materials
Cladding Market
Building Materials
Composite Decking and Railing Market
Building Materials
Aluminum Door and Window Market
Building Materials
Dry Mix Mortar Market
Building Materials
US Cement Tiles Market