
 Italy Construction Market | 2026-2036
Italy Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Construction Market Outlook
Multi-source procurement for specialty engineering is realigning how Italian infrastructure consortia form around complex tunneling and transport projects. Webuild S.p.A. leverages its transnational project portfolio to sustain bidding power on high-speed rail corridors. Saipem S.p.A. anchors offshore energy construction capabilities that differentiate its positioning in Mediterranean markets.
Italy construction encompasses the physical assembly of buildings and civil works using reinforced concrete, steel framing, masonry systems, and geotechnical stabilization, with structural materials serving load-bearing functions and finishing materials providing thermal and aesthetic closure. Residential application maintains the largest volume base, though infrastructure commands premium margins on public-private partnerships and EU-funded megaprojects. Building Information Modeling technology leads efficiency gains across design-bid-build workflows, while green building methods attract Superbonus-subsidized renovation demand.
Italy's Ministry of Infrastructure and Transport coordinates national building codes with EU Green Deal energy performance standards, and CE marking requirements govern structural material compliance across domestic supply chains. The Superbonus mechanism channels fiscal stimulus into deep energy retrofits, reshaping contractor specialization toward thermal envelope upgrades. Stakeholders must track how EU cohesion fund allocations and evolving tax credit rules alter project bankability for residential and industrial segments alike.
Market Dynamics
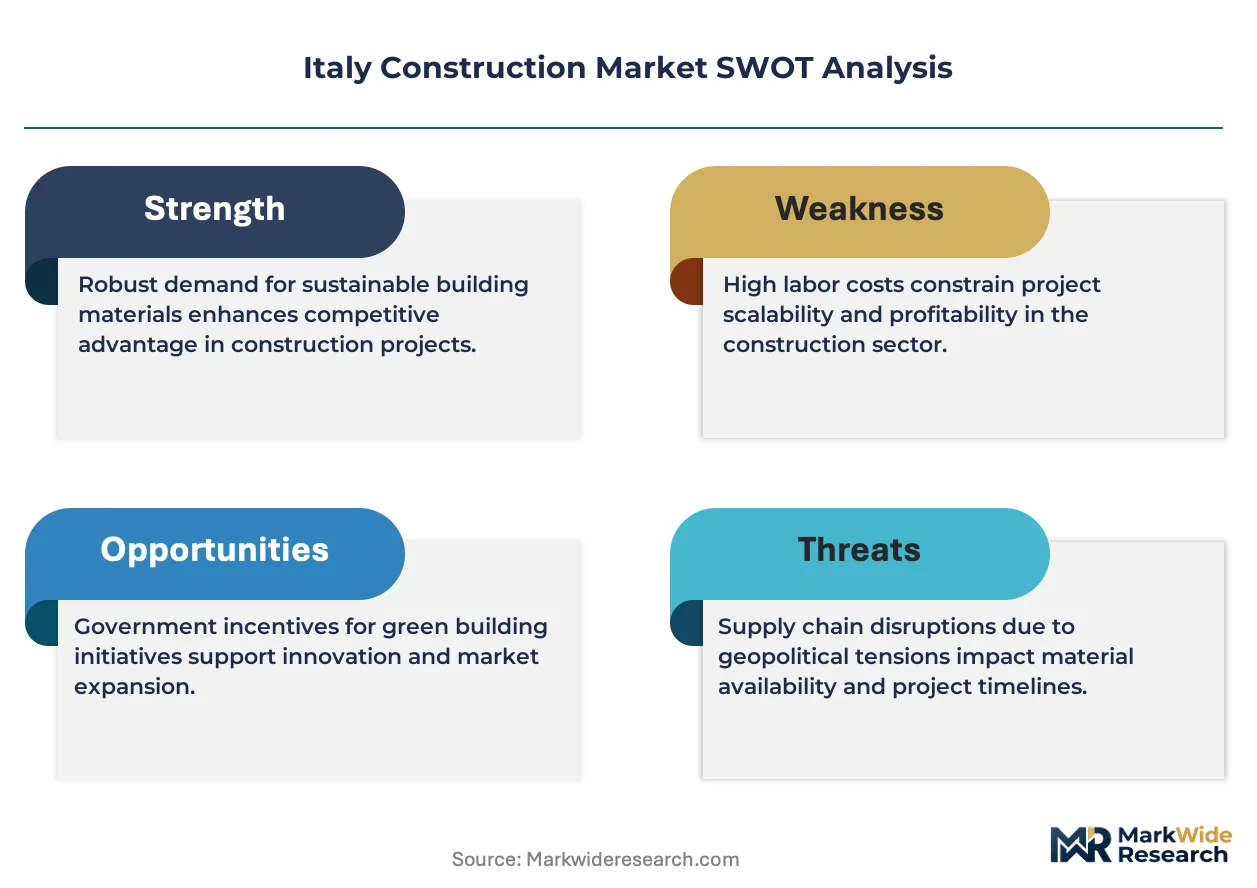
Italy's Superbonus tax credit mechanism is restructuring contractor specialization and procurement patterns across residential renovation, redirecting capital flows toward deep energy retrofits and thermal envelope upgrades.
Growth Catalysts
- Superbonus 110%:The fiscal incentive scheme channels public funds into building energy efficiency, creating guaranteed payment streams that reduce project bankability risk for renovation contractors.
- EU Green Deal alignment:National building codes now integrate EU-mandated energy performance standards, accelerating demand for certified low-carbon materials and construction methods.
- Milan-Rome housing corridor:Residential developers concentrate new stock construction around these metropolitan nodes, sustaining volume demand for reinforced concrete and masonry systems.
Market Restraints
- Steel and cement input volatility:Energy-intensive material production faces carbon border adjustment pressures and natural gas price fluctuations, compressing margins on fixed-price public contracts.
- Specialized engineering talent scarcity:Tunneling and transport megaprojects compete for limited geotechnical expertise, extending bid preparation timelines and raising personnel costs.
- Superbonus administrative complexity:Tax credit transfer mechanisms and compliance documentation create friction in contractor cash flow management and project scheduling.
Strategic Opportunities
- Southern Italy infrastructure gap:EU cohesion fund allocations target transport and energy networks in Calabria, Sicily, and Puglia, opening procurement channels outside northern concentration zones.
- Building Information Modeling integration:Design-bid-build workflows increasingly mandate digital twin capabilities, creating service revenue streams for technology-enabled contractors.
- Offshore wind foundation demand:Mediterranean energy transition projects require specialized marine construction expertise that Italian contractors can export to Spanish and Greek markets.
Industry Challenges
- BIM certification timelines:Workforce upskilling for digital design coordination lags project award schedules, forcing reliance on subcontracted specialist firms.
- CE marking compliance fragmentation:Structural material verification across multi-source procurement networks creates documentation bottlenecks and quality assurance gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Construction Market |
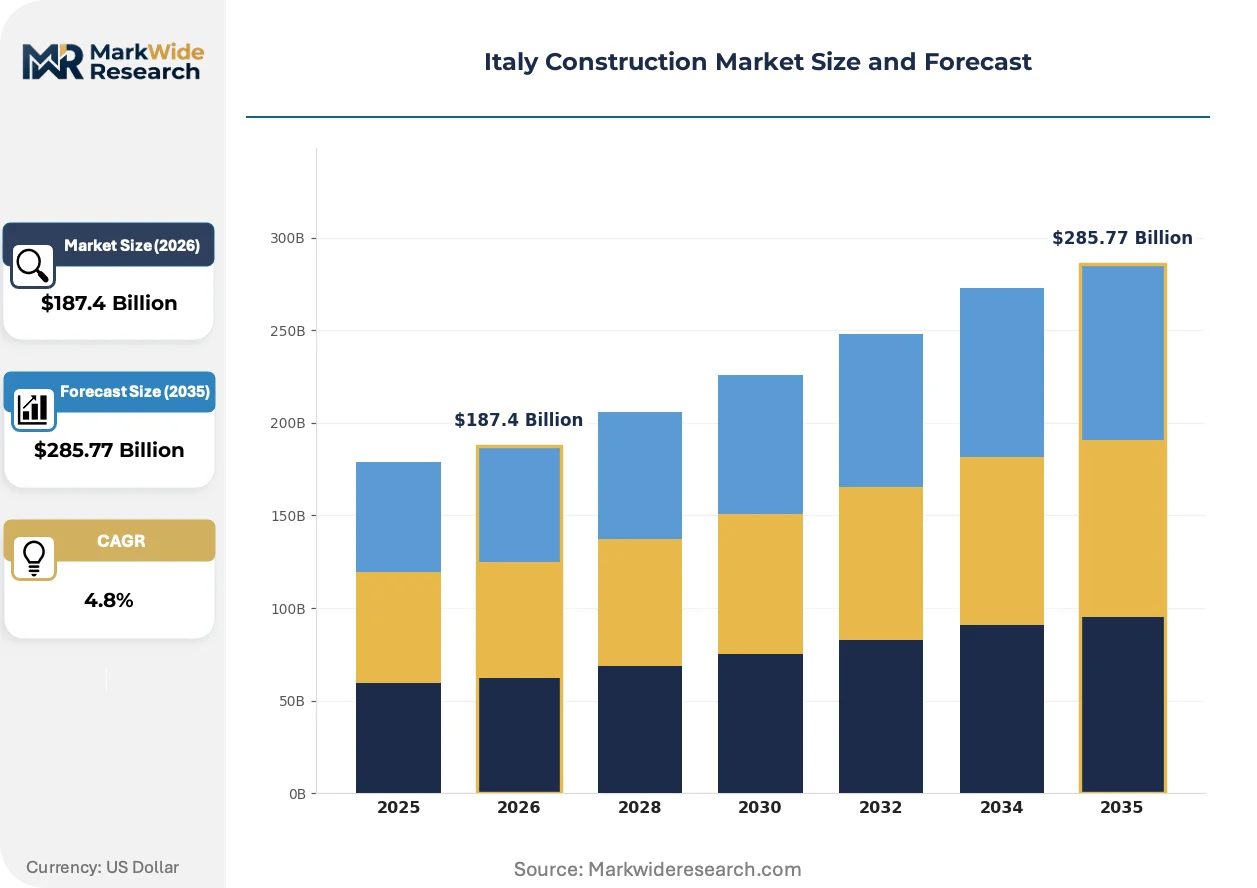
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Materials, Finishing Materials, Heavy Equipment, Construction Chemicals Application: Residential, Commercial, Infrastructure, Industrial End User: Contractors, Developers, Government Agencies, Architects Technology: Building Information Modeling, Precast Construction, Green Building, Traditional Methods |
| Companies Covered | Webuild S.p.A., Saipem S.p.A., Salcef Group S.p.A., Maire Tecnimont S.p.A., Itinera S.p.A., Impresa Pizzarotti & C. S.p.A., Ghella S.p.A., Trevi S.p.A., Rizzani de Eccher S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Construction Market Strategic Shifts
Digital fabrication and material traceability systems are compressing traditional design-construction handoffs, while regulatory pressure on embodied carbon reshapes specification standards across public procurement.
Cross-laminated timber and engineered wood products are unifying structural and aesthetic functions in mid-rise residential construction. Lombardy and Veneto developers specify these systems for Superbonus-eligible projects. The technology is unifying supply chains previously segmented between concrete framers and interior finish contractors.
EU Green Deal energy performance standards now govern Italy's national building code revisions through the Ministry of Infrastructure and Transport. Industrial consequence includes mandatory thermal bridge calculation and airtightness testing for renovation permits. Deep retrofit contractors in Emilia-Romagna and Tuscany are acquiring blower-door certification capacity to maintain bid eligibility.
Public-sector clients now unbundle design, construction, and facility management phases that previously traveled as single-source design-build contracts. Municipal housing authorities in Turin and Bologna pilot separated procurement for energy performance guarantees. This restructuring is most visible in social housing renovation, where ESCO-style service contracts displace traditional general contractor arrangements.
Italy Construction Market Segmentation
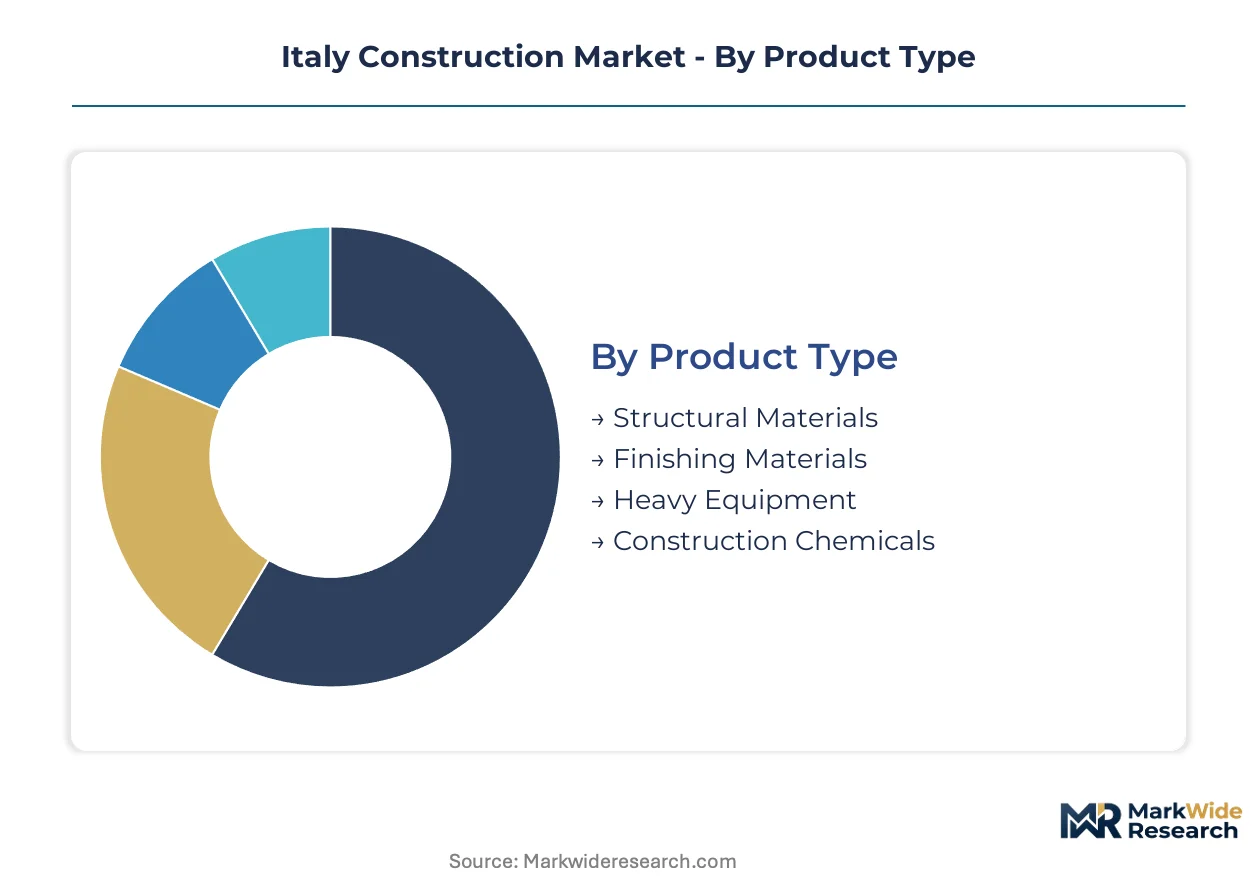
Construction market segmentation reveals how capital flows, regulatory incentives, and technical capabilities concentrate across distinct procurement channels. Italian contractors align specialization with segment-specific margin profiles and project bankability requirements.
Product Type:
Capital intensity varies sharply across material categories, with heavy equipment and structural materials demanding the largest upfront investment in manufacturing capacity and logistics infrastructure.
- Structural Materials:Reinforced concrete, structural steel, and engineered masonry systems form the load-bearing skeleton of buildings and civil works. Demand clusters around Milan-Rome residential corridors and northern infrastructure megaprojects, where EU-funded transport schemes sustain volume procurement.
- Heavy Equipment:Excavators, tower cranes, and tunnel boring machines represent the highest capital commitment per unit, with fleet utilization rates determining contractor profitability on fixed-price public contracts. Northern Italian consortia dominate procurement for high-speed rail and Alpine tunneling schemes.
- Finishing Materials:Thermal insulation, cladding systems, and interior surface products complete building envelopes. Superbonus eligibility criteria drive specification toward certified low-carbon products.
- Construction Chemicals:Admixtures, waterproofing compounds, and grouting materials enhance material performance. Specialty formulations for marine environments support offshore wind foundation projects.
Structural materials absorb the bulk of installed capacity; heavy equipment is expanding most quickly as infrastructure investment accelerates.
Application:
Margin profiles diverge across application types, with infrastructure and industrial segments commanding premium pricing on complex engineering while residential maintains volume scale.
- Infrastructure:Transport networks, energy systems, and water management facilities require specialized geotechnical and tunneling expertise. EU cohesion fund allocations target southern Italy gaps in Calabria, Sicily, and Puglia.
- Residential:Single-family housing and multi-unit developments constitute the largest addressable volume. Superbonus tax credits redirect renovation demand toward deep energy retrofits in Lombardy and Veneto.
- Commercial:Office, retail, and hospitality construction follows metropolitan employment density. Milan and Rome concentrate new stock development.
- Industrial:Manufacturing facilities, logistics hubs, and energy transition plants demand heavy foundations and process-integrated building systems.
Residential claims the largest revenue base; infrastructure is climbing the fastest on public-private partnership awards.
End User:
Procurement authority determines contract structure, with government agencies mandating strict compliance frameworks and developers optimizing for project finance timelines.
- Government Agencies:Ministry of Infrastructure and Transport coordinates national building codes with EU Green Deal standards. Public procurement mandates CE marking verification and energy performance guarantees.
- Contractors:General and specialty contractors execute design-bid-build and design-build delivery. Cash flow management complexity rises with Superbonus tax credit transfer mechanisms.
- Developers:Private and institutional developers initiate residential and commercial projects. Milan-Rome corridor concentration shapes land acquisition strategies.
- Architects:Design professionals specify materials and methods, with BIM certification increasingly required for public sector eligibility.
Government agencies anchor public investment volume; contractors face the steepest operational complexity from regulatory compliance.
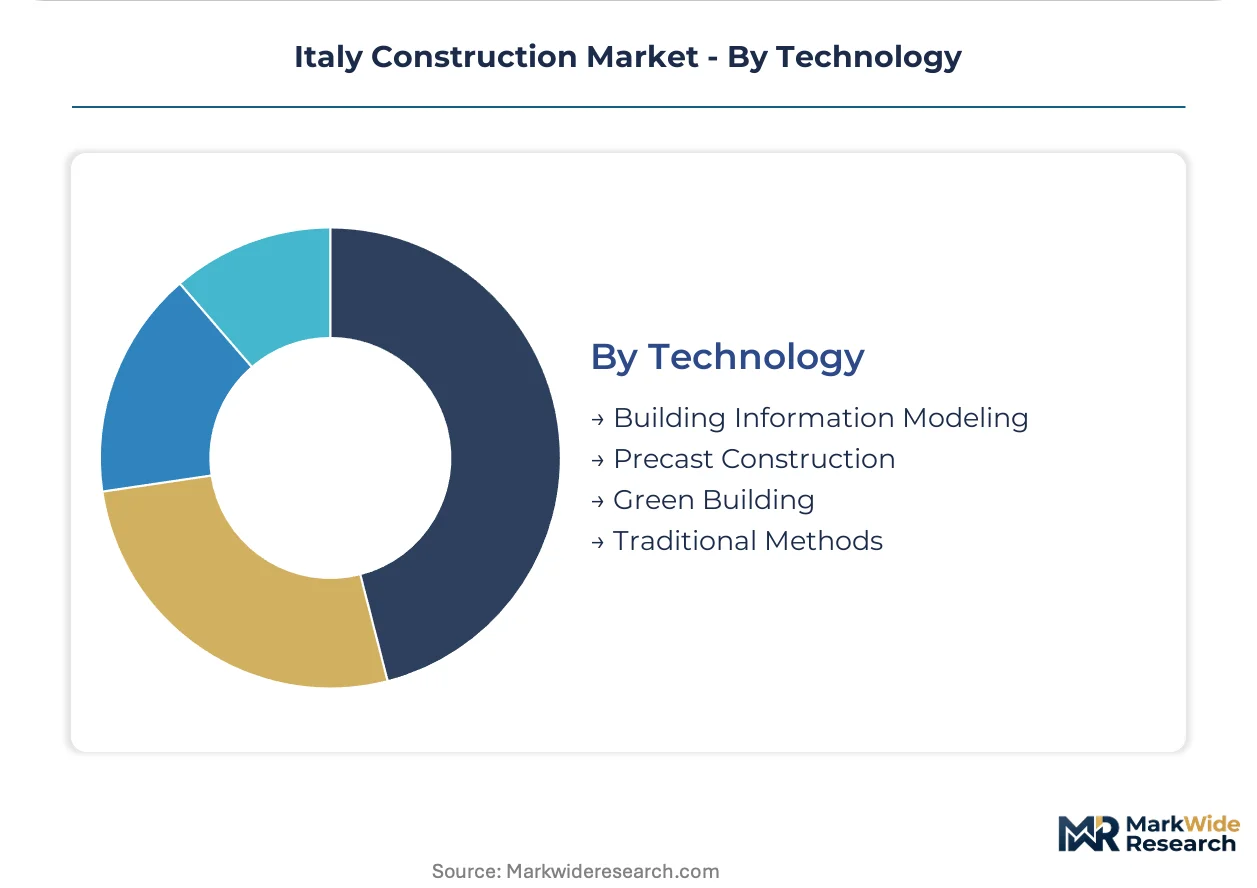
Technology:
Technology adoption separates bid-eligible contractors from excluded competitors, with digital and green building capabilities now mandatory for public sector access.
- Building Information Modeling:Digital twin creation and design coordination workflows compress project timelines. Turin and Bologna municipal housing authorities mandate BIM for social housing renovation tenders.
- Green Building:Low-carbon materials, renewable energy integration, and circular construction methods align with EU Green Deal requirements. Superbonus eligibility depends on certified energy performance thresholds.
- Precast Construction:Factory-produced structural and envelope components accelerate site assembly. Standardization suits repetitive residential and commercial typologies.
- Traditional Methods:Cast-in-place concrete and masonry construction persist in renovation and small-scale projects where prefabrication logistics prove uneconomical.
Traditional methods retain the largest installed base; Building Information Modeling is gaining share fastest on public procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian construction demand concentrates in northern industrial corridors and metropolitan rings around Rome, with public investment now redirecting toward southern infrastructure gaps through EU cohesion funding mechanisms.
Lombardy
Milan anchors residential stock expansion and commercial development across the metropolitan province. Superbonus tax credits drive deep energy retrofit demand in aging building stock throughout the region. Bergamo and Brescia industrial zones sustain precast concrete and structural steel fabrication capacity serving northern infrastructure megaprojects.
Lazio
Rome metropolitan construction concentrates on transport network extensions and social housing renovation under municipal procurement mandates. Ministry of Infrastructure and Transport coordinates high-speed rail corridor investments linking the capital to northern industrial centers. Fiumicino logistics hub development absorbs heavy civil works capacity from regional contractors.
Veneto
Padua and Verona construction clusters specialize in cross-laminated timber systems for Superbonus-eligible mid-rise residential projects. EU Green Deal energy performance standards govern building code enforcement through regional environmental agencies. Vicenza province hosts engineered wood product manufacturing integrated with thermal envelope installation services.
Emilia-Romagna
Bologna municipal housing authorities pilot separated procurement for energy performance guarantees in social housing renovation. Deep retrofit contractors acquire blower-door certification capacity to maintain bid eligibility under tightened airtightness testing requirements. Modena and Parma industrial zones supply precast structural components for repetitive residential typologies.
Calabria
EU cohesion fund allocations target transport and energy network construction across the southern region's infrastructure deficit. Strait of Messina crossing preliminary works and port modernization projects attract specialized marine construction expertise from northern contractors. Catanzaro and Reggio Calabria metropolitan areas concentrate limited regional building activity around public sector procurement.
Italy Construction Market Competitive Environment
Strategic partnerships dominate the current landscape as infrastructure consortia form around complex tunneling and transport megaprojects requiring pooled technical capabilities and risk-sharing mechanisms. The vendor structure concentrates around three tiered archetypes: transnational engineering groups with EU-wide project portfolios, regional specialists capturing Superbonus renovation flows, and public-sector-dependent contractors anchored to municipal procurement cycles. Portfolio diversification and technology licensing represent the principal competitive vectors as BIM mandates and green building certification requirements reshape bid eligibility criteria.
Among Italy-based engineering specialists, Webuild S.p.A., Saipem S.p.A., and Salcef Group S.p.A. occupy distinct positioning archetypes within the competitive structure. Webuild exemplifies the transnational infrastructure consortium leader leveraging cross-border project execution capabilities. Saipem represents offshore and marine construction specialization aligned with Mediterranean energy transition demand. Salcef sits within the railway infrastructure niche serving specialized track and electrification segments. These three entities anchor the competitive landscape without exhausting its structural variation.
| Leading Market Players |
|---|
| Webuild S.p.A. |
| Saipem S.p.A. |
| Salcef Group S.p.A. |
| Maire Tecnimont S.p.A. |
| Itinera S.p.A. |
| Impresa Pizzarotti & C. S.p.A. |
| Ghella S.p.A. |
| Trevi S.p.A. |
| Rizzani de Eccher S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Steel rebar and Portland cement feed into three-tier pricing structures across premium certified, standard compliance, and economy unbranded tiers, with CE marking verification costs separating bid-eligible northern consortia from excluded competitors in southern procurement channels.
Pricing Analysis
Volume-scale residential construction compresses margins on standardized concrete and masonry packages, while infrastructure megaprojects sustain premium pricing on performance-guaranteed tunneling and marine foundation contracts. Price differentiation hinges on CE marking tier and BIM certification status, with Superbonus-eligible thermal envelope upgrades commanding 15-25% premiums over conventional renovation. Cost compression in economy-grade structural materials intensifies as energy-intensive production faces natural gas price volatility and carbon border adjustment exposure. Public-sector agencies exhibit lowest price sensitivity due to EU-funded payment guarantees, while small private developers in peripheral regions demonstrate highest sensitivity to upfront material costs.
Supply Chain Analysis
CE marking compliance and BIM certification requirements gate supplier eligibility for public procurement, concentrating qualified structural material production in Germany, France, and domestic northern Italian zones. Raw material dependencies center on Turkish and Ukrainian steel scrap, Algerian natural gas for cement clinker, and Chinese specialty chemicals for marine grouting formulations. Single-source vulnerability in tunnel boring machine components from German and Japanese manufacturers threatens project timelines on Alpine corridor schemes. Distribution runs through regional precast yards and just-in-time delivery networks serving Milan-Rome construction corridors, with southern Italy relying on northern logistics hubs for certified materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized geotechnical engineering talent scarcity props pricing power for qualified infrastructure consortia, constraining rapid capacity expansion despite EU cohesion fund inflows.
For Market Incumbents: Anticipate margin compression on fixed-price public contracts by securing captive supply of CE-marked precast components through backward integration into Emilia-Romagna manufacturing zones. Defensive consolidation around BIM-certified workforce pools mitigates substitution risk from technology-enabled mid-tier entrants capturing municipal renovation mandates.
For New Entrants and Emerging Players: Municipal housing authorities in secondary cities represent the most penetrable buyer archetype, with Turin and Bologna pilot programs unbundling design-build contracts into ESCO-style energy performance arrangements. White-space targets include blower-door certification services for Superbonus retrofit contractors and cross-laminated timber installation capacity in Veneto mid-rise residential clusters. Go-to-market positioning should emphasize digital twin capabilities as mandatory bid criteria expand.
For Investors and Strategic Acquirers: Strait of Messina crossing preliminary works award is the leading indicator that southern Italy infrastructure gaps are converting from planning documents to bankable procurement, signaling viable deployment timelines for marine construction specialists. Long-term viability favors vertically integrated contractors with in-house geotechnical expertise and EU fund access credentials. Monitor CE marking compliance cost inflation as a margin pressure signal requiring portfolio rebalancing toward premium-tier infrastructure exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precast Manufacturing | Captive supply of CE-marked components secures margin control on Superbonus-eligible thermal envelope projects. |
| BIM Certification Workforce Investment | Municipal housing authorities in Turin and Bologna now mandate digital twin capabilities for social housing tenders. |
| Marine Construction Capability Buildout | Strait of Messina and offshore wind foundations require specialized expertise transferable to Spanish and Greek markets. |
| ESCO-Style Energy Performance Contracting | Unbundled procurement separates construction from long-term efficiency guarantees in social housing renovation. |
| Cross-Laminated Timber Supply Chain Integration | Lombardy and Veneto developers specify engineered wood systems for mid-rise Superbonus projects. |
Study Parameters
Document review covered EU cohesion fund allocation reports, Ministry of Infrastructure and Transport building code revisions, and CE marking compliance databases, complemented by interviews with general contractor procurement directors, municipal housing authority planning officers, precast concrete plant managers, and geotechnical engineering specialists. Secondary validation drew from ANCE construction industry statistics, Eurostat infrastructure investment data, and Superbonus tax credit transfer documentation. Bottom-up project pipeline analysis triangulated against top-down macroeconomic construction output models.
Cross-reference between historical award patterns and expert panel input shaped segment-level projections across structural materials, heavy equipment, finishing systems, and construction chemicals, with application splits modeled for infrastructure, residential, commercial, and industrial end uses. Technology adoption curves incorporated BIM mandate rollout schedules and green building certification penetration rates. CAGRs derived from weighted average of demand elasticity estimates and public investment commitment trajectories across the analysis window.
Revisions become necessary when Superbonus credit transfer mechanisms face administrative suspension, EU Green Deal energy performance standards accelerate implementation timelines, or natural gas price volatility disrupts cement and steel input costs. A model refresh is warranted upon material change in EU cohesion fund disbursement rates to southern Italian regions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Turkey Construction Market
Building Construction
Dominican Republic Construction Market
Building Construction
South Korea 3D Printing Construction Market
Building Construction
Spain Construction Market
Building Construction
Thailand Construction Market
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
India Construction Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
India Commercial Construction Market
Building Construction
US Prefabricated Buildings Market
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
UAE Facade Market
Building Construction
Qatar Construction Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
Saudi Arabia Infrastructure Sector Market