
 Cribbing Blocks Market | 2026-2036
Cribbing Blocks Market Size, Share, and Industry Trends Forecast 2026-2036
Cribbing Blocks Market Analytics
Maintenance subscription packages for cribbing inventory audits and replacement scheduling is restructuring how contractors procure stabilization equipment. Turtle Plastics dominates the recycled polyethylene segment through its closed-loop manufacturing program. Strickland MFG anchors the heavy-duty steel category with foundry-direct distribution across North American mining corridors. Superior Cribbing differentiates through on-site engineering support bundled with large-format custom orders.
Cribbing blocks are load-bearing stabilization devices, typically fabricated from hardwood timber, high-density recycled plastics, structural steel, or fiber-reinforced polymer composites, engineered to distribute concentrated loads across uneven surfaces during lifting, jacking, or shoring operations in industrial and construction environments. Plastic cribbing commands widening specification due to moisture immunity and splinter resistance, while composite cribbing captures premium positioning in corrosive marine settings where traditional materials fail prematurely. Standard-size wooden blocks retain volume leadership among price-sensitive contractor segments, though heavy-duty custom configurations generate disproportionate margin contribution from OEM integration contracts.
OSHA workplace safety standards and the EU Machinery Directive govern load-rating certifications and material traceability requirements, compelling manufacturers to maintain third-party testing documentation for market access. The EPA's recycled content procurement guidelines and REACH chemical compliance obligations in Europe further constrain material sourcing flexibility for cross-border suppliers. Stakeholders must monitor evolving polymer feedstock regulations and regional infrastructure spending commitments to align capacity investments with specification shifts.
Market Dynamics
OSHA's escalating enforcement of load-rating documentation for temporary stabilization equipment is compressing procurement cycles and disqualifying uncertified timber suppliers from federal infrastructure contracts. This regulatory pressure is accelerating specification migration toward engineered materials with traceable testing records.
Growth Catalysts
- EU Machinery Directive compliance mandates:European industrial maintenance contractors must source CE-marked cribbing with documented load ratings, eliminating informal timber suppliers from cross-border supply chains.
- Polymer formulation advances:High-density recycled polyethylene cribbing delivers moisture immunity and splinter resistance that hardwood cannot match in marine port maintenance and wastewater treatment facilities.
- US infrastructure spending concentration:Federal bridge rehabilitation and highway expansion projects in Texas, California, and Pennsylvania generate sustained demand for heavy-lift stabilization equipment with certified capacity ratings.
Market Restraints
- Petrochemical feedstock volatility:Recycled polyethylene cribbing manufacturers face margin compression when virgin resin prices spike, as pricing contracts often lag input cost movements by two quarters.
- Regional hardwood supply concentration:Traditional timber cribbing production clusters in the Pacific Northwest and Appalachian regions, exposing buyers to weather-driven harvesting disruptions and freight cost spikes.
- Steel cribbing weight limitations:Foundry-cast steel blocks exceed manual handling thresholds above 50-ton capacity ratings, restricting deployment flexibility in confined industrial maintenance spaces.
Strategic Opportunities
- India's port modernization:Jawaharlal Nehru Port Trust and Mundra Port expansion projects create demand for corrosion-resistant cribbing in high-humidity coastal environments where timber degrades rapidly.
- Subscription-based inventory management:Contractors in Germany's Ruhr industrial belt are adopting scheduled cribbing replacement programs that bundle engineering audits with just-in-time delivery.
- Fiber-reinforced polymer convergence:Composite cribbing combining glass fiber with thermoset resins penetrates offshore wind turbine maintenance, where salt spray and cyclic loading degrade conventional materials.
Industry Challenges
- Third-party certification timelines:OSHA-recognized testing laboratory backlogs extend load-rating documentation delivery by four to six months, delaying project approvals for custom-engineered cribbing configurations.
- Legacy timber specification inertia:Municipal procurement departments in price-sensitive regions retain outdated wooden cribbing standards that conflict with updated safety engineering requirements.
- Skilled field engineering scarcity:Complex multi-point lifting operations require certified rigging engineers to design cribbing configurations, and contractor employers report difficulty recruiting professionals with combined mechanical and structural expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cribbing Blocks Market |
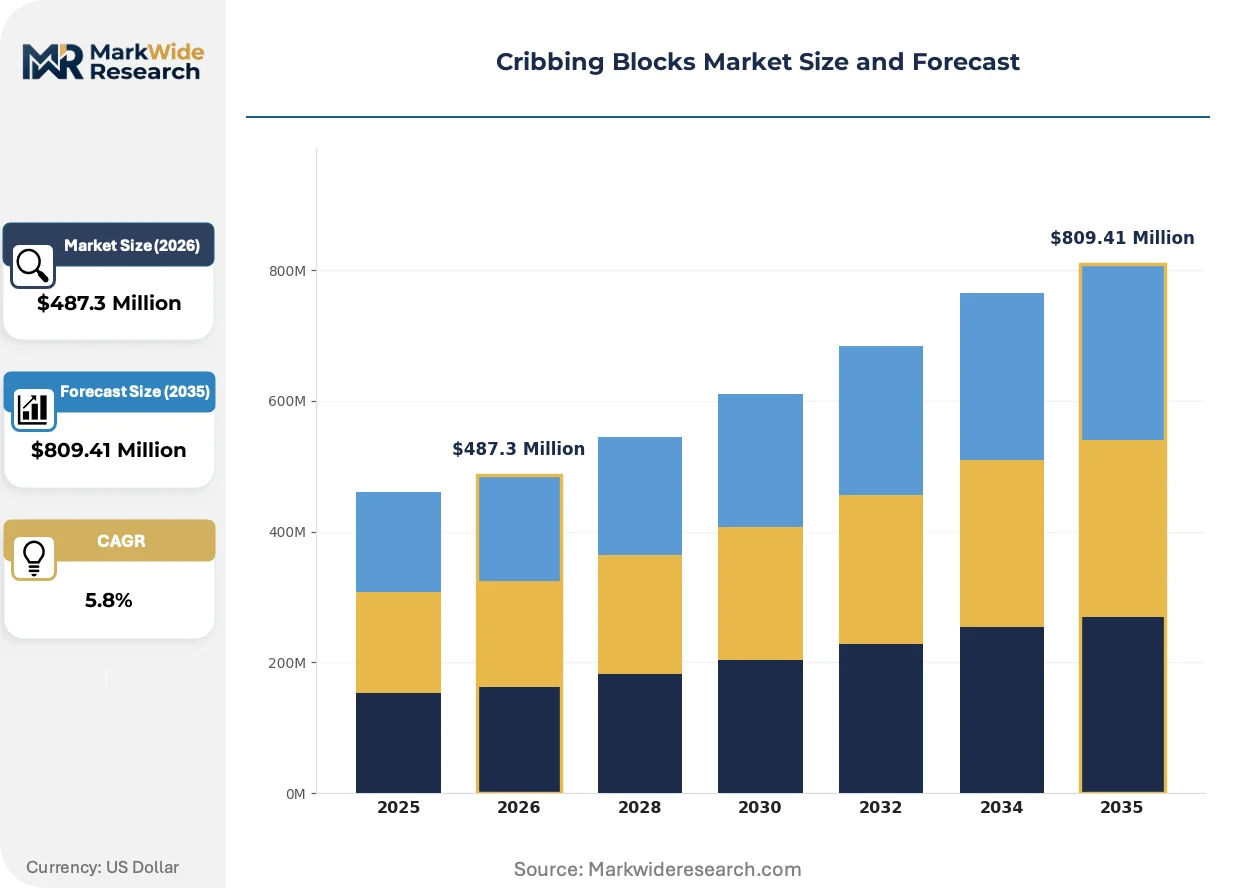
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Cribbing, Plastic Cribbing, Steel Cribbing, Composite Cribbing Application: Construction, Automotive, Marine, Industrial End User: Contractors, OEMs, Logistics Companies, Maintenance Providers Size: Standard, Mini, Heavy Duty, Custom Sizes |
| Companies Covered | Turtle Plastics, Sell Lumber Corporation, Millwood Inc, Strickland MFG, Superior Cribbing, Resilient Blocks, GreenLine Cribbing, Acme Cribbing, BlockTech Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cribbing Blocks Market Evolving Landscape
Material science breakthroughs and procurement digitization are restructuring how stabilization equipment is specified, sourced, and deployed across heavy-lift operations. Three converging developments are compressing traditional supply relationships and opening new performance tiers.
Recycled high-density polyethylene cribbing is expanding into marine infrastructure maintenance through closed-loop manufacturing programs that reclaim end-of-life blocks into virgin-equivalent feedstock. Port authorities in Rotterdam and Singapore specify these formulations for quayside crane stabilization, where saltwater immersion destroys timber within eighteen months. The technology is compressing lifecycle cost calculations by eliminating replacement frequency penalties previously accepted as unavoidable.
REACH chemical compliance obligations in Europe now mandate full material disclosure for polymer cribbing components, forcing reformulation of legacy colorants and UV stabilizers. Manufacturers serving German automotive stamping plants and French nuclear maintenance facilities have requalified supply chains to eliminate restricted phthalates and heavy metal pigments. Composite cribbing suppliers with pre-certified material libraries capture specification preference in tender processes where documentation burden disqualifies smaller competitors.
Maintenance contractors are consolidating vendor relationships through multi-year framework agreements that bundle cribbing supply with engineered configuration support. Large civil engineering firms in the United States now demand on-site technical consultation for complex shoring operations, displacing transactional procurement from distributor catalogs. This concentration is most visible in Texas and California energy sector projects, where integrated service contracts now represent the dominant commercial model for heavy-lift stabilization equipment.
Cribbing Blocks Market Segmentation
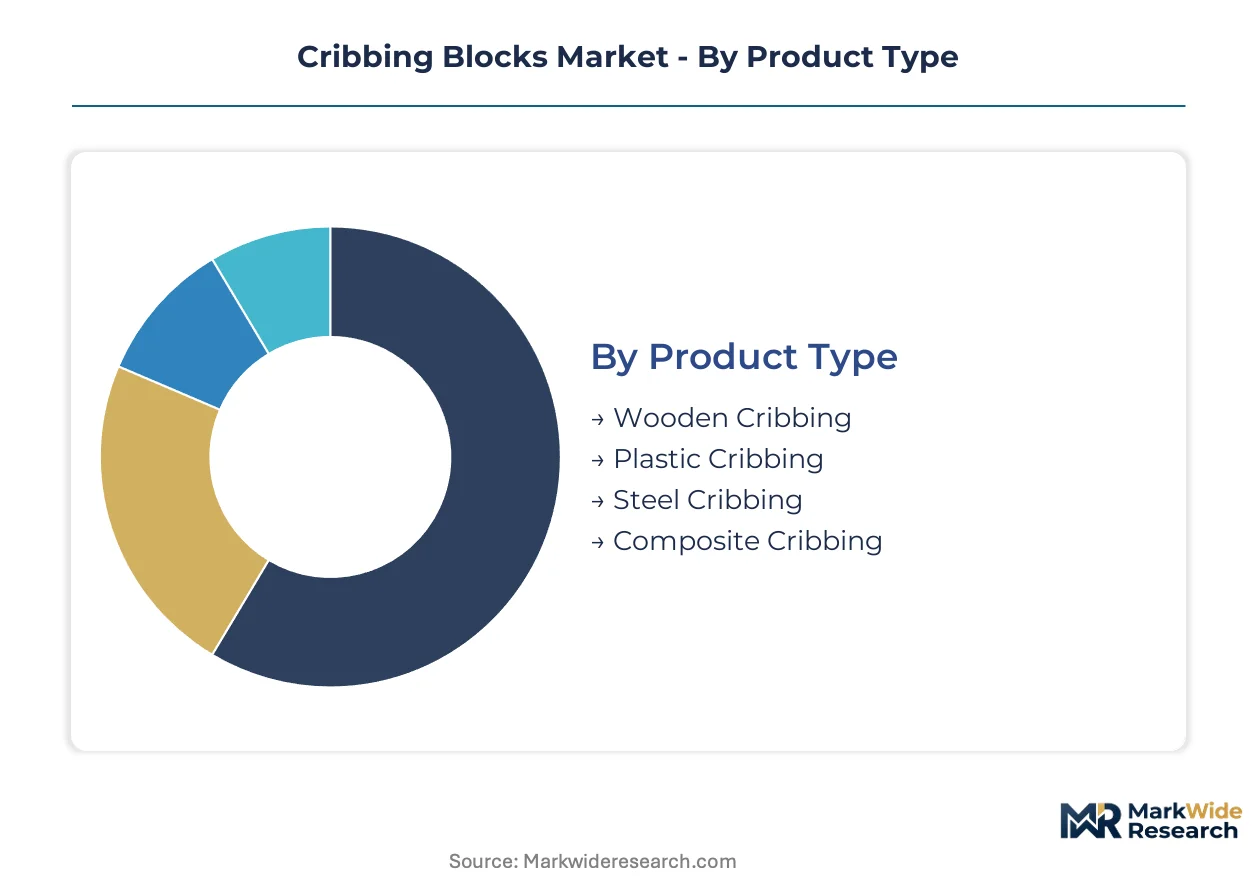
Cribbing block specification varies sharply by load requirements, environmental exposure, and procurement authority. Contractors prioritize manual handling ergonomics and OSHA traceability, while OEMs engineer for integration into permanent lifting systems with documented duty cycles.
Product Type:
Buyers differentiate primarily by moisture exposure severity and load-rating documentation requirements rather than upfront unit cost.
- Plastic Cribbing:High-density recycled polyethylene formulations deliver moisture immunity and splinter resistance that hardwood cannot match. Demand concentrates in marine port maintenance and wastewater treatment facilities across Rotterdam and Singapore, where saltwater immersion destroys timber within eighteen months and OSHA-compliant load documentation is mandatory.
- Composite Cribbing:Glass fiber-reinforced polymer construction penetrates offshore wind turbine maintenance and corrosive chemical processing environments. Salt spray and cyclic loading degrade conventional materials prematurely in North Sea installations, driving specification preference where lifecycle cost calculations override capital expenditure constraints.
- Wooden Cribbing:Standard hardwood blocks retain volume leadership among price-sensitive municipal contractors with dry indoor applications.
- Steel Cribbing:Foundry-cast configurations exceed manual handling thresholds above 50-ton ratings, restricting deployment to automated heavy-lift corridors.
Volume sits with wooden cribbing; growth tilts toward plastic formulations.
Application:
Environmental exposure severity and regulatory enforcement intensity determine material specification across use cases.
- Construction:Federal bridge rehabilitation and highway expansion projects in Texas, California, and Pennsylvania generate sustained demand for certified capacity ratings. OSHA's escalating enforcement of load-rating documentation compresses procurement cycles toward engineered materials with traceable testing records.
- Marine:Quayside crane stabilization in high-humidity coastal environments requires corrosion-resistant formulations where timber degrades rapidly. Jawaharlal Nehru Port Trust and Mundra Port expansion projects in India specify plastic and composite alternatives.
- Industrial:Automotive stamping plants and nuclear maintenance facilities in Germany and France demand REACH-compliant material disclosure.
- Automotive:Vehicle assembly line maintenance uses standardized cribbing configurations with rapid replacement protocols.
Construction commands the largest shipment volumes; marine applications are climbing the fastest.
End User:
Procurement sophistication and technical support requirements separate transactional buyers from integrated service adopters.
- Contractors:Large civil engineering firms in Texas and California energy sectors now demand on-site technical consultation for complex shoring operations. Multi-year framework agreements bundle cribbing supply with engineered configuration support, displacing transactional catalog procurement.
- Maintenance Providers:Germany's Ruhr industrial belt contractors adopt scheduled replacement programs combining engineering audits with just-in-time delivery. Subscription-based inventory management restructures procurement from episodic purchasing to continuous supply relationships.
- OEMs:Integration contracts for permanent lifting system manufacturers require custom-engineered configurations with extended duty cycle documentation.
- Logistics Companies:Warehouse stabilization needs concentrate in standard-size plastic cribbing for racking and equipment maintenance.
Contractors drive current volume; maintenance providers are gaining share fastest through service bundling.
Size:
Load concentration and handling constraints determine dimensional specification, with custom configurations generating disproportionate margin contribution.
- Custom Sizes:OEM integration contracts and complex multi-point lifting operations require engineered configurations. Superior Cribbing and similar suppliers differentiate through on-site engineering support bundled with large-format orders, capturing premium positioning despite longer fulfillment timelines.
- Heavy Duty:Above 50-ton capacity ratings, steel and composite configurations dominate where manual handling limits restrict deployment flexibility. Foundry-direct distribution across North American mining corridors anchors supply relationships.
- Standard:Catalog-specified dimensions serve routine construction and maintenance with rapid availability.
- Mini:Compact configurations address confined industrial maintenance spaces and precision equipment stabilization.
Standard sizes anchor volume; custom configurations command the steepest expansion trajectory in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in timber-rich regions and polymer processing corridors, while consumption gravitates toward heavy infrastructure corridors with active OSHA and EU Machinery Directive enforcement. This geographic mismatch creates freight cost premiums and specification fragmentation across procurement networks.
United States
Federal bridge rehabilitation and highway expansion projects in Texas and California generate sustained demand for certified heavy-lift stabilization equipment. OSHA's escalating enforcement of load-rating documentation compresses procurement cycles toward engineered materials with traceable testing records. Houston and Los Angeles industrial maintenance corridors anchor specification migration away from uncertified timber suppliers.
Germany
Automotive stamping plants and nuclear maintenance facilities in the Ruhr industrial belt demand REACH-compliant material disclosure for all polymer cribbing components. The EU Machinery Directive mandates CE-marked cribbing with documented load ratings, eliminating informal timber suppliers from cross-border supply chains. Stuttgart and Munich engineering clusters drive adoption of scheduled replacement programs bundling engineering audits with just-in-time delivery.
India
Jawaharlal Nehru Port Trust and Mundra Port expansion projects create demand for corrosion-resistant cribbing in high-humidity coastal environments where timber degrades rapidly. The country's national infrastructure regulator emphasizes material traceability for heavy-lift operations in port modernization contracts. Mumbai and Gujarat industrial corridors specify plastic and composite alternatives for quayside crane stabilization applications.
Netherlands
Rotterdam port authorities specify recycled high-density polyethylene cribbing formulations for quayside crane stabilization, where saltwater immersion destroys timber within eighteen months. REACH chemical compliance obligations mandate full material disclosure for polymer components, forcing reformulation of legacy colorants and UV stabilizers. The Randstad logistics cluster drives closed-loop manufacturing programs that reclaim end-of-life blocks into virgin-equivalent feedstock.
Singapore
Maritime port maintenance operations in high-humidity coastal environments require corrosion-resistant cribbing formulations with moisture immunity and splinter resistance. The country's national workplace safety regulator enforces load-rating documentation for temporary stabilization equipment in heavy-lift operations. The Jurong industrial corridor anchors specification preference for engineered materials with traceable testing records in marine infrastructure applications.
Cribbing Blocks Market Competitive Landscape
Top-tier vendors anchor specification-driven segments with certified load-rating documentation and on-site engineering support, while mid-tier fabricators compete on rapid availability of standard configurations. The vendor base stratifies across polymer specialists with closed-loop manufacturing programs, timber producers serving price-sensitive municipal contractors, and composite engineers targeting corrosive marine environments. Three archetypes dominate: recycled material innovators bundling sustainability credentials with technical compliance, heavy-duty steel foundries with direct mining corridor distribution, and custom-engineering houses capturing premium positioning through bundled configuration support. Competitive moves concentrate on multi-year framework agreements that displace transactional catalog procurement, and vertical integration into polymer feedstock reclamation to secure supply chain resilience.
Within the recycled polyethylene tier, Turtle Plastics exemplifies closed-loop manufacturing positioning, while Strickland MFG anchors heavy-duty steel fabrication through foundry-direct distribution relationships. Superior Cribbing occupies a position in the custom-engineering segment, representing the archetype of suppliers bundling on-site technical consultation with large-format orders. These three companies collectively illustrate how specification complexity and service bundling are restructuring procurement relationships away from transactional distributor channels.
| Leading Market Players |
|---|
| Turtle Plastics |
| Sell Lumber Corporation |
| Millwood Inc |
| Strickland MFG |
| Superior Cribbing |
| Resilient Blocks |
| GreenLine Cribbing |
| Acme Cribbing |
| BlockTech Industries |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap timber producers across the Pacific Northwest and Appalachian regions anchor supply-side discipline through generational harvesting relationships, constraining price volatility for hardwood cribbing despite polymer feedstock swings. Their patient capital structure resists margin compression tactics that pressure PE-rolled plastic competitors during resin price spikes.
Pricing Analysis
Cost-down pressure on standard wooden cribbing accelerates because municipal procurement departments retain outdated specification standards that conflict with OSHA-compliant engineered alternatives. Three-tier pricing structure across premium composite, standard plastic, and economy hardwood levels separates buyers by certification burden and lifecycle cost horizon. Price differentiation traces to CE-marking documentation and REACH material disclosure compliance, with German automotive stamping plants least sensitive and price-focused US municipal contractors most reactive to unit cost.
Supply Chain Analysis
Dual-sourcing requirements from federal infrastructure contractors mandate qualified suppliers across both domestic timber corridors and recycled polymer processing hubs. Supply concentrates in the United States for hardwood feedstock and high-density polyethylene reclamation, with secondary polymer processing in Germany and the Netherlands. Raw material dependencies rest on Appalachian oak and maple harvesting, post-industrial polyethylene scrap streams, and glass fiber roving for composite formulations. Tariff exposure on European REACH-compliant additives creates single-source vulnerability for colorant and UV stabilizer inputs. Distribution runs through foundry-direct relationships for heavy-duty steel and distributor networks for standard catalog configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as polymer specialists pursue captive feedstock reclamation and timber producers acquire regional distribution assets to defend margin position.
For Market Incumbents: Anchor specification leadership through accelerated OSHA-recognized laboratory certification investments that disqualify uncertified timber competitors from federal bridge rehabilitation contracts. Defend against recycled polyethylene margin compression by securing long-term post-industrial scrap supply agreements with automotive and packaging waste generators, creating feedstock cost advantages that lagging competitors cannot replicate. For New Entrants and Emerging Players: Capture India's port modernization wave by qualifying corrosion-resistant cribbing formulations for Jawaharlal Nehru Port Trust and Mundra Port expansion tenders, where timber degradation creates immediate specification openings. Target marine maintenance providers in high-humidity coastal environments with subscription-based inventory management offerings that bundle engineering audits with just-in-time delivery, displacing transactional procurement relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor custom-engineering specialists with on-site technical consultation capabilities in the US energy corridor, where integrated service contracts now dominate commercial models for heavy-lift stabilization equipment. Long-term viability hinges on backward integration into polymer feedstock reclamation or forward integration into maintenance subscription platforms. Watch for inflection when OSHA enforcement timelines compress four-to-six-month certification backlogs, accelerating disqualification of informal timber suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Manufacturing Program | Turtle Plastics reclaims end-of-life blocks into virgin-equivalent feedstock, eliminating raw material cost volatility. |
| Foundry-Direct Distribution | Strickland MFG bypasses distributor markups across North American mining corridors, capturing margin and relationship control. |
| On-Site Engineering Support Bundling | Superior Cribbing differentiates large-format custom orders with technical consultation, locking in multi-year framework agreements. |
| REACH-Compliant Material Requalification | European suppliers eliminate restricted phthalates and heavy metal pigments to retain German automotive and French nuclear facility access. |
| Subscription-Based Inventory Management | Germany's Ruhr industrial belt contractors adopt scheduled replacement programs, converting episodic purchasing to continuous supply relationships. |
Research Methodology
Independent corroboration across maintenance directors at industrial facilities, procurement leads at heavy-lift contractors, and aftermarket service heads at OEMs underwrites the qualitative findings. Primary interviews with plant engineers, rigging specialists, and distributor channel partners combined with secondary validation from OSHA enforcement records, EPA recycled content procurement guidelines, EU Machinery Directive compliance databases, and customs trade data. Bottom-up shipment analysis and top-down infrastructure spending allocation triangulate volume estimates.
Comparable-period anchoring to historical certification timelines and material substitution patterns structured the projection horizon across product type, application severity, end-user procurement sophistication, and dimensional specification tiers. CAGRs derived from segmented demand elasticity modeling and infrastructure commitment trajectories incorporate polymer feedstock price volatility assumptions and regulatory enforcement intensity gradients.
The model holds under stable OSHA and EU Machinery Directive enforcement intensity; deviation in federal infrastructure spending allocation or REACH chemical restriction expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Portland Cement Market
Building Materials
Blended Cement Market
Building Materials
Rubbing Bricks Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Engineered Wood Product Market
Building Materials
Italy Architectural Coatings Market
Building Materials
Brick Adhesive Market
Building Materials
Global Magnesia Chrome Brick Market
Building Materials
Germany Architectural Coatings Market
Building Materials
Composite Decking and Railing Market
Building Materials
Construction Glass Market
Building Materials
Engineered Stone Market
Building Materials
Sprayed Concrete Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
US Facade Market