
 Pneumatic Cylinder Market | 2026-2036
Pneumatic Cylinder Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Cylinder Market Intelligence
Increased automation investment in Southeast Asia is repositioning supply chain priorities for pneumatic actuators. SMC Corporation leverages its extensive product portfolio and distribution network to serve this demand. Festo SE & Co. KG differentiates through its focus on integrated automation solutions and training services. Parker Hannifin Corporation competes on the basis of its broad fluid power and motion control technologies, serving diverse industrial end-users.
A pneumatic cylinder is a mechanical device that converts the potential energy of compressed air into linear motion. Key performance parameters include bore size, which determines force output, and stroke length. Its primary purpose is to provide force and movement for industrial automation tasks. Double-acting cylinders constitute the largest product segment, while compact cylinders designed for space-constrained applications in electronics assembly see heightened interest.
Product design and market access are governed by multiple standards, including ISO 15552 for interchangeability and CE marking for European safety compliance. In the United States, OSHA regulations influence the safe implementation of pneumatic systems in industrial environments. Vendor success depends on navigating these diverse regional standards while adapting product lines to include sensor integration and enhanced energy efficiency features.
Market Dynamics
The concentration of factory automation investment in manufacturing hubs across China and Southeast Asia represents the central force shaping component demand and supply chain strategy for pneumatic cylinders. This geographical shift dictates product development priorities and competitive focus.
Growth Catalysts
- ISO Standardization:The proliferation of ISO 15552 ensures interchangeability between cylinders from different manufacturers, reducing vendor lock-in for end-users and broadening the addressable market for compliant suppliers.
- Food and Beverage Automation:Demand for hygienic, corrosion-resistant stainless steel cylinders is expanding within the food processing sector, driven by stringent food safety regulations and the need for automated clean-in-place systems.
- Sensor Integration:The embedding of position and pressure sensors directly into cylinders provides critical data for process control and predictive maintenance, a key enabler for Industry 4.0 applications.
Market Restraints
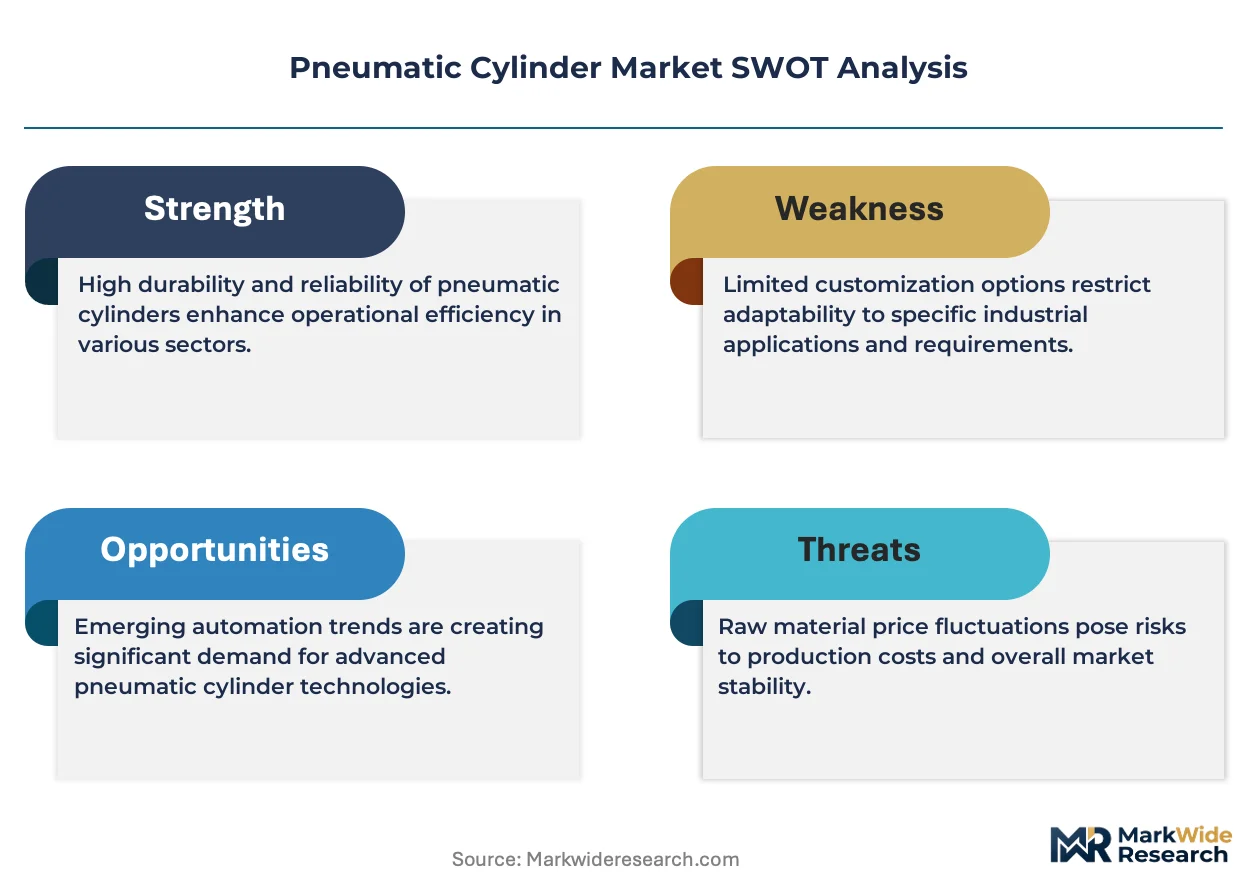
- Electric Actuator Substitution:The superior energy efficiency and precise positioning capabilities of electric actuators present a significant substitution threat, particularly in applications requiring high control accuracy.
- Raw Material Volatility:Cylinder manufacturing costs are directly exposed to price fluctuations in aluminum and steel, which constitute the main body materials, creating margin pressure for manufacturers.
- Compressed Air Inefficiency:The inherent energy loss in generating and distributing compressed air makes pneumatic systems less energy-efficient than electric alternatives, a key disadvantage under rising energy costs.
Strategic Opportunities
- Energy Efficiency Mandates:Regulations like the EU's Ecodesign Directive create opportunities for energy-efficient cylinders that help users meet compliance targets.
- IO-Link Communication:Integrating the IO-Link communication protocol into smart cylinders simplifies wiring and enhances diagnostics for factory control systems.
- Medical and Lab Automation:The need for compact, clean actuators in medical diagnostic equipment and laboratory automation represents an underpenetrated market for specialized, miniature cylinders.
Industry Challenges
- Mechatronics Skill Gap:A shortage of technicians skilled in both pneumatics and electronic controls hampers adoption and increases service complexity for end-users.
- Legacy System Integration:Connecting new digital components with older factory Programmable Logic Controllers (PLCs) presents significant technical and cost hurdles.
- Navigating Global Compliance:Adhering to fragmented regional standards, from CE marking in Europe to OSHA rules in the United States, increases design and certification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Cylinder Market |
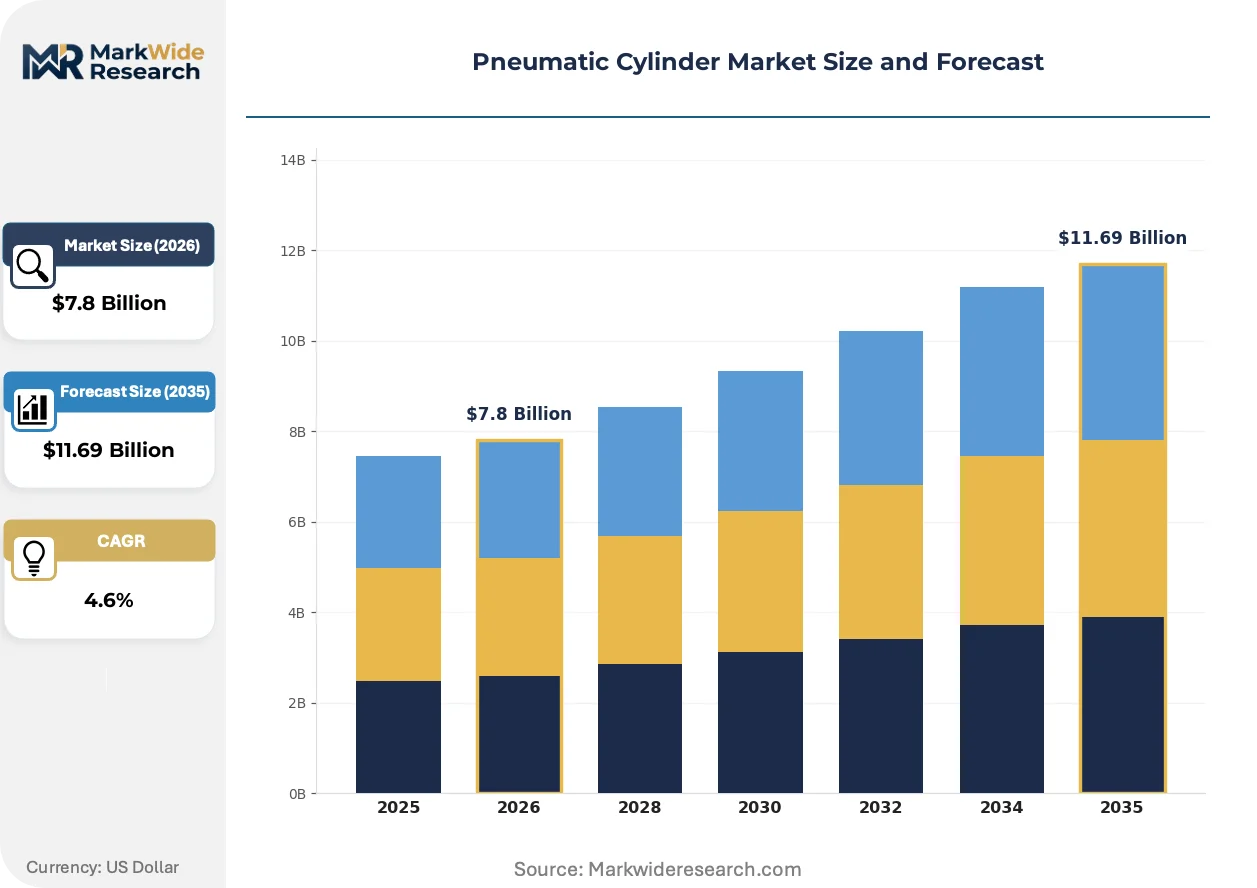
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Acting, Single Acting, Tie-Rod, Compact, Rodless Mounting Style: Flange, Foot, Clevis, Face, Trunnion Application: Material Handling, Packaging, Automation Equipment, Food Processing, Textile Machinery End User Industry: Manufacturing Plants, Automotive Manufacturers, Electronics Assembly, HVAC Installation, Construction Equipment |
| Companies Covered | SMC Corporation, Festo SE & Co. KG, Parker Hannifin Corporation, Airtac International Group, Aventics GmbH, IMI Precision Engineering, Camozzi Automation, Bosch Rexroth AG, CKD Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Cylinder Market Strategic Shifts & Innovations
Product evolution centers on embedding intelligence and improving energy efficiency to defend market share against electric alternatives. This shift is driven by both regulatory pressure for greener operations and end-user demand for data-rich automation components.
Onboard sensor technology provides real-time feedback on cylinder position, speed, and pressure for closed-loop control. The automotive and electronics manufacturing sectors are early adopters of these smart cylinders. This embedded intelligence is converging with industrial IoT platforms, enabling predictive maintenance algorithms that reduce unplanned downtime across global production lines.
The ISO 50001 standard for energy management is influencing pneumatic system design. The standard compels facilities to optimize energy use, targeting compressed air as a major cost. In response, manufacturers are engineering cylinders with lower air leakage and better sealing, especially for the European replacement market.
A significant behavioral change involves OEMs sourcing pre-assembled and tested pneumatic modules rather than individual components. This practice shifts design risk from the machine builder to the automation supplier, altering traditional distribution channel dynamics. This modular procurement approach is most visible in high-volume sectors like packaging machinery and conveying systems.
Pneumatic Cylinder Market Segmentation
Understanding the segmentation of the pneumatic cylinder market provides critical insights into product development priorities and strategic investment areas. This detailed analysis reveals how different cylinder types and their applications shape demand across diverse industrial landscapes.
Product Type:
Product type segmentation highlights the varying degrees of complexity and integration required for pneumatic cylinders within automated systems.
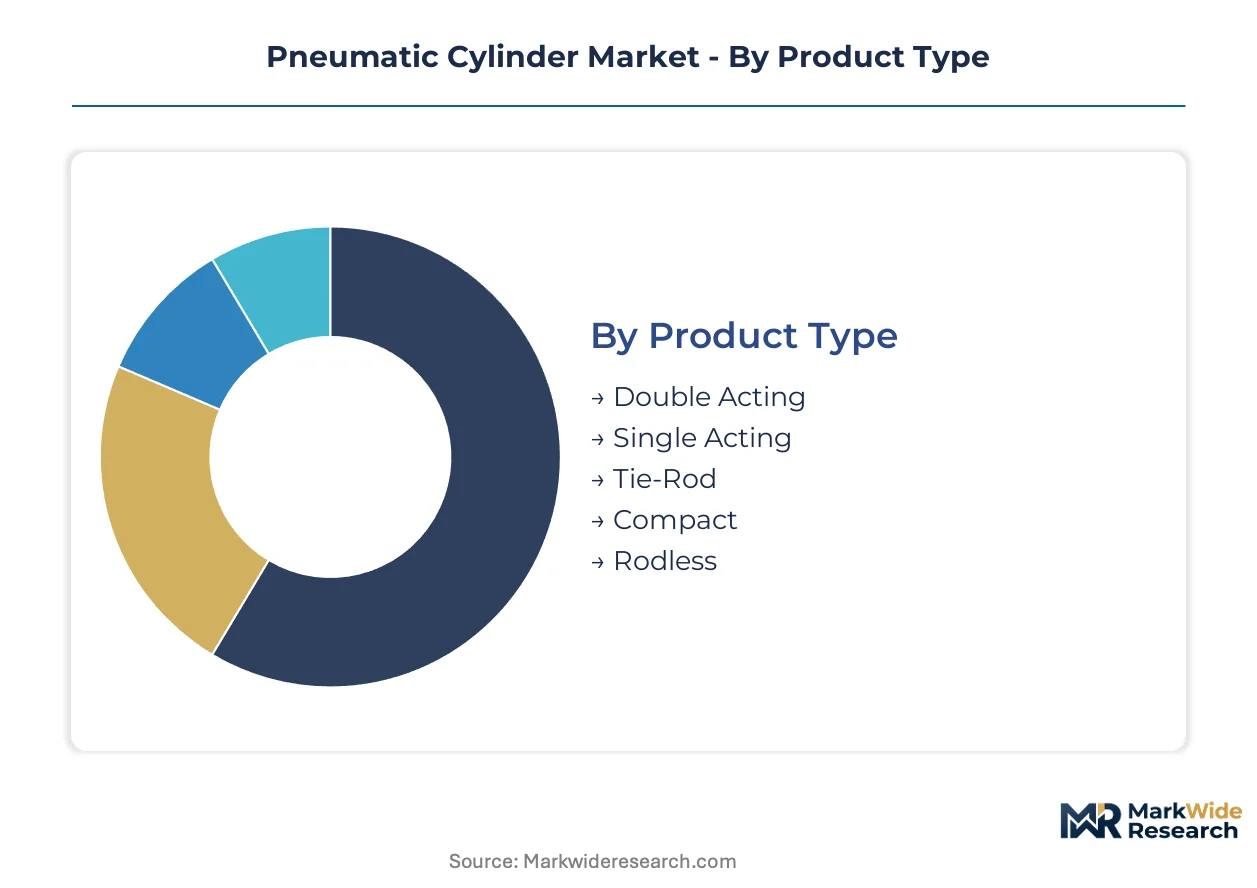
- Double Acting:These cylinders extend and retract using compressed air on both sides of the piston, providing controlled force in two directions. This segment represents the largest product category, essential for repetitive industrial automation tasks in manufacturing hubs across China.
- Compact:Designed with a short stroke and minimal footprint, these cylinders are ideal for applications where space is severely restricted. High interest for compact cylinders exists in electronics assembly within Southeast Asia, supporting miniaturization trends.
- Tie-Rod:Constructed with external tie rods, these cylinders offer robust performance and are suitable for heavy-duty industrial applications requiring high force output.
- Single Acting:Utilizing compressed air for extension and a spring for retraction, these cylinders are common in simpler clamping or ejecting tasks.
- Rodless:These cylinders eliminate the piston rod, providing a compact solution for long-stroke applications where conventional rod cylinders are impractical.
Volume placements concentrate in Double Acting cylinders; the faster expansion belongs to Compact cylinders.
Mounting Style:
Mounting style defines how pneumatic cylinders integrate physically into machinery, influencing their application suitability and operational stability.
- Flange:These mounts attach directly to machine frames, providing rigid support for high-load applications in material handling systems. Flange mounting ensures stability where significant thrust forces are present.
- Clevis:A clevis mount allows for pivoting motion, making it commonly used in linkages and articulating mechanisms within construction equipment. This style facilitates rotational movement of the cylinder body.
- Foot:Foot mounts attach to a flat surface with feet, offering versatile installation for various industrial setups.
- Face:Face mounts secure the cylinder to a machine's front or rear face, suitable for applications needing compact installation.
- Trunnion:Trunnion mounts provide a pivot point at the cylinder's approximate center of gravity, ideal for swinging or rotating movements.
The selection of mounting styles often optimizes cylinder performance for specific operational demands in manufacturing plants.
Application:
Application segmentation reveals the diverse operational impacts of pneumatic cylinders across various industrial processes, from movement to processing.
- Automation Equipment:This segment drives a wide array of automated functions, including pick-and-place, clamping, and pressing, particularly in high-volume production lines. The demand for integrated solutions in automation equipment is significant.
- Food Processing:This sector employs hygienic, corrosion-resistant stainless steel cylinders for tasks like sorting, filling, and packaging, meeting stringent food safety regulations. Automated clean-in-place systems are a key driver here.
- Material Handling:Cylinders are utilized for lifting, pushing, and conveying components in logistics and manufacturing environments.
- Packaging:This application integrates cylinders for sealing, cutting, and forming operations in automated packaging machinery.
- Textile Machinery:Cylinders are deployed for controlling fabric tension, cutting, and weaving processes in textile manufacturing.
Each application area presents unique demands for cylinder performance, driving specialized product development.
End User Industry:
End user industry segmentation highlights where strategic investments in automation are driving demand for pneumatic cylinder solutions.
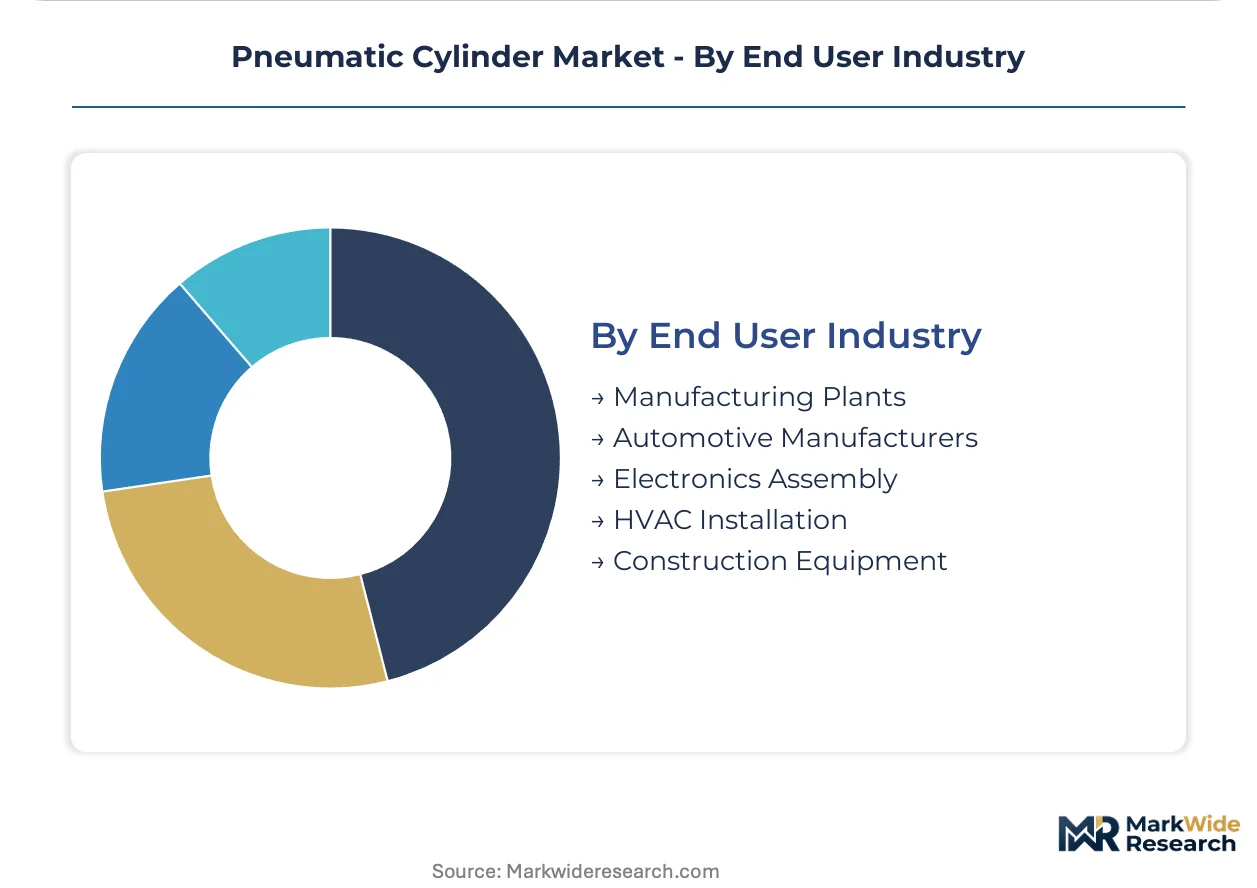
- Manufacturing Plants:This segment represents a foundational demand, deploying cylinders across diverse production lines for assembly, pressing, and material transfer tasks. General manufacturing plants remain a primary consumer of pneumatic technology.
- Electronics Assembly:This industry requires precision and compact cylinders for intricate tasks like component placement and circuit board handling, especially in Asian manufacturing hubs. Miniaturization and speed are critical factors.
- Automotive Manufacturers:Cylinders are integrated into assembly lines for welding, clamping, and painting processes within vehicle production.
- HVAC Installation:This sector utilizes cylinders for damper control and ventilation system actuation in commercial and industrial buildings.
- Construction Equipment:Robust cylinders are employed for heavy lifting, digging, and articulation in machinery like excavators and loaders.
The varied operational environments across these industries necessitate tailored cylinder designs and material specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's vast aluminum and steel production capacity anchors the global pneumatic cylinder market. This foundational supply supports extensive manufacturing across Asia, particularly where automation investment accelerates. Global demand for these components is increasingly influenced by regional industrial policies and evolving regulatory landscapes.
China
China's extensive manufacturing base drives significant demand for double-acting pneumatic cylinders across diverse industries. The government's "Made in China 2025" initiative promotes automation and smart manufacturing technologies. Industrial clusters like the Yangtze River Delta actively integrate smart cylinders into high-volume production lines. This focus enhances operational efficiency across numerous sectors, supported by GB standards.
Vietnam
Vietnam experiences strong demand for compact pneumatic cylinders, particularly in its expanding electronics and textile industries. The government actively attracts foreign direct investment through various incentives and free trade agreements. Manufacturing zones around Ho Chi Minh City are rapidly adopting automated systems for precision assembly tasks. This regional growth underscores a shift in supply chain priorities for pneumatic actuators.
Germany
Germany's advanced manufacturing sector, especially automotive and machine building, requires high-performance pneumatic cylinders. CE marking ensures product safety and compliance across the European Union, while the EU Ecodesign Directive pushes for energy efficiency. Industrial regions like Baden-Württemberg lead in integrating smart cylinders with IO-Link communication into complex automation solutions. This focus supports the Industry 4.0 agenda within the country.
United States
United States manufacturing plants demand diverse pneumatic cylinders for material handling and assembly operations. OSHA regulations mandate safe implementation of pneumatic systems, influencing design and installation practices. The Midwest industrial belt, encompassing states like Michigan and Ohio, sees continuous investment in factory automation upgrades. This regional activity supports robust domestic demand for pneumatic technology.
India
India's burgeoning automotive and food processing sectors are expanding their use of pneumatic cylinders. BIS standards ensure product quality and safety for industrial equipment within the country. Manufacturing hubs in Maharashtra, including Pune and Mumbai, are investing in automated production lines requiring reliable pneumatic solutions. This growth trajectory reflects increasing industrialization across the nation.
Pneumatic Cylinder Market Key Industry Players
Global majors compete with regional champions across product innovation and distribution network reach. The pneumatic cylinder market features a tiered competitive structure. A few global manufacturers dominate the premium segment with broad portfolios and integrated solutions. Mid-tier specialists focus on niche applications or specific regional markets, often differentiating through cost or customization. Competitive moves frequently involve strategic partnerships for technology co-development and targeted geographic expansion into high-growth manufacturing hubs.
Among the global leaders, SMC Corporation exemplifies a broad product portfolio and extensive distribution capabilities, particularly within Asian manufacturing hubs. Festo SE & Co. KG, a German-based company, represents a strong focus on integrated automation solutions and educational services, catering to complex industrial needs. Parker Hannifin Corporation, based in the United States, anchors the market with its diverse fluid power and motion control technologies, serving a wide array of industrial end-users globally. These companies collectively illustrate the strategic importance of comprehensive offerings, technological depth, and robust market presence in the pneumatic cylinder sector. Their competitive strategies often involve continuous product refinement and adaptation to regional compliance standards.
| Leading Market Players |
|---|
| SMC Corporation |
| Festo SE & Co. KG |
| Parker Hannifin Corporation |
| Airtac International Group |
| Aventics GmbH |
| IMI Precision Engineering |
| Camozzi Automation |
| Bosch Rexroth AG |
| CKD Corporation |
| Others |
Cost & Logistics Intelligence
Manufacturing plants across Asia, particularly in China and Southeast Asia, concentrate demand for pneumatic cylinders, influencing a transactional and project-based pricing model. This buyer archetype drives competition among suppliers to offer cost-effective, high-volume solutions while maintaining quality standards. The market's structure reflects a balance between large-scale industrial demand and specialized application needs.
Pricing Analysis
Warranty and service bundling often differentiates premium pneumatic cylinder offerings, particularly for complex integrated automation solutions. Pricing stratifies across performance tiers, with ISO 15552 compliant cylinders commanding a premium due to interchangeability and quality. Brand premium, especially for established players like Festo SE & Co. KG, also drives price differentiation. Pricing pressure stems from the superior energy efficiency of electric actuator alternatives. Small-to-medium enterprises typically exhibit higher price sensitivity compared to large automotive manufacturers.
Supply Chain Analysis
Domestic content mandates, such as China's "Made in China 2025" initiative, increasingly reshape sourcing strategies for pneumatic cylinder components. Geographic supply concentrates in China, Germany, and Japan, reflecting the manufacturing bases of key players. The supply chain draws from aluminum and steel as primary raw material dependencies. Raw material volatility presents a structural risk for manufacturers, impacting production costs and margins. Distribution runs through a network of specialized industrial distributors and direct sales channels to large original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a supply-constrained story for specialized components, with the scarcity of advanced sensor integration capabilities currently propping pricing for smart cylinders.
For Market Incumbents: Lock in long-term OEM contracts by offering comprehensive, integrated pneumatic solutions that include advanced sensor technology and energy-efficient designs. Deepen R&D investment into IO-Link communication protocols and predictive maintenance features to counter electric actuator substitution threats. Expand localized manufacturing and support services within high-growth Asian manufacturing hubs to strengthen channel control and reduce lead times.
For New Entrants and Emerging Players: Miniaturization capabilities and specialized materials present a technology-first wedge into underpenetrated segments like medical and lab automation. Target space-constrained electronics assembly in Southeast Asia with compact, high-precision cylinders. A go-to-market angle focusing on rapid customization and simplified integration with existing factory PLCs can attract niche customers seeking agile solutions.
For Investors and Strategic Acquirers: The window for entry favors specialized technology acquirers with expertise in sensor integration or clean-room actuation for medical applications. Long-term viability over the next 5-10 years remains strong due to sustained factory automation investment. Target mid-tier specialists with robust intellectual property in energy-efficient designs or strong regional distribution networks. Increased M&A activity for companies developing advanced communication protocols is a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Supports growing demand for factory automation in regional manufacturing hubs like Vietnam. |
| Sensor Integration R&D | Enhances data feedback for Industry 4.0 applications and predictive maintenance across production lines. |
| IO-Link Protocol Adoption | Simplifies wiring and improves diagnostics for smart pneumatic cylinders in complex control systems. |
| Specialized Cylinder Development | Addresses unmet needs for compact, hygienic actuators in medical and food processing sectors. |
| Long-term OEM Partnerships | Secures stable demand channels and facilitates co-development of application-specific pneumatic solutions. |
Research Approach
Independent corroboration across primary interviews with industry experts, secondary market reports, and regulatory documents underwrites the qualitative findings of this analysis. The study integrates insights from plant engineers, OEM procurement teams, R&D directors, and specialized distributors. Bottom-up and top-down triangulation ensures data consistency across diverse sources, including ISO standards documents, national manufacturing reports, and company annual reports.
Historical reference periods anchor the forecast window, integrating market drivers, restraints, and opportunities into a robust analytical framework over the projection horizon. The modeling incorporates segmentation dimensions such as product type, mounting style, application, end-user industry, and regional economic growth. Compound Annual Growth Rates (CAGRs) derive from historical trends and projected growth catalysts, with factory automation investment rates and raw material price forecasts serving as key inputs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical trade tensions and rapid shifts in energy costs. The forecasts reflect assumptions regarding sustained automation investment and technological advancements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mechanical and Electrical Services
Global Mechanical Electrical and Plumbing (MEP) Services Market
Mechanical and Electrical Services
US Electrical Services Market
Mechanical and Electrical Services
Spur Gear Market
Mechanical and Electrical Services
MEP Services in US Market
Mechanical and Electrical Services
Diaphragm Coupling in Turbo Machinery Market
Mechanical and Electrical Services
Air Conditioning Repair Market
Mechanical and Electrical Services
Rotary Machinery Market
Mechanical and Electrical Services
Pressure Pumping Services Market