
 Thyroid Eye Disease Treatment Market | 2026-2036
Thyroid Eye Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Thyroid Eye Disease Treatment Market Analytics
Modular treatment protocols is pivoting how physicians sequence biologic and surgical interventions for thyroid eye disease. Horizon Therapeutics leverages its rare-disease commercial infrastructure to anchor infusion center partnerships. Viridian Therapeutics specializes in subcutaneous formulation development to differentiate from intravenous alternatives. Immunovant sustains clinical momentum through FcRn inhibitor research that competes with established IL-6 and IGF-1R pathways.
Thyroid eye disease treatment encompasses pharmacologic and surgical interventions targeting orbital inflammation, extraocular muscle dysfunction, and soft tissue expansion in Graves' orbitopathy; biologic agents functionally block cytokine signaling or receptor activation to halt disease progression before irreversible fibrosis develops. Monoclonal antibodies command the deepest margin pools as first-line biologics displace chronic corticosteroid dependence in active-phase patients. Delivery mode stratification reveals subcutaneous administration as the fastest-growing configuration, reducing hospital dependency and shifting site-of-care economics toward specialty clinics and home infusion.
FDA orphan drug designation and EMA PRIME eligibility frameworks compress development timelines and extend market exclusivity for novel mechanisms in this indication. The European Medicines Agency applies MDR conformity requirements to surgical implants used in orbital decompression, while Japan's PMDA maintains distinct Sakigake fast-track provisions for ophthalmic biologics. Stakeholders must monitor how biosimilar entry timelines for reference monoclonal antibodies reshape payer contracting and physician prescribing thresholds across markets.
Market Dynamics
FDA orphan drug designation and EMA PRIME eligibility frameworks compress development timelines for novel mechanisms in thyroid eye disease, reshaping how biologic developers sequence clinical programs and commercial infrastructure investments.
Growth Catalysts
- EMA Accelerated Assessment:The European Medicines Agency's fast-track pathway reduces review timelines for therapies addressing unmet needs in active-phase Graves' orbitopathy, incentivizing European trial site activation.
- Specialty Clinic Expansion:Oculoplastic and endocrine referral networks in the United States and Japan are expanding infusion center capacity to accommodate biologic administration outside hospital settings.
- Subcutaneous Formulation Engineering:Delivery mode innovation is reducing hospital dependency and shifting site-of-care economics toward home administration and ambulatory settings.
Market Restraints
- Biologic Manufacturing Concentration:Contract development and manufacturing organizations for monoclonal antibodies cluster in specific regions, creating supply vulnerability for sponsors without captive production.
- Chronic Corticosteroid Substitution Threshold:Physician prescribing habits in established markets retain systemic steroid protocols despite biologic alternatives, slowing first-line displacement.
- Reimbursement Lag for Surgical Sequencing:Payer coding frameworks have not adapted to modular treatment protocols combining pharmacologic and orbital decompression interventions.
Strategic Opportunities
- Home Infusion Channel Development:Specialty pharmacy networks capable of cold-chain biologic delivery to residential settings represent underdeveloped infrastructure in Germany and Japan.
- FcRn Inhibitor Mechanism Differentiation:Novel immunologic pathways competing with established IL-6 and IGF-1R blockade offer positioning white space for mechanism-of-action diversification.
- Japan Sakigake Fast-Track:PMDA ophthalmic biologic provisions enable priority review for therapies demonstrating efficacy in Japanese patient populations with distinct disease phenotypes.
Industry Challenges
- Oculoplastic-Endocrine Care Coordination:Fragmented referral pathways between thyroid specialists and orbital surgeons delay treatment initiation and complicate outcome measurement.
- Biosimilar Entry Preparation:Reference monoclonal antibody patent cliffs require incumbent developers to defend prescriber relationships before payer contracting shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thyroid Eye Disease Treatment Market |
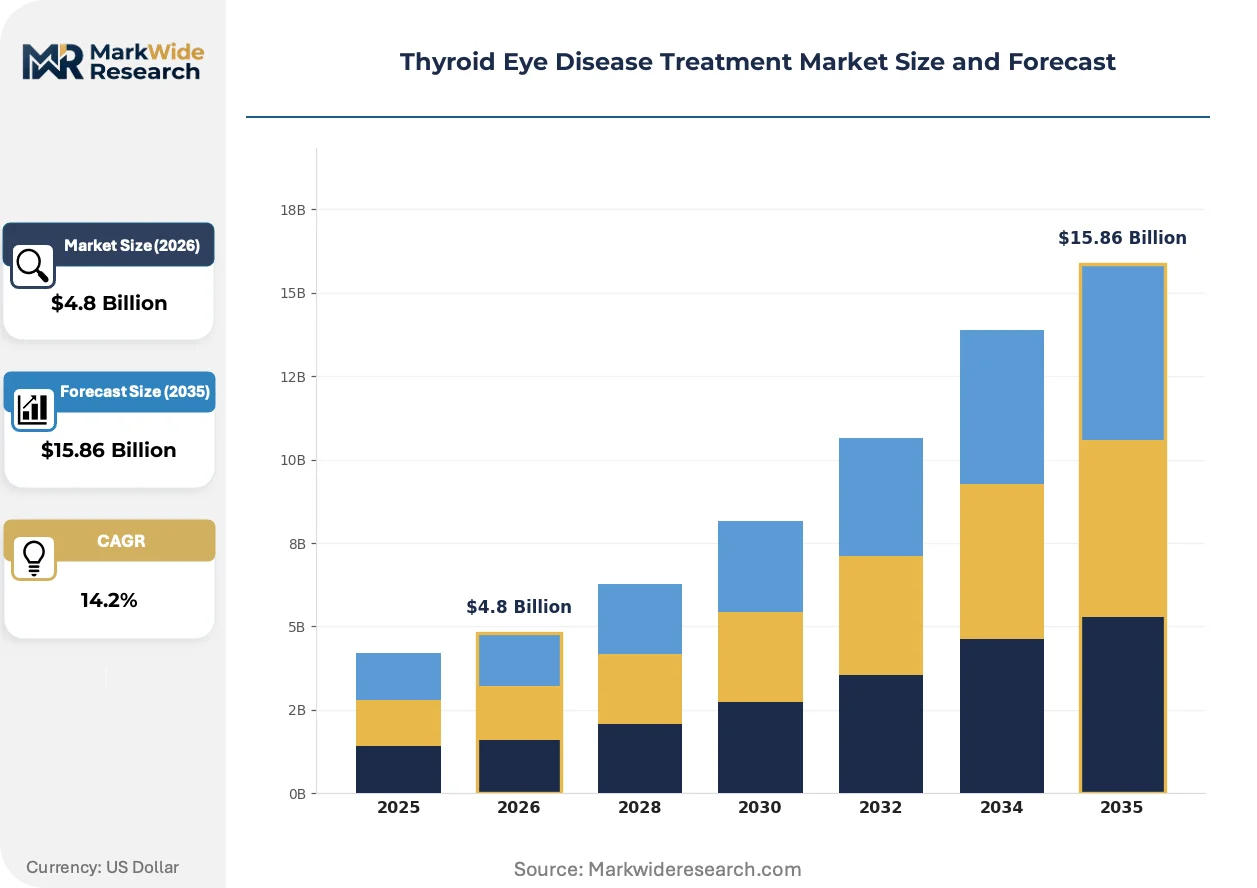
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Corticosteroids, Surgical Options, Thyroid Hormones Delivery Mode: Intravenous, Oral, Subcutaneous, Surgical End User: Hospitals, Specialty Clinics, Home Care, Research Institutions Treatment Stage: Active Phase, Chronic Phase, Remission Phase, Maintenance Phase |
| Companies Covered | Amgen, Horizon Therapeutics, Viridian Therapeutics, Regeneron Pharmaceuticals, Pfizer, Novartis, Roche, Immunovant, Sling Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thyroid Eye Disease Treatment Market Evolving Landscape
Modular treatment protocols are reordering how physicians sequence interventions, with biologic-surgical combination approaches displacing sequential monotherapy as the standard of care in active-phase disease management.
Subcutaneous biologic administration is converging with specialty clinic infrastructure investments, enabling site-of-care migration away from hospital-based infusion centers. Ambulatory surgery centers and independent ophthalmology practices in the United States are adopting cold-chain handling capabilities previously restricted to tertiary facilities. This convergence is compressing per-dose facility fees and redirecting margin capture toward drug acquisition and home nursing services.
EMA MDR conformity requirements now apply to orbital implants used in decompression surgery, mandating clinical evidence updates for legacy titanium and porous polyethylene devices. Surgical device manufacturers must resubmit technical documentation under the 2017/745 regulation, extending procurement cycles for hospital materials management departments. German and French university hospitals are prioritizing suppliers with completed MDR certifications in competitive tenders.
Site-of-care economics are driving payer preference for outpatient biologic administration over hospital-based infusion, with United States commercial plans and Medicare Advantage programs expanding specialty pharmacy network carve-outs. This channel migration requires manufacturers to restructure distribution agreements and patient support services. The shift is most pronounced in markets with mature home health nursing infrastructure and established specialty pharmacy consolidation.
Thyroid Eye Disease Treatment Market Segmentation
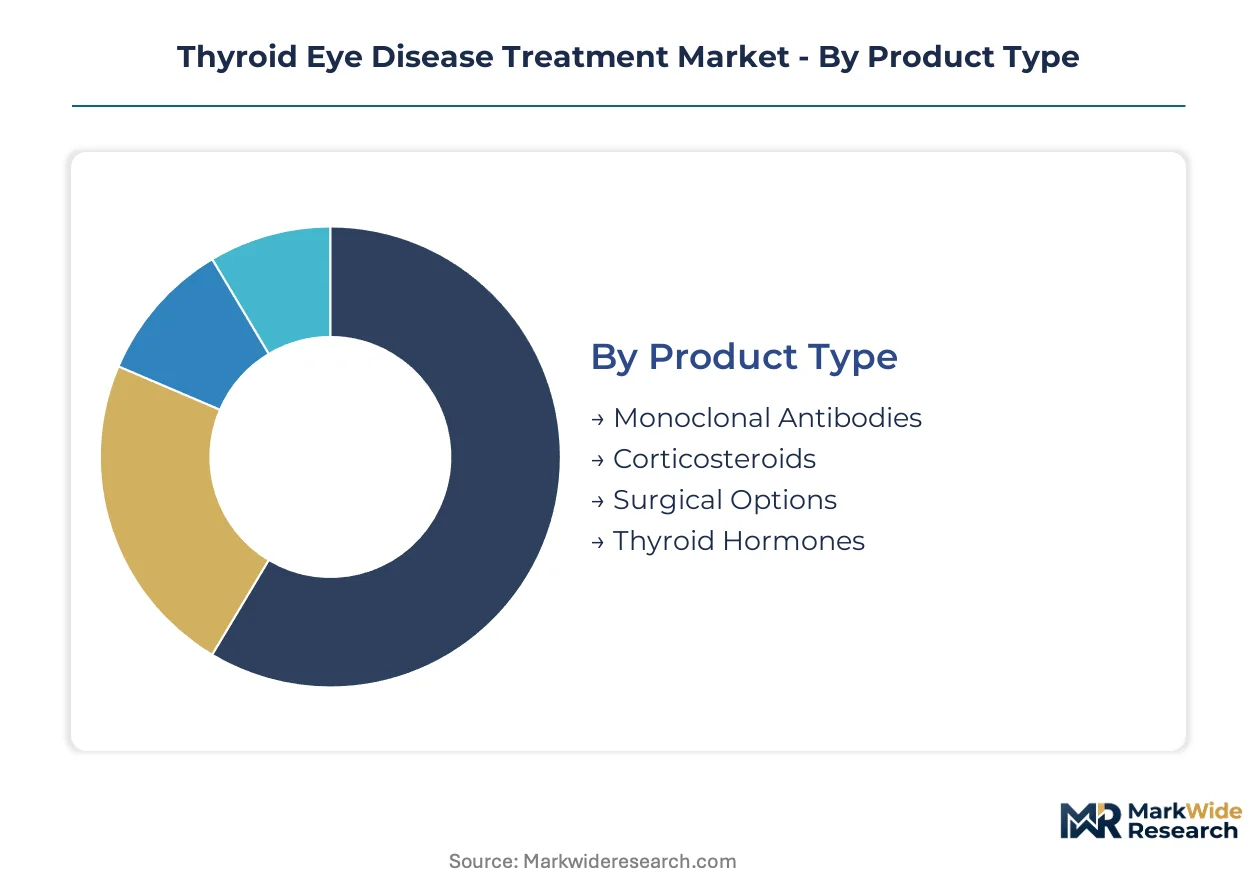
Segmentation in thyroid eye disease treatment reveals how clinical workflows, reimbursement pathways, and site-of-care economics fragment demand across modalities. Understanding these divisions exposes where margin pools concentrate and which configuration shifts threaten incumbent positioning.
Product Type:
Cost tier differentiation separates chronic management from acute intervention, with biologics commanding premium positioning against commoditized surgical and hormonal alternatives.
- Monoclonal Antibodies:Engineered immunoglobulins block IL-6 signaling or IGF-1R activation to arrest orbital inflammation before fibrotic remodeling. Demand concentrates in United States specialty clinics where prior authorization infrastructure supports biologic access, though EMA orphan drug pathways accelerate European adoption.
- Corticosteroids:Systemic and intraorbital glucocorticoid formulations remain the default first-line intervention in resource-constrained settings and mild-to-moderate active disease. Volume sits with oral prednisone protocols; growth tilts toward monoclonal antibodies as payer step-edit requirements relax in Germany and Japan.
- Surgical Options:Orbital decompression, strabismus correction, and eyelid repositioning address structural complications after inflammatory quiescence.
- Thyroid Hormones:Adjunctive levothyroxine or antithyroid agents manage underlying Graves' disease without direct orbital effect.
Margin capture concentrates in biologics; surgical volume expands with delayed diagnosis trends.
Delivery Mode:
Application context determines whether administration requires hospital infrastructure or permits ambulatory migration, reshaping distribution economics and patient adherence profiles.
- Subcutaneous:Self-administered formulations eliminate infusion center dependency and reduce facility fee burdens. United States specialty pharmacy networks and Japanese home nursing services are expanding cold-chain capabilities to support this shift.
- Intravenous:Hospital-based infusion maintains dominance for complex biologics requiring monitoring, though site-of-care carve-outs are compressing per-dose economics.
- Oral:Corticosteroid and hormonal protocols dominate prescription volume through primary care and endocrinology channels.
- Surgical:Orbital and extraocular muscle procedures require operative facilities with oculoplastic specialization.
Configuration leadership sits with intravenous platforms; patient preference and payer pressure are accelerating subcutaneous development pipelines.
End User:
Customer type fragmentation reflects referral pathway complexity between thyroid specialists, orbital surgeons, and primary management settings.
- Specialty Clinics:Dedicated oculoplastic and neuro-ophthalmology centers coordinate biologic initiation and surgical sequencing. United States metropolitan markets and Japanese university hospitals are expanding infusion capacity to capture site-of-care migration.
- Hospitals:Tertiary academic centers manage severe active-phase disease requiring multidisciplinary endocrine-ophthalmology coordination.
- Home Care:Subcutaneous administration and remote monitoring enable residential management for stable patients.
- Research Institutions:Phase II-III trial sites drive protocol development and investigator network formation.
Service volume concentrates in hospitals; patient flow is shifting fastest toward specialty clinic and home care channels.
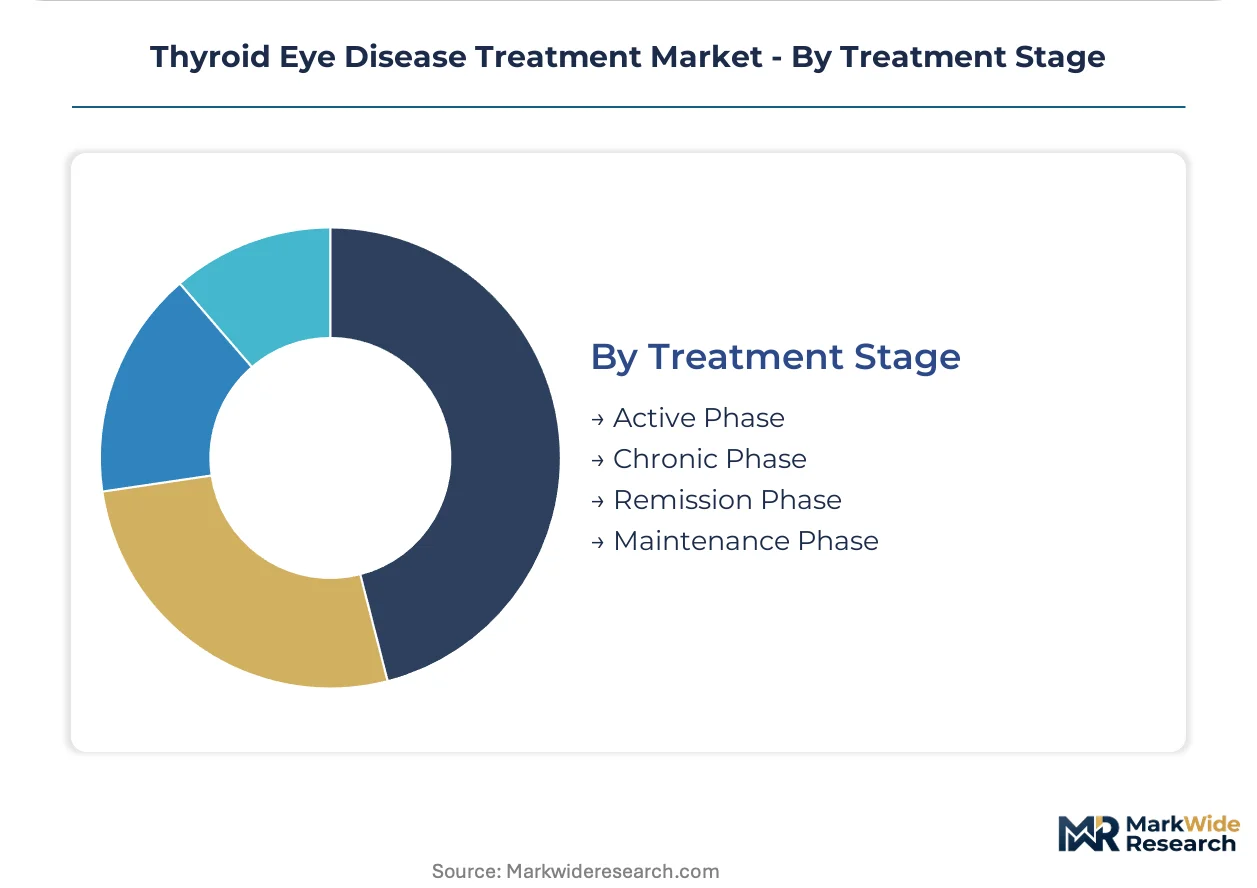
Treatment Stage:
Disease maturity at presentation dictates whether pharmacologic suppression, surgical rehabilitation, or maintenance monitoring dominates clinical resource allocation.
- Active Phase:Inflammatory disease with clinical activity score elevation requires urgent immunomodulation to prevent irreversible tissue changes. United States and German markets show highest biologic penetration here due to referral network density.
- Chronic Phase:Stable fibrotic sequelae drive surgical intervention demand for diplopia correction and cosmetic rehabilitation.
- Remission Phase:Disease quiescence with residual structural defects requires monitoring for reactivation.
- Maintenance Phase:Long-term thyroid function management prevents orbital recurrence without direct eye-specific therapy.
Clinical attention concentrates in active phase management; commercial investment is expanding most quickly into chronic phase surgical sequencing protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for biologic therapies sits with United States and German contract development organizations, while patient demand clusters in markets with mature oculoplastic referral networks. Consumption geography diverges from production geography, with Japan and specialized United States metropolitan markets driving per-capita treatment intensity.
United States
FDA orphan drug designation accelerates biologic development timelines for active-phase Graves' orbitopathy. Medicare Advantage and commercial payers are expanding specialty pharmacy carve-outs for subcutaneous administration. Boston and New York metropolitan areas anchor the densest oculoplastic-endocrine referral networks, with academic medical centers piloting modular treatment protocols.
Germany
EMA accelerated assessment pathways and PRIME eligibility compress regulatory review for novel mechanisms. University hospitals in Munich and Hamburg are prioritizing MDR-certified orbital implants in competitive tenders. The country's statutory health insurance funds are negotiating indication-based contracts for biologic sequencing before surgical intervention.
Japan
PMDA Sakigake fast-track provisions enable priority review for ophthalmic biologics demonstrating efficacy in Japanese patient populations. Tokyo and Osaka university hospitals maintain the highest density of dedicated thyroid eye disease clinics. Home nursing infrastructure supports cold-chain biologic delivery to residential settings for stable patients.
United Kingdom
NICE technology appraisals determine biologic reimbursement thresholds for National Health Service commissioning. London and Manchester house specialized oculoplastic units coordinating with endocrinology services. The country's regulatory alignment with EMA MDR requirements affects procurement cycles for orbital decompression devices.
Switzerland
Swissmedic maintains parallel review procedures with EMA for ophthalmic biologics while preserving independent pricing authority. Basel and Zurich academic centers participate in multinational clinical trial networks for FcRn inhibitor development. The country's compulsory health insurance system permits rapid access to approved therapies without prior authorization delays.
Thyroid Eye Disease Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the thyroid eye disease treatment landscape. Large pharmaceutical companies leverage established immunology franchises and rare-disease commercial infrastructure against biotechnology firms concentrating on single mechanisms. Three archetypes dominate: platform biologic developers with multi-indication pipelines, orbital surgery device manufacturers with MDR certification priorities, and specialty clinic operators consolidating regional referral networks. Competitive moves center on infusion center partnership expansion and subcutaneous formulation differentiation.
Among United States-based biologic developers, Horizon Therapeutics, Viridian Therapeutics, and Immunovant exemplify distinct strategic positioning within the competitive structure. Horizon Therapeutics occupies a position anchoring rare-disease commercial infrastructure against larger immunology franchises. Viridian Therapeutics represents the subcutaneous formulation specialization archetype, differentiating from intravenous alternatives. Immunovant sits within the novel mechanism tier, competing through FcRn inhibitor research against established cytokine signaling pathways.
| Leading Market Players |
|---|
| Amgen |
| Horizon Therapeutics |
| Viridian Therapeutics |
| Regeneron Pharmaceuticals |
| Pfizer |
| Novartis |
| Roche |
| Immunovant |
| Sling Therapeutics |
| Others |
Value Network & Pricing Analysis
Subcutaneous formulation engineering simultaneously compresses manufacturing complexity and redistributes margin capture toward specialty pharmacy networks, tightening supply concentration among CDMOs with cold-chain biologic capabilities while amplifying price differentiation between hospital-based infusion and ambulatory administration models.
Pricing Analysis
Margin tightening in biologic tiers reflects site-of-care migration pressure as United States commercial payers expand specialty pharmacy carve-outs for subcutaneous alternatives. Three-tier pricing structure across premium biologics, standard monoclonal antibodies, and economy corticosteroid protocols stratifies by certification level and administration setting. Cost-down pressure on intravenous formulations accelerates because facility fee compression erodes hospital-based economics. Price sensitivity concentrates in German statutory health insurance funds negotiating indication-based contracts, while United States Medicare Advantage programs show lowest sensitivity due to prior authorization infrastructure.
Supply Chain Analysis
Monoclonal antibody production rests on contract manufacturing concentration in the United States, Germany, and Switzerland, with active pharmaceutical ingredient synthesis drawing from Irish and Singaporean biologics hubs. Critical dependencies include cell culture media, single-use bioreactor systems, and cold-chain packaging validated for biologic stability. Single-source vulnerability sits with fill-finish capacity at specialized CDMOs serving orphan disease indications. Distribution runs through specialty pharmacy networks capable of patient-specific cold-chain delivery, with hospital procurement departments managing surgical implant inventory under EMA MDR conformity timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologic manufacturing capacity constraints prop pricing power for sponsors with captive production or secured CDMO slots, creating supply-constrained dynamics that favor early movers in subcutaneous formulation development.
For Market Incumbents: Acquire fill-finish manufacturing capacity in Germany or Switzerland to secure supply continuity against CDMO queue competition. Consolidate infusion center partnerships in United States metropolitan markets before biosimilar entry erodes prescriber loyalty. Prioritize MDR certification completion for orbital implant portfolios to defend hospital procurement positioning against device manufacturers with delayed technical documentation. For New Entrants and Emerging Players: Mid-tier pricing gaps between premium monoclonal antibodies and generic corticosteroid protocols create entry space for FcRn inhibitor mechanisms with differentiated immunologic positioning. Target Japanese university hospital networks leveraging PMDA Sakigake fast-track provisions for ophthalmic biologics. Pursue home infusion channel development in Germany where specialty pharmacy cold-chain infrastructure remains underdeveloped relative to patient demand. For Investors and Strategic Acquirers: Exit pathways concentrate in platform biologic developers with multi-indication pipelines and established rare-disease commercial infrastructure. Long-term viability favors sponsors with vertical integration into biologic manufacturing or exclusive CDMO relationships spanning the projection horizon. Monitor EMA accelerated assessment award rates as inflection signal for European market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Reduces hospital dependency and shifts site-of-care economics toward specialty pharmacy networks in United States metropolitan markets. |
| Infusion Center Partnership Expansion | Captures patient flow migration from tertiary hospitals to ambulatory settings with compressed per-dose facility fees. |
| FcRn Inhibitor Clinical Advancement | Creates mechanism-of-action differentiation against established IL-6 and IGF-1R blockade pathways in active-phase disease. |
| MDR Certification Completion | Secures competitive tender positioning for orbital implants in German and French university hospital procurement cycles. |
| Home Infusion Channel Investment | Enables cold-chain biologic delivery to residential settings in Japan and Germany where nursing infrastructure supports site-of-care migration. |
Research Methodology
Document review covered FDA orphan drug designation records, EMA PRIME eligibility databases, and PMDA Sakigake fast-track announcements, complemented by interviews with oculoplastic surgeons, endocrinology referral coordinators, biologic access specialists at United States commercial payers, and procurement managers at German university hospitals. Secondary validation drew from ClinicalTrials.gov protocol registrations, hospital formulary databases, and MDR certification status trackers. Bottom-up patient flow modeling triangulated against top-down biologic revenue estimates across the analysis window.
Cross-referencing historical prescription patterns against investigator panel input anchored the forecast framework. Segmentation dimensions modeled include treatment stage, delivery mode, and regional regulatory cluster. CAGRs were derived from patient population projections weighted by biologic penetration assumptions and surgical sequencing protocol adoption curves. Forecast inputs incorporated prior authorization approval rates and specialty pharmacy network expansion timelines.
Underlying measurement precision varies by segment; active-phase biologic demand carries tighter precision than chronic-phase surgical volume given referral pathway fragmentation. Forecasts reflect assumptions about EMA accelerated assessment award rates and United States payer step-edit relaxation timelines. Biosimilar entry velocity and CDMO capacity constraints represent primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Synoptophore Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Global Hemianopsia Market
Ophthalmology
Eye Infections Treatment Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Eye Care Surgical Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
Blue Light Blocking Contact Lenses Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market