
 Global Ophthalmoplegia Market | 2026-2036
Global Ophthalmoplegia Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ophthalmoplegia Market Foresight
Aftermarket service revenue from post-surgical monitoring and long-term neuromuscular rehabilitation programs is tilting toward biologics-dependent care models. Novartis AG leverages its ophthalmology franchise depth to sustain neuro-ophthalmology pipeline investments. Pfizer Inc. anchors its position through broad-spectrum neurology partnerships that extend into rare movement disorders. Regeneron Pharmaceuticals differentiates via retinal-neural crossover research platforms that compete for specialist prescriber attention.
Ophthalmoplegia encompasses paralytic conditions affecting the extraocular muscles or their cranial nerve innervation, typically arising from trauma, vascular insult, demyelination, or compressive neuropathies, with diagnostic workup requiring forced duction testing, neuroimaging, and targeted serological assays to localize the lesion and guide intervention. The condition serves commercial and clinical purposes primarily through restoration of binocular alignment, prevention of amblyopia in pediatric presentations, and mitigation of diplopia-related disability in adult populations. Pharmaceuticals and biologics command concentrated margin pools as chronic immunomodulatory and targeted therapies displace repeated surgical correction, while gene therapy segments attract development capital despite longer regulatory timelines. Devices and surgical interventions retain stable demand in acute compressive cases and congenital cranial nerve palsies where anatomical correction remains necessary.
FDA breakthrough therapy designation and EMA PRIME eligibility are compressing development timelines for novel biologics in rare neuro-ophthalmic indications, while WHO essential medicines criteria and national formulary inclusion decisions shape reimbursement access across divergent healthcare systems. Japan's PMDA orphan drug framework and China's NMPA conditional approval pathways create parallel regulatory tracks that manufacturers must navigate simultaneously. Stakeholders should monitor how real-world evidence requirements evolve for durable gene therapy interventions versus chronic pharmaceutical administration.
Market Dynamics
Gene therapy platforms are compressing development timelines for chronic ophthalmoplegia management while displacing repeated surgical intervention as the default care pathway in tertiary neuro-ophthalmology centers.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:Accelerated review timelines for novel biologics targeting rare cranial nerve disorders compress commercialization cycles and attract venture capital into neuro-ophthalmic pipelines.
- Pediatric Strabismus Correction:Early intervention protocols in congenital cranial nerve palsies prevent amblyopia progression and create sustained demand for specialized surgical and pharmacologic services.
- Japan PMDA Orphan Drug Framework:Tax incentives and priority review vouchers for rare disease therapeutics incentivize manufacturers to pursue indications with limited prevalence but high unmet need.
Market Restraints
- Gene Therapy Manufacturing Concentration:Viral vector production capacity clusters in select contract manufacturing organizations, creating supply bottlenecks for late-stage clinical candidates.
- Reimbursement Compression:National formulary inclusion decisions in Germany and Japan impose cost-effectiveness thresholds that delay patient access to premium biologics.
- Surgical Substitution Limits:Anatomical correction remains necessary for compressive neuropathies and trauma cases, constraining the addressable market for pharmaceutical-only interventions.
Strategic Opportunities
- China NMPA Conditional Approval:Real-world evidence pathways for urgent medical needs enable earlier revenue generation while confirmatory trials continue.
- Telemedicine-Enabled Referral Networks:Remote forced duction testing and neuroimaging interpretation extend specialist reach into underserved rural populations across the United States.
- Biologics-Device Convergence:Sustained-release depot formulations paired with adjustable suture techniques reduce revision surgery rates in complex paralytic strabismus.
Industry Challenges
- Neuro-Ophthalmologist Workforce Scarcity:Fellowship-trained specialists concentrate in academic medical centers, limiting patient access in community hospital settings.
- Gene Therapy Cold Chain Complexity:Ultra-low temperature storage requirements for viral vectors strain distribution infrastructure and create wastage risk in lower-volume treatment centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ophthalmoplegia Market |
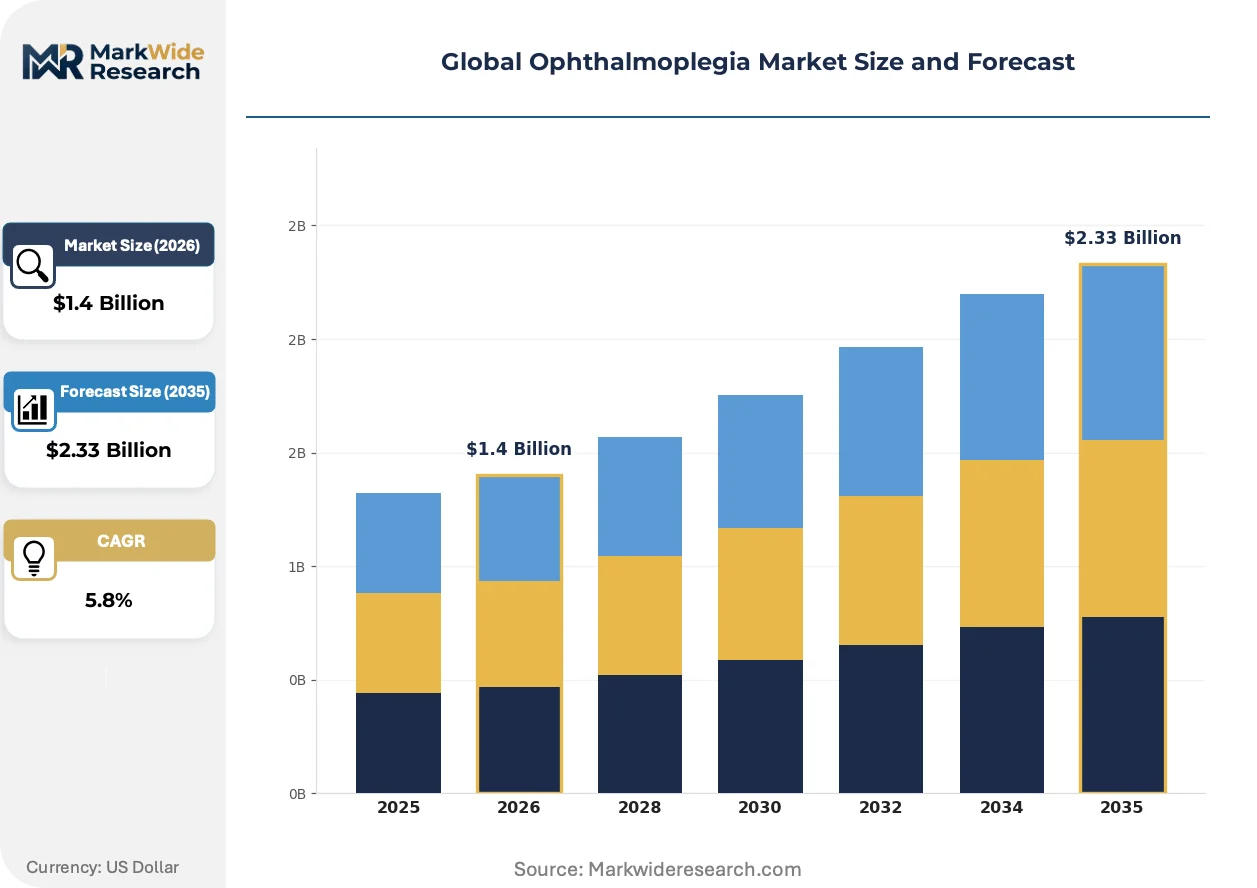
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Biologics, Devices, Surgical Interventions End User: Hospitals, Clinics, Research Laboratories, Home Healthcare Technology: Gene Therapy, Monoclonal Antibodies, Neuromodulation, Surgery Delivery Mode: Injectable, Oral, Topical, Others |
| Companies Covered | Novartis AG, Sanofi, F. Hoffmann-La Roche Ltd., Pfizer Inc., Bayer AG, Bausch Health, Regeneron Pharmaceuticals, Allergan, Santen Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ophthalmoplegia Market Shifts & Advancements
Biologics-dependent care models are displacing episodic surgical correction as the dominant revenue architecture, while regulatory innovation compresses timelines for rare disease therapeutics.
Adeno-associated viral vector delivery is migrating from experimental protocols toward first-line chronic management in specialized neuro-ophthalmology departments. Academic medical centers in the United States and Germany are establishing dedicated gene therapy infusion suites with integrated forced duction monitoring protocols. This platform shift is compressing the interval between diagnosis and durable functional restoration while elevating reimbursement complexity for one-time versus recurring interventions.
EMA PRIME eligibility criteria are streamrolling scientific advice and accelerated assessment for medicines targeting unmet medical needs in rare neuro-ophthalmic conditions. Manufacturers gain enhanced regulatory dialogue and potential conditional marketing authorization based on surrogate endpoints. Pediatric indications and progressive mitochondrial disorders are securing disproportionate benefit from this framework due to ethical constraints on placebo-controlled trials.
Hospital procurement committees are consolidating vendor relationships for biologics and surgical devices into single-source agreements with outcome guarantees. Tertiary referral centers in Japan and the United States now require manufacturers to provide real-world effectiveness data as a contract condition. This behavioral shift concentrates purchasing power among integrated delivery networks and disadvantages smaller manufacturers lacking health economics capabilities.
Global Ophthalmoplegia Market Segmentation
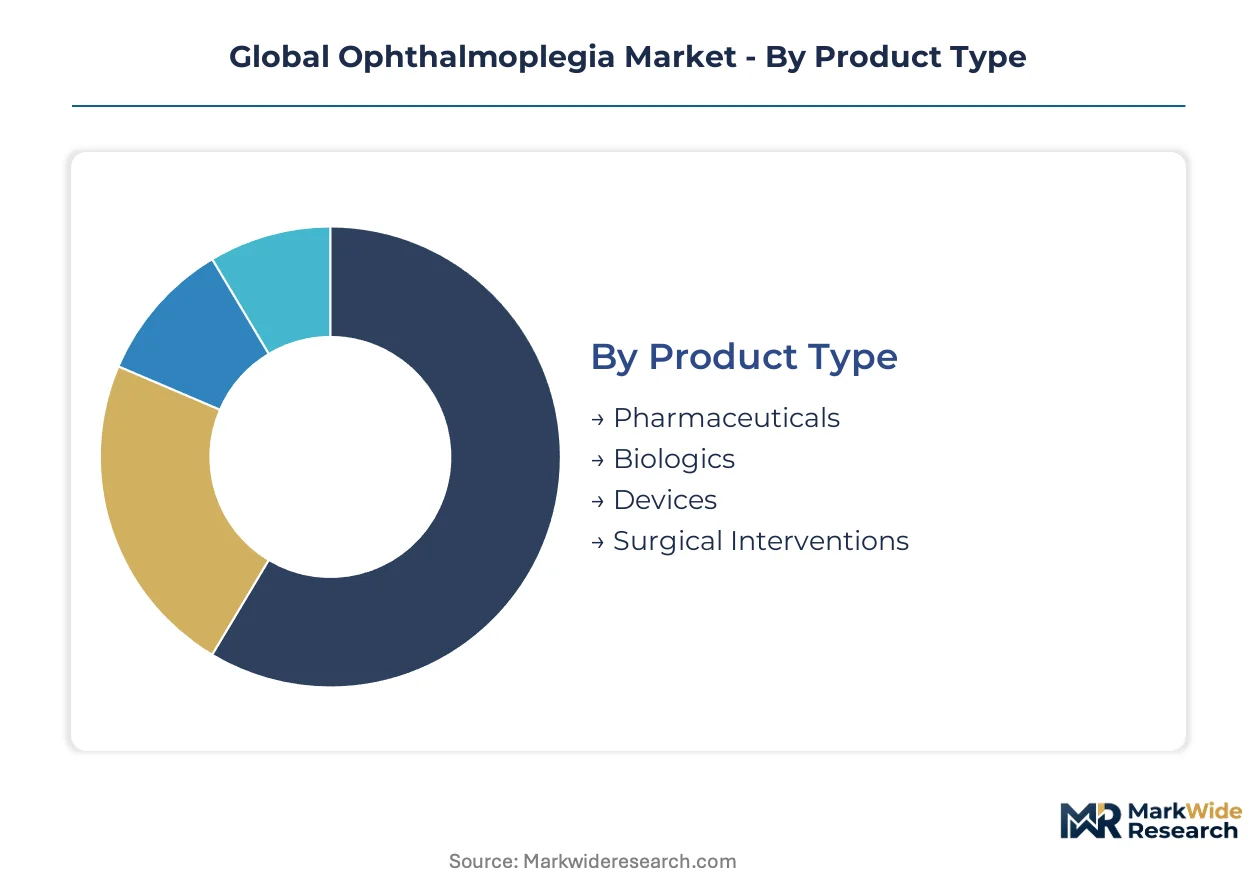
Segmentation reveals how treatment paradigms split between durable interventions and chronic management models. Understanding these divisions helps stakeholders allocate R&D capital across gene therapy platforms, biologics manufacturing, and surgical device portfolios.
Product Type:
Mature surgical interventions coexist with emerging gene therapy platforms as neuro-ophthalmology departments recalibrate their service mix.
- Pharmaceuticals:Small-molecule immunomodulators and corticosteroid formulations address acute inflammatory cranial nerve palsies. Demand clusters in United States hospital emergency departments and German outpatient neurology clinics where rapid diplopia control prevents disability progression.
- Biologics:Monoclonal antibodies targeting complement pathways and cytokine signaling deliver sustained functional improvement in chronic autoimmune-mediated ophthalmoplegia. Tertiary referral centers in Japan and the United States are prioritizing these agents for myasthenia gravis-associated extraocular muscle weakness.
- Devices:Adjustable suture systems and forced duction measurement instruments support intraoperative decision-making.
- Surgical Interventions:Strabismus correction and decompression procedures remain necessary for compressive neuropathies and trauma cases.
Pharmaceuticals handle the majority of throughput; biologics are gaining share fastest as immunomodulatory protocols displace repeated surgical revision.
End User:
Volume concentrates in institutional settings while cost pressures push monitoring into lower-acuity environments.
- Hospitals:Academic medical centers in the United States, Germany, and Japan house specialized neuro-ophthalmology departments with integrated gene therapy infusion suites and intraoperative electrophysiology monitoring. These facilities capture complex congenital cases and acquired compressive neuropathies requiring multidisciplinary coordination.
- Clinics:Private ophthalmology practices and community neurology clinics manage stable chronic cases with periodic botulinum toxin injection and prism adaptation protocols. Germany's ambulatory care reimbursement framework supports high-volume outpatient strabismus correction.
- Research Laboratories:Academic and contract research organizations conduct natural history studies and biomarker validation for rare mitochondrial disorders affecting extraocular muscles.
- Home Healthcare:Visiting nurse services administer depot formulations and coordinate rehabilitation exercises for mobility-limited patients.
Hospitals anchor revenue concentration; home healthcare is expanding most quickly as payors seek alternatives to institutional reimbursement.
Technology:
Margin profiles diverge sharply between one-time curative interventions and recurring pharmaceutical administration.
- Gene Therapy:Adeno-associated viral vector delivery of neurotrophic factors and mitochondrial gene replacement targets progressive chronic ophthalmoplegia. FDA breakthrough therapy designation and EMA PRIME eligibility accelerate development timelines for candidates addressing Leber hereditary optic neuropathy and chronic progressive external ophthalmoplegia.
- Monoclonal Antibodies:Targeted immunotherapy for myasthenia gravis and thyroid eye disease reduces extraocular muscle inflammation. United States specialty pharmacies and Japanese hospital pharmacies manage cold chain distribution for these temperature-sensitive biologics.
- Neuromodulation:Non-invasive and implantable electrical stimulation devices explore adjunctive treatment for nerve regeneration.
- Surgery:Microsurgical techniques and adjustable suture technologies enable personalized anatomical correction.
Surgery retains the largest installed base; gene therapy shows the steepest expansion trajectory as viral vector manufacturing scales.
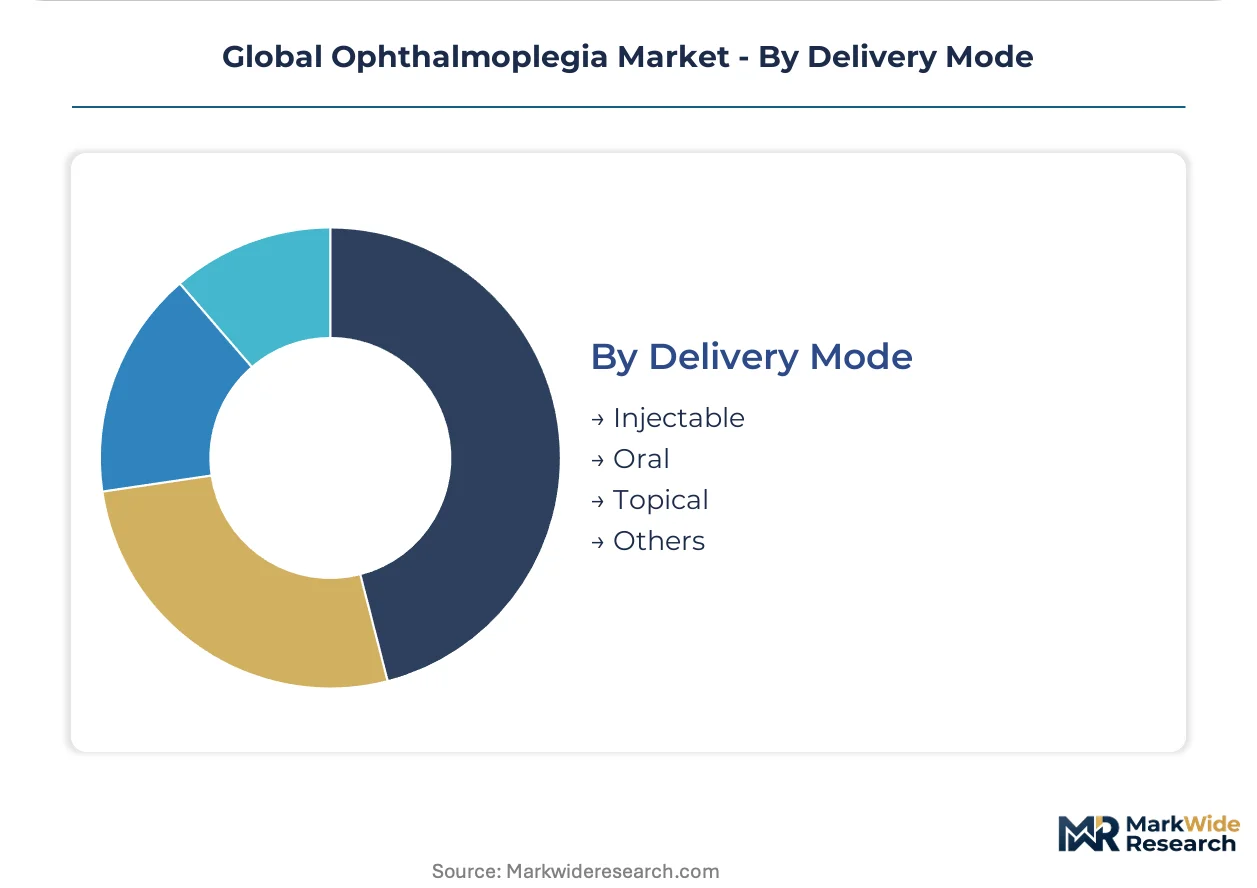
Delivery Mode:
Route selection depends on anatomical target accessibility and duration of therapeutic effect required.
- Injectable:Intravitreal, peribulbar, and intramuscular delivery routes dominate biologics administration. United States ambulatory surgery centers and Japanese hospital infusion suites have adapted workflows for viral vector gene therapy injections requiring specialized handling protocols.
- Oral:Small-molecule immunomodulators and mitochondrial supplements support chronic maintenance therapy. German statutory health insurance formulary inclusion decisions heavily influence prescribing patterns for these agents.
- Topical:Ocular surface preparations address associated dry eye and exposure keratopathy in paralytic lagophthalmos.
- Others:Transdermal patches and implantable depot systems explore sustained-release alternatives.
Injectable formats command premium pricing; oral administration is climbing the fastest as manufacturers reformulate biologics for subcutaneous delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity for premium biologics, while cost-conscious procurement in China and India compresses margins for standard surgical interventions. Reimbursement frameworks in the United States and Switzerland sustain premium pricing for gene therapy candidates. Demand fragmentation across these five markets creates divergent go-to-market requirements.
United States
Academic medical centers in Boston and Baltimore house the highest concentration of specialized neuro-ophthalmology departments with integrated gene therapy infusion capabilities. FDA breakthrough therapy designation accelerates commercialization timelines for viral vector candidates targeting chronic progressive external ophthalmoplegia. The Cleveland Clinic and Johns Hopkins anchor clinical trial recruitment for mitochondrial disorder interventions.
Germany
Statutory health insurance formulary inclusion decisions impose stringent cost-effectiveness thresholds that delay patient access to novel monoclonal antibodies. EMA centralized marketing authorization procedures enable simultaneous access across federal states once reimbursement is secured. Heidelberg and Tübingen university hospitals coordinate the GANNET network for rare neuro-ophthalmic disease natural history studies.
Japan
PMDA orphan drug tax incentives and priority review vouchers attract manufacturers to indications with prevalence below 50,000 patients. National health insurance price premiums for designated orphan therapeutics sustain domestic R&D investment. Tokyo Medical University Hospital and Osaka University Hospital operate dedicated ocular motility disorder referral centers with embedded forced duction testing protocols.
China
NMPA conditional approval pathways based on real-world evidence enable earlier revenue generation while confirmatory trials continue. Provincial centralized procurement drives price compression for conventional strabismus surgical devices. Shanghai Jiao Tong University Affiliated Sixth People's Hospital and Zhongshan Ophthalmic Center in Guangzhou lead multi-center gene therapy investigator-initiated trials.
Switzerland
Swissmedic accelerated assessment procedures for medicines addressing unmet medical needs compress regulatory review timelines. Cantonal hospital networks in Zurich and Geneva maintain dedicated neuro-ophthalmology units with intraoperative electrophysiology monitoring. The country's mandatory health insurance framework includes premium biologics in basic benefit catalogs without prior authorization requirements.
Global Ophthalmoplegia Market Competitive Landscape
Capability concentration sits with specialized biopharmaceutical developers; scale advantage sits with diversified pharmaceutical conglomerates. The market exhibits tiered structure with gene therapy platforms commanding development-stage premiums and established surgical device manufacturers defending installed base positions. Three archetypes dominate: viral vector specialists, broad neurology franchises, and ophthalmology-focused biologics developers. Consolidation activity centers on gene therapy manufacturing capacity acquisition and neuro-ophthalmology referral network partnerships.
Among Swiss-based pharmaceutical conglomerates, Novartis AG and Roche anchor the diversified tier with ophthalmology franchise depth. Pfizer Inc. represents the broad neurology partnership model extending into rare movement disorders. Regeneron Pharmaceuticals occupies a position exemplifying retinal-neural crossover research platforms competing for specialist prescriber attention.
| Leading Market Players |
|---|
| Novartis AG |
| Sanofi |
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Bayer AG |
| Bausch Health |
| Regeneron Pharmaceuticals |
| Allergan |
| Santen Pharmaceutical |
| Others |
Supply & Pricing Matrix
Viral vector manufacturing clusters in the United States and Germany capture disproportionate margin pools as gene therapy platforms displace episodic surgical correction in tertiary neuro-ophthalmology centers. Cold chain infrastructure requirements and single-source biologics contracts concentrate pricing power among integrated delivery networks while fragmenting procurement leverage for standalone community hospitals.
Pricing Analysis
Aftermarket service revenue from long-term neuromuscular rehabilitation monitoring and post-surgical follow-up protocols drives lifetime value capture for device and biologics manufacturers alike. Pricing stratifies across premium, standard, and economy tiers based on FDA breakthrough therapy designation status and bundled after-sales service commitments. Cost compression in German statutory health insurance formulary negotiations is intensifying because national cost-effectiveness thresholds delay access to novel monoclonal antibodies. Pediatric referral centers demonstrate the lowest price sensitivity due to ethical urgency and limited therapeutic alternatives, while provincial procurement committees in China exhibit the highest elasticity for conventional strabismus surgical instruments.
Supply Chain Analysis
Export-control restrictions on adeno-associated viral vector production technology limit technology transfer to contract manufacturing organizations outside approved jurisdictions. Active pharmaceutical ingredient synthesis draws from Switzerland, the United States, and Japan for high-purity immunomodulators, while viral vector seed stocks and specialized forced duction measurement instruments rest on single-source suppliers in Germany and Massachusetts. Tariff exposure on temperature-controlled logistics equipment creates supply vulnerability for gene therapy cold chain distribution. Distribution runs through hospital procurement committees and specialty pharmacy networks with integrated infusion suite partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. FDA breakthrough therapy designation and EMA PRIME eligibility create multi-year head starts that compound through clinical data generation and prescriber relationship depth.
For Market Incumbents: Entrench position through captive viral vector manufacturing capacity in Boston and Baltimore corridor facilities, insulating against supply bottlenecks that constrain emerging competitors. Deepen backward integration into mitochondrial disorder natural history databases to control biomarker validation pathways. Priority investment in telemedicine-enabled forced duction testing protocols defends against ambulatory surgery center encroachment on routine monitoring revenue.
For New Entrants and Emerging Players: China's NMPA conditional approval pathway offers the most penetrable regulatory entry point, with real-world evidence requirements lower than FDA confirmatory trial standards. Target investigator-initiated trial partnerships at Shanghai Jiao Tong University and Zhongshan Ophthalmic Center to generate publication assets before formal commercial infrastructure deployment. Go-to-market execution should emphasize biosimilar monoclonal antibody positioning in thyroid eye disease adjacent indications.
For Investors and Strategic Acquirers: Capital is best deployed toward gene therapy platform developers with demonstrated viral vector manufacturing scale and existing FDA breakthrough therapy designations in mitochondrial ophthalmoplegia indications. Long-term viability over the medium-term horizon rests on durability of functional improvement data versus chronic pharmaceutical administration models. Watch for EMA PRIME eligibility announcements as inflection indicators for accelerated assessment timelines and enhanced valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Captive viral vector capacity in Boston corridor insulates against CMO bottlenecks. |
| FDA Breakthrough Therapy Designation | Accelerated review timelines compress development cycles for rare neuro-ophthalmic indications. |
| Hospital System Partnership | Integrated delivery network contracts concentrate purchasing power and lock out competitors. |
| Reimbursement Strategy | Swissmedic and German statutory inclusion decisions determine European market access. |
| Pipeline Diversification | Retinal-neural crossover platforms compete for specialist prescriber attention across indications. |
Research Methodology
Operator-level perspectives from neuro-ophthalmology department heads, gene therapy manufacturing executives, hospital procurement committee chairs, and specialty pharmacy distribution managers anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FDA breakthrough therapy designation filings, EMA PRIME eligibility databases, ClinicalTrials.gov mitochondrial disorder protocols, and Japanese PMDA orphan drug tax incentive records. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation cross-checked segmentation outputs.
Scenario-bracketing around regulatory approval timelines, viral vector manufacturing yield assumptions, and reimbursement inclusion probability weighted the projection framework across the analysis window. Segmentation dimensions modeled include treatment modality, delivery route, end-user facility type, and regional regulatory cluster. CAGRs derived from epidemiological prevalence trajectories, therapy penetration curves, and pricing evolution assumptions for one-time gene therapy versus chronic biologic administration. Forecast inputs incorporated PMDA orphan drug voucher issuance rates and NMPA conditional approval pathway utilization.
Practitioners should monitor FDA breakthrough therapy designation revocation patterns and EMA PRIME withdrawal decisions for early signals of regulatory sentiment shifts. Forecasts reflect documented assumptions on viral vector manufacturing scale-up timelines and national formulary inclusion probability. Material shifts in gene therapy durability data or German cost-effectiveness threshold recalibration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Artificial Iris Market
Ophthalmology
Uveal Melanoma Treatment Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Usher Syndrome Market
Ophthalmology
Retinal Disease Therapeutics Market
Ophthalmology
Vitreous Detachment Treatment Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
Global Ophthalmic Perimeters Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Global Ophthalmology Drugs and Devices Market
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Global Advanced Ophthalmology Technologies Market