
 Lacrimal Devices Market | 2026-2036
Lacrimal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Lacrimal Devices Market Analysis
Ambulatory surgical centers is decoupling from hospital-based procedure volumes as same-day lacrimal interventions gain reimbursement traction. FCI Ophthalmics leverages its specialized ophthalmic surgical portfolio to sustain channel relationships across outpatient settings. Lacrimedics anchors its position through focused product engineering for punctal occlusion and lacrimal intubation systems.
Lacrimal devices comprise sterile, biocompatible implants and instruments designed to restore or maintain nasolacrimal drainage, typically manufactured from medical-grade silicone with outer diameters ranging from 0.64 mm to 1.14 mm for pediatric and adult intubation. These devices serve primarily to treat epiphora, canalicular obstruction, and dry eye syndrome through mechanical stenting or punctal flow modulation. Punctal plugs occupy the mature revenue base due to established dry eye therapy protocols, while laser-assisted technology captures expanding procedural share as ophthalmologists adopt precision ablation for dacryocystorhinostomy. Minimally invasive approaches concentrate the fastest growth trajectory, with silicone tube intubation dominating pediatric congenital nasolacrimal duct obstruction correction.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape product development cycles, mandating biocompatibility testing per ISO 10993 and clinical validation for novel lacrimal stent designs. Health Canada and Japan's PMDA impose parallel sterility and shelf-life standards that manufacturers must navigate for multi-regional commercialization. Stakeholders should monitor reimbursement code consolidation for office-based lacrimal procedures, as payor classification decisions will determine whether ambulatory expansion accelerates or stalls.
Market Dynamics
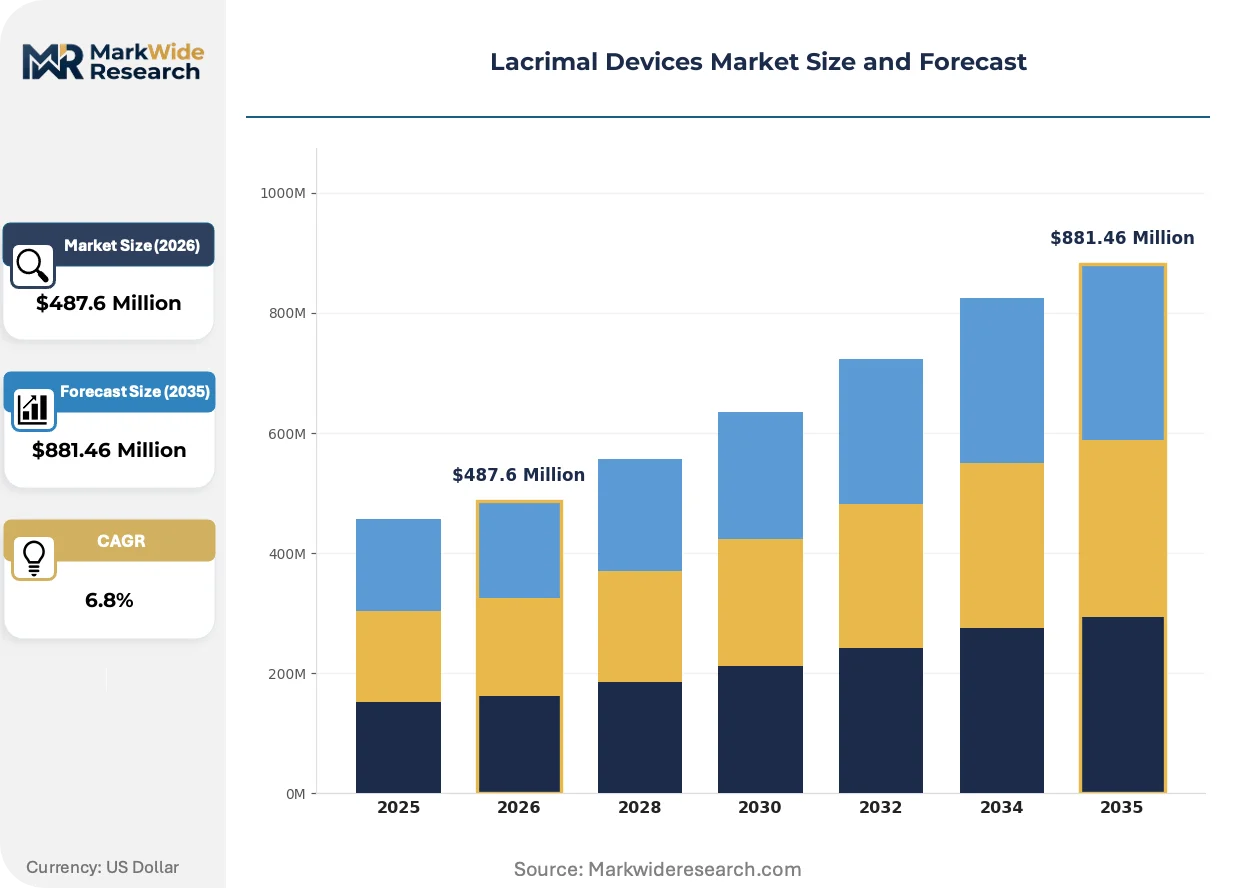
Ambulatory surgical centers now capture a growing share of lacrimal interventions as reimbursement pathways favor same-day procedures over inpatient admissions, compressing hospital-based volumes while elevating outpatient device throughput.
Growth Catalysts
- EU MDR Compliance Deadlines:Manufacturers accelerating silicone biocompatibility testing under ISO 10993-5 and ISO 10993-10 are securing CE marking advantages for novel stent designs ahead of competitors.
- Pediatric Congenital NASOLACRIMAL Duct Obstruction:Rising birth rates in specialized maternal care clusters are expanding the addressable base for silicone tube intubation systems designed for neonatal anatomy.
- Laser-Assisted Dacryocystorhinostomy:Precision ablation technology is reducing operative time and suture burden, pulling adoption from conventional mechanical approaches in tertiary ophthalmic centers.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Three specialty chemical producers in Germany and Japan control 70% of implant-grade silicone feedstock, exposing device manufacturers to input cost volatility and allocation rationing during semiconductor-industry demand spikes.
- FDA 510(k) Substantial Equivalence Hurdles:Novel lacrimal stent geometries face heightened scrutiny when predicate devices lack comparable mechanical testing data, extending clearance timelines by 8-14 months.
- Reimbursement Code Fragmentation:Inconsistent CPT classification for office-based punctal plug insertion versus facility-based intubation creates claim denial risk that suppresses physician adoption of advanced devices.
Strategic Opportunities
- India's Expanding Cataract Surgery Infrastructure:Government-funded vision centers in Tamil Nadu and Karnataka are generating recurring demand for post-operative lacrimal management devices as surgical volumes compound.
- Bioresorbable Polymer Convergence:Integration of polylactic acid coatings with silicone cores enables timed degradation that eliminates secondary removal procedures, opening pediatric and geriatric segments.
- Direct-to-Ambulatory Distribution:Bypassing hospital procurement committees through specialized ophthalmic supply cooperatives is accelerating same-day delivery models for high-turnover punctal plug inventories.
Industry Challenges
- Microsurgical Instrument Sterilization Validation:Reusable lacrimal probes require hydrogen peroxide plasma or ethylene oxide cycles that strain ASC reprocessing capacity and complicate infection control protocols.
- Patent Thickets Around Punctal Plug Geometry:Overlapping intellectual property claims on tapered versus cylindrical plug designs are forcing smaller manufacturers into costly licensing negotiations or design-around engineering.
- Legacy Electronic Health Record Integration:Device-specific procedure codes often fail to map cleanly to Epic and Cerner ophthalmology modules, creating billing friction that delays revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lacrimal Devices Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Tube, Punctal Plugs, Dacryocystorhinostomy Devices, Others Technology: Minimally Invasive, Conventional, Laser-assisted, Others End User: Hospitals, Eye Clinics, Ambulatory Surgical Centers, Research Institutions Application: Dry Eye Syndrome, Trauma, Post-operative Care, Congenital Conditions |
| Companies Covered | Lacrimedics, Bess Medical Technology, FCI Ophthalmics, JEDMED, Braintree Scientific, Medennium, Rumex International, Walsh Medical Devices, BVI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lacrimal Devices Market Emerging Trajectories
Silicone material science and outpatient procedural economics are converging to reshape how lacrimal devices are designed, sterilized, and distributed across ophthalmic care settings.
Laser-assisted dacryocystorhinostomy systems are absorbing capital investment from traditional mechanical trephination equipment as ambulatory surgical centers prioritize reduced operative time and minimized tissue trauma. Tertiary eye hospitals in the United States and Germany are retrofitting existing OR suites with diode laser platforms at replacement cycles compressed from seven to four years. This technology absorption is compressing demand for reusable steel trephines while elevating single-use silicone stent consumption.
Japan's PMDA has tightened biocompatibility documentation requirements for implantable ophthalmic devices under revised Ministerial Ordinance No. 169, mandating extended cytotoxicity studies that add 6-9 months to premarket timelines. Domestic manufacturers are responding by consolidating regulatory affairs functions and pre-submission consultations to preempt review queries. The policy shift most affects novel drug-eluting punctal plugs where silicone-polymer interfaces require additional characterization.
Physician buying committees in ASCs are unbundling device procurement from capital equipment leases, creating direct purchasing relationships with specialty distributors that bypass traditional hospital supply chain intermediaries. This disintermediation is most pronounced in Florida and Texas ophthalmology networks where private equity-backed practice consolidation concentrates purchasing power. The channel shift favors manufacturers with same-day fulfillment capabilities and consignment inventory programs over legacy distributors with 48-72 hour lead times.
Lacrimal Devices Market Segmentation
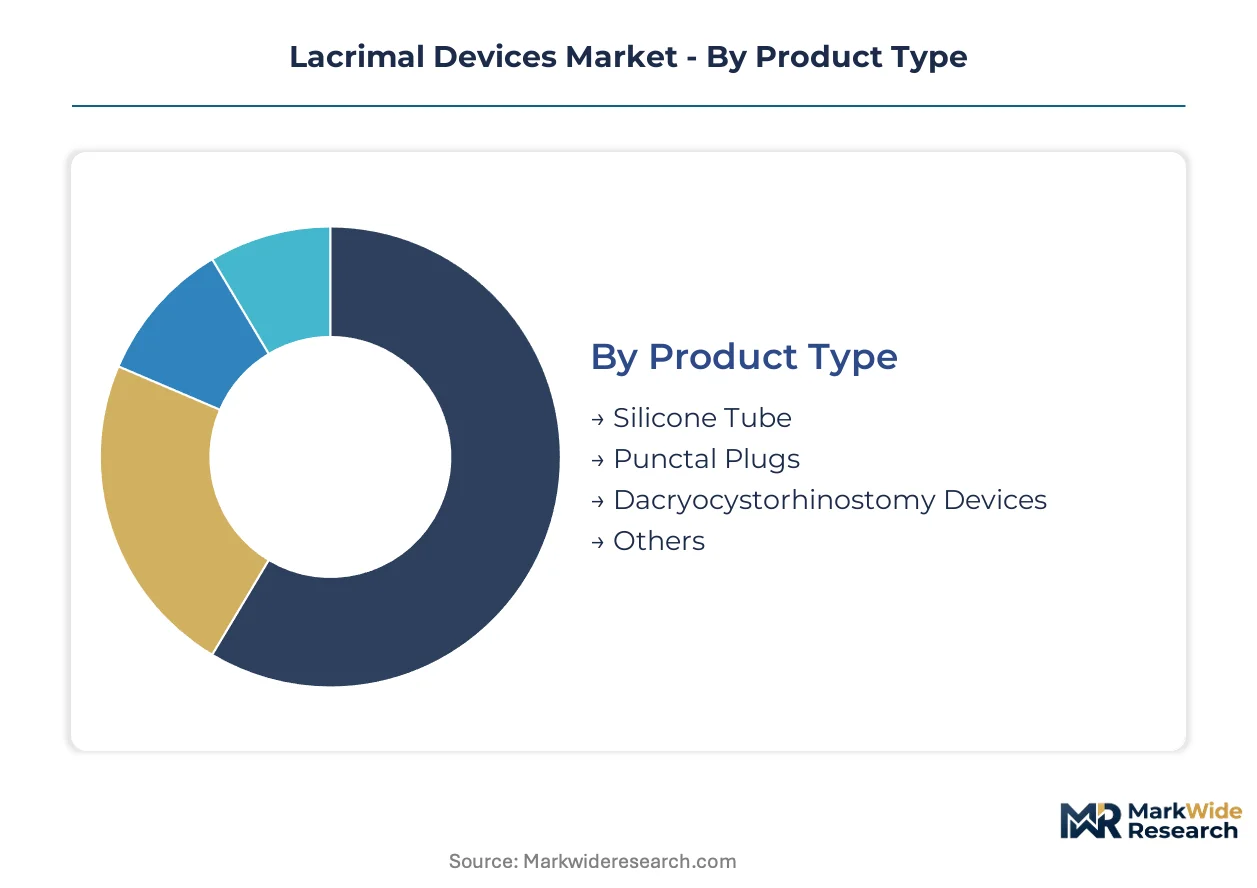
Lacrimal device purchasing decisions split across material specifications, procedural settings, and patient age profiles. Manufacturers configure product portfolios around these fracture lines to capture recurring replacement revenue and procedural volume concentration.
Product Type:
Replacement cycles vary sharply by implant durability and reversibility, with temporary stents demanding annual turnover while permanent punctal modifications lock in decade-long patient relationships.
- Silicone Tube:Medical-grade silicone constructs ranging 0.64-1.14 mm outer diameter accommodate neonatal through adult nasolacrimal anatomy. Pediatric congenital obstruction correction in United States tertiary centers drives recurring demand for these temporary stents requiring secondary removal procedures.
- Punctal Plugs:Tapered or cylindrical occluders manufactured from hydrophobic silicone or collagen-composite materials modulate tear drainage through mechanical canalicular blockage. Dry eye therapy protocols in Medicare-reimbursed office settings sustain mature revenue volumes despite reimbursement code fragmentation.
- Dacryocystorhinostomy Devices:Specialized trephines, stents, and laser-compatible instrumentation for surgical drainage reconstruction.
- Others:Lacrimal probes, cannulae, and accessory irrigation instruments for diagnostic and interventional procedures.
Punctal plugs sit at the top of the volume ranking, with silicone tube intubation climbing the fastest on pediatric procedure expansion.
Technology:
Capital equipment depreciation schedules and surgeon training curves determine technology penetration, with laser platforms requiring four-year replacement cycles against seven-year mechanical system longevity.
- Minimally Invasive:Transcanalicular approaches utilizing microscopic instrumentation and image-guided navigation reduce tissue disruption and recovery intervals. Ambulatory surgical centers in Florida and Texas ophthalmology networks prioritize these techniques for same-day discharge economics.
- Laser-assisted:Diode laser platforms enable precision ablation of bony and soft tissue structures with minimized suture burden. Tertiary eye hospitals in Germany and the United States are absorbing capital investment into these systems at compressed replacement cycles.
- Conventional:Mechanical trephination and external dacryocystorhinostomy approaches utilizing reusable steel instrumentation.
- Others:Balloon dacryoplasty and non-laser energy-based modalities for nasolacrimal recanalization.
Minimally invasive approaches command premium pricing tiers, while laser-assisted systems gain share fastest through operative time compression.
End User:
Procurement authority fragmentation separates hospital committee purchasing from direct ambulatory acquisition, reshaping distributor relationships and inventory models.
- Ambulatory Surgical Centers:Physician-owned and private equity-backed outpatient facilities performing same-day lacrimal interventions. United States reimbursement pathway consolidation favors these settings over inpatient admission, elevating device throughput through direct specialty distributor relationships.
- Eye Clinics:Office-based ophthalmology practices performing punctal plug insertion and diagnostic lacrimal irrigation. Epic and Cerner EHR integration friction complicates billing for device-specific procedure codes in these settings.
- Hospitals:Tertiary medical centers with inpatient surgical capacity and capital equipment leasing arrangements.
- Research Institutions:Academic medical centers conducting clinical validation studies for novel stent designs and biocompatibility assessment.
Ambulatory surgical centers are climbing the volume ranking fastest, with eye clinics retaining the largest installed base of punctal plug procedures.
Application:
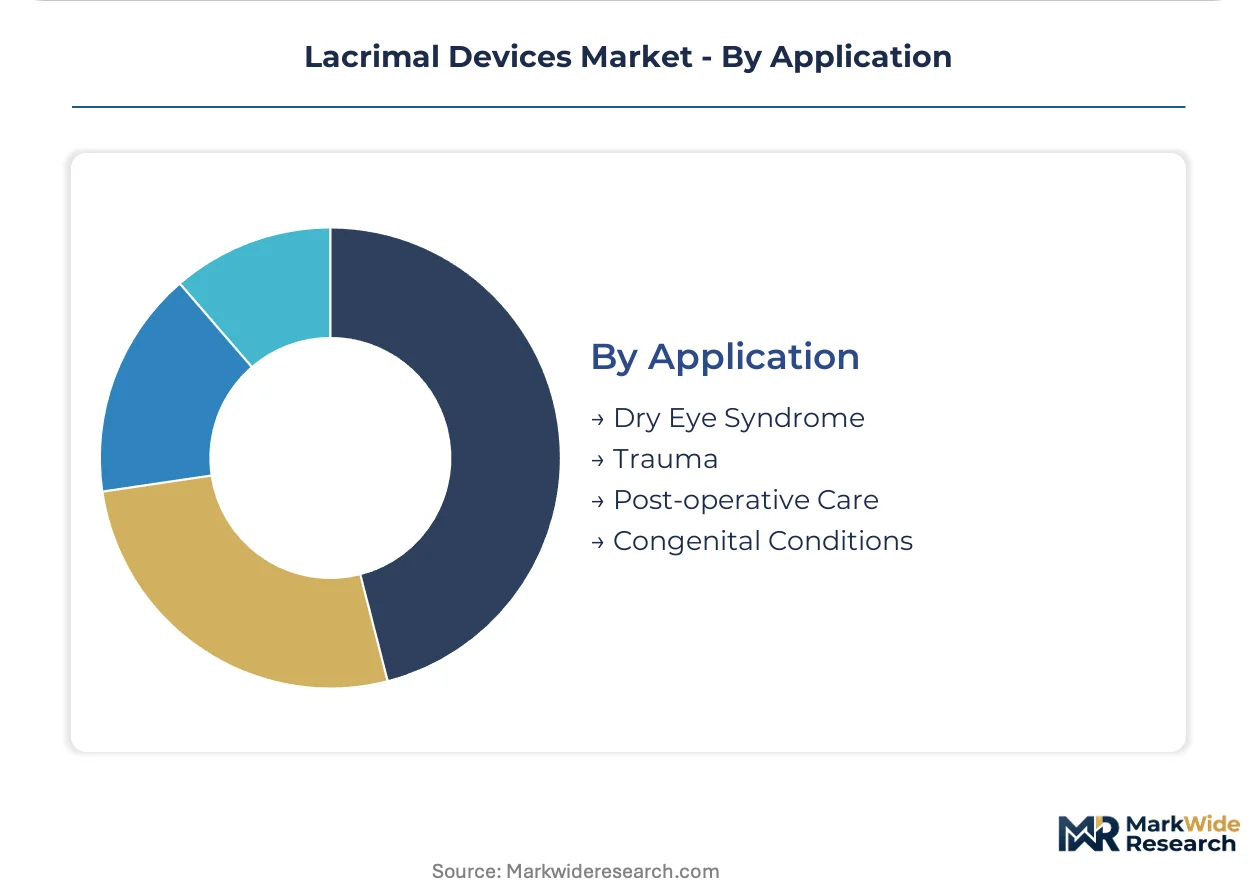
Patient demographics and etiology determine device selection, with congenital conditions requiring anatomically specialized pediatric systems and post-operative care driving recurring replacement schedules.
- Congenital Conditions:Neonatal nasolacrimal duct obstruction affecting approximately one-third of infants, typically resolving spontaneously or requiring silicone tube intubation. Rising birth rates in specialized United States maternal care clusters expand addressable volume for pediatric-specific device geometries.
- Dry Eye Syndrome:Chronic tear film dysfunction managed through punctal occlusion therapy. Aging demographics in the United States sustain recurring need for flow-modulating implants as cataract surgery volumes compound post-operative lacrimal management requirements.
- Post-operative Care:Lacrimal complications following orbital, nasal, or ophthalmic surgical interventions.
- Trauma:Canalicular laceration repair and acquired nasolacrimal obstruction from facial injury.
Dry eye syndrome sits at the top of the volume ranking, with congenital conditions climbing fastest on pediatric procedure infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's specialty chemical corridor anchors silicone feedstock supply for lacrimal device manufacturing, with three producers controlling implant-grade material flows that determine global input costs. FDA 510(k) pathways in the United States and Japan's PMDA biocompatibility mandates are tightening documentation requirements simultaneously. Surgical volume concentration in tertiary eye hospitals across these markets is compressing capital equipment replacement cycles.
United States
Aging demographics and high cataract surgery volumes sustain recurring demand for post-operative lacrimal management devices. FDA 510(k) clearance timelines for novel stent geometries have extended by 8-14 months due to heightened substantial equivalence scrutiny. Florida and Texas ophthalmology networks concentrate ambulatory surgical center expansion where private equity-backed practice consolidation drives direct specialty distributor relationships.
Germany
Specialty chemical producers in the industrial corridor control 70% of medical-grade silicone feedstock for global lacrimal device manufacturing. EU Medical Device Regulation biocompatibility testing under ISO 10993 shapes product development cycles for CE marking. Tertiary eye hospitals in Baden-Württemberg and Bavaria are retrofitting diode laser platforms at compressed four-year replacement cycles.
Japan
Revised Ministerial Ordinance No. 169 mandates extended cytotoxicity studies that add 6-9 months to PMDA premarket timelines for implantable ophthalmic devices. Domestic manufacturers are consolidating regulatory affairs functions to preempt review queries. Tokyo and Osaka metropolitan areas concentrate pediatric congenital nasolacrimal duct obstruction procedure infrastructure.
India
Government-funded vision centers in Tamil Nadu and Karnataka are generating recurring demand for post-operative lacrimal management devices as cataract surgical volumes compound. The Central Drugs Standard Control Organization maintains parallel sterility standards for multi-regional commercialization. Chennai and Bengaluru clusters anchor expanding maternal care infrastructure that drives pediatric silicone tube intubation demand.
Canada
Health Canada imposes sterility and shelf-life standards that manufacturers must navigate alongside FDA and PMDA requirements. Toronto and Vancouver metropolitan areas concentrate ambulatory surgical center adoption of minimally invasive lacrimal interventions. Provincial reimbursement pathway consolidation favors same-day procedures over inpatient admission.
Lacrimal Devices Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers extend silicone material science capabilities across punctal plug and intubation system categories. The vendor base fragments across specialized ophthalmic surgical portfolios and focused punctal occlusion engineering. Three strategic archetypes emerge: integrated surgical device conglomerates, single-product punctal plug specialists, and regional distribution-focused entities. M&A activity and direct-to-ambulatory distribution channel development represent the dominant competitive moves reshaping procurement relationships.
Within the specialized ophthalmic surgical tier, FCI Ophthalmics and JEDMED exemplify channel relationship sustainment across outpatient settings. Lacrimedics occupies a position representing focused product engineering for punctal occlusion and lacrimal intubation systems. Among diversified medical device manufacturers, BVI sits within the broader surgical portfolio archetype. These three entities collectively illustrate how market participants configure around material specification expertise, procedural setting concentration, and regulatory navigation capabilities rather than scale-driven cost positioning.
| Leading Market Players |
|---|
| Lacrimedics |
| Bess Medical Technology |
| FCI Ophthalmics |
| JEDMED |
| Braintree Scientific |
| Medennium |
| Rumex International |
| Walsh Medical Devices |
| BVI |
| Others |
Supply Flow & Price Mechanics
Microsurgical instrument specialists in the Black Forest region of Germany command wage premiums that cascade through three-tier pricing structures across premium, standard, and economy levels for lacrimal devices. Labor-cost differentials between German precision manufacturing clusters and Asian assembly operations widen spreads between FDA-validated silicone stents and non-CE marked alternatives.
Pricing Analysis
Medical-grade silicone feedstock pass-through from three German and Japanese chemical producers anchors per-unit pricing for intubation systems. Price differentiation separates FDA 510(k)-cleared devices from CE-marked equivalents, with certification tier and volume scale determining contract terms. Pricing pressure stems from reimbursement code fragmentation that compresses physician willingness-to-pay for punctal plugs. Ambulatory surgical centers exhibit highest price sensitivity due to direct procurement accountability, while tertiary hospitals absorb premium tiers through capital equipment bundling.
Supply Chain Analysis
Dual-sourcing requirements from major ophthalmic device manufacturers mandate qualified silicone suppliers in Germany, Japan, and the United States for implant-grade feedstock. Raw material dependencies center on medical-grade silicone polymers, precision extrusion tooling, and ethylene oxide sterilization services. Single-source vulnerability concentrates in the Black Forest-Tokyo chemical corridor where three producers control implant-grade silicone flows. Distribution runs through specialized ophthalmic supply cooperatives that bypass hospital procurement committees for ambulatory surgical center direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in Germany diverge from India's CDSCO pathway efficiencies, creating manufacturing relocation incentives for cost-sensitive product tiers.
For Market Incumbents: Anticipate bioresorbable polymer convergence threatening silicone-dominant stent portfolios by accelerating in-house polylactic acid coating capabilities. Defend channel position through backward integration into medical-grade silicone feedstock contracts with German chemical producers. Prioritize FDA pre-submission consultations for novel geometries to compress 510(k) review timelines.
For New Entrants and Emerging Players: Specialty distributors serving Florida and Texas ophthalmology networks offer the most accessible entry channel for punctal plug consignment programs. Target India's government-funded vision centers in Tamil Nadu and Karnataka where cataract surgical volume expansion outpaces established supplier coverage. Pursue direct-to-ambulatory fulfillment models that bypass legacy distributor markups.
For Investors and Strategic Acquirers: Private equity-backed ophthalmology practice consolidators are the most active acquirer in this space, driving vertical integration into device distribution. Five-to-ten year viability hinges on reimbursement pathway consolidation favoring outpatient settings. Acquisition target archetype: regional distributors with same-day fulfillment infrastructure and established ASC relationships. Monitor CPT code unification for office-based lacrimal procedures as the decisive inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for novel stent geometries ahead of EU MDR competitors. |
| CE Marking Pathway | ISO 10993 biocompatibility testing secures European ambulatory surgical center procurement. |
| Hospital System Partnership | Epic EHR integration reduces billing friction for device-specific procedure codes. |
| Software Companion Development | Image-guided navigation platforms differentiate minimally invasive intubation systems. |
| Reimbursement Strategy | CPT classification advocacy determines ambulatory expansion velocity in United States networks. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and Canada, with primary inputs from each market cluster. The study combines interviews with ophthalmic surgeons, ambulatory surgical center purchasing committees, biomedical engineers, and GPO contracts managers with secondary validation from FDA 510(k) filings, PMDA submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchor market sizing.
Granularity-level modeling disaggregates volume and value across product type, technology platform, end-user setting, application indication, and patient age profile throughout the forecast period. CAGRs derive from segmented growth rate application with cross-validation against macroeconomic healthcare expenditure trends. Industry-specific forecast inputs include cataract surgery volume projections, birth rate trajectories in maternal care clusters, and laser platform replacement cycle compression.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to reimbursement code consolidation timing and silicone feedstock allocation disruptions. Deviation in FDA substantial equivalence scrutiny intensity or EU MDR notified body capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Portable Medical Ventilators Market
Medical Devices
Middle East and Africa Aligner Sheet Market
Medical Devices
Global Pressure Relief Devices Market
Medical Devices
Hybrid Microcirculation Detector Market
Medical Devices
C-Arms Devices Market
Medical Devices
Cranial Clamps Market
Medical Devices
Toe Fixation System Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Bariatric Beds Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Global Bone Cement Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Asia-Pacific Nerve Repair and Regeneration Market
Medical Devices
South America C-Arms Market
Medical Devices
MRI Safe Biopsy Needle Market