
 Intraocular Lymphoma Treatment Market | 2026-2036
Intraocular Lymphoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Intraocular Lymphoma Treatment Market Foresight
Precision biologics manufacturing is rewriting how intraocular lymphoma therapies reach patients, shifting batch production toward patient-specific dosing platforms. Roche Holding AG leverages its ophthalmology infrastructure to sustain vitreoretinal delivery networks across North America and Europe. Genentech Inc. anchors its position through specialized intravitreal formulation capabilities that competitors struggle to replicate. Bristol-Myers Squibb differentiates via integrated immuno-oncology platforms that extend from systemic lymphoma into rare ocular indications.
Intraocular lymphoma treatment encompasses therapeutic interventions targeting malignant lymphoid cell proliferation within the eye's uveal tract, vitreous, or retina, typically requiring agents that cross blood-retinal barriers at concentrations between 0.1 and 4 mg per intravitreal dose. The primary purpose centers on preserving visual function while controlling systemic disease progression in this rare primary central nervous system lymphoma variant. Immunotherapy commands the fastest expansion within product type categories as checkpoint inhibitors demonstrate durable vitreous responses. Combination therapy approaches generate the deepest margin pools within treatment approach segments due to premium pricing for multi-agent protocols administered in hospital settings.
The FDA orphan drug program shapes development economics by granting seven-year market exclusivity and tax incentives for therapies targeting intraocular lymphoma's small patient populations. EMA's Committee for Orphan Medicinal Products creates parallel access pathways in Europe, while WHO classification updates for primary vitreoretinal lymphoma standardize diagnostic criteria that determine reimbursement eligibility. Stakeholders must monitor how evolving central nervous system lymphoma treatment guidelines redistribute patients between systemic and local ocular therapy protocols.
Market Dynamics
Precision biologics manufacturing is compressing production cycles for intraocular lymphoma therapies, shifting from batch processes toward patient-specific dosing platforms that demand specialized cold-chain infrastructure and sterility assurance.
Growth Catalysts
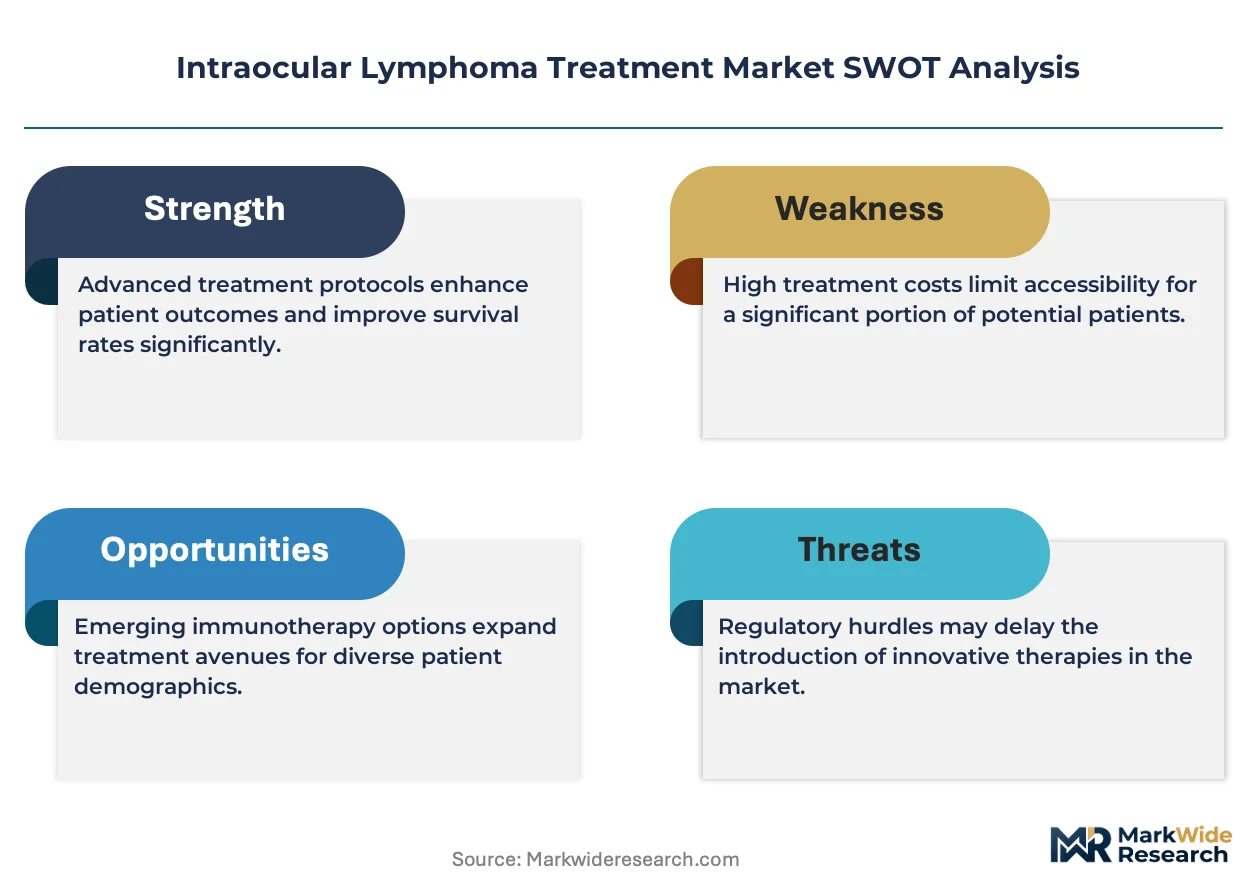
- FDA Orphan Drug Exclusivity:Seven-year market exclusivity and tax incentives accelerate therapeutic development timelines for small patient populations, attracting biopharma investment into rare ocular indications.
- Intravitreal Delivery Networks:Specialized ocular oncology centers in the United States concentrate patient referrals and create demand density for advanced formulation capabilities.
- Immunotherapy Platform Expansion:Checkpoint inhibitor classes demonstrate durable vitreous responses, pulling systemic lymphoma protocols into localized ocular applications.
Market Restraints
- Biologic Cold-Chain Fragility:Temperature excursions during intravitreal dose transport destroy therapeutic potency, constraining distribution radius from compounding facilities.
- Blood-Retinal Barrier Pharmacokinetics:Agent penetration at 0.1-4 mg dose windows limits formulation options and extends development timelines.
- Specialized Infusion Center Concentration:Vitreoretinal surgical capacity clusters in tertiary academic medical centers, creating geographic access inequities.
Strategic Opportunities
- EMA Parallel Access Pathways:The Committee for Orphan Medicinal Products creates expedited European market entry for therapies holding FDA orphan designation.
- Combination Protocol Premium Positioning:Multi-agent hospital-administered regimens command pricing differentiation versus monotherapy alternatives.
- WHO Diagnostic Standardization:Updated primary vitreoretinal lymphoma classification criteria harmonize reimbursement eligibility determination across national health systems.
Industry Challenges
- Ocular Oncology Specialist Scarcity:Fellowship-trained vitreoretinal surgeons with lymphoma expertise represent a bottleneck capacity constraint.
- Intravitreal Sterility Validation:Compounding pharmacy compliance with ophthalmic preparation standards demands capital-intensive cleanroom infrastructure.
- Systemic-Ocular Protocol Integration:CNS lymphoma treatment guideline evolution creates uncertainty in patient routing between local and systemic therapy pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intraocular Lymphoma Treatment Market |
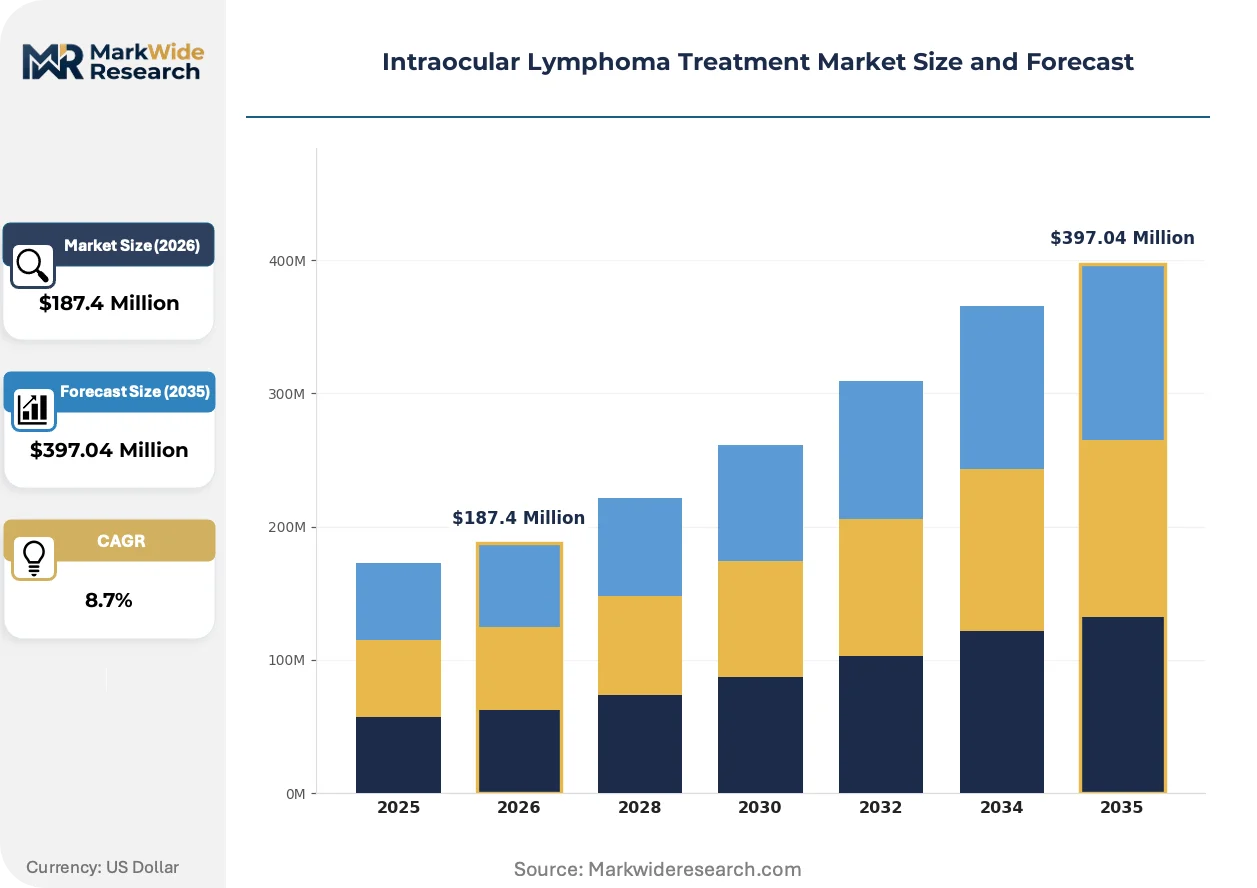
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Immunotherapy, Surgical Intervention Treatment Approach: Monotherapy, Combination Therapy, Palliative Care, Personalized Medicine End User: Hospitals, Oncology Clinics, Research Institutions, Home Healthcare Administration Route: Intravitreal Injection, Systemic Delivery, Topical Application, Oral Administration |
| Companies Covered | Roche Holding AG, Novartis AG, Pfizer Inc., Bristol-Myers Squibb, Celgene Corporation, Genentech Inc., Seagen Inc., AstraZeneca, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intraocular Lymphoma Treatment Market Shifts & Advancements
Patient-specific manufacturing platforms are disrupting conventional batch production economics, while regulatory harmonization efforts and shifting referral patterns reshape competitive positioning across the intraocular lymphoma treatment landscape.
Gene-edited autologous cell therapies are rendering obsolete standardized biologic dosing for relapsed intraocular lymphoma cases. Academic medical centers in Germany and the United States pilot chimeric antigen receptor protocols adapted for ocular sanctuary sites. These programs compress the viable development window for conventional intravitreal chemotherapy formulations.
REACH substance restriction updates tighten excipient purity requirements for European intravitreal formulations. EMA's revised guideline on quality aspects of ophthalmic products forces reformulation of legacy preservative systems. Manufacturers serving EU markets accelerate migration toward single-use sterile filling lines to preempt compliance gaps.
Hospital-based ocular oncology service lines unbundle diagnostic workup from therapeutic administration, creating distinct procurement categories. United States academic centers now separately contract vitreous biopsy pathology from intravitreal injection services. This bifurcation concentrates purchasing leverage among integrated delivery networks possessing in-house pathology capabilities.
Intraocular Lymphoma Treatment Market Segmentation
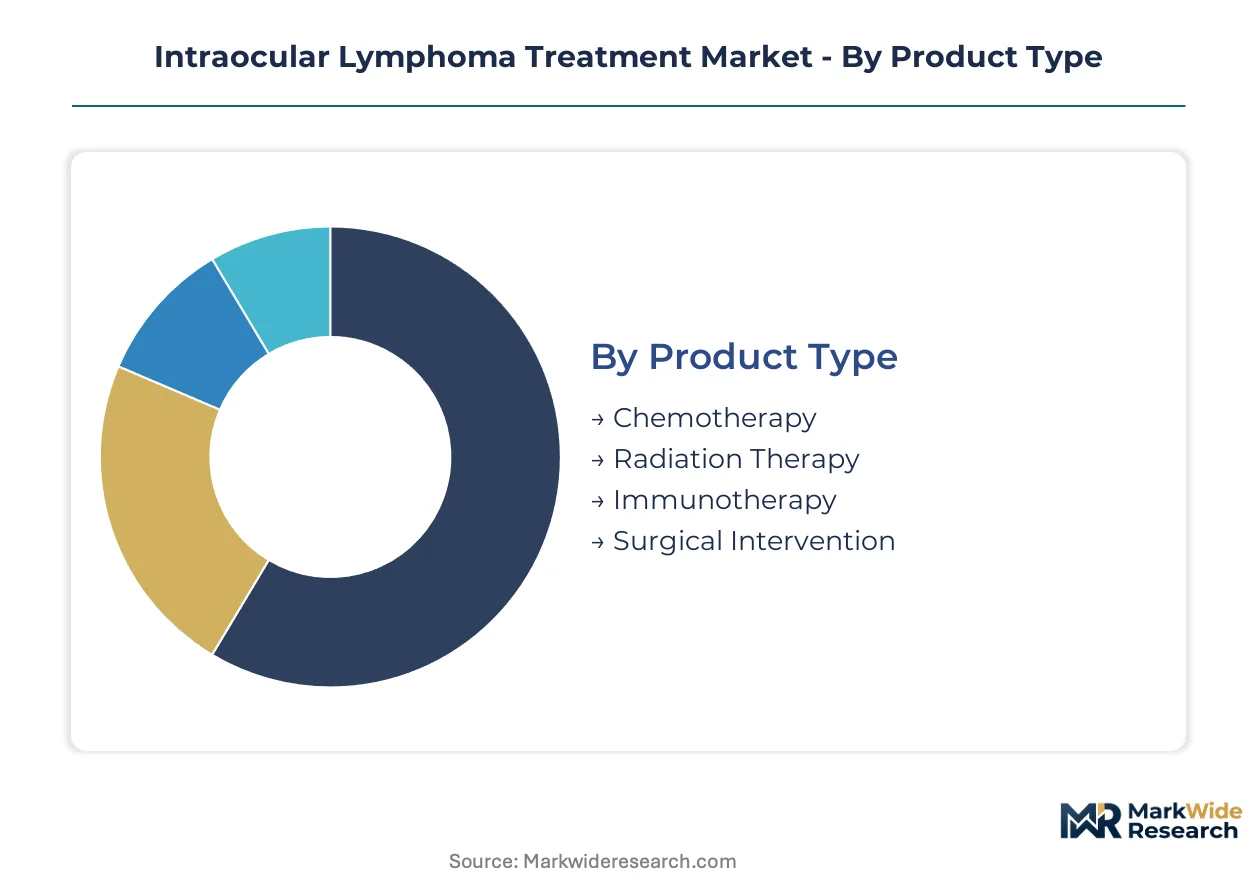
Treatment modality selection in intraocular lymphoma hinges on blood-retinal barrier penetration requirements and whether disease presents as isolated ocular involvement or CNS extension. Segmentation reveals how formulation capabilities and delivery infrastructure shape competitive boundaries across therapeutic categories.
Product Type:
Use-case spectrum spans localized cytotoxic control through systemic immune modulation, with each modality demanding distinct manufacturing and clinical infrastructure.
- Immunotherapy:Checkpoint inhibitors and monoclonal antibodies engineered for vitreous penetration occupy the steepest expansion trajectory. Academic medical centers in the United States concentrate demand as protocols migrate from systemic lymphoma into sanctuary site applications.
- Chemotherapy:Intravitreal methotrexate and rituximab formulations retain established volume leadership despite manufacturing complexity. Cold-chain fragility constrains distribution radius from compounding facilities, preserving regional supply concentration.
- Radiation Therapy:External beam and plaque brachytherapy protocols serve patients with contraindications to intravitreal injection.
- Surgical Intervention:Vitrectomy with therapeutic adjunct addresses diagnostic confirmation and debulking requirements.
Established volume favors chemotherapy; emerging adoption favors immunotherapy.
Treatment Approach:
Cost tier differentiation separates hospital-administered multi-agent protocols from outpatient monotherapy alternatives.
- Combination Therapy:Multi-agent regimens administered in inpatient settings command premium positioning through bundled reimbursement structures. United States integrated delivery networks leverage pathology capabilities to capture margin across diagnostic and therapeutic episodes.
- Personalized Medicine:Patient-specific dosing platforms and companion diagnostic integration represent the fastest-climbing category. German and United States academic centers pilot chimeric antigen receptor protocols adapted for ocular sanctuary sites.
- Monotherapy:Single-agent protocols dominate initial presentation management in resource-constrained settings.
- Palliative Care:Symptom-focused protocols address end-stage visual preservation priorities.
Margin concentration pools in combination therapy; capability investment flows toward personalized medicine.
End User:
Customer type determines procurement leverage and service line bundling economics.
- Hospitals:Tertiary academic centers anchor demand through fellowship-trained vitreoretinal surgical capacity. United States hospital systems unbundle diagnostic workup from therapeutic administration, creating distinct contracting categories.
- Oncology Clinics:Community and hospital-affiliated clinics expand service lines as patient referrals rise. These settings favor monotherapy protocols that avoid surgical infrastructure requirements.
- Research Institutions:Early-phase trial sites concentrate in Germany and the United States for autologous cell therapy development.
- Home Healthcare:Limited applicability given intravitreal administration requirements and sterility validation needs.
Procurement scale favors hospitals; referral expansion favors oncology clinics.
Administration Route:
Supply concentration follows sterile compounding facility geography and surgical capacity distribution.
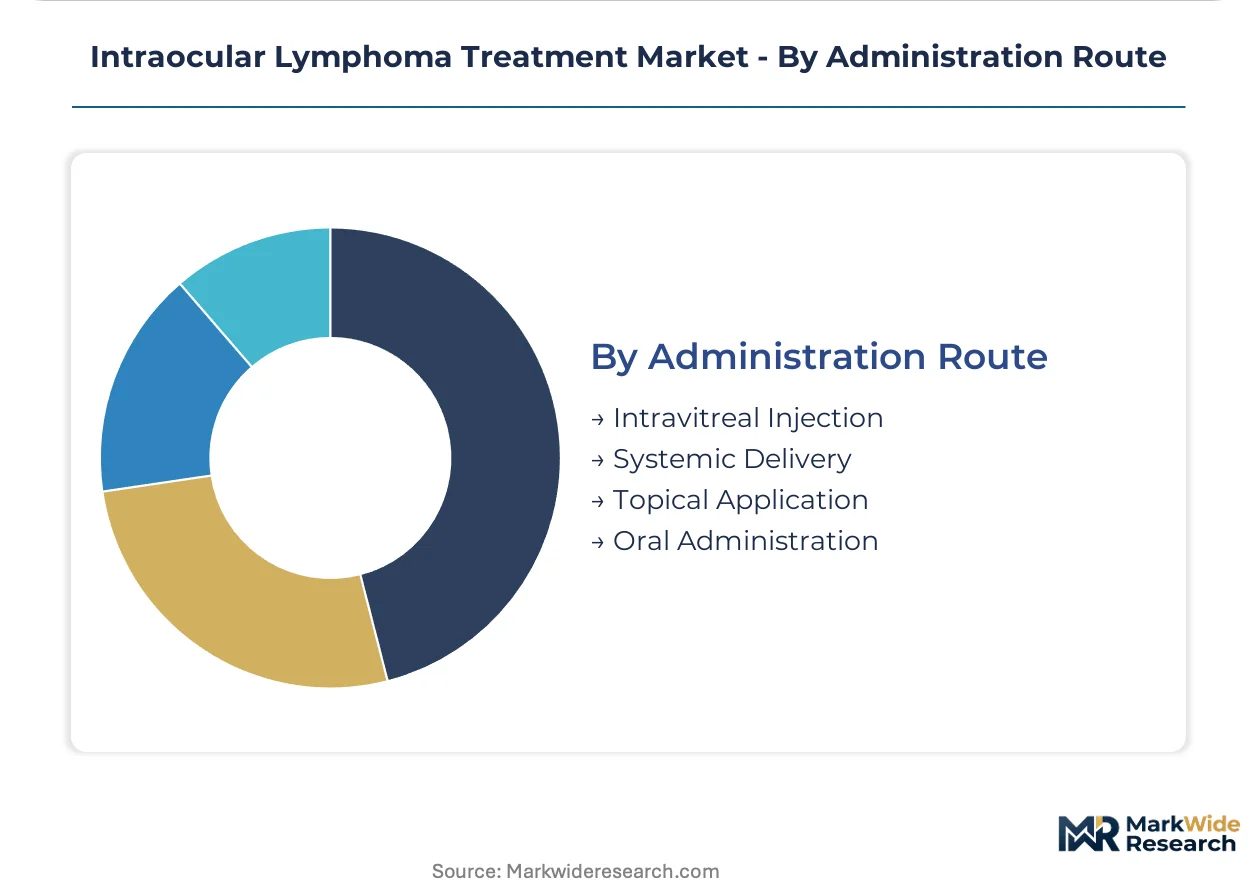
- Intravitreal Injection:Direct vitreous delivery at 0.1-4 mg dose windows dominates therapeutic response rates. Specialized ocular oncology centers in the United States create demand density for advanced formulation capabilities.
- Systemic Delivery:Intravenous protocols address concurrent CNS involvement but achieve suboptimal ocular penetration. Blood-retinal barrier pharmacokinetics limit efficacy for isolated intraocular presentations.
- Topical Application:Limited penetration restricts utility to anterior segment adjuvant therapy.
- Oral Administration:Systemic agents with CNS penetration serve patients refusing invasive procedures.
Efficacy concentration favors intravitreal injection; access expansion favors systemic delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounding pharmacies export intravitreal formulations to tertiary centers across Austria and Switzerland, establishing a cross-border supply corridor that shapes European treatment access patterns.
United States
FDA orphan drug exclusivity and seven-year market protection accelerate biopharma investment into rare ocular indications. The National Institutes of Health funds vitreoretinal lymphoma consortia through specialized research grants. Boston and Philadelphia anchor demand density through fellowship-trained surgical capacity at academic medical centers.
Germany
EMA Committee for Orphan Medicinal Products creates expedited European pathways for therapies with FDA designation. REACH substance restrictions tighten excipient purity requirements for intravitreal formulations. Heidelberg and Tübingen concentrate early-phase CAR-T development programs adapted for ocular sanctuary sites.
Japan
PMDA's Sakigake designation system accelerates review timelines for innovative ophthalmic therapies. METI funding supports precision biologics manufacturing infrastructure for patient-specific dosing platforms. Tokyo and Osaka medical districts unbundle diagnostic pathology from intravitreal injection services.
United Kingdom
NICE technology appraisals determine reimbursement eligibility for combination therapy protocols within the National Health Service. MHRA post-Brexit regulatory autonomy enables accelerated access schemes for rare disease treatments. London's Moorfields Eye Hospital anchors specialized ocular oncology referral networks.
Switzerland
Swissmedic's streamlined orphan drug procedures attract biopharma headquarters for European market entry strategies. Federal funding for personalized medicine initiatives supports autologous cell therapy manufacturing. Basel and Zurich concentrate pharmaceutical R&D infrastructure with integrated ophthalmology partnerships.
Intraocular Lymphoma Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around integrated immuno-oncology platforms and specialized intravitreal formulation capabilities. Large-cap biopharmaceuticals with systemic lymphoma portfolios extend into rare ocular indications through indication expansion strategies. Three archetypes dominate: diversified oncology majors with ophthalmology infrastructure, precision biologics specialists with patient-specific manufacturing, and regional compounding pharmacies with sterile filling expertise. Competitive moves center on portfolio diversification into ocular indications and strategic partnerships with academic medical centers for clinical trial access.
Within the diversified oncology tier, Roche Holding AG and Bristol-Myers Squibb occupy positions anchored by established immuno-oncology platforms. Genentech Inc. exemplifies the precision formulation archetype through its specialized intravitreal capabilities. These three companies represent the dominant competitive anchors as the market shifts from batch production toward patient-specific dosing platforms and combination therapy protocols.
| Leading Market Players |
|---|
| Roche Holding AG |
| Novartis AG |
| Pfizer Inc. |
| Bristol-Myers Squibb |
| Celgene Corporation |
| Genentech Inc. |
| Seagen Inc. |
| AstraZeneca |
| Merck & Co. |
| Others |
Supply & Pricing Matrix
Cold-chain fragility during intravitreal dose transport compresses both pricing tier spreads and supply chain radius from compounding facilities. FDA sterility requirements and temperature excursion risks force manufacturers to cluster production near demand-dense academic medical centers, creating geographic price differentiation that favors integrated delivery networks with captive pathology capabilities.
Pricing Analysis
Next-generation patient-specific CAR-T protocols command substantial premiums over established intravitreal methotrexate formulations and legacy rituximab batches. Three-tier pricing structure across premium immunotherapy, standard chemotherapy, and economy radiation protocols reflects formulation complexity and administration setting. Price differentiation stems from hospital-based bundled reimbursement for multi-agent regimens versus outpatient monotherapy alternatives. Cost compression in the chemotherapy tier is intensifying because REACH substance restrictions force excipient reformulation. Community oncology clinics exhibit highest price sensitivity due to limited pathology infrastructure and preference for monotherapy protocols that avoid surgical facility fees.
Supply Chain Analysis
Upstream biologic active pharmaceutical ingredients concentrate in Switzerland, Germany, and the United States, where precision manufacturing infrastructure supports patient-specific dosing platforms. Sterile filling operations draw from specialized cleanroom equipment, single-use consumables, and validated cold-chain packaging systems. Single-source vulnerability pervades the intravitreal formulation segment, as few compounding pharmacies meet FDA ophthalmic preparation standards. Distribution runs through hospital-based ocular oncology service lines that unbundle diagnostic biopsy from therapeutic injection, creating distinct procurement categories with concentrated purchasing leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained vitreoretinal surgical capacity represents the binding constraint reshaping competitive dynamics, with only a handful of academic medical centers possessing the integrated pathology and sterile compounding infrastructure required for advanced protocol administration.
For Market Incumbents: Entrench position through backward integration into sterile compounding capabilities and exclusive partnerships with pathology-equipped integrated delivery networks. Roche and Bristol-Myers Squibb should lock in multi-year contracts with Boston and Philadelphia academic centers before CAR-T protocols displace conventional intravitreal chemotherapy. Capacity addition in Germany's Heidelberg-Tübingen corridor preempts EMA parallel access pathway competitors. For New Entrants and Emerging Players: Build out specialized intravitreal formulation expertise targeting community oncology clinics seeking to expand service lines without surgical infrastructure investment. The most penetrable segment lies in monotherapy protocols for initial presentation management, where demand concentrates among United States hospital-affiliated clinics facing rising patient referrals. A go-to-market angle emphasizing companion diagnostic integration with outpatient administration captures margin without competing for scarce vitreoretinal surgical slots. For Investors and Strategic Acquirers: FDA orphan drug exclusivity expiration timelines reshape the acquisition landscape for precision biologics specialists with patient-specific manufacturing platforms. Long-term viability hinges on capabilities spanning both localized ocular and systemic CNS lymphoma protocols, as treatment guideline evolution redirects patient routing. Target acquisition archetype: mid-cap immuno-oncology firms with existing intravitreal formulation infrastructure and academic medical center trial relationships. The signal to watch is WHO classification updates for primary vitreoretinal lymphoma, which standardize reimbursement eligibility and determine addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA seven-year exclusivity accelerates investment timelines for rare ocular indications. |
| Academic Medical Center Partnership | Boston and Philadelphia centers anchor demand density for advanced formulation capabilities. |
| Patient-Specific Manufacturing Scale-Up | Precision biologics platforms displace batch production economics for relapsed cases. |
| EMA Parallel Access Filing | Committee for Orphan Medicinal Products creates expedited European market entry. |
| Companion Diagnostic Integration | WHO classification standardization harmonizes reimbursement eligibility determination. |
Research Methodology
Initial hypotheses were tested against primary input from vitreoretinal surgeons, ocular oncology fellowship directors, hospital procurement managers, and compounding pharmacy compliance officers and refined through secondary validation. FDA orphan drug filings, EMA Committee for Orphan Medicinal Products decisions, ClinicalTrials.gov protocol registrations, and hospital GPO contract databases supplied quantitative anchors. Bottom-up patient flow modeling from academic medical centers and top-down biopharma pipeline valuation were triangulated to constrain estimate ranges.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning treatment modality, administration route, end-user facility type, and regional regulatory cluster. CAGRs were derived from patient population epidemiology, protocol adoption curves, and pricing evolution assumptions. Forecast inputs incorporated blood-retinal barrier pharmacokinetics constraints and vitreoretinal surgical capacity expansion timelines.
Stress conditions across FDA sterility enforcement intensity, CAR-T protocol clinical trial outcomes, and CNS lymphoma guideline revision were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding orphan drug exclusivity retention and REACH substance restriction implementation pace. Cross-checking against Medicare reimbursement rate determinations and integrated delivery network capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Corneal Edema Treatment Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Global Ophthalmic Equipment Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Tonometry Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market