
 Corneal Pachymetry Market | 2026-2036
Corneal Pachymetry Market Size, Share, and Industry Trends Forecast 2026-2036
Corneal Pachymetry Market Analysis
Modular platform bundling is repositioning how ophthalmology clinics evaluate capital equipment purchases. Carl Zeiss Meditec leverages its integrated diagnostic suite to anchor premium positioning across European and North American accounts. Topcon Corporation sustains competitive pressure through specialized optical coherence tomography modules that integrate with existing practice management systems. NIDEK Co. Ltd. dominates the Asia-Pacific installed base with compact ultrasound pachymeters designed for high-throughput screening environments.
Corneal pachymetry measures central and peripheral corneal thickness using ultrasound, optical, or tomographic methods, typically achieving precision within five microns for clinical decision-making in refractive and glaucoma care. The primary commercial purpose centers on preoperative screening for laser vision correction and longitudinal monitoring of corneal ectasia. Optical pachymeter and anterior segment OCT categories command the strongest margin pools due to software subscription attach rates and upgrade cycles. Hospitals and ambulatory surgical centers represent the fastest-growing end user channel as health systems consolidate ophthalmology service lines and standardize on multi-function diagnostic platforms.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development timelines and market access costs for manufacturers seeking dual-territory placement. The CE marking process under MDR intensifies clinical evidence demands for optical pachymetry systems relative to legacy ultrasound devices. Stakeholders must monitor evolving reimbursement codes for corneal imaging in glaucoma management, as payer coverage decisions will determine upgrade velocity across ophthalmology clinic networks.
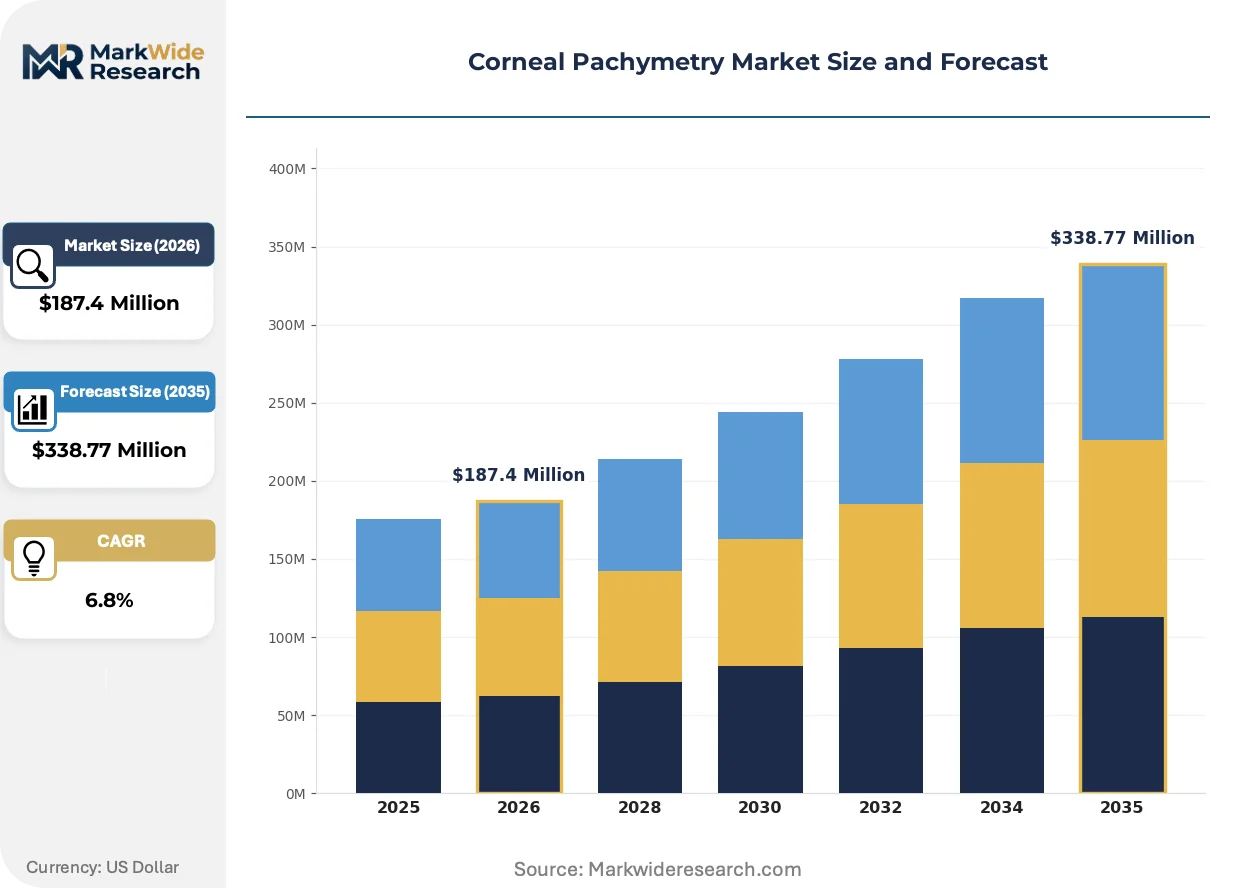
Market Dynamics
Modular diagnostic platforms are compressing capital equipment replacement cycles as ophthalmology clinics consolidate vendors and standardize on integrated imaging suites. The shift from standalone ultrasound pachymeters to software-subscription-driven anterior segment OCT systems is redistributing margin pools toward recurring revenue models.
Growth Catalysts
- EU MDR compliance deadlines:The Medical Device Regulation's enhanced clinical evidence requirements for optical pachymetry systems is accelerating hospital procurement of validated multi-function platforms ahead of legacy device phase-outs.
- Refractive surgery volume concentration:High-throughput LASIK and SMILE centers in the United States, Germany, and Japan are driving replacement demand for precision corneal thickness measurement tools.
- Glaucoma screening protocol expansion:Payer-mandated corneal imaging for IOP correction algorithms is embedding pachymetry into routine optometric workflows across integrated health networks.
Market Restraints
- Optical component supply concentration:Precision interferometry subassemblies source predominantly from German and Japanese optical specialists, creating vulnerability to regional logistics disruptions.
- CE marking cost inflation:MDR clinical evaluation requirements for Class IIa optical devices have doubled notified body review timelines relative to legacy Medical Device Directive pathways.
- Ultrasound probe substitution:Compact handheld ultrasound pachymeters retain cost advantages in mobile screening programs, limiting optical system penetration in price-sensitive deployment settings.
Strategic Opportunities
- Tele-ophthalmology integration:Cloud-connected anterior segment imaging platforms enable remote corneal ectasia monitoring, opening subscription revenue streams from rural and underserved catchment areas.
- India diagnostic infrastructure buildout:The country's PLI scheme for medical device manufacturing is attracting optical assembly investments to serve South Asian refractive surgery expansion.
- AI-assisted tomography analysis:Machine learning algorithms for automated corneal thickness mapping and ectasia risk scoring are creating differentiated software attach rates for premium OCT configurations.
Industry Challenges
- Cross-trained technician scarcity:Anterior segment OCT operation requires simultaneous competency in optical alignment, patient positioning, and software navigation, stretching staffing at high-volume clinics.
- Legacy device interoperability:Proprietary data formats from installed ultrasound pachymeter bases complicate longitudinal patient record migration to unified electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corneal Pachymetry Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Pachymeter, Optical Pachymeter, Scheimpflug Imaging, Anterior Segment OCT End User: Ophthalmology Clinics, Hospitals, Ambulatory Surgical Centers, Research Institutions Technology: Standard Pachymetry, Swept-Source Technology, Time-Domain OCT, Phase-Shift Interferometry Application: Glaucoma Diagnosis, Refractive Surgery, Keratoconus Assessment, Corneal Transplantation |
| Companies Covered | Sonomed Escalon, Topcon Corporation, Carl Zeiss Meditec, TOMEY Corporation, Haag-Streit Group, Reichert Inc., DGH Technology, Inc, Lumibird Group, NIDEK Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corneal Pachymetry Market Emerging Trajectories
Spectral-domain OCT engines are absorbing corneal topography and biometry functions into single-capture workflows, collapsing the historical separation between structural and refractive diagnostic categories. This convergence is redrawing competitive boundaries between specialized pachymetry vendors and full-suite ophthalmic platform suppliers.
swept-source OCT technology is absorbing anterior segment imaging duties from standalone Scheimpflug cameras and rotating Scheimpflug-Placido topographers. Academic medical centers in the United States and university hospitals in Germany are deploying these systems for combined corneal thickness, epithelial mapping, and lenticule detection. The structural consequence is margin compression for single-function topographers as multi-modal platforms capture premium positioning.
MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data collection from optical pachymetry systems. Manufacturers must now maintain active implant registries or equivalent longitudinal tracking for devices with software-controlled diagnostic algorithms. High-volume refractive surgery chains in Spain and Italy are responding by centralizing procurement with vendors offering compliant data infrastructure.
Health system consolidation is compressing vendor diversity as integrated delivery networks impose standardized diagnostic protocols across acquired ophthalmology practices. Single-specialty clinics in Texas and Florida are losing procurement autonomy as parent organizations mandate multi-function platform purchases. This behavioral shift is most visible in United States ambulatory surgical center roll-ups, where capital committees now prioritize interoperability over device-specific performance metrics.
Corneal Pachymetry Market Segmentation
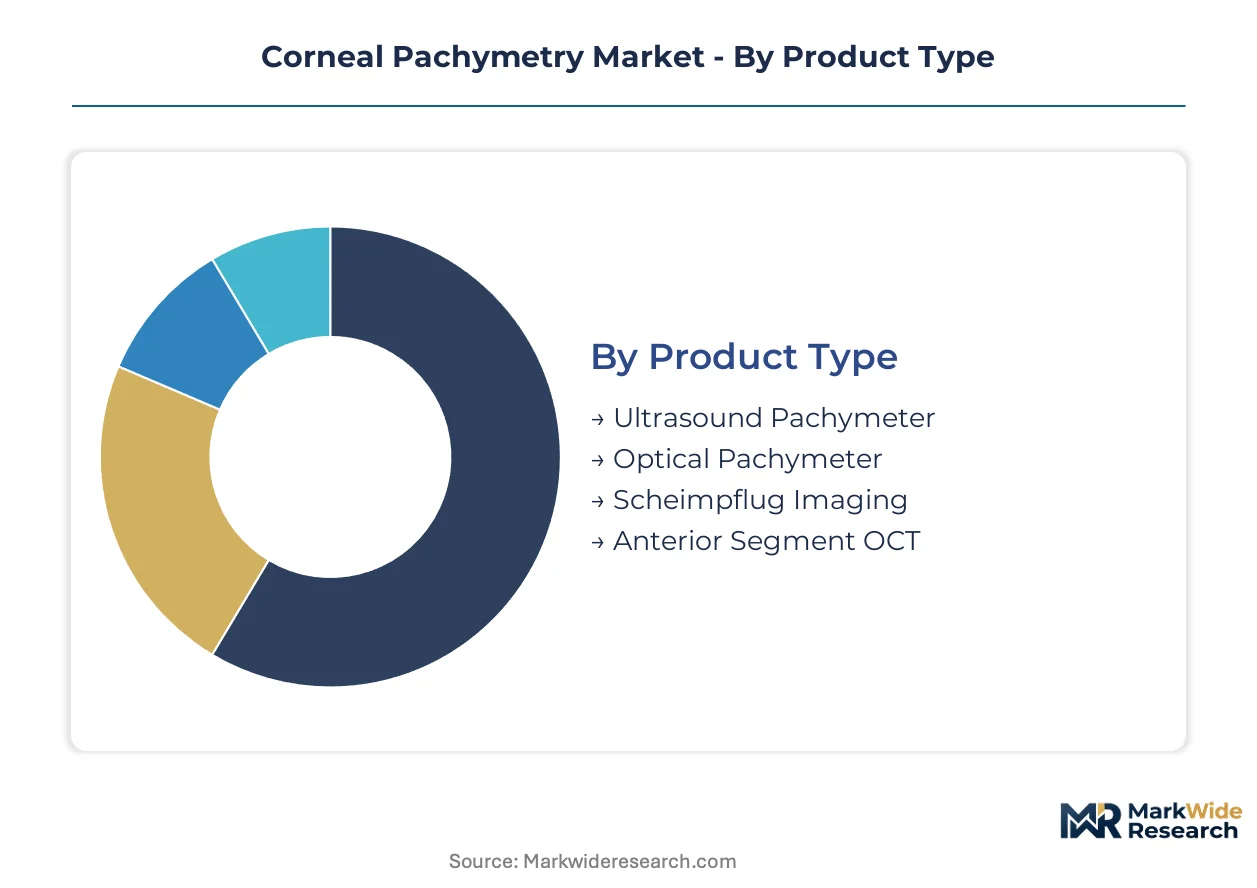
Corneal pachymetry equipment purchasing decisions split between high-throughput volume buyers and premium precision seekers. Technology convergence across optical and tomographic methods is collapsing traditional category boundaries and reshaping vendor positioning strategies.
Product Type:
Ultrasound systems dominate unit shipments while optical platforms command pricing premiums through software attach rates.
- Anterior Segment OCT:Spectral-domain engines capture corneal thickness, epithelial mapping, and biometry in single-capture workflows. Demand concentrates in United States ambulatory surgical centers consolidating diagnostic suites ahead of health system roll-ups.
- Optical Pachymeter:Non-contact interferometry achieves sub-micron repeatability for preoperative LASIK screening. Germany's high-volume refractive surgery chains drive replacement cycles as MDR compliance deadlines accelerate legacy device phase-outs.
- Scheimpflug Imaging:Rotating camera systems deliver corneal topography alongside thickness measurement. Japan's university hospitals deploy these for ectasia progression monitoring.
- Ultrasound Pachymeter:Compact handheld units retain cost advantages in mobile screening programs across India and Southeast Asia.
Today's leader: Anterior Segment OCT. Tomorrow's challenger: Optical Pachymeter.
End User:
Procurement autonomy is shifting from individual practitioners toward centralized capital committees.
- Hospitals:Integrated health networks standardize on multi-function platforms to serve consolidated ophthalmology service lines. United States health system roll-ups in Texas and Florida mandate interoperable diagnostic protocols across acquired practices.
- Ambulatory Surgical Centers:High-throughput LASIK and SMILE centers prioritize precision throughput over capital cost. Germany's refractive surgery chains drive premium platform adoption.
- Ophthalmology Clinics:Independent practices face vendor consolidation pressure as parent organizations impose procurement standards.
- Research Institutions:Academic medical centers deploy swept-source systems for longitudinal ectasia studies.
ASCs are climbing the fastest; hospital procurement committees are gaining veto power over clinic-level preferences.
Technology:
Engine architecture determines whether vendors capture hardware margins or recurring software revenue.
- Swept-Source Technology:Longer wavelength lasers penetrate through corneal haze and dense opacities. United States academic centers deploy these for combined anterior segment and biometry applications.
- Standard Pachymetry:Conventional ultrasound and optical methods serve price-sensitive screening environments. India's diagnostic infrastructure buildout under PLI scheme attracts compact ultrasound assembly investments.
- Time-Domain OCT:Earlier generation platforms remain in installed bases requiring MDR-mandated post-market surveillance.
- Phase-Shift Interferometry:High-precision optical benches serve calibration-dependent research protocols.
Swept-source architectures are expanding most quickly; standard pachymetry retains emerging-market relevance.
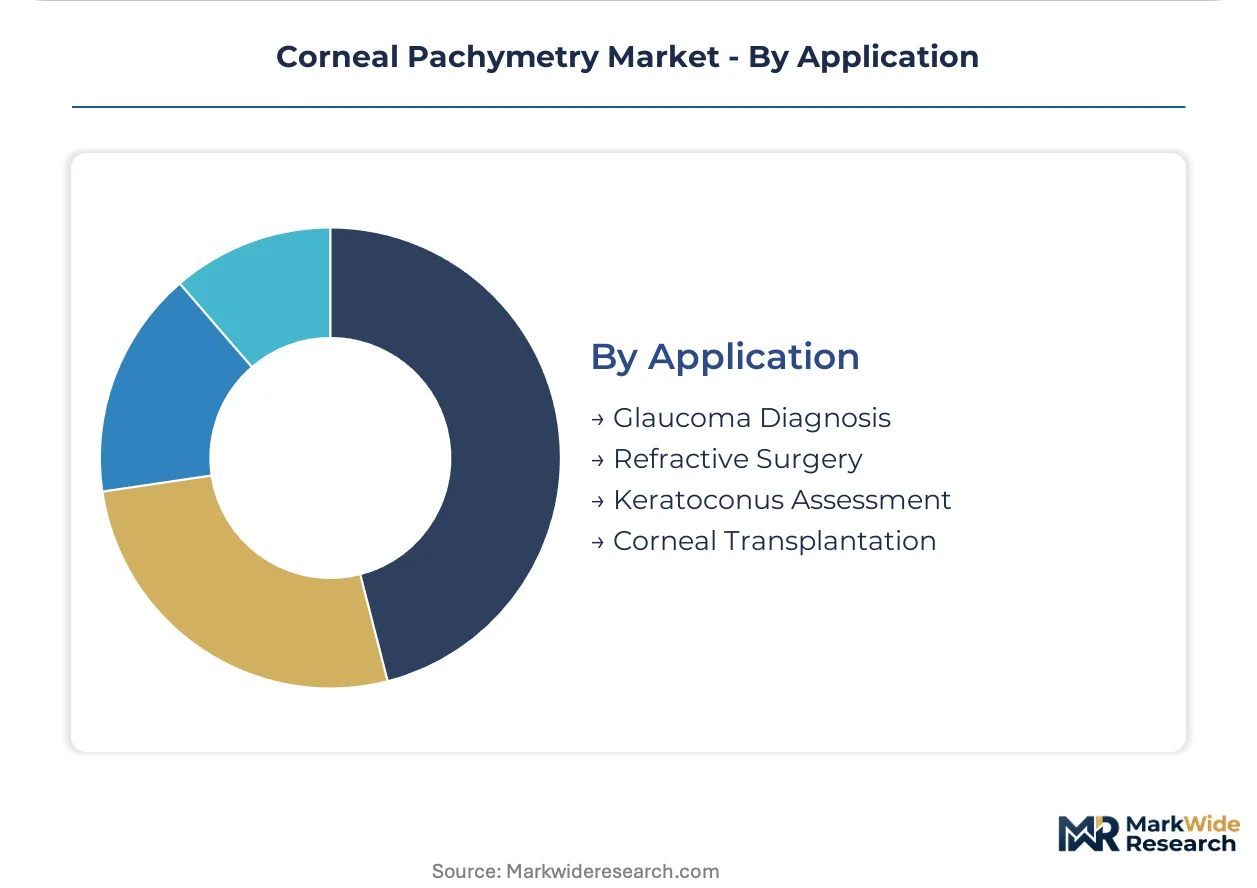
Application:
Reimbursement code evolution is embedding pachymetry into routine workflows beyond traditional refractive surgery.
- Refractive Surgery:Preoperative screening for LASIK, PRK, and SMILE procedures demands precision within five microns. Japan's high-volume correction centers drive replacement demand for validated measurement tools.
- Glaucoma Diagnosis:Payer-mandated corneal imaging for IOP correction algorithms is expanding optometric adoption. United States integrated networks embed pachymetry into routine screening protocols.
- Keratoconus Assessment:Longitudinal ectasia monitoring requires tomographic progression tracking. Germany's university hospitals lead adoption of AI-assisted risk scoring.
- Corneal Transplantation:Preoperative donor tissue evaluation and postoperative graft monitoring utilize thickness mapping.
Refractive surgery anchors current revenue; glaucoma applications are gaining share fastest through payer mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corneal pachymetry technology originated in German optical engineering laboratories during the 1980s, with precision interferometry methods first commercialized by Heidelberg instrument makers before spreading to Japanese ultrasound specialists and American refractive surgery chains.
United States
Ambulatory surgical center roll-ups in Texas and Florida are consolidating ophthalmology procurement under centralized capital committees. FDA 510(k) clearance pathways for anterior segment OCT systems shape product development timelines for vendors seeking market access. High-throughput LASIK centers in California and Nevada drive replacement demand for precision measurement platforms.
Germany
University hospitals in Heidelberg and Berlin deploy swept-source OCT systems for combined corneal thickness and biometry applications. EU MDR Article 10 post-market surveillance requirements mandate systematic clinical follow-up data collection from optical pachymetry installations. Refractive surgery chains in Bavaria and North Rhine-Westphalia accelerate legacy device phase-outs ahead of compliance deadlines.
Japan
Compact ultrasound pachymeters designed for high-throughput screening environments dominate the Asia-Pacific installed base. METI standards for medical device software validation influence product registration pathways for optical coherence tomography modules. University hospitals in Osaka and Tokyo lead adoption of AI-assisted tomography analysis for ectasia risk scoring.
India
The PLI scheme for medical device manufacturing attracts optical assembly investments to serve South Asian refractive surgery expansion. CDSCO medical device rules classify corneal diagnostic tools according to risk-based categorization affecting import licensing. Diagnostic infrastructure buildout concentrates in Maharashtra and Gujarat, where mobile screening programs retain cost advantages for compact handheld ultrasound units.
Corneal Pachymetry Market Vendor Landscape
The competitive structure tilts toward integrated diagnostic suite providers over standalone device specialists. Optical platform vendors capture premium positioning through software subscription attach rates, while ultrasound manufacturers defend volume segments in price-sensitive deployment settings. Two strategic archetypes dominate: multi-function ophthalmic platform suppliers bundling anterior segment imaging with biometry, and specialized pachymetry vendors emphasizing precision repeatability for refractive surgery workflows. M&A activity concentrates on digital health capabilities, with strategic partnerships linking hardware manufacturers to cloud-based image analysis services.
Within the integrated platform tier, Carl Zeiss Meditec and Topcon Corporation exemplify the diagnostic suite archetype, anchoring premium positioning across European and North American accounts through modular bundling strategies. NIDEK Co. Ltd. occupies a distinct position among Asia-Pacific specialists, with its compact ultrasound systems representing the high-throughput screening archetype in mobile and emerging-market deployments.
| Leading Market Players |
|---|
| Sonomed Escalon |
| Topcon Corporation |
| Carl Zeiss Meditec |
| TOMEY Corporation |
| Haag-Streit Group |
| Reichert Inc. |
| DGH Technology, Inc |
| Lumibird Group |
| NIDEK Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Precision optical engineers concentrated in German and Japanese manufacturing clusters drive labor-cost differentials that widen spreads between premium anterior segment OCT systems and economy-tier ultrasound alternatives. This workforce geography anchors pricing power at the high end while enabling cost-competitive handheld production for emerging-market screening programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates corneal pachymetry equipment procurement. Premium spectral-domain OCT platforms command subscription-anchored valuations through software attach rates and upgrade cycles, while economy ultrasound units compete on per-unit transactional terms. Cost compression in the standard tier intensifies because MDR compliance investments inflate notified body review expenses. Mobile screening programs in price-sensitive deployment settings exhibit greatest price sensitivity; high-throughput refractive surgery chains in the United States and Germany demonstrate least sensitivity due to precision-throughput requirements.
Supply Chain Analysis
Precision interferometry subassemblies rest on German and Japanese optical specialists, with swept-source laser engines drawing from American photonics manufacturers. Key component dependencies include superluminescent diodes, precision translation stages, and custom optical coatings. Single-source vulnerability concentrates in specialty long-wavelength laser sources subject to export control classifications. Distribution runs through authorized ophthalmic equipment distributors serving hospital purchasing committees and ambulatory surgical center roll-ups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corneal pachymetry market functions as a regulatory compounder where EU MDR Article 10 post-market surveillance mandates are accelerating replacement demand for validated multi-function platforms ahead of legacy device phase-outs.
For Market Incumbents: Hedge against margin compression from spectral-domain OCT convergence by securing captive supply of precision optical subassemblies through backward integration into German and Japanese component sources. Fortify software subscription attach rates through AI-assisted tomography analysis modules that create differentiated renewal economics against emerging cloud-connected competitors. For New Entrants and Emerging Players: Rural tele-ophthalmology networks represent the most penetrable buyer archetype for cloud-connected anterior segment imaging platforms with remote monitoring capabilities. India's diagnostic infrastructure buildout under PLI scheme incentives offers white-space entry for compact ultrasound assembly investments serving South Asian refractive surgery expansion. Target GPO contracts at consolidating United States health systems as the primary go-to-market angle. For Investors and Strategic Acquirers: Integrated diagnostic suite providers are the most active acquirer in this space, seeking digital health capabilities to anchor premium positioning. The five-to-ten year viability window favors vendors with compliant MDR data infrastructure and recurring software revenue models. Acquisition target archetype: specialized pachymetry vendors with validated optical platforms and installed base migration potential. Watch FDA reimbursement code evolution for corneal imaging in glaucoma management as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence requirements reshape product development timelines for dual-territory placement. |
| Hospital System Partnership | Integrated delivery networks in Texas and Florida mandate standardized diagnostic protocols across acquired practices. |
| Software Companion Development | AI-assisted ectasia risk scoring creates differentiated attach rates for premium OCT configurations. |
| Reimbursement Strategy | Payer-mandated corneal imaging for IOP correction algorithms embeds pachymetry into routine workflows. |
| Geographic Expansion | PLI scheme incentives attract optical assembly investments to serve South Asian refractive surgery growth. |
Methodological Framework
Bottom-up ophthalmology clinic modeling reconciled against top-down optical equipment manufacturing tracking forms the analytical core. Primary interviews with refractive surgery center directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EUDAMED device registrations, CMS Medicare reimbursement databases, and hospital procurement records. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of equipment replacement cycles and refractive surgery volume concentration informed projection parameters across the analysis window. Segmentation dimensions modeled include product type, end user channel, technology architecture, and application area. CAGRs derive from fitted growth curves applied to validated base-year estimates, with specific inputs including EU MDR compliance deadline schedules and health system consolidation trajectories in the United States.
Underlying measurement precision varies by segment; anterior segment OCT and optical pachymetry categories carry tighter precision than ultrasound pachymeter estimates due to software subscription visibility. Forecasts reflect assumptions about regulatory timeline adherence and payer coverage expansion for glaucoma applications. MDR implementation delays, optical component supply disruptions, and reimbursement code denials represent specific risk factors that could revise projections. A small set of regulatory, supply chain, and payer triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Therapeutic Lenses Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
Ophthalmic Devices Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Tonometry Market
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
Aesthetic Ophthalmology Device Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Usher Syndrome Market
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
Dacryocystitis Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market