
 Blue Light Blocking Contact Lenses Market | 2026-2036
Blue Light Blocking Contact Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Blue Light Blocking Contact Lenses Market Insights
The capital-intensity gap between polymer-in-house producers and outsource-dependent assemblers is collapsing as silicone hydrogel co-polymerization becomes table stakes. Bausch + Lomb leverages captive monomer supply chains to sustain margin structures that commodity competitors cannot match. Menicon anchors its position through precision-cast molding expertise in toric geometries. CooperVision differentiates via direct-to-practitioner channel control across North American optometry networks.
Blue light blocking contact lenses incorporate selective wavelength-filtering chromophores or surface coatings that attenuate high-energy visible light between 380 and 500 nanometers while preserving visual acuity. Silicone hydrogel variants now dominate prescription volumes due to elevated oxygen permeability exceeding 100 Dk/t units. Daily use formats command premium positioning among professionals with intermittent screen exposure, whereas extended wear silicone hydrogel lenses capture recurring revenue from chronic digital workers. Toric designs for astigmatic correction concentrate margin pools where fitting complexity limits generic competition.
FDA 510(k) clearance pathways and ISO 11980 ophthalmic standards govern biocompatibility and blue light attenuation claims in the United States, while China's NMPA enforces GB standards for imported lens registration. The EU Medical Device Regulation intensifies post-market surveillance for pigment leaching and hypoxia-related adverse events. Stakeholders must monitor whether regulators classify high-filter lenses as wellness accessories or therapeutic devices, since this determination reshapes reimbursement and channel economics.
Market Dynamics
Silicone hydrogel co-polymerization is collapsing the capital barrier between integrated polymer producers and assembly-dependent competitors, forcing wholesale restructuring of margin architectures across the value chain.
Growth Catalysts
- Screen-time professional cohorts:Software developers, financial analysts, and remote knowledge workers now constitute the fastest-expanding prescription base for daily-use formats.
- FDA 510(k) pathway maturation:Streamlined biocompatibility review for silicone hydrogel variants accelerates time-to-market for chromophore-embedded designs.
- Germany's workplace safety frameworks:Occupational health guidelines now recognize high-energy visible light exposure as an ergonomic risk factor, triggering employer-subsidized lens programs.
Market Restraints
- Silicone monomer supply concentration:Three Asian chemical conglomerates control over 70% of medical-grade silicone hydrogel precursor output, creating input vulnerability.
- EU MDR post-market surveillance burdens:Mandatory pigment leaching studies and hypoxia adverse event reporting extend compliance costs by 18-24 months.
- LASIK and orthokeratology substitution:Permanent refractive correction continues capturing younger myopic patients who would otherwise convert to recurring lens revenue.
Strategic Opportunities
- China's tier-2 city penetration:Chengdu, Hangzhou, and Wuhan exhibit sub-15% blue light lens penetration despite 10+ hour daily screen exposure norms.
- Telehealth prescription channels:Direct-to-consumer vision testing platforms bypass traditional optometry gatekeepers, collapsing customer acquisition costs.
- ISO 11980 harmonization with NMPA:Converging international standards reduce dual-certification overhead for manufacturers seeking simultaneous US and China market entry.
Industry Challenges
- Toric fitting expertise scarcity:Astigmatic correction requires practitioner training that generic retail channels cannot replicate, constraining volume in mass-market formats.
- Chromophore stability validation:Accelerated aging protocols for wavelength-filtering additives lack industry consensus, creating certification timeline uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blue Light Blocking Contact Lenses Market |
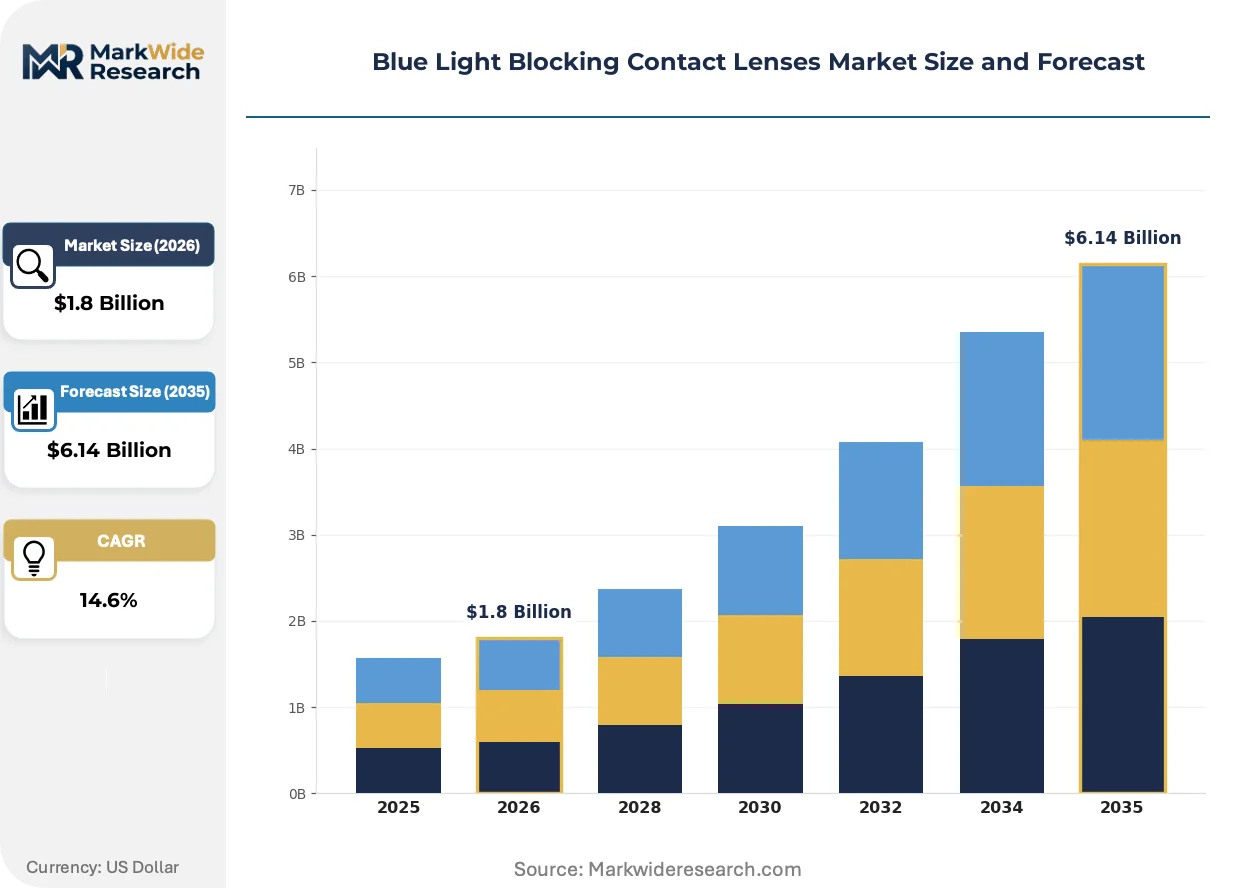
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Daily Use, Extended Wear, Toric, Spherical Material: Hydrogel, Silicone Hydrogel, PMMA, Others Distribution Channel: Online Retail, Optical Stores, Direct Sales, Hospitals End User: Adults, Children, Seniors, Professionals |
| Companies Covered | Bausch + Lomb, Menicon, Johnson & Johnson Vision Care, Jiangsu Hongchen Optical Co., Ltd., Clearlab, Novartis, Hoya Corp, St.Shine Optical, CooperVision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blue Light Blocking Contact Lenses Market Trends and Innovations
Active materials research is dissolving the boundary between optical correction and ocular surface therapy, embedding bioactive functions directly into lens substrates rather than treating them as passive devices.
Embedded nanoparticle chromophore systems are miniaturizing selective blue-light filtration into molecular-scale architectures without compromising oxygen permeability. Daily-disposable formats incorporating these materials now capture the majority of new prescriptions among intermittent screen users. The technology is miniaturizing the functional footprint of protective optics, enabling thinner lens profiles that reduce end-of-day discomfort while maintaining 450-nanometer peak attenuation.
China's NMPA has tightened GB standard enforcement for imported lens registration, requiring in-country clinical validation for all chromophore-containing designs. Domestic manufacturers with established trial networks now hold 6-12 month approval advantages over foreign entrants. European producers are responding by establishing Shanghai-based regulatory affairs subsidiaries to compress submission timelines.
Subscription replenishment models are displacing episodic retail purchasing among chronic digital workers, locking in 12-24 month revenue visibility. Direct-to-practitioner platforms now bundle automatic shipment with remote fitting support, capturing patient loyalty that brick-and-channel distributors cannot match. This behavioral pivot is most pronounced in the United States, where employer vision benefit administrators increasingly mandate mail-order fulfillment for premium-tier products.
Blue Light Blocking Contact Lenses Market Segmentation
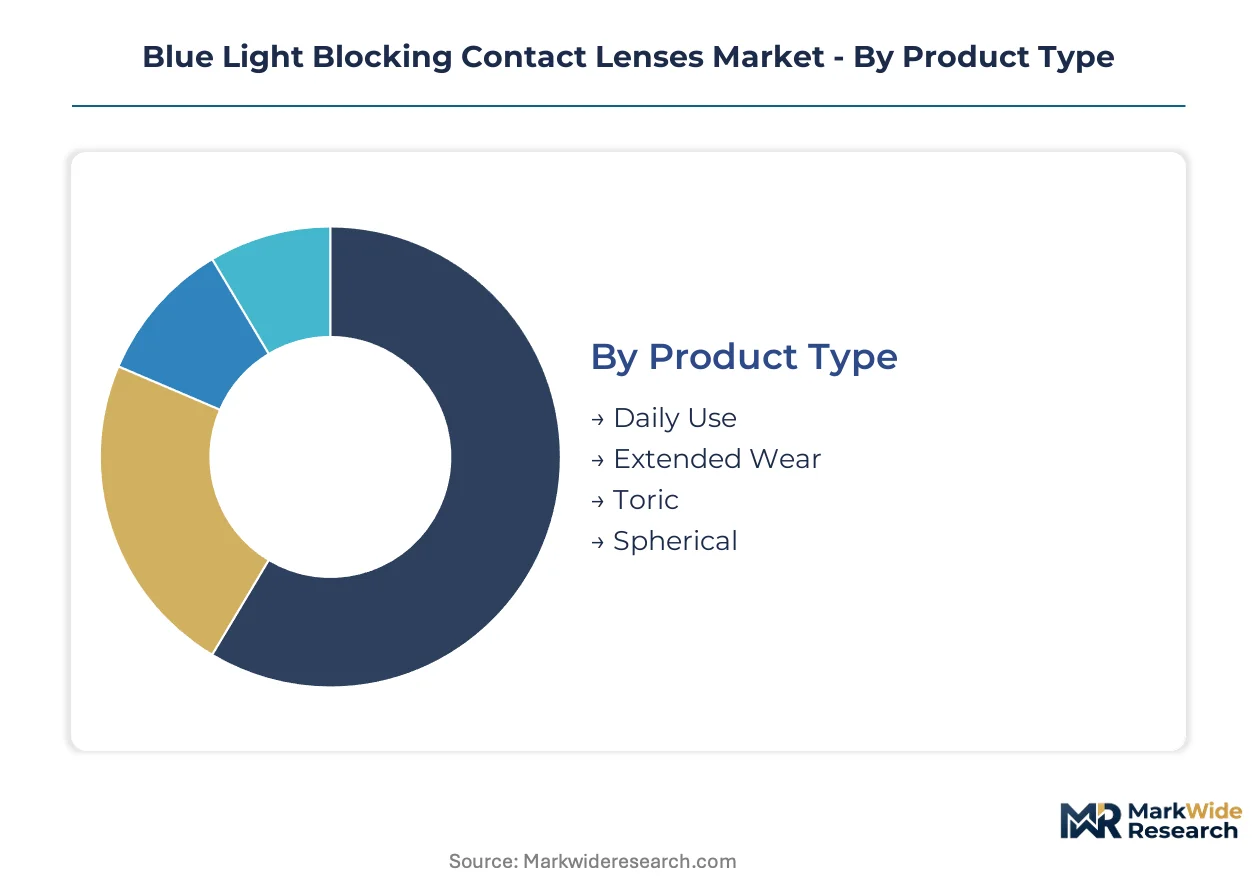
Blue light blocking contact lenses fragment across four distinct category axes, each mapping to different margin architectures and regulatory pathways. Understanding where value concentrates within each dimension separates premium-positioned suppliers from commodity assemblers.
Product Type:
Margin pools concentrate in formats requiring practitioner fitting expertise and recurring replenishment rather than one-time purchases.
- Daily Use:Single-use silicone hydrogel lenses embed chromophores directly into the polymer matrix for consistent 450-nanometer attenuation. Software developers and financial analysts in the United States drive prescription volumes through employer vision benefit programs.
- Extended Wear:Seven-to-thirty day continuous wear formats demand Dk/t values exceeding 100 units to prevent hypoxia-related complications. Chronic digital workers in Germany's employer-subsidized lens programs generate recurring revenue streams with 12-24 month subscription locks.
- Toric:Astigmatic correction requires precision-cast molding expertise that generic retail channels cannot replicate, limiting competition and preserving margin structures.
- Spherical:Standard refractive correction faces the steepest price compression from online retail channels and direct-to-consumer telehealth platforms.
Daily Use holds installed capacity. Extended Wear is rotating up the share rankings.
Material:
Cost tier stratification separates integrated polymer producers from assembly-dependent competitors, with oxygen permeability specifications determining clinical positioning.
- Silicone Hydrogel:Co-polymerized silicone hydrogel dominates prescription volumes through Dk/t values exceeding 100 units. China's NMPA now requires in-country clinical validation for all chromophore-containing designs, advantaging domestic manufacturers with established trial networks.
- Hydrogel:Legacy materials retain share in price-sensitive markets but suffer from oxygen permeability limitations below 30 Dk/t units, restricting wear duration.
- PMMA:Rigid gas-permeable formats persist in specialized orthokeratology applications despite comfort disadvantages.
- Others:Experimental materials including surface-modified fluorosilicone acrylates remain confined to clinical trial phases.
Silicone Hydrogel holds installed capacity. Hydrogel is rotating up the share rankings.
Distribution Channel:
Volume concentration shifts toward channels that collapse customer acquisition costs while preserving fitting quality assurance.
- Online Retail:Direct-to-consumer vision testing platforms bypass traditional optometry gatekeepers. Subscription replenishment models now displace episodic purchasing among chronic digital workers in the United States.
- Optical Stores:Brick-and-mortar channels retain toric fitting expertise that mass-market formats cannot replicate, constraining generic competition in astigmatic correction.
- Direct Sales:Manufacturer-to-practitioner platforms bundle automatic shipment with remote fitting support, capturing patient loyalty through North American optometry network control.
- Hospitals:Clinical settings concentrate therapeutic lens prescriptions for post-surgical or ocular surface disease patients requiring specialist oversight.
Optical Stores holds installed capacity. Online Retail is rotating up the share rankings.
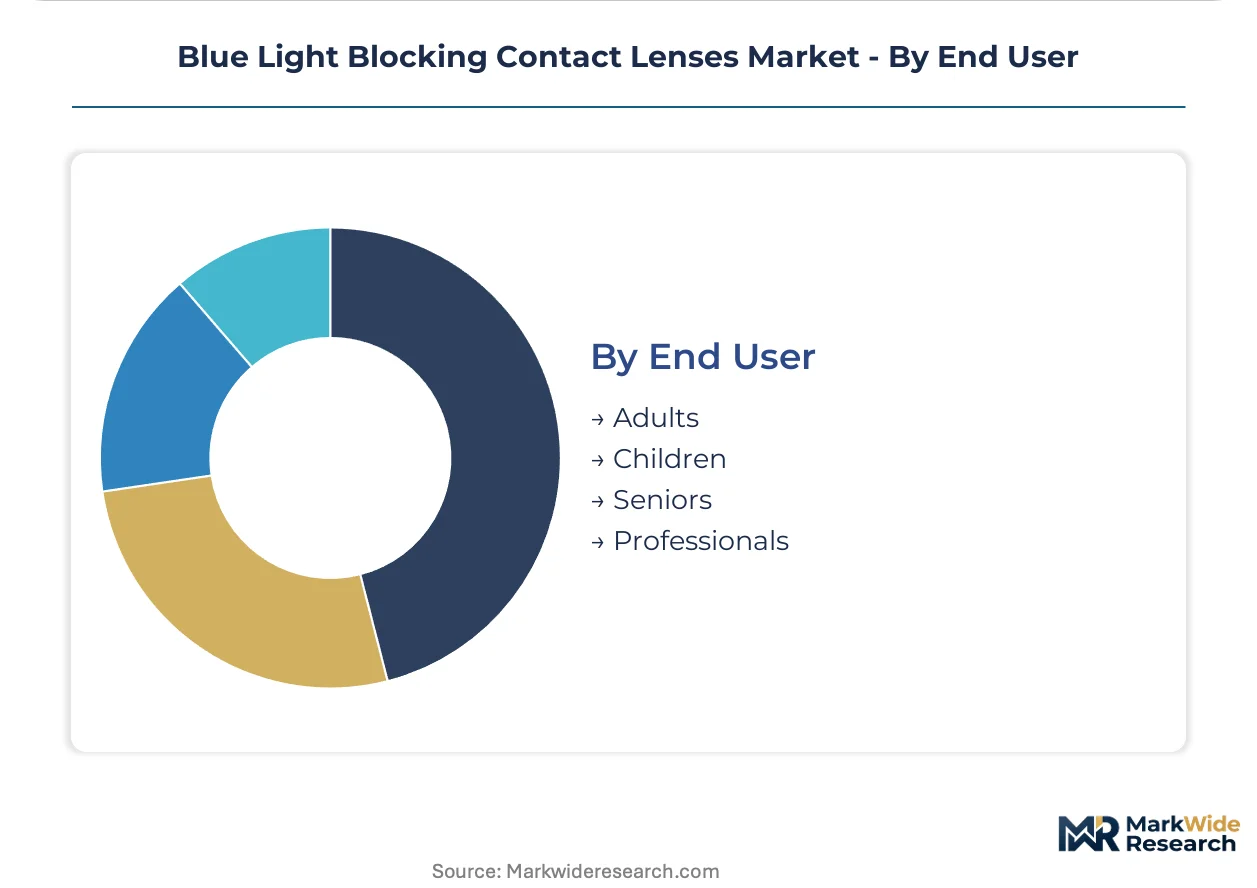
End User:
Customer type segmentation reveals divergent willingness-to-pay patterns across age cohorts and occupational exposure profiles.
- Professionals:Knowledge workers with 10+ hour daily screen exposure command premium positioning for daily-use formats. Chengdu, Hangzhou, and Wuhan exhibit sub-15% penetration despite comparable exposure norms, indicating expansion headroom.
- Adults:General myopic population represents the volume base but faces substitution pressure from LASIK and orthokeratology permanent correction.
- Seniors:Presbyopic patients with accumulated ocular surface sensitivity drive demand for high-oxygen-permeability extended wear formats.
- Children:Pediatric myopia control applications remain underpenetrated due to fitting complexity and parental compliance challenges.
Adults holds installed capacity. Professionals is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in India by a factor reflecting employer-subsidized occupational health mandates versus out-of-pocket consumer markets. This asymmetry shapes where manufacturers prioritize premium-format launches versus economy-tier volume plays.
United States
Software developers and financial analysts drive prescription volumes through employer vision benefit programs covering daily-use silicone hydrogel formats. FDA 510(k) clearance pathways streamline biocompatibility review for chromophore-embedded designs, accelerating commercialization timelines. Boston's biotechnology corridor hosts multiple firms refining nanoparticle chromophore systems for oxygen-permeable substrates.
Germany
Occupational health guidelines classify high-energy visible light exposure as an ergonomic risk factor, triggering employer-subsidized lens programs for chronic digital workers. The EU Medical Device Regulation intensifies post-market surveillance requirements for pigment leaching studies. Munich's precision optics cluster concentrates toric fitting expertise that limits generic retail competition.
China
Chengdu, Hangzhou, and Wuhan exhibit sub-15% blue light lens penetration despite 10+ hour daily screen exposure norms among knowledge workers. NMPA enforcement of GB standards for imported lens registration requires in-country clinical validation, advantaging domestic manufacturers with established trial networks. Shanghai-based regulatory affairs subsidiaries now compress submission timelines for European producers.
Japan
Presbyopic patients with accumulated ocular surface sensitivity command premium positioning for extended wear formats exceeding 100 Dk/t oxygen permeability. PMDA oversight harmonizes with ISO 11980 ophthalmic standards for biocompatibility certification. Tokyo's contact lens retail density supports practitioner-controlled fitting channels that resist direct-to-consumer displacement.
India
Price-sensitive consumers in metro markets sustain hydrogel format volumes despite oxygen permeability limitations below 30 Dk/t units. CDSCO registration requirements for imported medical devices create compliance barriers for foreign entrants lacking local distribution partnerships. Bangalore's IT workforce represents latent demand for employer-subsidized blue light protection programs.
Blue Light Blocking Contact Lenses Market Competitive Landscape
Concentration sits with integrated polymer producers capable of captive silicone hydrogel monomer supply. Three Asian chemical conglomerates control over 70% of medical-grade precursor output, creating structural barriers for assembly-dependent competitors. The vendor base stratifies across multinational ophthalmic device manufacturers, precision-cast molding specialists, and regional direct-to-practitioner platforms. Dominant competitive moves include backward integration into monomer production and direct channel control across North American optometry networks.
Among multinational ophthalmic device manufacturers, Bausch + Lomb and CooperVision exemplify divergent approaches to margin architecture. Bausch + Lomb occupies a position emphasizing captive supply chain control, while CooperVision anchors its presence through practitioner-facing platform investments. Menicon represents the precision-cast molding specialist archetype, with toric geometry expertise constraining generic competition. Johnson & Johnson Vision Care sits within the scale-driven tier, leveraging global distribution infrastructure across multiple regulatory jurisdictions.
| Leading Market Players |
|---|
| Bausch + Lomb |
| Menicon |
| Johnson & Johnson Vision Care |
| Jiangsu Hongchen Optical Co., Ltd. |
| Clearlab |
| Novartis |
| Hoya Corp |
| St.Shine Optical |
| CooperVision |
| Others |
Pricing and Supply Chain Analysis
Ninety-day chromophore inventory buffers at silicone hydrogel polymer plants now separate margin-resilient integrated producers from assembly-dependent competitors facing input volatility. This lead-time concentration concentrates pricing power with three Asian chemical conglomerates controlling medical-grade precursor supply, while downstream lens assemblers absorb cost pass-throughs they cannot hedge.
Pricing Analysis
The customization-premium spread between toric configured-to-order formats and spherical standard lenses now exceeds threefold in Germany's employer-subsidized occupational health programs. Pricing stratifies across premium, standard, and economy tiers based on oxygen permeability certification grade and practitioner fitting complexity. Price erosion runs through spherical daily-use formats as telehealth platforms collapse customer acquisition costs for commoditized refractive correction. Software developers and financial analysts in the United States exhibit lowest price sensitivity, while India's metro consumers sustain hydrogel volumes through out-of-pocket purchasing constraints.
Supply Chain Analysis
Silicone monomer feedstock transit through Korean and Japanese chemical processing hubs underwrites lens polymer output stability for integrated manufacturers. Medical-grade silicone hydrogel precursors draw from China, South Korea, and Japan, with chromophore additives sourcing from specialized German and Swiss dye chemistry specialists. Single-source vulnerability concentrates in medical-grade silicone hydrogel monomer supply, where three Asian conglomerates control over seventy percent of global output. Distribution runs through direct-to-practitioner platforms in North America, optical store networks in Japan, and online retail channels in China's tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent refractive correction through LASIK and orthokeratology now captures younger myopic patients who would otherwise convert to recurring lens revenue, forcing incumbents to defend replacement demand through clinical differentiation and channel lock-in.
For Market Incumbents: Secure captive silicone hydrogel monomer supply chains to sustain margin structures that commodity assemblers cannot replicate under input volatility. Invest in precision-cast molding capacity for toric geometries where fitting complexity limits generic retail competition. The threat of telehealth platform disintermediation demands direct-to-practitioner channel control across North American optometry networks. For New Entrants and Emerging Players: Remote fitting support for astigmatic patients represents a service-layer gap where incumbents under-serve through legacy brick-and-channel structures. Target China's tier-2 cities—Chengdu, Hangzhou, and Wuhan—where sub-fifteen percent blue light lens penetration contrasts with ten-plus hour daily screen exposure norms. Pursue NMPA in-country clinical validation partnerships to compress approval timelines against foreign entrants lacking established trial networks. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue defense play because subscription replenishment models now displace episodic retail purchasing among chronic digital workers, locking in twelve-to-twenty-four month revenue visibility. Acquisition targets should concentrate on precision-cast molding specialists with toric geometry expertise and established regulatory affairs subsidiaries in Shanghai. The signal to watch is NMPA classification determination for high-filter lenses as wellness accessories versus therapeutic devices, which reshapes reimbursement economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive silicone hydrogel supply insulates margin structures from Asian precursor concentration. |
| Direct-to-Practitioner Platform Investment | Channel control across North American optometry networks resists telehealth disintermediation. |
| NMPA Regulatory Affairs Subsidiary Establishment | Shanghai-based operations compress chromophore-containing design approval timelines. |
| Precision-Cast Molding Capacity Expansion | Toric geometry expertise constrains generic competition in astigmatic correction segments. |
| Subscription Replenishment Model Deployment | Automatic shipment bundling captures patient loyalty that brick-and-channel distributors cannot match. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with contact lens manufacturing executives, regulatory affairs specialists at FDA and NMPA, optometrists in North American network practices, and procurement managers at employer vision benefit administrators. Secondary validation drew from FDA 510(k) clearance databases, NMPA GB standard filings, ISO 11980 ophthalmic standard documentation, and optical industry trade data. Bottom-up prescription volume modeling and top-down market sizing triangulated across these sources.
Across the analysis window, the quantitative framework segmented by product type, material composition, distribution channel, and end-user occupational exposure profile. CAGRs were derived from installed base erosion rates, replacement cycle compression, and new user conversion assumptions. Forecast inputs incorporated silicone hydrogel Dk/t specification adoption curves, chromophore stability validation timelines, and employer subsidy program expansion trajectories.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR post-market surveillance frameworks, and NMPA GB standard enforcement; material classification shifts for high-filter lenses would require re-modeling reimbursement and channel economics. Chromophore leaching study outcomes, silicone monomer supply disruptions, and LASIK technology advancement present specific revision triggers. Practitioners should keep alternative scenarios live as employer vision benefit administrator mandates and telehealth prescription channel penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Global Artificial Tear Market
Ophthalmology
Global Ophthalmology Drugs and Devices Market
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market
Ophthalmology
Ophthalmology Diagnostics Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Vitreous Detachment Treatment Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
USA Ophthalmic Devices Market