
 Latin America Dry Eye Syndrome Market | 2026-2036
Latin America Dry Eye Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Dry Eye Syndrome Market Intelligence
Capital-intensity divergence between multinational pharmaceutical manufacturers and regional distributors is bifurcating competitive dynamics across Latin America. Alcon Inc leverages its vertically integrated supply chain to sustain premium positioning in prescription medications and punctal plug portfolios. Johnson & Johnson anchors broad market penetration through extensive retail pharmacy partnerships spanning Mexico and Colombia. Sun Pharmaceutical Industries competes on cost-optimized artificial tear formulations tailored to price-sensitive homecare segments.
Dry eye syndrome encompasses a spectrum of ocular surface disorders characterized by tear film instability, hyperosmolarity, and inflammation of the corneal and conjunctival epithelia, typically diagnosed through tear break-up time testing, Schirmer strip assessment, and osmolarity measurement. The condition's primary commercial purpose centers on restoring tear film homeostasis to prevent progressive corneal damage and sustain visual function. Prescription medications command concentrated margin pools due to cyclosporine and lifitegrast formulations requiring sustained clinical oversight, while artificial tears represent the volume foundation driven by self-directed consumer purchasing in retail channels. Eye drops dominate delivery mode preferences for their convenience profile, though gel formulations are gaining traction among severe cases requiring prolonged corneal contact time.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce divergent ophthalmic product registration standards that directly shape market access timelines and clinical trial obligations for imported therapies. CE marking equivalency provisions under Mercosur technical regulations partially streamline pathway convergence for certain device categories, though pharmaceutical registrations remain jurisdiction-specific. Stakeholders must monitor evolving pharmacovigilance harmonization discussions across the Pacific Alliance to anticipate consolidated submission requirements that could reshape regional launch sequencing and partnership structures.
Market Dynamics
ANVISA's tightened ophthalmic device registration pathways are compressing product entry timelines and forcing manufacturers to front-load clinical evidence generation before Brazilian market access. This regulatory friction is redistributing competitive advantage toward established players with dedicated Latin American regulatory affairs infrastructure.
Growth Catalysts
- Evaporative diagnostic expansion:Ophthalmology clinics across Brazil and Mexico are installing meibomian gland imaging systems to segment treatment pathways for evaporative versus aqueous-deficient cases.
- COFEPRIS streamlined review:Mexico's regulatory authority has implemented priority review tracks for novel ophthalmic actives, accelerating cyclosporine and lifitegrast formulation approvals.
- Southeastern corridor concentration:Private eye care networks in São Paulo and Rio de Janeiro are scaling specialty dry eye clinics with in-house tear osmolarity testing capacity.
Market Restraints
- API import dependency:Cyclosporine and hyaluronic acid raw materials concentrate among Indian and Chinese suppliers, exposing formulation costs to currency volatility and shipping disruptions.
- Reimbursement fragmentation:Brazil's SUS public system excludes most prescription dry eye therapies, restricting volume to affluent private-pay segments concentrated in coastal metropolitan areas.
- Diagnostic equipment capex:Tear osmolarity meters and meibography systems require capital outlays that independent ophthalmology practices in secondary Colombian and Argentine cities cannot absorb.
Strategic Opportunities
- Homecare artificial tear penetration:Price-optimized preservative-free formulations targeting self-directed consumers in Chile's pharmacy retail chains represent underexploited volume pools.
- Teleophthalmology convergence:Remote diagnostic platforms integrating smartphone-based tear film imaging with AI-assisted severity scoring are opening rural and suburban access corridors.
- Mercosur technical harmonization:CE marking equivalency provisions for ophthalmic devices are reducing redundant conformity testing costs across Brazil, Argentina, and Uruguay.
Industry Challenges
- Specialized technician scarcity:Tear film analysis and meibomian gland expression procedures require trained ophthalmic technicians that training programs in Peru and Ecuador have not scaled to match clinic expansion.
- Multijurisdictional pharmacovigilance:Divergent adverse event reporting timelines across ANVISA, COFEPRIS, and INVIMA force manufacturers to maintain parallel compliance infrastructures with non-overlapping submission calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Dry Eye Syndrome Market |
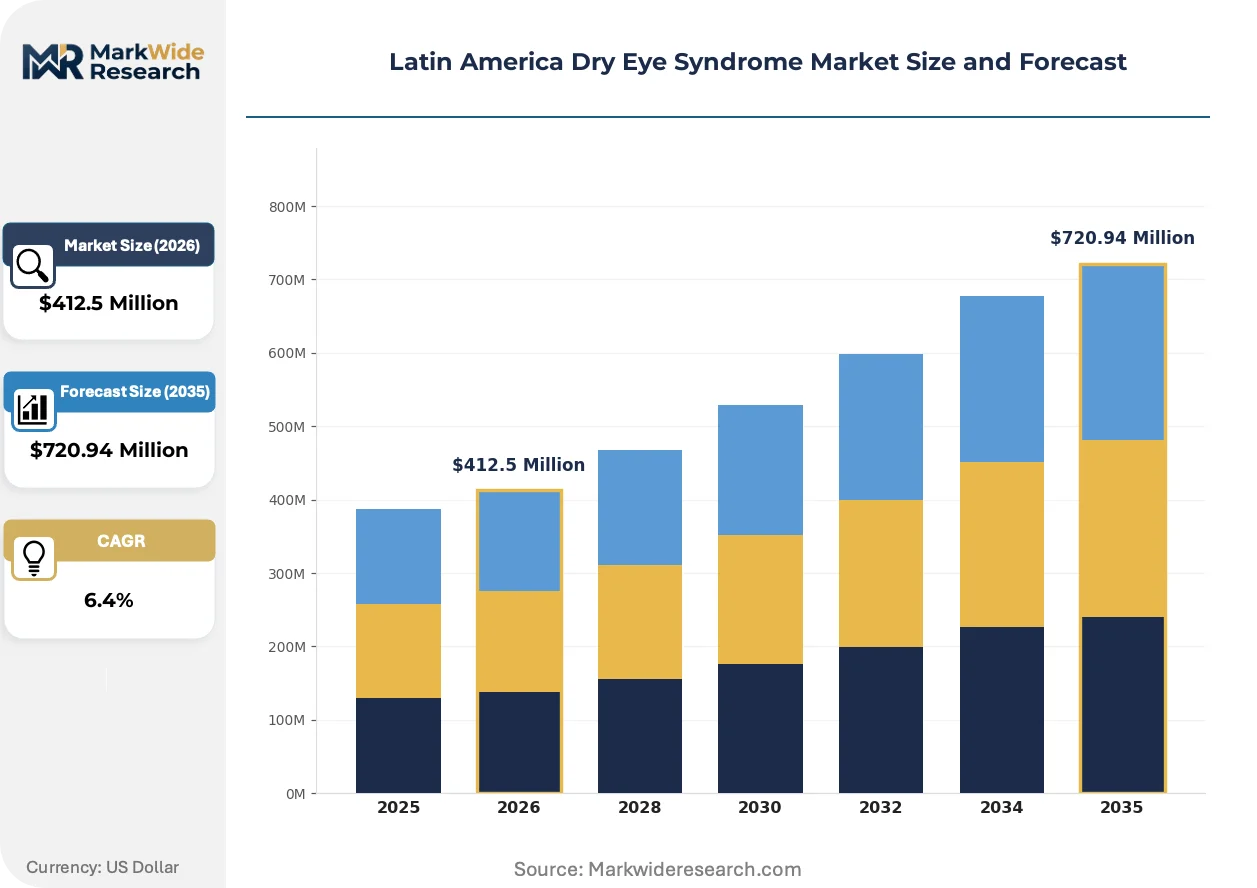
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Tears, Prescription Medications, Punctal Plugs, Hydrating Drops Delivery Mode: Eye Drops, Ointments, Gels, Inserts End User: Ophthalmology Clinics, Hospitals, Homecare Settings, Research Laboratories Application: Therapeutic, Diagnostic, Surgical, Research |
| Companies Covered | Alcon Inc, Johnson & Johnson, AbbVie Inc, Otsuka Pharmaceutical, Sun Pharmaceutical Industries, Santen Pharmaceutical Co Ltd, Bausch & Lomb Corp, OASIS Medical, Novartis AG, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Dry Eye Syndrome Market Strategic Shifts & Innovations
Tear film diagnostics and treatment delivery modes are fragmenting into specialty subsystems, with technology vendors and pharmaceutical developers pursuing divergent innovation pathways rather than integrated platform dominance.
Osmolarity-based diagnostic systems are decomposing the traditional slit-lamp examination workflow into quantifiable, reimbursable procedure codes. Large ophthalmology groups in São Paulo and Mexico City are adopting point-of-care osmolarity meters as front-line screening tools. This decomposition is compressing the addressable market for comprehensive dry eye workups into discrete, billable diagnostic components that general ophthalmologists can perform without subspecialty referral.
ANVISA's 2023 ophthalmic device guidance requiring local clinical validation for novel diagnostic platforms is extending registration timelines for imported meibography and tear film interferometry systems. The industrial consequence is a shift toward Brazilian contract research organizations conducting bridging studies. Multinational manufacturers are responding by pre-positioning clinical affairs personnel in São Paulo to manage investigator-initiated trial networks.
Self-directed purchasing of artificial tears through e-pharmacy channels is displacing traditional pharmacist counseling in Brazil's southeastern states. Mercado Libre and Drogasil's digital platforms now capture significant volume for preservative-free formulations. This channel rotation is most visible among working-age contact lens wearers in São Paulo's metropolitan corridor, where convenience and subscription pricing override retail pharmacy loyalty.
Latin America Dry Eye Syndrome Market Segmentation
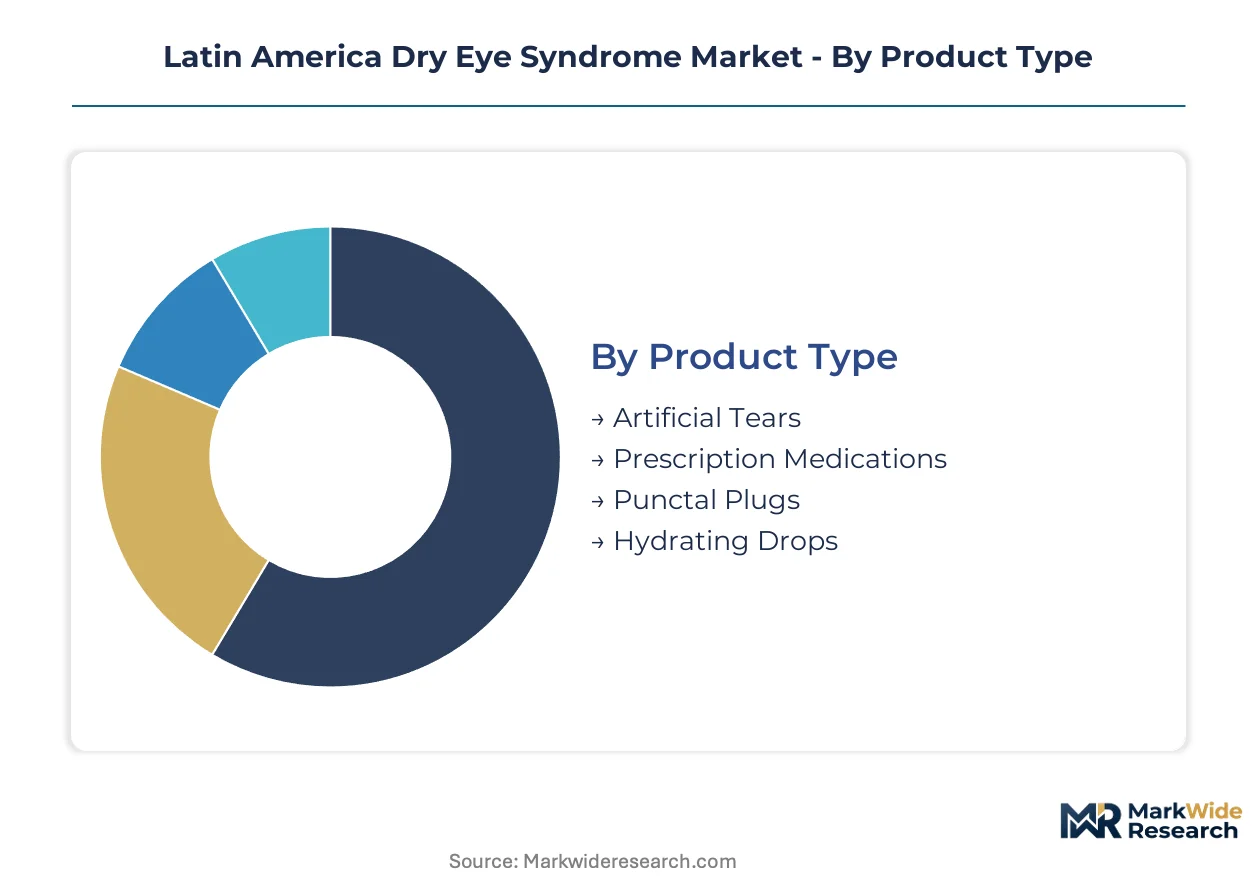
Segmentation in Latin America's dry eye syndrome market reveals distinct procurement patterns across public and private channels, with product type and delivery mode preferences diverging sharply between metropolitan clinic networks and dispersed homecare consumers. Understanding these divides enables targeted positioning against regulatory and reimbursement fragmentation.
Product Type:
Geographic concentration varies: artificial tears flow through retail pharmacy networks across all major cities, while prescription medications concentrate in São Paulo and Mexico City where private insurance penetration sustains reimbursement.
- Artificial Tears:Preservative-free formulations dominate shelf space in Brazilian pharmacy chains. Demand clusters among contact lens wearers in São Paulo's metropolitan corridor, where self-directed purchasing through Mercado Libre and Drogasil digital platforms is displacing traditional retail.
- Prescription Medications:Cyclosporine and lifitegrast formulations require sustained clinical oversight and command concentrated margin pools. Volume concentrates in private eye care networks across southeastern Brazil, where tear osmolarity testing justifies therapeutic escalation.
- Punctal Plugs:Silicone and collagen-based variants serve refractory cases in specialized ophthalmology clinics. ANVISA's tightened device registration pathways compress entry timelines for novel materials.
- Hydrating Drops:Hyaluronic acid-based formulations compete on viscosity differentiation. API import dependency from Indian and Chinese suppliers exposes margins to currency volatility.
Artificial tears hold the largest share; momentum sits with prescription medications as diagnostic capacity expands.
Delivery Mode:
Cost tiering separates convenience-driven retail purchases from clinically supervised interventions, with reimbursement eligibility determining channel placement.
- Eye Drops:Dominant delivery preference for convenience profile. Volume concentrates in Brazil's southeastern states through e-pharmacy subscription models targeting working-age professionals.
- Ointments:Overnight lubrication for severe cases. Demand clusters in hospital-based ophthalmology departments with inpatient capacity.
- Gels:Prolonged corneal contact time addresses evaporative dry eye. Adoption accelerates in Mexico City clinics installing meibomian gland imaging systems.
- Inserts:Sustained-release hydroxypropyl cellulose devices serve refractory aqueous-deficient cases. Limited penetration due to insertion technique requirements and patient education burdens.
Eye drops capture volume leadership; gels are climbing the fastest as evaporative diagnostic segmentation expands.
End User:
Customer type stratification reflects capital intensity divergence: institutional settings absorb diagnostic equipment costs while homecare depends on out-of-pocket retail purchasing.
- Ophthalmology Clinics:Primary site for diagnostic workup and prescription initiation. Private networks in São Paulo and Rio de Janeiro are scaling specialty dry eye clinics with in-house tear osmolarity testing.
- Hospitals:Acute presentation and surgical comanagement. Concentrated in tertiary centers with corneal subspecialty coverage.
- Homecare Settings:Self-directed artificial tear purchasing dominates. Chile's pharmacy retail chains represent underexploited volume pools for price-optimized preservative-free formulations.
- Research Laboratories:Clinical trial sites for novel actives. ANVISA's 2023 device guidance requiring local clinical validation is extending registration timelines.
Ophthalmology clinics anchor revenue; homecare settings are gaining share fastest through digital channel expansion.
Application:
Maturity stages separate established therapeutic categories from emerging diagnostic and research segments with divergent margin profiles.
- Therapeutic:Established revenue base spanning artificial tears through immunomodulatory prescriptions. Brazil's SUS public system exclusions restrict prescription volume to affluent private-pay segments.
- Diagnostic:Osmolarity-based systems decomposing slit-lamp workflows into reimbursable procedure codes. Point-of-care meters are gaining traction in large ophthalmology groups.
- Surgical:Punctal plug insertion and amniotic membrane application. Limited to subspecialty practices with procedural reimbursement contracts.
- Research:Investigator-initiated trials for novel formulations. Brazilian CROs are conducting bridging studies to satisfy ANVISA validation requirements.
Therapeutic applications command current share; diagnostic applications show the steepest expansion trajectory as billing codes crystallize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Latin America. Brazilian private-pay patients absorb premium prescription therapies, while Mexican and Colombian consumers gravitate toward cost-optimized artificial tears. Argentina's currency instability forces patients toward the lowest-cost formulations regardless of clinical severity.
Brazil
ANVISA's tightened ophthalmic device registration pathways are extending timelines for imported diagnostic platforms. São Paulo's private eye care networks are scaling specialty dry eye clinics with in-house tear osmolarity testing. Southeastern metropolitan corridors concentrate demand for cyclosporine and lifitegrast formulations.
Mexico
COFEPRIS has implemented priority review tracks for novel ophthalmic actives, accelerating prescription medication approvals. Mexico City's ophthalmology clinics are installing meibomian gland imaging systems to segment evaporative versus aqueous-deficient cases. Private insurance penetration sustains reimbursement for sustained clinical oversight therapies.
Argentina
Currency volatility and import restrictions are compressing margins for multinational pharmaceutical manufacturers. Buenos Aires maintains concentration of tertiary ophthalmology centers with corneal subspecialty coverage. Patients face forced substitution toward domestically compounded artificial tear formulations.
Chile
Chile's pharmacy retail chains represent underexploited volume pools for price-optimized preservative-free artificial tears. The country's national pharmaceutical regulator maintains streamlined over-the-counter pathways for lubricant eye drops. Santiago's metropolitan corridor drives e-pharmacy subscription adoption among working-age contact lens wearers.
Colombia
INVIMA enforces jurisdiction-specific ophthalmic product registration standards that shape market access timelines for imported therapies. Bogotá's hospital-based ophthalmology departments absorb capital equipment costs for diagnostic workups. Independent practices in secondary cities cannot absorb tear osmolarity meter capital outlays.
Latin America Dry Eye Syndrome Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across Latin America's dry eye syndrome market. Multinational pharmaceutical manufacturers with vertically integrated supply chains sustain premium positioning in prescription medications and device portfolios. Regional distributors compete on cost-optimized artificial tear formulations tailored to price-sensitive homecare segments. Dominant competitive moves include strategic partnerships with private eye care networks and portfolio diversification into preservative-free formulations.
Within the multinational tier, Alcon Inc and Johnson & Johnson occupy positions anchored by extensive retail pharmacy partnerships spanning Mexico and Colombia. Sun Pharmaceutical Industries exemplifies the cost-optimized archetype, competing on artificial tear formulations for price-sensitive segments. These three companies represent the spectrum from premium prescription therapies through volume-driven homecare products.
| Leading Market Players |
|---|
| Alcon Inc |
| Johnson & Johnson |
| AbbVie Inc |
| Otsuka Pharmaceutical |
| Sun Pharmaceutical Industries |
| Santen Pharmaceutical Co Ltd |
| Bausch & Lomb Corp |
| OASIS Medical |
| Novartis AG |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts for cyclosporine and hyaluronic acid raw materials lock in supply access and price visibility for multinational pharmaceutical manufacturers navigating ANVISA's tightened registration pathways. These arrangements insulate formulation costs from currency volatility while exposing regional distributors to spot-market fluctuations in API pricing.
Pricing Analysis
After-sales service revenue from sustained clinical oversight drives lifetime value for prescription medications, with cyclosporine and lifitegrast formulations commanding premium positioning through physician-administered monitoring programs. Three-tier pricing structure across premium preservative-free, standard preserved, and economy generic artificial tears separates reimbursement-eligible therapies from self-pay retail purchases. Pricing pressure stems from API import dependency on Indian and Chinese suppliers, compressing margins for regional distributors. Private-pay patients in São Paulo's metropolitan corridor show lowest price sensitivity, while Argentine consumers face forced substitution toward domestically compounded formulations.
Supply Chain Analysis
Strategic stockpiling of hyaluronic acid and cyclosporine APIs dominates inventory strategy among multinational manufacturers buffering against shipping disruptions from Indian and Chinese supply centers. Raw material concentration in these two countries creates single-source vulnerability for preservative-free formulation lines. Distribution runs through vertically integrated supply chains for premium prescription tiers, while cost-optimized artificial tears feed from regional compounding facilities into retail pharmacy networks. Tariff exposure on imported diagnostic equipment compounds capital intensity for independent ophthalmology practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as evaporative diagnostic capacity proliferates across Brazil and Mexico, creating infrastructure for therapeutic escalation that did not exist five years ago.
For Market Incumbents: Consolidate regulatory affairs infrastructure in São Paulo to manage ANVISA's local clinical validation requirements for diagnostic platforms. Deepen backward integration into preservative-free formulation lines to defend margin position against Sun Pharmaceutical Industries' cost-optimized artificial tear competition. Prioritize capacity reservation contracts with Indian API suppliers to secure cyclosporine access. For New Entrants and Emerging Players: Differentiate on teleophthalmology-enabled remote diagnostics targeting Chile's underexploited pharmacy retail chains and Colombia's secondary cities lacking tear osmolarity meter capital absorption. White-space concentration sits in homecare artificial tear penetration through e-pharmacy subscription models. Pursue partnership-based go-to-market structures with Mercado Libre and Drogasil digital platforms. For Investors and Strategic Acquirers: Capital is best deployed toward Brazilian contract research organizations conducting bridging studies for ANVISA device registrations, capturing regulatory friction rents over the medium-term horizon. Acquisition target archetype: specialty dry eye clinic networks in São Paulo and Rio de Janeiro with in-house diagnostic capacity. Signal to watch is COFEPRIS priority review track expansion to additional ophthalmic actives.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Local Clinical Validation | Brazilian CRO partnerships compress registration timelines for meibography and tear film interferometry systems. |
| Preservative-Free Formulation Line | Capacity addition captures self-directed purchasing displacement through Mercado Libre and Drogasil digital channels. |
| Teleophthalmology Platform Integration | Remote diagnostic access opens rural and suburban corridors beyond metropolitan clinic concentration. |
| API Supplier Diversification | Dual-sourcing from Indian and Chinese cyclosporine manufacturers mitigates currency volatility exposure. |
| Specialty Clinic Network Partnership | Hospital system alliances in Mexico City and Bogotá secure reimbursement contracts for sustained clinical oversight therapies. |
Research Approach
Cross-validation between ophthalmology clinic procurement managers and pharmaceutical regulatory affairs leads anchors the qualitative findings on ANVISA pathway friction. Primary interviews with formulary directors at private Brazilian insurers, tear film diagnostic equipment biomedical engineers, and GPO contracts managers at Mexican hospital systems combined with secondary validation from ANVISA registration databases, COFEPRIS approval records, ClinicalTrials.gov ophthalmic trial listings, and customs import data for API shipments. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation reconcile volume estimates.
Sensitivity analysis on evaporative diagnostic adoption rates and prescription therapy reimbursement eligibility shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user setting, and regional regulatory cluster. CAGRs derive from patient population growth, diagnostic penetration curves, and pricing trajectory assumptions. Forecast inputs incorporate meibomian gland imaging system installation rates and e-pharmacy channel share displacement.
Decision-makers should treat outputs as directional under stable ANVISA registration pathway assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions on private insurance penetration sustaining prescription medication access and API import channel stability. Revision becomes warranted when COFEPRIS priority review track scope expansion or Pacific Alliance pharmacovigilance harmonization crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
United States Dry Eye Syndrome Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Non-Infectious Macular Edema Treatment Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Global Uveitis Treatment Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Tonometry Market
Ophthalmology
Ophthalmology Diagnostics Market
Ophthalmology
Superficial Punctate Keratitis Treatment Market