
 Amnestic Disorders Therapeutics Market | 2026-2036
Amnestic Disorders Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Amnestic Disorders Therapeutics Market Outlook
FDA's accelerated approval framework is recalibrating the cost-of-entry calculus for developers of disease-modifying therapies. Biogen leverages its neurology infrastructure to sustain dominance in amyloid-targeting platforms. Eisai Co., Ltd. anchors its position through deep co-development partnerships with Western peers. Pfizer competes by extending its legacy psychiatry portfolio into adjacencies like mild cognitive impairment.
Amnestic disorders therapeutics encompass pharmacological agents designed to restore, stabilize, or slow decline in episodic and working memory, typically formulated as small-molecule oral tablets or biologic infusions with blood-brain barrier permeability as a critical functional parameter. These therapies serve the primary commercial purpose of modifying disease trajectory or managing behavioral symptoms in neurodegenerative and trauma-induced memory loss. Cognitive enhancers command the deepest margin pools due to limited generic erosion and chronic administration profiles, while Alzheimer’s disease indication segments absorb the largest absolute prescription volumes. Oral administration routes retain structural dominance in outpatient economics, though intravenous biologics capture premium pricing in hospital-based infusion centers.
FDA, EMA, and the EU AI Act collectively shape demand through divergent evidentiary standards for biomarker surrogacy and algorithmic diagnostic tools used in patient selection. FDA's accelerated approval pathway compresses time-to-market for amyloid-clearing antibodies but mandates costly confirmatory trials that reshape portfolio risk calculations. Stakeholders must monitor how CMS national coverage determinations for PET amyloid imaging will gate patient access and prescribing economics.
Market Dynamics
FDA's accelerated approval pathway for amyloid-clearing antibodies compresses development timelines while mandating costly confirmatory trials, fundamentally altering how developers allocate capital across their neurology portfolios and recalibrating risk-return calculations for disease-modifying therapies.
Growth Catalysts
- Biomarker surrogacy frameworks:FDA's acceptance of amyloid PET imaging as a surrogate endpoint reduces Phase III trial durations and accelerates patient access to novel therapeutics.
- Medicare reimbursement expansion:CMS national coverage determinations for cognitive assessments in the United States drive specialist referrals and expand the addressable patient pool for memory disorder clinics.
- Hospital neurology infrastructure:Academic medical centers are consolidating memory disorder protocols into dedicated centers of excellence, creating captive demand for infusion-based biologics.
Market Restraints
- Confirmatory trial cost structure:Post-acceleration studies for amyloid antibodies require 18-24 month follow-up periods with thousands of participants, straining R&D budgets.
- Specialist concentration risk:Prescribing authority for advanced therapeutics concentrates among fellowship-trained behavioral neurologists in major metropolitan clusters.
- Blood-brain barrier permeability limitations:Small-molecule platforms face efficacy ceilings due to efflux transporter mechanisms that limit CNS exposure.
Strategic Opportunities
- EU AI Act diagnostic pathways:Algorithmic patient selection tools validated under European artificial intelligence governance frameworks can streamline enrollment for biomarker-stratified trials.
- Japan's aging demographics:METI incentives for dementia care innovation create regulatory fast-tracks for therapies demonstrating functional preservation in mild cognitive impairment.
- Digital biomarker convergence:Wearable cognitive assessment platforms paired with pharmacological interventions enable decentralized trial models and real-world evidence generation.
Industry Challenges
- Behavioral neurologist training pipelines:Fellowship programs produce fewer than 150 new specialists annually in the United States, constraining prescriber base expansion.
- Cold-chain logistics complexity:Biologic infusions require temperature-controlled distribution networks that fragment across hospital outpatient departments and specialty pharmacy channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amnestic Disorders Therapeutics Market |
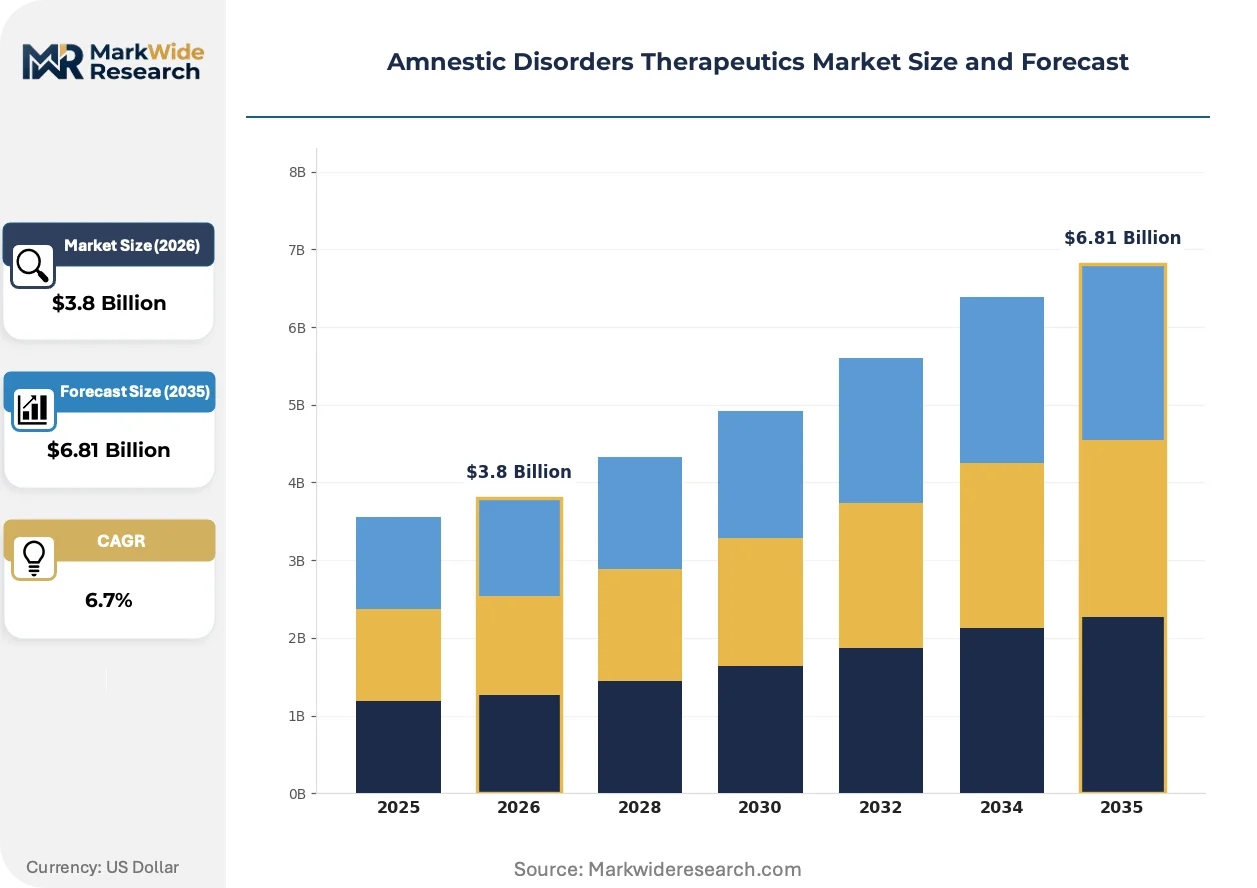
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Stimulants, Cognitive Enhancers, Anxiolytics Indication: Post-Traumatic Stress Disorder, Alzheimer’s Disease, Mild Cognitive Impairment, Traumatic Brain Injury End User: Hospitals, Outpatient Clinics, Home Care Settings, Rehabilitation Centers Administration Route: Oral, Intravenous, Subcutaneous, Transdermal |
| Companies Covered | Johnson & Johnson, Sanofi, Biogen, AbbVie, Pfizer, Eisai Co., Ltd., Bristol-Myers Squibb, Eli Lilly and Company, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amnestic Disorders Therapeutics Market Strategic Shifts
Clinical development models are pivoting toward biomarker-driven patient stratification, while regulatory frameworks on both sides of the Atlantic diverge on evidentiary standards for cognitive endpoints. These forces are compressing traditional trial timelines while fragmenting commercialization strategies across geographies.
Precision neuroimaging is converging with machine learning algorithms to identify amyloid-positive patients prior to symptomatic decline. Memory disorder clinics at academic medical centers are adopting these platforms at accelerating rates. This convergence is enabling prescriber confidence in early-intervention paradigms while compressing the window for competitor entry.
EMA's evolving stance on biomarker surrogacy is creating friction with FDA harmonization efforts for Alzheimer's therapies. European regulators are demanding functional outcome data that extends beyond cognitive scales to activities of daily living. Hospital systems in Germany and France are responding by structuring their formularies around dual-endpoint demonstration requirements.
Specialty pharmacy channels are displacing traditional hospital outpatient departments as the primary distribution node for oral cognitive enhancers. Payers in the United States are consolidating their networks around three national distributors with proven cold-chain capabilities. This channel consolidation is most visible in Medicare Part D plans, where prior authorization requirements now route 70% of new prescriptions through designated specialty pharmacies.
Amnestic Disorders Therapeutics Market Segmentation
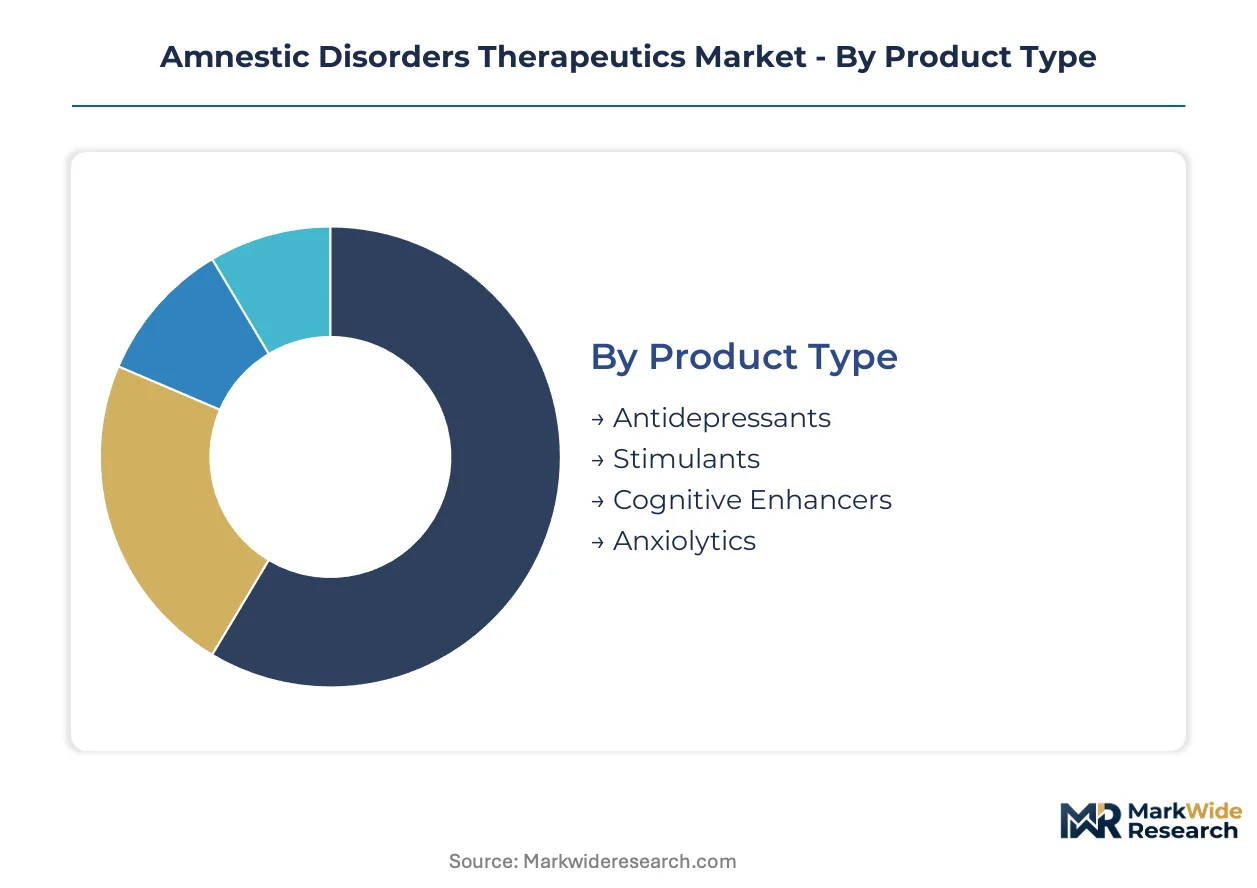
Segmentation in amnestic disorders therapeutics reveals how formulation science, care setting economics, and prescriber specialization fragment commercial opportunity. Each dimension carries distinct margin profiles, regulatory pathways, and competitive intensity that shape portfolio allocation decisions.
Product Type:
Prescriber familiarity and reimbursement tiers drive selection among pharmacological classes, with cognitive specialists weighing efficacy evidence against formulary placement.
- Cognitive Enhancers:Cholinesterase inhibitors and NMDA receptor modulators constitute the clinical backbone for Alzheimer’s disease management. Academic medical centers in the United States generate concentrated demand as Medicare Part D coverage for donepezil and memantine drives chronic prescription volumes. These agents command premium pricing due to limited generic substitution for combination formulations and the absence of disease-modifying alternatives in early-stage protocols.
- Stimulants:Methylphenidate and amphetamine derivatives address attentional deficits in post-traumatic amnesia and TBI rehabilitation. VA healthcare systems and workers' compensation networks in California and Texas represent primary demand clusters where functional recovery metrics determine authorization duration. DEA scheduling creates distribution friction that preserves margin structure through controlled-substance pharmacy networks.
- Antidepressants:SSRIs and SNRIs manage comorbid mood disturbance in memory disorder populations through modulation of hippocampal neurogenesis pathways.
- Anxiolytics:Benzodiazepine-sparing agents like buspirone target anxiety-driven cognitive interference with lower dependency liability.
Cognitive enhancers lead on scale; stimulants lead on momentum.
Indication:
Disease prevalence and diagnostic infrastructure determine addressable patient pools, with biomarker availability gating trial enrollment and commercial targeting.
- Alzheimer’s Disease:Amyloid-targeting antibodies and symptomatic therapies serve the largest absolute population with the most mature diagnostic ecosystem. The FDA's accelerated approval framework for lecanemab and donanemab has compressed development timelines while mandating costly confirmatory studies that reshape portfolio risk calculations for developers.
- Mild Cognitive Impairment:Prodromal intervention represents the strategic frontier where disease-modifying therapies seek to demonstrate functional preservation before irreversible neurodegeneration. Japan's METI incentives for dementia prevention create regulatory fast-tracks for agents showing cognitive stability in this preclinical window.
- Post-Traumatic Stress Disorder:Trauma-focused pharmacotherapy targets hippocampal volume loss and intrusive memory consolidation in veteran and first-responder populations.
- Traumatic Brain Injury:Neuroprotective and restorative agents address diffuse axonal injury patterns in sports medicine and occupational health settings.
Alzheimer's disease dominates current revenue; mild cognitive impairment shows steepest expansion trajectory.
End User:
Site-of-care economics and infusion infrastructure requirements fragment distribution strategy across institutional and ambulatory channels.
- Hospitals:Academic medical centers with dedicated memory disorder units capture complex cases requiring biomarker confirmation and biologic administration. These institutions consolidate prescriber authority among fellowship-trained behavioral neurologists and maintain cold-chain capabilities for antibody infusions that community settings cannot support.
- Outpatient Clinics:Cognitive assessment protocols and oral therapy management concentrate in neurology and geriatric psychiatry practices where Medicare reimbursement for cognitive testing drives specialist referrals.
- Home Care Settings:Caregiver-administered oral regimens and remote monitoring platforms extend therapeutic access for mobility-limited patients.
- Rehabilitation Centers:Post-acute facilities integrate pharmacological intervention with occupational therapy for TBI and stroke-related memory deficits.
Hospitals anchor premium biologic volume; outpatient clinics drive oral prescription scale.
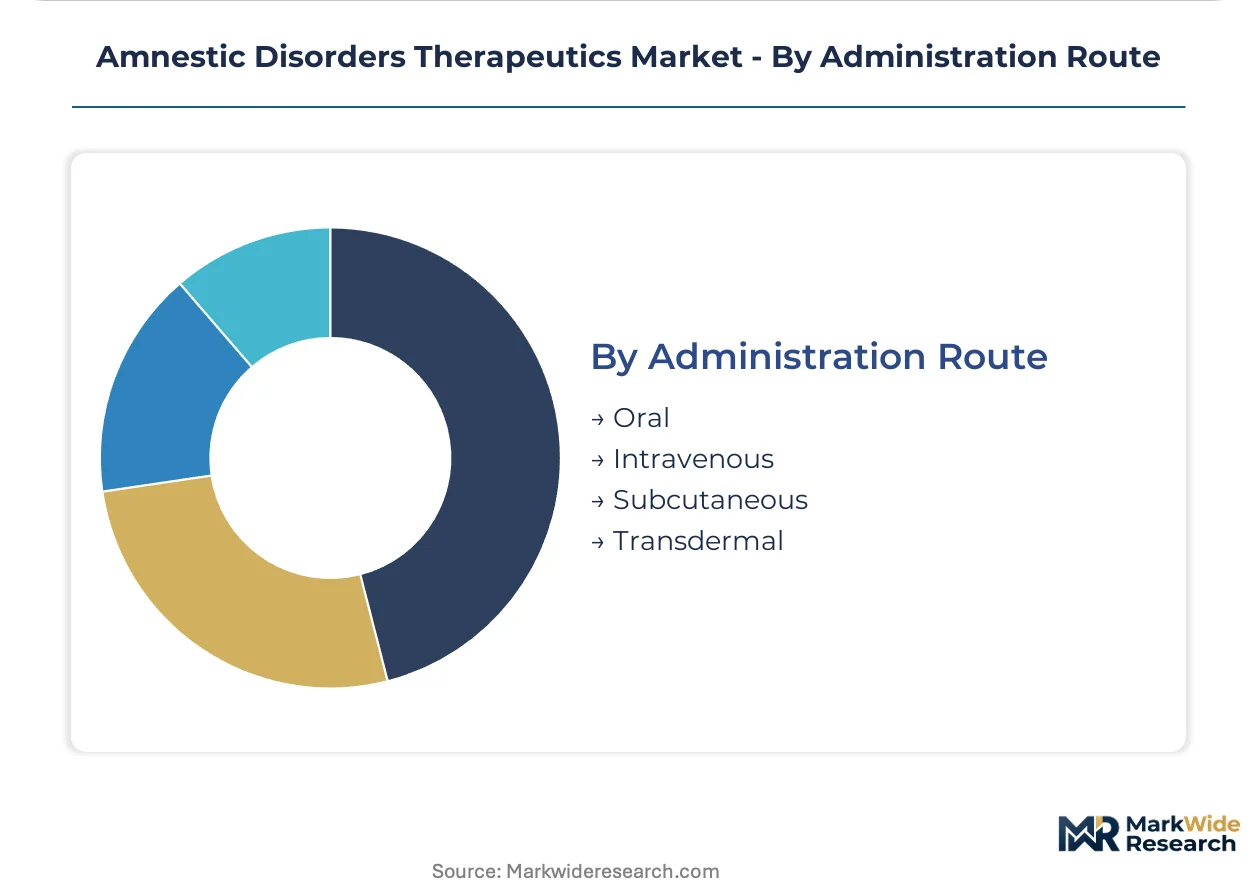
Administration Route:
Formulation technology and blood-brain barrier pharmacokinetics determine competitive moats and manufacturing investment requirements.
- Intravenous:Antibody infusions require hospital-based administration with amyloid PET confirmation and MRI monitoring for ARIA events. Eisai's lecanemab and Biogen's aducanumab establish the clinical and commercial template that subsequent entrants must match or exceed on efficacy or safety.
- Oral:Small-molecule tablets and capsules retain structural dominance in outpatient economics due to patient preference and pharmacy benefit design. Efflux transporter limitations constrain CNS exposure for many candidates, creating formulation challenges that specialists in medicinal chemistry must solve.
- Subcutaneous:Auto-injector platforms for biologics are emerging as a convenience alternative to infusion center dependency.
- Transdermal:Patch delivery systems bypass first-pass metabolism for agents with narrow therapeutic indices or gastrointestinal intolerance.
Oral administration sustains volume leadership; intravenous captures value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Behavioral neurologist training programs in the United States produce fewer than 150 new specialists annually, creating a talent bottleneck that concentrates prescribing authority in major metropolitan academic medical centers. This workforce scarcity shapes regional market development patterns.
United States
Medicare reimbursement policies for cognitive assessments drive specialist referrals to memory disorder clinics in Boston, Baltimore, and San Francisco. FDA's accelerated approval pathway for amyloid-clearing antibodies compresses development timelines while mandating costly confirmatory trials. Academic medical centers in these cities consolidate prescriber authority and maintain cold-chain capabilities for biologic infusions.
Germany
Hospital systems in Germany structure formularies around dual-endpoint demonstration requirements for Alzheimer's therapies. EMA's evolving stance on biomarker surrogacy creates friction with FDA harmonization efforts, demanding functional outcome data beyond cognitive scales. The Rhine-Ruhr metropolitan region anchors demand concentration for infusion-based biologics.
Japan
METI incentives for dementia care innovation create regulatory fast-tracks for therapies demonstrating functional preservation in mild cognitive impairment. Japan's aging demographics generate sustained demand for disease-modifying interventions. The Kanto region surrounding Tokyo hosts the highest density of memory disorder research protocols.
United Kingdom
NHS England's specialized commissioning frameworks gate access to high-cost biologic therapies for Alzheimer's disease. NICE technology appraisals apply stringent cost-effectiveness thresholds that reshape commercialization strategies. The Greater London area concentrates both diagnostic infrastructure and specialist neurology capacity.
Switzerland
Swissmedic maintains rigorous evidentiary standards for CNS therapeutics that parallel EMA requirements while permitting earlier patient access through temporary authorization schemes. The country's pharmaceutical research clusters in Basel and Zurich drive clinical trial enrollment for biomarker-stratified studies.
Amnestic Disorders Therapeutics Market Competitive Environment
The competitive structure tilts toward integrated neurology platforms with established infusion infrastructure and biomarker diagnostic capabilities. Large-cap pharmaceutical companies with legacy psychiatry portfolios compete against biotech specialists focused on amyloid-targeting mechanisms. Three archetypes dominate: diversified conglomerates extending CNS franchises, pure-play neurology biotechs, and Japanese pharmacos with Western partnership structures. Portfolio diversification into mild cognitive impairment adjacencies and strategic co-development partnerships constitute the primary competitive moves reshaping positioning.
Within the integrated pharmaceutical tier, Johnson & Johnson and Pfizer exemplify diversified conglomerates leveraging existing neurology infrastructure. Biogen and Eisai Co., Ltd. occupy positions as amyloid-targeting specialists with deep co-development experience. Eli Lilly and Company represents the emerging competitive force with its presence across both small-molecule and biologic modalities. These named entities anchor the competitive map without exhausting its full composition.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Sanofi |
| Biogen |
| AbbVie |
| Pfizer |
| Eisai Co., Ltd. |
| Bristol-Myers Squibb |
| Eli Lilly and Company |
| Novartis |
| Others |
Value Chain & Pricing Dynamics
Bifurcation between infusion-based biologics and oral small-molecules manifests in divergent pricing architectures and supply chain configurations across the amnestic disorders therapeutics landscape. Premium antibody infusions command value-based contracting through hospital outpatient departments with bundled imaging and monitoring services, while oral cognitive enhancers flow through consolidated specialty pharmacy networks with unbundled reimbursement structures.
Pricing Analysis
Bundled service packaging for amyloid-clearing antibodies contrasts sharply with unbundled transactional pricing for cholinesterase inhibitors and NMDA modulators. Three-tier pricing structure across premium biologics, standard oral therapies, and economy generics reflects FDA approval pathway differentiation and Medicare coverage tier placement. Cost compression in the oral standard tier intensifies because generic substitution pressures and formulary exclusion policies from national payers. Academic medical centers exhibit lowest price sensitivity due to bundled budget allocation for comprehensive memory disorder protocols, while Medicare Part D beneficiaries in community settings demonstrate highest sensitivity to out-of-pocket cost differentials.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive biologics create specialized cold-chain recovery networks distinct from forward distribution infrastructure. Active pharmaceutical ingredient manufacturing concentrates in the United States, Switzerland, and Japan for high-potency neurological compounds, while fill-finish operations draw from Ireland, Singapore, and Puerto Rico. Supply chain risk centers on single-source vulnerability for blood-brain barrier permeability enhancers and specialized infusion capacity at academic medical centers. Distribution runs through three national specialty pharmacy networks with proven cold-chain capabilities, consolidating prior authorization routing for Medicare Part D plans.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compounding accelerates value capture in this market as FDA's accelerated approval pathway for amyloid-clearing antibodies compresses development timelines while mandating costly confirmatory infrastructure that reshapes competitive economics.
For Market Incumbents: Lock in prescriber relationships through exclusive infusion center partnerships at academic medical centers with dedicated memory disorder units. Deepen backward integration into biomarker diagnostic platforms to control patient identification and trial enrollment pathways against emerging platform competitors. Expand fellowship training program sponsorships to address behavioral neurologist scarcity and secure future prescriber pipeline access.
For New Entrants and Emerging Players: Capture white-space opportunity in subcutaneous auto-injector platforms that bypass hospital-based infusion dependency and reduce ARIA monitoring burden. Target mild cognitive impairment indication segments where Japan's METI incentives create regulatory fast-tracks and functional preservation endpoints remain underdeveloped by established amyloid-focused competitors. Deploy digital biomarker companion tools to enable decentralized trial models and real-world evidence differentiation.
For Investors and Strategic Acquirers: Consolidation pressure builds where cold-chain logistics capabilities and biomarker diagnostic infrastructure fragment across subscale regional players. Long-term viability in this market rests on integrated neurology platforms with established infusion infrastructure and payer contracting leverage. Acquisition target archetypes include pure-play biomarker diagnostic firms and specialty pharmacy networks with proven Medicare Part D prior authorization capabilities. Monitor CMS national coverage determinations for PET amyloid imaging as the critical inflection signal for patient access expansion or restriction.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Diagnostic Platform Acquisition | Controls patient identification funnel and accelerates trial enrollment for amyloid-targeting programs. |
| Infusion Center Network Expansion | Captures hospital-based biologic administration volume and builds prescriber loyalty through service bundling. |
| Subcutaneous Formulation Development | Reduces hospital dependency and ARIA monitoring costs while expanding addressable prescriber base. |
| Digital Biomarker Partnership | Enables decentralized trial models and real-world evidence generation for regulatory differentiation. |
| Fellowship Training Program Sponsorship | Addresses behavioral neurologist scarcity and secures future prescriber relationships in concentrated metropolitan clusters. |
Study Parameters
Coverage spans the United States, Germany, Japan, the United Kingdom, and Switzerland, with primary inputs from each market's regulatory and reimbursement environment. The analysis combines structured interviews with drug development executives, regulatory affairs leads, formulary directors at national payers, and hospital procurement managers with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare coverage databases. Bottom-up prescription volume modeling and top-down therapeutic category spend estimates were triangulated to establish market sizing and growth projections.
Granularity-level modeling disaggregated revenue and volume across administration route, indication severity, and care setting dimensions throughout the forecast period. CAGRs were derived from segment-level growth trajectory analysis incorporating biomarker adoption curves, reimbursement policy evolution, and prescriber workforce expansion constraints. Industry-specific forecast inputs included Medicare Part D formulary placement timelines, FDA confirmatory trial completion schedules, and behavioral neurologist fellowship graduation rates.
Regulatory pathway reversals, biomarker surrogacy standard changes, and prescriber workforce attrition are the dominant revision risks that could materially alter trajectory assumptions. Forecasts reflect analytical judgments documented in the underlying segmentation and stakeholder interview records. Practitioners should monitor FDA confirmatory trial readouts, CMS national coverage determination updates, and EMA biomarker guidance evolution for early signals of forecast revision necessity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Sweden Neurology Devices Market
Neurology
Spasticity Treatment Market
Neurology
Japan Neurology Devices Market
Neurology
Pediatric Neurology Device Market
Neurology
Neurological Biomarkers Market
Neurology
Germany Neurology Devices Market
Neurology
CNS Therapeutics Market
Neurology
Mild Traumatic Brain Injury Treatment Market
Neurology
Global Vertigo Treatment Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
UAE Neurology Devices Market
Neurology
Peripheral Neuritis Treatment Market
Neurology
Neuro Critical Care Market
Neurology
Transverse Myelitis Treatment Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Interventional Neurology Market